
 High-Performance Electric Sports Cars Market | 2026-2036
High-Performance Electric Sports Cars Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Electric Sports Cars Market Insights
Premium electric sports car engineering is decoupling from mass-market EV commodity economics around battery thermal management and carbon-fiber chassis construction. Porsche sustains R&D intensity across 800-volt architectures and track-grade cooling systems. Rimac Automobili specializes in hypercar powertrain supply to third-party OEMs. Tesla leverages its in-house cell production and over-the-air performance calibration to occupy a distinct tier between traditional automakers and boutique builders.
High-performance electric sports cars are battery-electric vehicles engineered for sustained high-speed operation, typically delivering continuous output above 500 kW through multi-motor layouts with liquid-cooled battery packs operating at 800 volts or higher. Their primary purpose is to combine zero-emission compliance with lap-time performance previously achievable only by internal-combustion supercars. Coupe and roadster body styles dominate current revenue pools, while solid-state battery technology represents the fastest-advancing segment for next-generation thermal stability and energy density. Ultra-performance tiers command disproportionate margin concentration despite lower unit volumes.
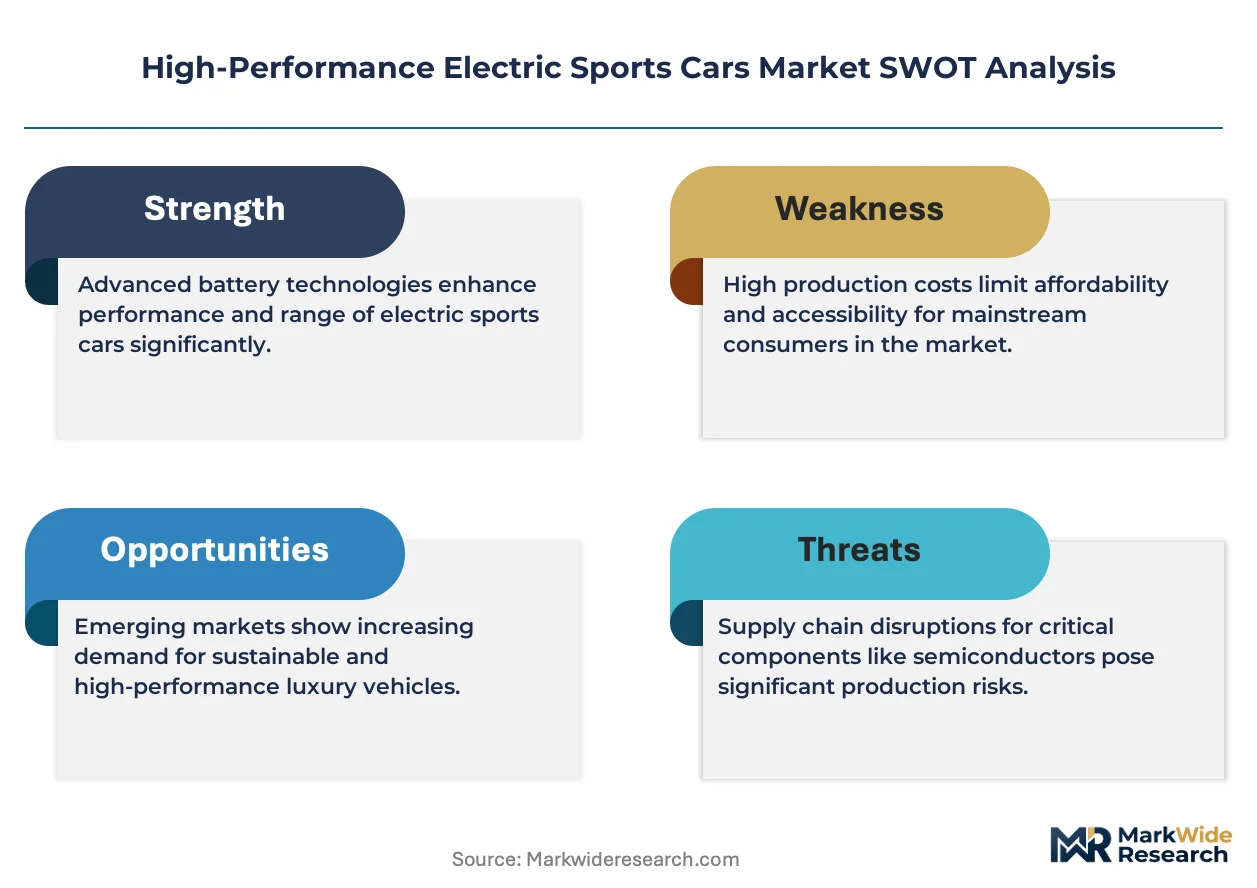
EPA, NHTSA, and EU fleet emissions frameworks are tightening CO2 thresholds and mandating phase-out timelines for internal-combustion powertrains, directly reshaping product development budgets and platform decisions. China's MIIT dual carbon goals and NEV credit system create parallel compliance pressure that funnels engineering resources toward electric architectures. Stakeholders must weigh battery chemistry roadmaps against regulatory cliff edges that will render ICE-derived sports car platforms commercially unviable before their typical seven-year model cycles conclude.
Market Dynamics
800-volt battery architectures are compressing thermal management development cycles and forcing legacy chassis engineering teams to abandon ICE-derived platform strategies mid-cycle. This voltage threshold represents the pivot point where sustained track performance becomes technically viable for electric powertrains.
Growth Catalysts
- EU fleet emissions standards:Binding CO2 thresholds under the EU Green Deal are eliminating ICE platform economics before typical seven-year model cycles conclude, redirecting R&D budgets toward zero-emission architectures.
- Solid-state battery chemistry:Improved thermal stability and energy density from sulfide and oxide electrolyte formulations are extending sustained high-speed operation windows without thermal derating.
- Collector demand concentration:Luxury vehicle collectors in Germany, California, and China are pre-ordering limited-production electric hypercars, creating order backlogs that validate premium pricing tiers.
Market Restraints
- Lithium supply concentration:Battery-grade lithium hydroxide processing concentrates in Chile, Argentina, and Australia, exposing cell manufacturers to geopolitical disruption and price volatility in cathode material supply.
- Carbon-fiber chassis cost structure:Autoclave-cured composite monocoques require 10-14 day production cycles and specialized tooling that cannot amortize across mass-market volumes.
- EPA certification friction:Tailpipe regulations create parallel compliance burdens for manufacturers maintaining residual ICE sports car lines while developing electric successors.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting powertrain suppliers to establish localized battery pack assembly for Asian market variants.
- Track-day subscription services:Circuit operators in Germany and Japan are bundling vehicle access with charging infrastructure, creating new ownership-lite revenue streams beyond traditional retail.
- Over-the-air performance calibration:Firmware-delivered powertrain updates enable post-purchase torque and thermal limit adjustments, converting one-time sales into recurring service relationships.
Industry Challenges
- High-voltage systems engineering talent:Scarce expertise in 800-volt inverter design and dielectric isolation is constraining development team scaling across multiple simultaneous vehicle programs.
- Homologation timeline compression:UN ECE R100 battery safety certification and NHTSA crash testing protocols require 18-24 month lead times that misalign with compressed product reveal schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Electric Sports Cars Market |
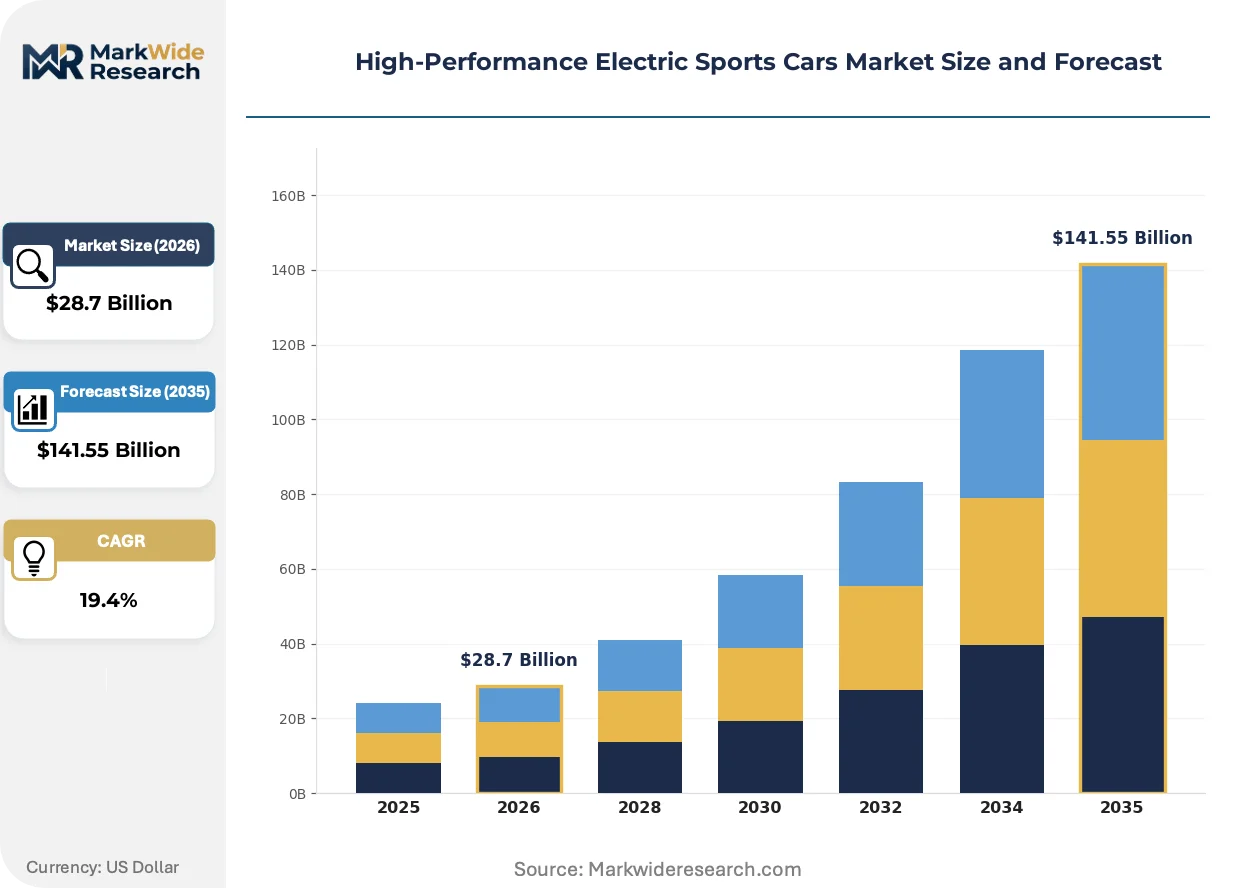
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $141.55 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coupe, Roadster, Hatchback, Convertible, Targa Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lithium-Polymer, Sodium-Ion Performance Tier: Entry-Level, Mid-Range, High-End, Ultra-Performance Customer Type: Luxury Collectors, Motorsport Enthusiasts, Eco-Conscious Buyers, Technology Early Adopters |
| Companies Covered | Tesla, Porsche, Audi, Rimac Automobili, Lotus Cars, Ferrari, BMW, Lucid Motors, Mercedes-Benz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Electric Sports Cars Market Trends and Innovations
Powertrain thermal management and chassis construction methods are diverging sharply from mass-market EV commodity economics, creating distinct engineering hierarchies that reward specialized competence over scale.
Silicon-carbide power semiconductors are consolidating inverter efficiency gains across 800-volt architectures. Boutique manufacturers and third-party hypercar builders are adopting these devices faster than legacy automakers, compressing the performance gap between established marques and emerging entrants. This semiconductor transition is consolidating supplier relationships around a handful of wafer fabricators capable of automotive-grade defect densities.
REACH chemical restrictions and EU battery passport mandates are reshaping material sourcing disclosure requirements. Cell manufacturers must now document cobalt provenance and carbon intensity across the full supply chain, raising compliance costs for smaller producers. European-registered vehicles face the most stringent traceability thresholds, pushing assembly localization decisions toward EU member states with established recycling infrastructure.
Collector purchasing patterns are rotating toward direct manufacturer relationships and away from traditional dealership networks. Buyers in Germany and China increasingly reserve vehicles through digital configurators with non-refundable deposits, bypassing established retail channels. This disintermediation is most visible in limited-production hypercar segments where allocation scarcity supports premium pricing without intermediary markups.
High-Performance Electric Sports Cars Market Segmentation
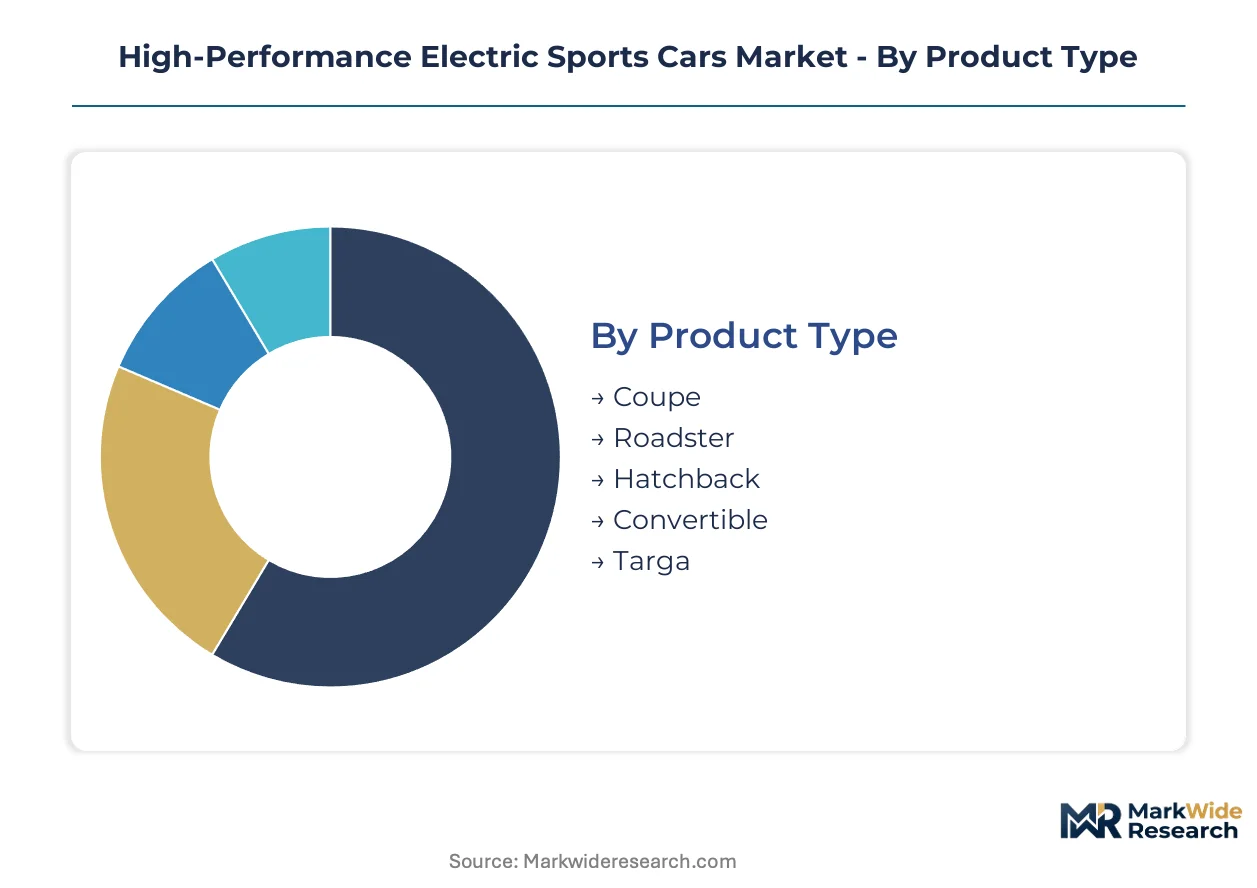
Segmentation in high-performance electric sports cars reveals how engineering specifications, purchasing psychology, and battery chemistry roadmaps partition addressable demand. Manufacturers configure platform architectures and thermal management systems differently across these axes, with direct implications for margin structure and production tooling amortization.
Product Type:
Body style selection determines chassis rigidity requirements, aerodynamic packaging constraints, and roof mechanism mass penalties that cascade into battery placement decisions.
- Coupe:Fixed-roof architectures deliver the highest torsional stiffness-to-weight ratios, enabling the lowest center of gravity for battery pack placement. German collectors and California track-day operators concentrate orders here, drawn by structural efficiency that sustains repeated high-g cornering without flex-induced handling degradation.
- Roadster:Two-seat open-cockpit configurations sacrifice some rigidity for emotional engagement and reduced mass, requiring reinforced sills and floor pans to compensate. Demand clusters among Japanese collectors and coastal Chinese buyers seeking weekend-oriented vehicles with direct wind exposure and unfiltered motor acoustics.
- Hatchback:Rear cargo accessibility and expanded interior volume appeal to buyers bridging daily utility with performance credentials.
- Convertible:Folding soft-top mechanisms add complexity and mass, limiting sustained track capability but expanding fair-weather usability.
- Targa:Removable roof panels split the difference between coupe rigidity and open-air experience, attracting buyers prioritizing structural compromise over full convertible convenience.
Coupe leads on scale; Roadster leads on momentum.
Battery Technology:
Cell chemistry selection governs thermal runaway thresholds, fast-charge acceptance rates, and energy density ceilings that define sustained power output capabilities.
- Lithium-Ion:NMC and NCA cathode formulations dominate current production with established supply chains and 800-volt compatibility. Cell manufacturers in South Korea and China supply the majority of packs, though energy density plateaus near 300 Wh/kg constrain next-generation performance targets without chemistry shifts.
- Solid-State:Sulfide and oxide electrolyte architectures promise 400+ Wh/kg density with inherent thermal stability that eliminates liquid cooling complexity. Japanese and European OEMs concentrate development partnerships here, targeting the steepest expansion trajectory as manufacturing scalability improves.
- Nickel-Metal Hydride:Mature chemistry with limited energy density but proven cycle life, now relegated to hybrid auxiliary applications.
- Lithium-Polymer:Pouch cell formats enable packaging flexibility for low-volume hypercar builders with irregular chassis cavities.
- Sodium-Ion:Emerging chemistry using abundant raw materials, currently limited by lower energy density but attracting interest for cost-sensitive performance variants.
Lithium-Ion commands installed base; Solid-State captures R&D allocation intensity.
Performance Tier:
Power output bands segment engineering investment, materials specification, and pricing architecture with minimal overlap in component sourcing.
- Entry-Level:Single or dual-motor layouts delivering 300-400 kW through shared platforms with mass-market EV siblings, prioritizing accessibility over track durability.
- Mid-Range:Tri-motor configurations with dedicated track modes and upgraded brake systems, representing the volume concentration for established sports car marques transitioning ICE lineages.
- High-End:Quad-motor architectures with carbon-ceramic brakes, active aerodynamics, and bespoke chassis construction. Ultra-Performance
- Ultra-Performance:Limited-production vehicles exceeding 1,000 kW with full carbon-fiber monocoques, active suspension, and sub-2.0-second acceleration capability. Order backlogs in Germany and China validate pricing multiples above mass-market EVs, with allocation scarcity converting engineering investment into brand elevation for parent companies.
Mid-Range generates volume throughput; Ultra-Performance defines margin extraction.
Customer Type:
Purchasing motivation determines sensitivity to specification trade-offs, channel preferences, and post-sale engagement models.
- Luxury Collectors:Portfolio diversification seekers acquiring limited-production vehicles as store-of-value assets, prioritizing provenance documentation and factory delivery experiences over immediate drivability.
- Motorsport Enthusiasts:Track-day practitioners demanding sustained lap-time consistency, telemetry integration, and over-the-air calibration updates that preserve residual performance value.
- Eco-Conscious Buyers:Zero-emission compliance motivation intersecting with performance expectations, concentrated in jurisdictions with ICE restrictions.
- Technology Early Adopters:Firmware-feature prioritization and semiconductor specification sensitivity, often accepting first-generation reliability risk for access to bleeding-edge powertrain architectures.
Luxury Collectors anchor pricing power; Technology Early Adopters accelerate feature validation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools for 800-volt powertrain development concentrate in Germany, California, and Japan, anchoring the geographic distribution of high-performance electric sports car R&D investment and collector demand.
Germany
Collector demand for limited-production electric hypercars concentrates in Munich and Stuttgart, with order backlogs validating premium pricing tiers. EU fleet emissions standards under the Green Deal eliminate ICE platform economics before seven-year model cycles conclude. The Stuttgart engineering cluster sustains development of track-grade cooling systems and carbon-fiber chassis construction.
United States
California track-day operators and technology early adopters drive pre-order activity for over-the-air performance calibration capabilities. EPA tailpipe regulations create parallel compliance burdens for manufacturers maintaining residual ICE sports car lines. The Silicon Valley-to-Los Angeles corridor anchors in-house cell production and firmware-delivered powertrain updates.
China
Luxury vehicle collectors in coastal cities pre-order limited-production vehicles through digital configurators with non-refundable deposits. MIIT dual carbon goals and the NEV credit system funnel engineering resources toward electric architectures. The Yangtze River Delta battery manufacturing cluster supplies cell chemistry for Asian market variants.
Japan
Motorsport enthusiasts in the Kanto region demand sustained lap-time consistency and telemetry integration for circuit use. METI industrial policy supports solid-state battery chemistry development partnerships targeting 400+ Wh/kg density. The Nagoya automotive supplier network specializes in silicon-carbide power semiconductor fabrication.
United Kingdom
Boutique hypercar builders around Silverstone leverage composite monocoque expertise from motorsport engineering services. REACH chemical restrictions and EU battery passport mandates reshape material sourcing disclosure requirements for European-registered vehicles. The Midlands manufacturing corridor hosts specialized tooling for autoclave-cured carbon-fiber production cycles.
High-Performance Electric Sports Cars Market Competitive Landscape
Top-tier vendors anchor ultra-performance and mid-range tiers, while emerging specialists occupy technology validation niches. The market structure reflects concentrated competence in 800-volt architectures and thermal management rather than scale economies. Three strategic archetypes dominate: legacy sports car marques transitioning ICE lineages, electric-native powertrain specialists, and technology-integrated volume challengers. Competitive moves center on strategic partnerships for battery chemistry access and geographic expansion into collector-dense Asian markets.
Within the legacy marque tier, Porsche and Ferrari represent established engineering hierarchies that reward specialized chassis competence over production volume. Rimac Automobili occupies a distinct position as a powertrain supplier to third-party OEMs, exemplifying the specialist archetype that consolidates inverter efficiency gains faster than integrated manufacturers. Tesla anchors the technology-integrated challenger segment, leveraging in-house cell production to bridge traditional automakers and boutique builders.
| Leading Market Players |
|---|
| Tesla |
| Porsche |
| Audi |
| Rimac Automobili |
| Lotus Cars |
| Ferrari |
| BMW |
| Lucid Motors |
| Mercedes-Benz |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of 800-volt battery packs and carbon-fiber monocoques anchors both supply security and pricing power for ultra-performance tier manufacturers. This backward integration insulates order backlogs from lithium hydroxide volatility and autoclave capacity constraints while supporting premium pricing multiples validated by collector demand in Germany and China.
Pricing Analysis
Vehicle-hardware and over-the-air calibration services increasingly unbundle, with firmware-delivered powertrain updates converting one-time sales into recurring revenue streams. Three-tier pricing structure across ultra-performance, high-end, and mid-range levels separates allocation-scarce limited production from volume-tier derivatives. Pricing pressure stems from carbon-fiber chassis cost structures that resist scale economies, compressing margins for mid-range tiers. Technology early adopters exhibit lowest price sensitivity, while eco-conscious buyers bridging from mass-market EVs drive standard-tier negotiation intensity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand for 800-volt architectures, while boutique hypercar builders source through specialized powertrain integrators. Battery-grade lithium hydroxide processing concentrates in Chile, Argentina, and Australia. Cell manufacturing draws from South Korean and Chinese cathode suppliers, with silicon-carbide wafers feeding from Japanese and German semiconductor fabricators. Single-source vulnerability around sulfide electrolyte solid-state chemistry partnerships creates concentration risk as manufacturing scalability improves. Distribution runs through regional assembly nodes in Germany, California, and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in high-performance electric sports cars rests on solid-state battery cost-down curves and ultra-performance tier demand concentration. Solid-state chemistry maturation and collector pre-order backlogs support premium pricing architecture.
For Market Incumbents: Deepen captive control over 800-volt inverter design talent pools to offset scarce high-voltage systems engineering expertise constraining program scaling. Secure multi-year offtake agreements with Chilean and Australian lithium processors before cathode material competition intensifies. Accelerate EU battery passport compliance documentation to preempt REACH disclosure cost escalation for European-registered vehicle lines.
For New Entrants and Emerging Players: Capture white-space in track-day subscription service bundling across German and Japanese circuit operators, where ownership-lite revenue models remain underdeveloped. Target India PLI scheme incentives for localized battery pack assembly serving Asian market variants. Enter through powertrain supply partnerships rather than full vehicle manufacturing, mirroring Rimac Automobili's specialist archetype.
For Investors and Strategic Acquirers: Roll-up economics work for silicon-carbide power semiconductor fabricators because automotive-grade defect density requirements consolidate supplier relationships around limited wafer production capacity. Platform specialization in 800-volt thermal management and dielectric isolation offers 5-10 year viability windows as legacy automakers abandon ICE-derived chassis strategies. Watch solid-state battery manufacturing yield rates as the inflection signal for chemistry transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake secures cell chemistry access against lithium hydroxide volatility. |
| Software-Defined Vehicle Investment | Over-the-air calibration capabilities convert one-time sales into recurring service relationships. |
| Geographic Manufacturing Footprint | EU assembly localization satisfies battery passport mandates and REACH traceability thresholds. |
| Charging Infrastructure Partnership | Track-day operator bundling creates ownership-lite revenue streams beyond traditional retail channels. |
| Platform Standardization | 800-volt architecture sharing across vehicle programs amortizes thermal management R&D investment. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down battery cell supply tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, track-day circuit operators, and luxury vehicle collectors combined with secondary validation from vehicle registration databases, IHS Markit production data, SEC automotive segment filings, and EU CO2 fleet compliance reports. Triangulation across these sources reconciles order backlog disclosures with cathode material demand projections.
Historical trendline analysis of battery energy density improvement curves and collector purchasing pattern shifts informed projection framework construction. Segmentation dimensions modeled include body style architecture, battery chemistry roadmap, performance tier power output, and customer purchasing motivation across the analysis window. CAGRs derived from segment-level volume assumptions weighted by regional regulatory phase-out timelines and pre-order deposit trends. Solid-state manufacturing yield assumptions and lithium supply expansion schedules served as key forecast inputs.
Regulatory acceleration of ICE phase-out timelines, solid-state chemistry manufacturing scalability delays, and lithium supply geopolitical disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding battery passport implementation timing and collector demand concentration stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
Saudi Arabia Electric Vehicle Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Bus Pantograph Charger Market