
 Electric Vehicle Panoramic Sunroof Market | 2026-2036
Electric Vehicle Panoramic Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Panoramic Sunroof Market Insights
Ultra-clear low-iron glass specifications are redrawing supplier hierarchies in the EV panoramic sunroof space. Webasto SE leverages its integrated mechatronics platform to sustain dominance in sliding roof architectures across European OEM programs. Magna International anchors North American supply through captive glass processing and bonded assembly lines. Aisin Seiki competes on thermal management integration, embedding PTC heating elements directly into glass laminates for cold-climate efficiency.
An electric vehicle panoramic sunroof is a large-format transparent or translucent roof panel, typically spanning 0.8 to 1.4 square meters, constructed from laminated tempered glass with interlayer films for acoustic damping and solar attenuation, designed to maximize cabin daylighting while maintaining structural integrity during rollover events. Fixed panoramic configurations occupy the largest share of current OEM fitment due to lower complexity and sealing reliability, though sliding variants command margin premiums where rail mechanism durability meets acoustic targets. Material segmentation shows glass sustaining its position against polycarbonate alternatives as OEMs prioritize scratch resistance and optical clarity for autonomous sensor integration. Feature differentiation increasingly centers on solar control coatings, with electrochromic and thermochromic layers enabling dynamic tint adjustment without mechanical shades.
FDA oversight of automotive glazing materials remains limited, but NHTSA FMVSS 216 roof crush resistance and ECE R43 safety glazing standards directly shape laminate thickness and curvature constraints for panoramic designs entering US and European markets. China's GB standards for motor vehicle safety, administered by SAMR, mandate specific fragmentation patterns and penetration resistance for glass roof assemblies on NEV platforms. Stakeholders must monitor how evolving autonomous vehicle sensor packaging requirements interact with roof aperture geometry, as LiDAR and camera housing integration threatens to fragment the continuous glass surface that defines panoramic value propositions.
Market Dynamics
Ultra-clear low-iron glass specifications are redrawing supplier hierarchies as OEMs prioritize optical clarity for autonomous sensor integration through roof apertures. The shift from mechanical shade systems to electrochromic coatings is compressing value chain margins while demanding new thermal management competencies from tier suppliers.
Growth Catalysts
- China's NEV Mandates:SAMR-administered GB standards for motor vehicle safety accelerate laminated glass adoption on electric platforms, with Yangtze River Delta OEMs sourcing integrated roof assemblies at scale.
- Sliding Rail Mechanisms:Premium EV buyers in cold-climate markets demand PTC-embedded glass laminates for defrost performance, expanding addressable volume beyond fixed-pane configurations.
- Autonomous Sensor Packaging:LiDAR and camera housing integration through roof structures creates specification pull for continuous glass surfaces with embedded antenna pathways.
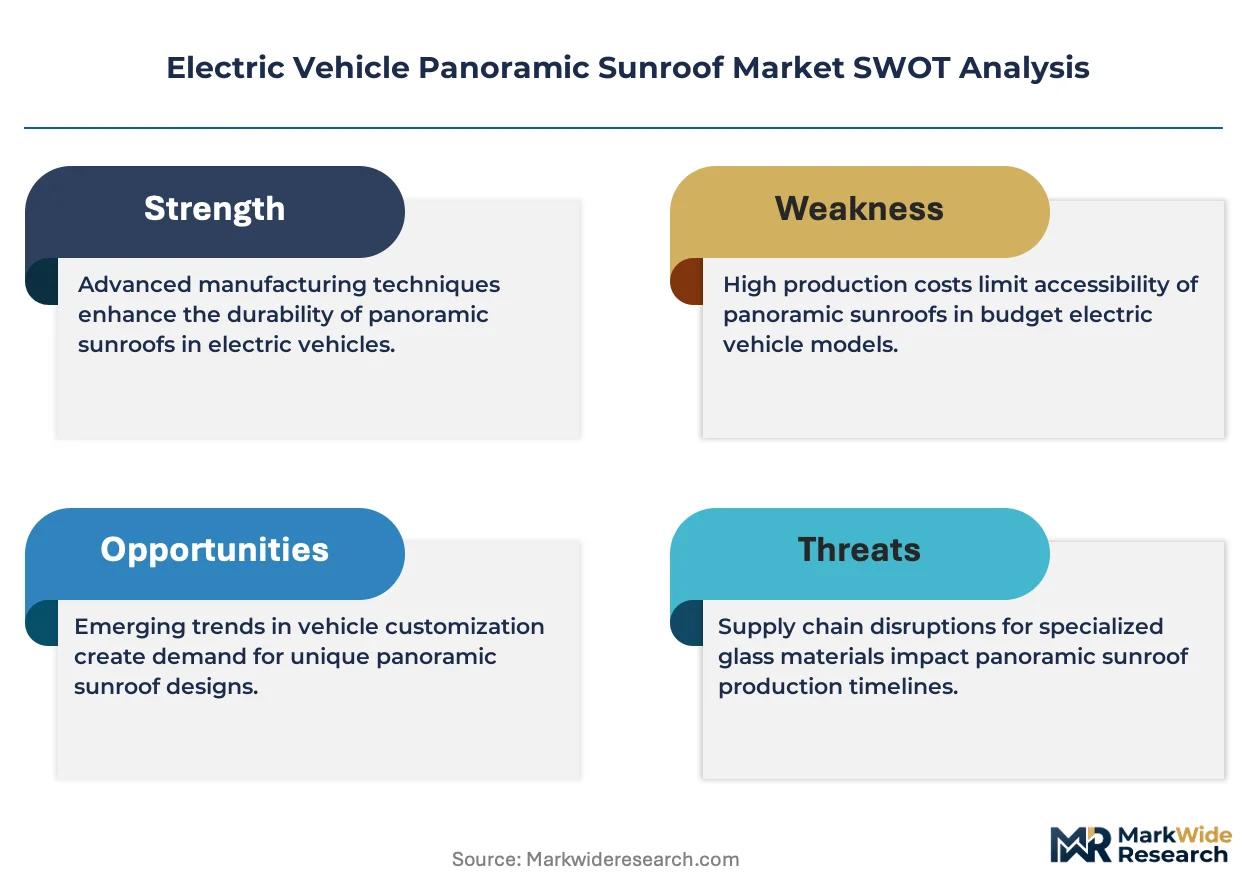
Market Restraints
- Low-Iron Silica Supply:Ultra-clear glass manufacturing depends on high-purity sand deposits concentrated in limited geographies, exposing OEM programs to input cost volatility.
- ECE R43 Compliance Friction:European safety glazing standards impose curvature and thickness constraints that fragment continuous pane designs, raising tooling amortization burdens.
- Polycarbonate Substitution:Scratch-resistant coated PC alternatives threaten glass dominance in price-sensitive EV segments where optical clarity requirements remain relaxed.
Strategic Opportunities
- Thermochromic Convergence:Integration of dynamic tint layers with photovoltaic films creates energy-generating roof systems for extended-range EV platforms.
- India's PLI Scheme:Component-level incentives for advanced automotive glazing attract glass processors to establish captive laminating capacity near Chennai and Pune assembly clusters.
- Direct OEM Procurement:Bypassing traditional tier-one roof system integrators through bonded assembly line investments lets manufacturers capture margin from glass processing steps.
Industry Challenges
- Optical Coating Talent Scarcity:Sputtering and chemical vapor deposition expertise for electrochromic layers concentrates among display industry veterans, forcing automotive suppliers into cross-sector recruitment.
- FMVSS 216 Certification Timelines:NHTSA roof crush resistance testing for panoramic designs extends validation cycles, compressing launch windows for model-year updates.
- Multi-Material Bonding Complexity:Sealing rail mechanisms to glass while maintaining acoustic targets demands precision automation that strains capital deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Panoramic Sunroof Market |
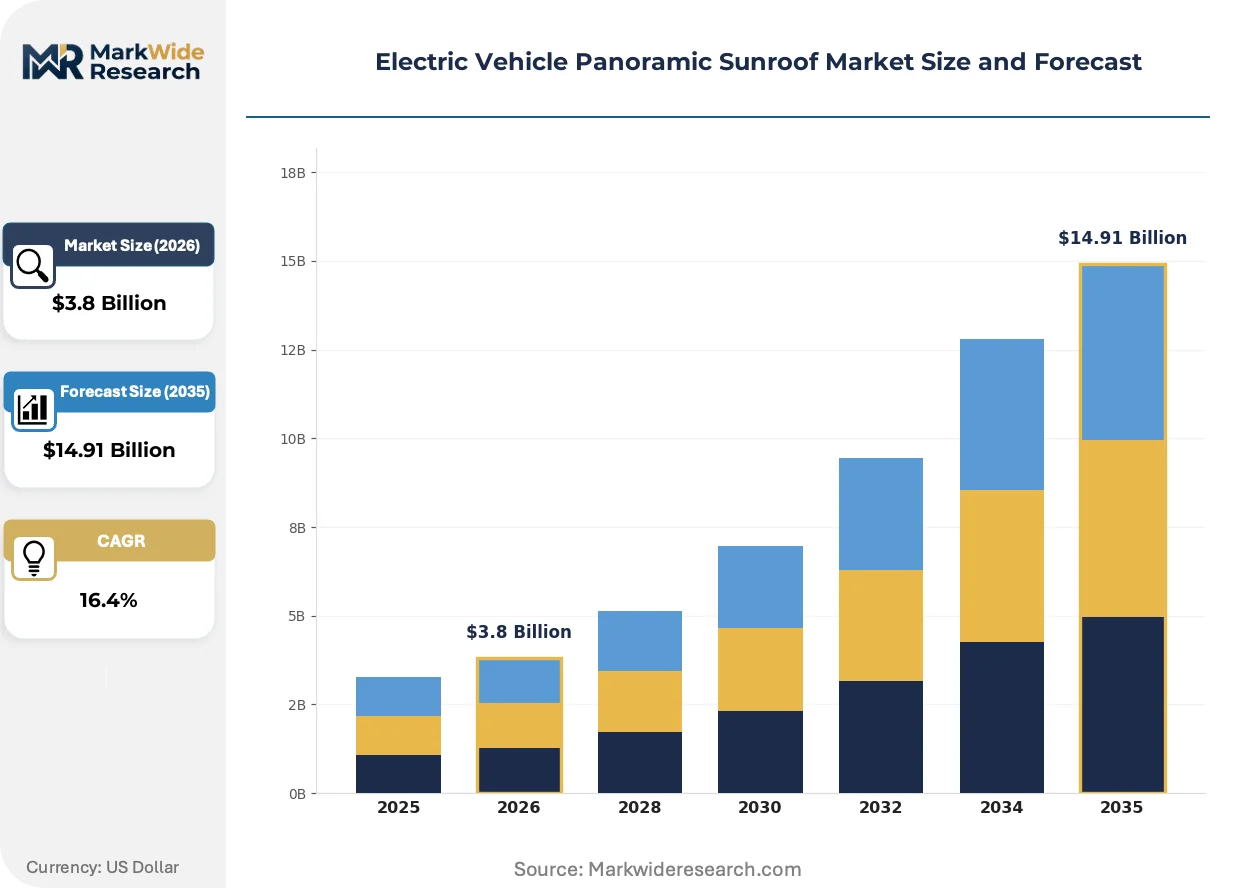
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Panoramic Sunroof, Sliding Panoramic Sunroof, Tinted Panoramic Sunroof, Retractable Panoramic Sunroof End User: OEMs, Aftermarket Providers, Service Centers, Fleet Operators Material: Glass, Polycarbonate, Acrylic, Composite Feature: UV Protection, Solar Control, Noise Reduction, Ventilation |
| Companies Covered | Aisin Seiki, CIE Automotive, Webasto SE, BOS GmbH & Co. KG, Magna International, Inalfa Roof Systems, Yachiyo Industry, AGC Automotive Europe, Inteva Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Panoramic Sunroof Market Trends and Innovations
Electrochromic layer deposition is compressing mechanical component counts while thermal management integration redefines supplier capability requirements. Three active developments are restructuring competitive positioning in EV roof system supply.
Photovoltaic-embedded glass laminates are miniaturizing cell interconnect architectures to maintain transparency ratios above 70%. Tier suppliers in Germany and Japan are piloting these systems for OEMs targeting solar-assisted cabin preconditioning. The technology is miniaturizing busbar footprints and enabling power generation without the visual interruption that plagued earlier transparent PV attempts.
REACH restrictions on heavy metals in automotive glazing are accelerating migration to tungsten-oxide-free electrochromic chemistries. Manufacturers serving European OEM programs must reformulate interlayer stacks to maintain switching speeds below 180 seconds. Premium EV platforms with continuous roof spans face the steepest reformulation costs, pushing some suppliers toward thermochromic alternatives that bypass electrical switching entirely.
Fleet procurement departments are consolidating roof system awards across multiple EV nameplates to extract volume leverage from glass processors. This behavior concentrates specification power with three to four platform architects per OEM group, marginalizing niche suppliers lacking bonded assembly capabilities. The shift is most visible in China's NEV sector, where BYD and NIO have reduced qualified supplier pools by half since 2022 through module commonality mandates.
Electric Vehicle Panoramic Sunroof Market Segmentation
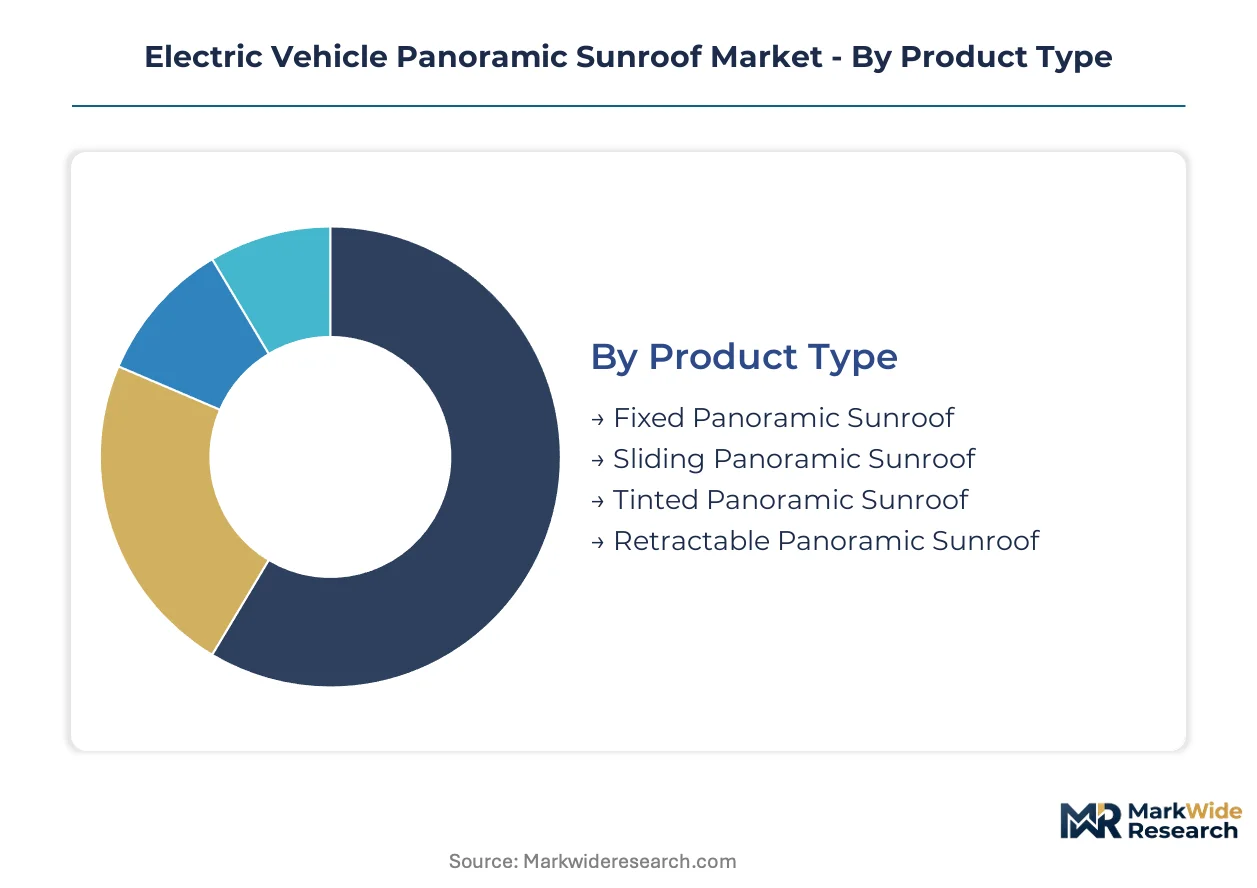
Segmentation in the EV panoramic sunroof market reveals how specification requirements fragment across thermal performance tiers, material science trade-offs, and autonomous sensor integration demands. Each dimension carries distinct margin structures and supplier capability thresholds that reshape procurement patterns.
Product Type:
Fixed configurations dominate domestic supply chains serving volume OEM programs, while sliding variants concentrate in export-led premium segments demanding cold-climate thermal management.
- Fixed Panoramic Sunroof:Single-pane laminated glass construction eliminates rail mechanism complexity and sealing failure modes. Demand concentrates in China's Yangtze River Delta cluster, where BYD and NIO source integrated assemblies for mass-market NEV platforms under SAMR-administered GB standards.
- Sliding Panoramic Sunroof:Multi-rail mechatronic systems integrate PTC heating elements directly into glass laminates for defrost performance. European OEM programs in Germany and Sweden drive specification pull, with Webasto SE anchoring supply through bonded assembly lines.
- Tinted Panoramic Sunroof:Factory-applied solar attenuation layers reduce cabin thermal load without electrochromic switching infrastructure.
- Retractable Panoramic Sunroof:Fabric or rigid panel stowage mechanisms maximize open-air aperture but impose structural reinforcement penalties.
Fixed panoramic sunroof holds the largest share; momentum sits with sliding panoramic sunroof as premium EV buyers demand active ventilation control.
End User:
Procurement concentration varies sharply: OEM direct awards favor bonded assembly capabilities, while aftermarket channels reward inventory flexibility over technical integration depth.
- OEMs:Platform architects consolidate roof system awards across multiple nameplates to extract volume leverage from glass processors. Tier-one integrators like Magna International and Aisin Seiki compete on thermal management integration and autonomous sensor packaging compatibility.
- Aftermarket Providers:Retrofit installations demand universal fitment kits with adaptable sealing profiles. Demand clusters in Germany and Japan, where aging EV fleets create replacement glass demand outside warranty periods.
- Service Centers:Warranty repairs and collision replacement drive spot procurement of laminated assemblies matched to specific model-year curvature specifications.
- Fleet Operators:Commercial EV procurement departments prioritize total cost of ownership, favoring fixed-pane configurations with minimal moving-part maintenance exposure.
OEMs command the dominant procurement volume; aftermarket providers are gaining share fastest as first-generation EV glass roofs exit warranty coverage.
Material:
Cost tier stratification separates optical-grade glass from polymer alternatives, with polycarbonate threatening substitution in price-sensitive segments where scratch resistance requirements remain relaxed.
- Glass:Laminated tempered construction with acoustic interlayer films sustains dominance despite weight penalties. Ultra-clear low-iron specifications from high-purity silica deposits in limited geographies expose OEM programs to input cost volatility.
- Polycarbonate:Scratch-resistant coated alternatives reduce mass and enable complex curvature without thermal forming constraints. Threatens glass dominance in entry-level EV segments where LiDAR transparency requirements are absent.
- Acrylic:Lower cost and lighter weight than polycarbonate but inferior impact resistance and UV stability limit automotive adoption.
- Composite:Hybrid glass-polymer laminates attempt to balance optical clarity with mass reduction, currently confined to concept vehicles and low-volume specialty builds.
Glass maintains the installed base leadership; polycarbonate shows the steepest expansion trajectory as coating technologies mature.
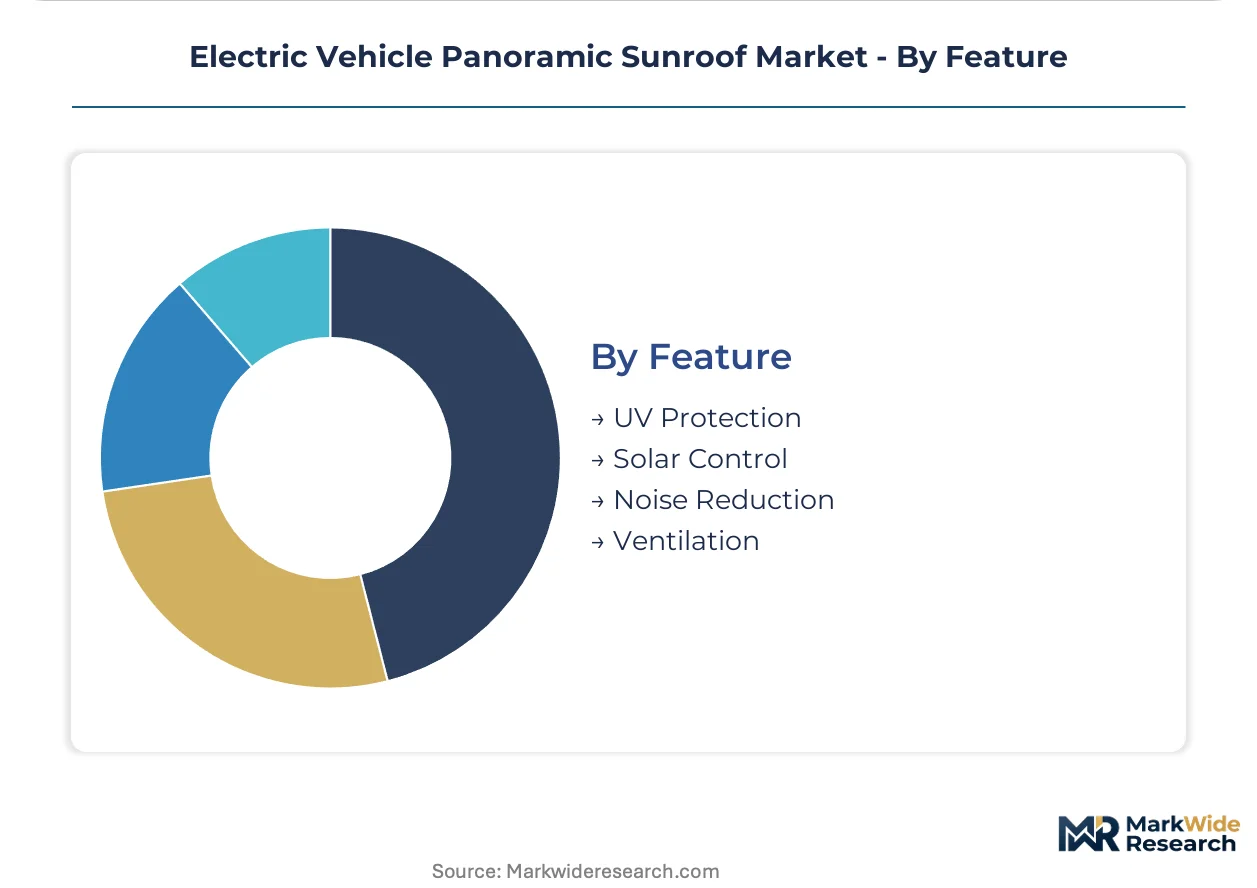
Feature:
Application-specific thermal and acoustic targets drive feature bundling, with solar control coatings commanding premium positioning over passive UV filtration.
- UV Protection:Standard interlayer formulations block ultraviolet transmission without dynamic tint adjustment. Baseline specification across all price tiers.
- Solar Control:Electrochromic and thermochromic layers enable dynamic tint adjustment, eliminating mechanical shade systems. REACH restrictions on heavy metals in European markets accelerate migration to tungsten-oxide-free chemistries with switching speeds below 180 seconds.
- Noise Reduction:Acoustic interlayer films dampen wind and road noise penetration through large-format roof apertures. Critical for premium EV platforms targeting luxury segment NVH benchmarks.
- Ventilation:Integrated pop-up or sliding mechanisms enable cabin airflow without side-window turbulence. Sliding panoramic configurations bundle this capability at margin premiums.
UV protection represents universal fitment; solar control features are climbing the fastest as electrochromic deposition costs compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of laminated glass assemblies tilt heavily toward Chinese manufacturing clusters, while European and North American markets absorb premium sliding configurations with embedded thermal management. Import dependencies for high-purity silica sand concentrate supply risk in select geographies.
China
NEV production quotas administered by MIIT accelerate panoramic roof fitment across domestic EV platforms. SAMR-enforced GB standards for motor vehicle safety glazing mandate specific fragmentation patterns that favor laminated construction. The Yangtze River Delta cluster hosts multiple bonded assembly lines supplying BYD, NIO, and Tesla Shanghai with integrated roof modules.
Germany
Premium OEM programs from BMW, Mercedes-Benz, and Volkswagen drive specification pull for sliding rail mechanisms with electrochromic tint layers. REACH restrictions on heavy metals in automotive glazing force reformulation of tungsten-oxide-based electrochromic chemistries. Suppliers in Baden-Württemberg and Lower Saxony anchor European bonded assembly capacity.
United States
Domestic EV final assembly expansion by Tesla, Rivian, and Lucid Motors creates demand for large-format glass roofs with LiDAR transparency. NHTSA FMVSS 216 roof crush resistance testing extends validation timelines for panoramic designs entering the market. Michigan and California assembly plants source processed glass from captive North American laminating facilities.
Japan
Keiretsu supply relationships concentrate thermal management integration expertise among a tight supplier pool serving Toyota, Nissan, and Honda electrification platforms. METI carbon neutrality roadmaps incentivize lightweight glazing solutions. Aichi and Kanagawa prefectures host precision glass processing operations aligned with just-in-time OEM delivery schedules.
South Korea
Hyundai Motor Group and Kia Corporation consolidate roof system awards across multiple EV nameplates to extract volume leverage. MFDS automotive safety standards align with ECE R43 glazing requirements for export-bound vehicles. Gyeonggi-do province suppliers specialize in acoustic interlayer films for premium NVH targets.
Electric Vehicle Panoramic Sunroof Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration depth. The supplier base organizes into three tiers: integrated mechatronics platforms with bonded assembly capabilities, glass processors with captive laminating lines, and regional specialists serving single OEM programs. Strategic moves concentrate on M&A to secure electrochromic coating expertise and capacity expansion near high-volume EV assembly clusters.
Among German-origin roof system integrators, Webasto SE exemplifies the integrated mechatronics archetype through its dominance in sliding architectures. Magna International anchors North American supply with captive glass processing infrastructure. Aisin Seiki represents Japanese thermal management integration, embedding heating elements directly into glass laminates for cold-climate performance.
| Leading Market Players |
|---|
| Aisin Seiki |
| CIE Automotive |
| Webasto SE |
| BOS GmbH & Co. KG |
| Magna International |
| Inalfa Roof Systems |
| Yachiyo Industry |
| AGC Automotive Europe |
| Inteva Products |
| Others |
Pricing and Supply Chain Analysis
NHTSA FMVSS 216 roof crush resistance certification gates both supplier qualification and price differentiation in the EV panoramic sunroof market, creating tiered access where bonded assembly capabilities command sustained premiums over component-only vendors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium sliding configurations with electrochromic coatings and PTC thermal integration extract 40-60% price premiums over fixed-pane baselines, while polycarbonate alternatives undercut glass in entry-level segments. Cost compression in standard-tier fixed configurations is intensifying because Chinese NEV OEMs consolidate awards across multiple nameplates, squeezing margin from glass processors. Fleet procurement departments show highest price sensitivity, prioritizing total cost of ownership over feature bundling, whereas luxury EV platform architects remain least sensitive, absorbing premiums for autonomous sensor transparency and thermal management integration.
Supply Chain Analysis
Inventory cycles for ultra-clear low-iron glass extend 12-16 weeks due to high-purity silica sand concentration in China, the United States, and Australia. Laminated assembly draws from acoustic interlayer films produced in Germany and Japan, plus electrochromic coating chemicals subject to REACH heavy metal restrictions. Single-source vulnerability concentrates in bonded assembly line equipment, where German and Japanese machinery suppliers control precision sealing automation. Distribution runs through tier-one integrators with captive laminating capacity, though direct OEM procurement is displacing traditional channel structures in China's Yangtze River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV panoramic sunroof market sits at a platform-economics inflection where module commonality mandates across NEV nameplates are collapsing supplier diversity into integrated mechatronics ecosystems.
For Market Incumbents: Compound bonded assembly capabilities with backward integration into electrochromic coating deposition to defend against polycarbonate substitution in entry segments. Webasto SE and Magna International must secure sputtering expertise from display industry veterans before talent scarcity hardens, while expanding laminating capacity near Chennai and Pune to capture India's PLI scheme incentives. For New Entrants and Emerging Players: Anchor in aftermarket retrofit channels where first-generation EV glass roofs exit warranty coverage, creating replacement demand outside OEM captive supply. Target Germany and Japan's aging EV fleets with universal fitment kits, leveraging adaptable sealing profiles that bypass bonded assembly capital requirements entirely. For Investors and Strategic Acquirers: REACH's tungsten-oxide-free electrochromic reformulation deadline reshapes the acquisition landscape, privileging coating chemistry specialists over traditional glass processors. Long-term viability hinges on thermal management integration depth rather than commodity laminating scale. Watch for SAMR announcements expanding GB standards to mandate dynamic tint capabilities as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BYD and NIO's module commonality mandates halved qualified supplier pools since 2022. |
| Backward Integration into Coating | Captive sputtering capacity insulates margin from display industry talent competition. |
| Battery Supply Agreement | Photovoltaic-embedded laminates create energy-generating roof systems for extended-range EVs. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts glass processors to Chennai and Pune assembly clusters. |
| Software-Defined Vehicle Investment | LiDAR transparency requirements embed antenna pathways into continuous glass surfaces. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership service heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, customs records of laminated glass imports, and SAMR GB standard filings. Bottom-up volume triangulation across product type, material grade, and regional production clusters converged with top-down value estimates from OEM program award values.
Sensitivity analysis tested demand elasticity to NEV mandate stringency and silica sand price volatility across the projection horizon. Segmentation dimensions modeled include product architecture, thermal performance tier, material science specification, and autonomous sensor integration depth. CAGRs derived from fitted growth curves incorporating fleet electrification schedules, content-per-vehicle trajectories, and regional assembly capacity buildouts. Industry-specific inputs captured electrochromic switching speed requirements and FMVSS 216 certification timeline distributions.
Decision-makers should treat outputs as directional under assumptions of sustained NEV production quotas and stable low-iron silica supply; material deviation in autonomous sensor packaging requirements or REACH chemical restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
AC BEV On-Board Charger Market