
 North America Automotive High Performance Electric Vehicle Market | 2026-2036
North America Automotive High Performance Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive High Performance Electric Vehicle Market Intelligence
Revenue from proprietary software and over-the-air update services is tilting the profit landscape away from the traditional model of one-time vehicle sales. Tesla Inc. leverages its vertically integrated software stack to offer continuous performance upgrades and unlock features post-purchase. Meanwhile, Rivian differentiates with its adventure-focused vehicle software ecosystem, creating a dedicated brand following. Lucid competes on the basis of its advanced in-cabin technology and superior powertrain efficiency, targeting the premium luxury segment.
Automotive high-performance electric vehicles are defined by rapid acceleration, typically 0-60 mph under 4.5 seconds, and superior handling dynamics. They employ advanced battery management systems and high-output electric motors to deliver sustained power and extended range. Battery Electric Vehicles (BEVs) constitute the largest product type, outpacing plug-in hybrids among performance-focused buyers. Within powertrains, Permanent Magnet Synchronous Motors lead due to their efficiency and high power density.
The Environmental Protection Agency (EPA) sets emissions standards that indirectly promote EV adoption by penalizing less efficient internal combustion engine vehicles. Concurrently, NHTSA safety regulations and the tax credits within the US Inflation Reduction Act (IRA) shape vehicle design and affordability. OEMs must now navigate evolving battery sourcing requirements and charging standard interoperability to secure market share.
Market Dynamics
The competitive landscape is defined by the tension between government incentives designed to accelerate adoption and the complex battery supply chain requirements stipulated by those same policies. The US Inflation Reduction Act simultaneously stimulates consumer demand while imposing strict sourcing rules on OEMs.
Growth Catalysts
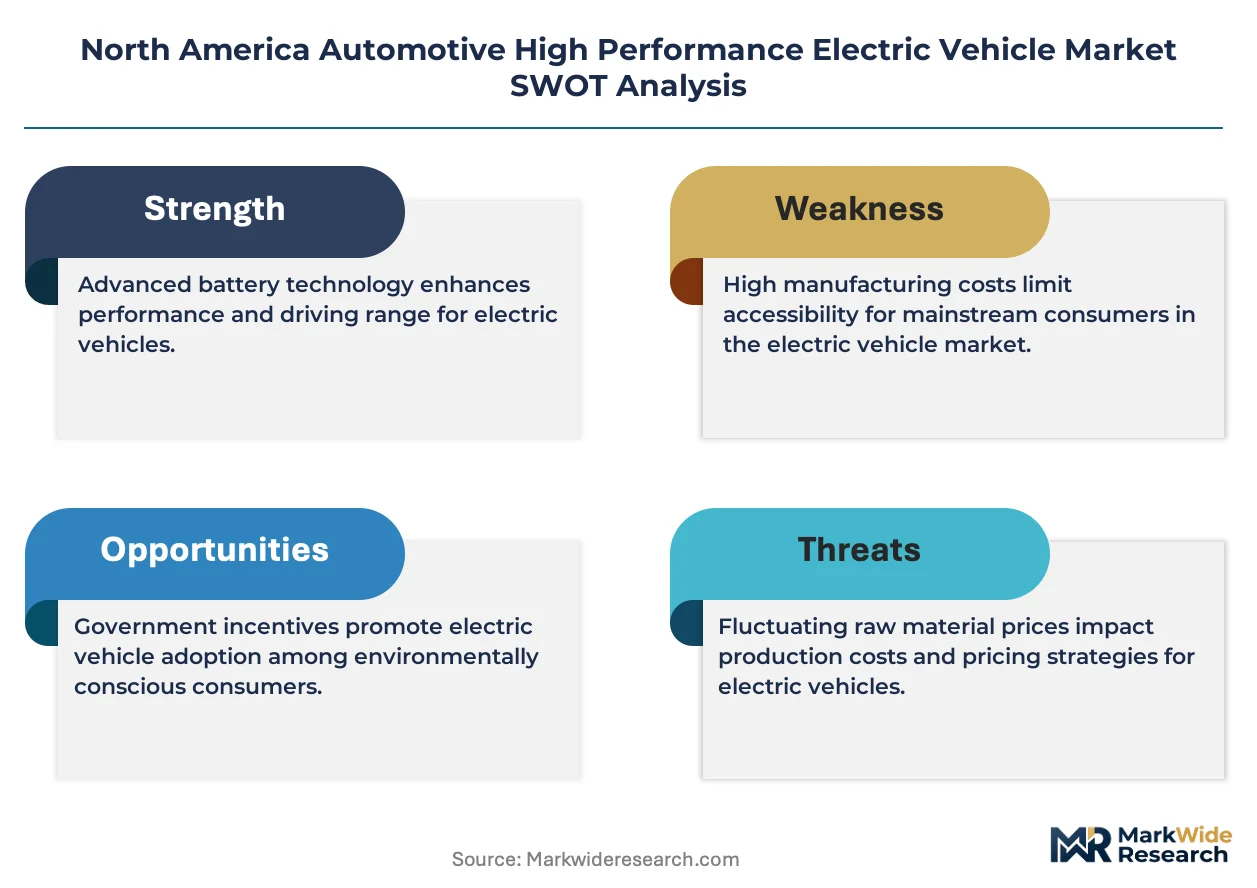
- Favorable Regulatory Frameworks:The US Inflation Reduction Act provides substantial consumer tax credits for qualifying new and used electric vehicles, directly lowering the purchase price and spurring demand from a wider base of consumers.
- Advancements in Battery Technology:Continuous improvements in battery management systems and cell chemistry are enhancing vehicle range, reducing charge times, and enabling the sustained power output required for high-performance driving applications.
- Concentrated Consumer Demand:Enthusiast buyers in affluent regions, particularly in states like California and Texas, demonstrate a strong preference for the instant acceleration and advanced technology features inherent in high-performance EVs.
Market Restraints
- Raw Material Volatility:The market is exposed to significant price fluctuations and supply chain instability for critical battery materials such as lithium, cobalt, and nickel, which directly impacts vehicle production costs and final pricing.
- Public Charging Infrastructure Gaps:Outside of major urban centers and key highway corridors, the availability of reliable, high-speed DC fast charging remains a significant barrier to ownership, creating range anxiety for long-distance travel.
- Battery Supply Chain Concentration:A heavy reliance on a few international regions for battery cell manufacturing and mineral processing creates geopolitical risks and logistical vulnerabilities for North American automotive manufacturers.
Strategic Opportunities
- Software and Subscription Services:Expanding revenue through over-the-air updates that unlock performance features, autonomous driving capabilities, or enhanced in-cabin experiences presents a significant opportunity for recurring income beyond the initial vehicle sale.
- Solid-State Battery Development:Investment in next-generation solid-state battery technology offers a pathway to leapfrog current lithium-ion limitations, promising greater energy density, enhanced safety, and faster charging for future models.
- Niche Vehicle Segment Electrification:There is untapped demand for high-performance variants in segments beyond passenger sedans, including electric pickup trucks, full-size SUVs, and purpose-built off-road vehicles that cater to adventure-focused consumers.
Industry Challenges
- Specialized Talent Scarcity:Automakers face intense competition for a limited pool of talent with expertise in battery chemistry, thermal management, and the complex software engineering required for advanced electric powertrain and vehicle operating systems.
- Charging Standard Interoperability:The transition toward the North American Charging Standard (NACS) while legacy Combined Charging System (CCS) infrastructure persists creates operational complexity for OEMs and potential confusion for consumers during the changeover period.
- High Capital Expenditure:The immense cost of retooling existing internal combustion engine manufacturing facilities or building new, dedicated EV production plants places significant financial strain on legacy automakers navigating the transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive High Performance Electric Vehicle Market |
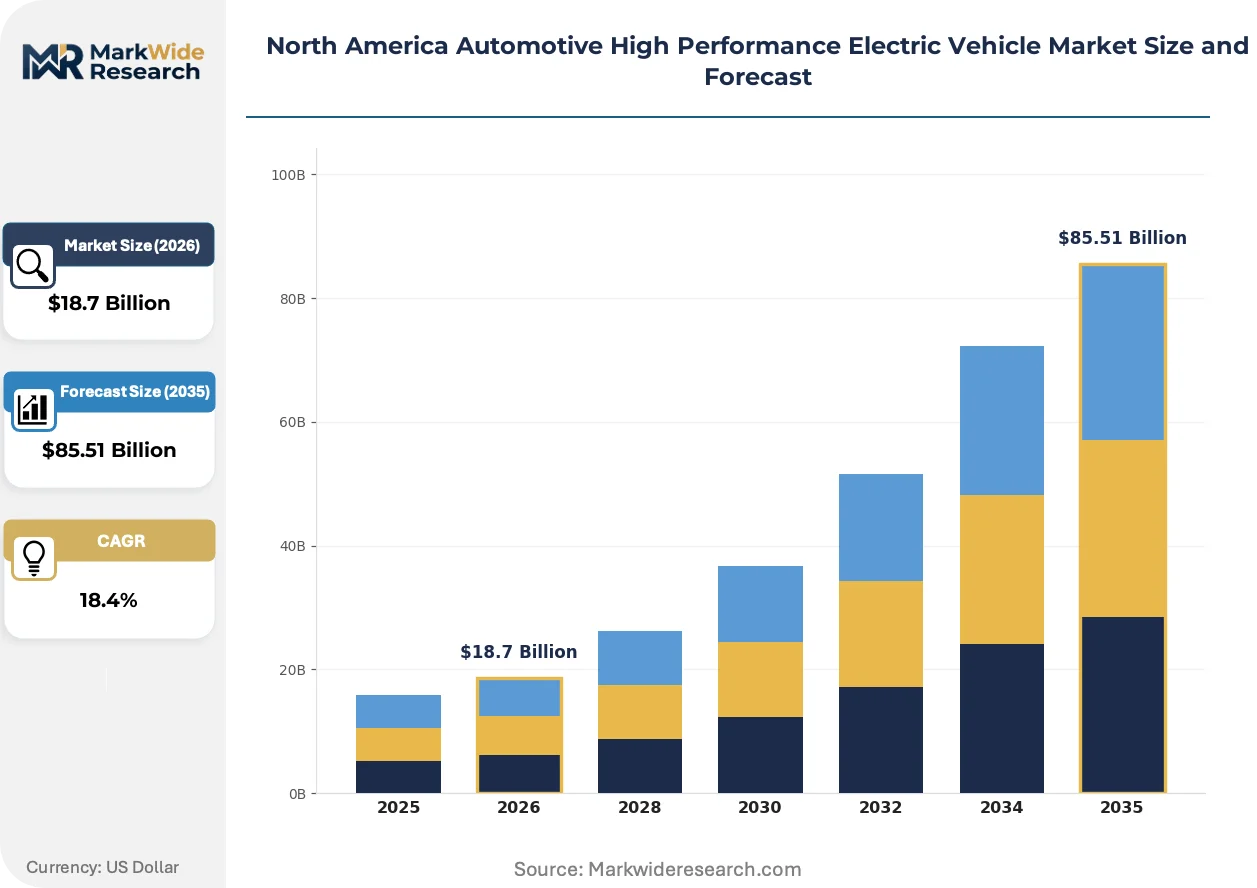
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Extended Range Electric Vehicles Powertrain Technology: Induction Motor, Permanent Magnet Synchronous Motor, Switched Reluctance Motor, Brushless DC Motor End User: Private Owners, Luxury Car Enthusiasts, Performance Car Retailers, Fleet Operators Charging Infrastructure: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Charging Stations |
| Companies Covered | Tesla Inc., General Motors, Ford Motor Company, Rivian, Lucid, Nissan Motor Co., Ltd, Mercedes-Benz USA, LLC, Volkswagen AG, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive High Performance Electric Vehicle Market Strategic Shifts & Innovations
Software is reshaping the definition of performance, moving beyond pure mechanical output to include user experience, upgradability, and system efficiency. The integration of advanced power electronics and intelligent vehicle software is creating a new competitive frontier for automakers in North America.
800-Volt Architectures and SiC Inverters
Silicon carbide (SiC) inverters are critical components that manage power flow from the battery to the electric motors. Performance EV manufacturers are rapidly adopting this technology to improve overall powertrain efficiency. As a result, the underlying vehicle power electronics architecture is migrating from legacy 400-volt systems with silicon-based components to more advanced 800-volt systems that enable faster charging and reduce energy loss.
Evolving Emissions and Safety Regulations
The Environmental Protection Agency (EPA) continues to tighten fleet-wide emissions standards for new vehicles. This regulatory pressure increases the effective cost of producing less efficient internal combustion engine vehicles, thereby improving the business case for OEM investment in high-performance EV platforms. The luxury and performance segments are most affected, as their traditional large-displacement engines face the highest compliance hurdles, accelerating their pivot to electric powertrains.
Shift to Post-Purchase Feature Unlocks
A fundamental shift in consumer engagement involves the unbundling of vehicle features through over-the-air (OTA) software updates. This model disrupts the traditional dealership-centric approach to options and accessories by allowing owners to purchase or subscribe to performance enhancements or convenience features after the initial sale. This trend is most prominent in the premium EV segment across the United States and Canada, where buyers show a higher propensity to pay for digital upgrades.
North America Automotive High Performance Electric Vehicle Market Segmentation
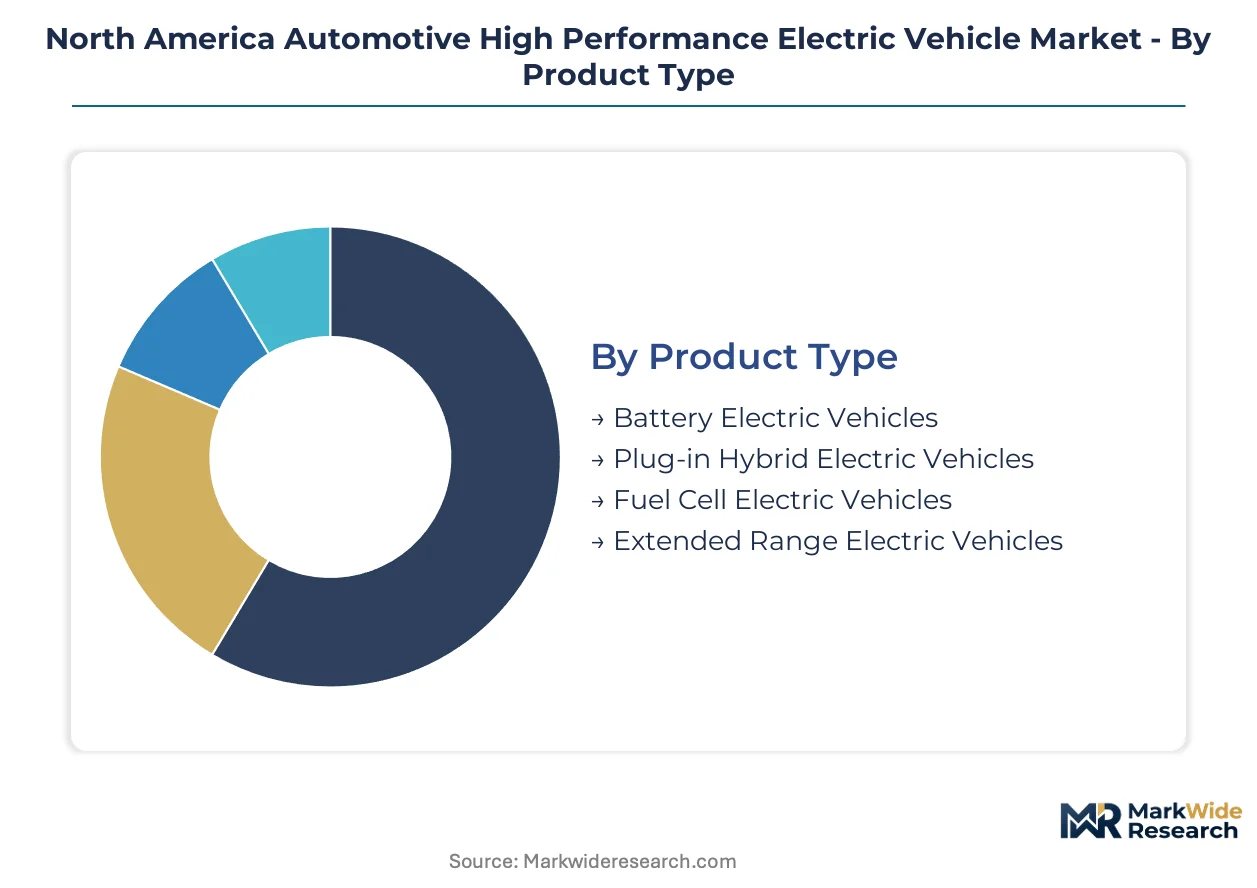
Market segmentation for high-performance electric vehicles provides clarity on diverse product preferences, technological adoption rates, and user behaviors shaping the North American landscape. Understanding these distinctions allows manufacturers to tailor offerings and infrastructure providers to optimize deployment strategies.
Product Type:
The various product types within high-performance electric vehicles exhibit distinct adoption cycles, influencing manufacturing priorities and consumer upgrade paths across North America.
- Battery Electric Vehicles:These vehicles rely solely on battery power for propulsion, featuring large battery packs and high-output electric motors. Demand concentrates in states like California and Texas, driven by instant torque delivery and zero tailpipe emissions, supported by US Inflation Reduction Act incentives.
- Plug-in Hybrid Electric Vehicles:PHEVs combine an electric motor and battery with an internal combustion engine, offering both electric-only range and gasoline backup. These appeal to consumers seeking flexibility for longer journeys, particularly in regions with developing charging infrastructure in North America.
- Fuel Cell Electric Vehicles:FCEVs generate electricity from hydrogen via a fuel cell, emitting only water vapor.
- Extended Range Electric Vehicles:EREVs feature a small gasoline generator to extend the electric range, reducing range anxiety for drivers.
Battery Electric Vehicles dominate the installed base. Plug-in Hybrid Electric Vehicles are where expansion concentrates for range-conscious performance buyers.
Powertrain Technology:
Powertrain technologies vary significantly in their prevalence and performance characteristics across high-performance EV platforms.
- Permanent Magnet Synchronous Motor:PMSMs use permanent magnets in the rotor, offering high power density and efficiency for sustained performance. These motors lead the market due to their superior efficiency and compact size, crucial for high-performance EV designs in North America.
- Induction Motor:Induction motors operate without permanent magnets, relying on electromagnetic induction to create rotor current and torque. These are widely adopted for their robustness and cost-effectiveness, particularly in earlier EV models and some current mass-market offerings.
- Switched Reluctance Motor:SRMs operate on the principle of reluctance torque, offering simplicity and fault tolerance without permanent magnets.
- Brushless DC Motor:BLDC motors are electronically commutated, providing high efficiency and reliability for various electric vehicle applications.
Permanent Magnet Synchronous Motors establish the performance benchmark. Induction Motors provide a balance of cost and reliability.
End User:
Different end-user segments approach the high-performance EV market with distinct motivations and purchasing behaviors.
- Luxury Car Enthusiasts:This segment comprises affluent individuals who prioritize cutting-edge technology, superior acceleration, and exclusive brand experiences. Their demand is a primary catalyst for market expansion, particularly in affluent regions like California and Texas.
- Private Owners:Individual consumers purchasing high-performance EVs for personal use, driven by a blend of performance, environmental consciousness, and technology. US Inflation Reduction Act tax credits significantly lower the purchase price, accelerating adoption among this broad consumer base.
- Performance Car Retailers:Dealerships and specialized outlets cater to performance buyers, influencing brand perception and vehicle availability.
- Fleet Operators:Commercial entities and rental companies integrate high-performance EVs for corporate fleets or premium rental services, focusing on total cost of ownership.
Luxury Car Enthusiasts drive innovation and premium segment growth. Private Owners represent the largest volume opportunity.
Charging Infrastructure:
Charging infrastructure types represent varying stages of deployment and impact on high-performance EV utility across North America.
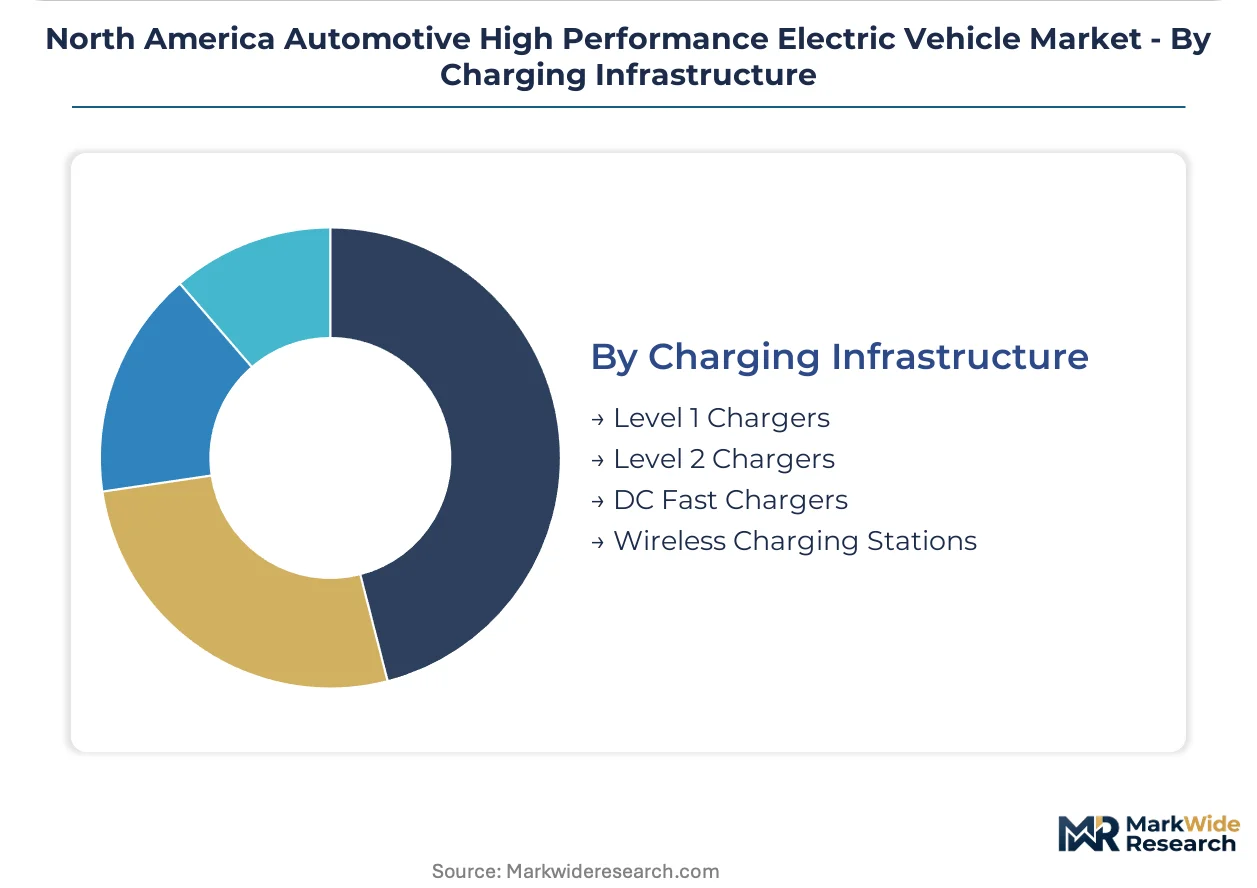
- DC Fast Chargers:These high-power charging stations deliver direct current directly to the vehicle battery, enabling rapid charge times. Their availability is crucial for long-distance travel and reducing range anxiety, especially along key highway corridors in North America.
- Level 2 Chargers:Level 2 chargers use 240-volt AC power, commonly found in homes, workplaces, and public charging stations. These provide a balance of charging speed and accessibility, forming the backbone of daily EV charging for most owners.
- Level 1 Chargers:Level 1 chargers utilize a standard 120-volt household outlet, offering the slowest but most accessible charging option.
- Wireless Charging Stations:These stations enable inductive charging without physical connections, providing convenience for future EV integration.
DC Fast Chargers are indispensable for performance EV usability. Wireless Charging Stations are poised for future integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for high-performance electric vehicles exhibit distinct characteristics across North America, reflecting varied economic landscapes and policy incentives. The United States leads in market size and infrastructure rollout, significantly bolstered by federal tax credits. Canada shows a strong affinity for premium EV offerings and digital services, while Mexico is in the early stages of market expansion.
United States
United States demand for high-performance electric vehicles is strongly propelled by luxury car enthusiasts who prioritize instant torque and cutting-edge technology. The US Inflation Reduction Act provides substantial consumer tax credits, directly lowering purchase costs and accelerating market adoption. Market activity concentrates in affluent states like California and Texas, which lead in both vehicle sales and advanced DC fast charging infrastructure development.
Canada
Canada's high-performance EV market demonstrates a strong preference for premium segments, where buyers actively embrace digital upgrades and enhanced in-cabin technology. Federal and provincial incentives, alongside carbon pricing mechanisms, encourage the widespread transition to electric powertrains. Major urban centers across Canada are seeing increased deployment of Level 2 and high-speed DC fast charging infrastructure to support this expanding demand.
Mexico
Mexico represents an emerging market for high-performance electric vehicles, with growing interest from consumers seeking advanced technology and sustainable transportation options. Government initiatives focus on promoting EV adoption through import duty reductions and the development of public charging networks in key urban areas. Mexico City and other metropolitan regions are witnessing initial investments in charging solutions to support early adopters and future market growth.
North America Automotive High Performance Electric Vehicle Market Key Industry Players
Capability concentration sits with one tier, often comprising specialized EV manufacturers focusing on performance and technology; scale advantage sits with another, typically established automotive OEMs with extensive production capacities. The market structure exhibits a dynamic tension between these specialized innovators and traditional industry giants. Strategic archetypes include dedicated EV pioneers, diversified legacy automakers, and luxury segment specialists. Dominant competitive moves involve significant capital expenditure in new EV platforms and strategic partnerships for battery supply chain security.
Dedicated EV pioneers like Tesla Inc. exemplify the capability-focused tier, leveraging vertically integrated software stacks for continuous performance upgrades and post-purchase feature unlocks. Tesla's approach highlights the shift towards recurring revenue streams beyond the initial vehicle sale. Rivian occupies a position as an adventure-focused EV manufacturer, clearly differentiating through its unique software ecosystem tailored for niche vehicle segments such as electric pickup trucks and SUVs. Lucid, meanwhile, represents the premium luxury segment, competing on the basis of advanced in-cabin technology and superior powertrain efficiency to attract discerning buyers with its focus on extended range and refined experience.
| Leading Market Players |
|---|
| Tesla Inc. |
| General Motors |
| Ford Motor Company |
| Rivian |
| Lucid |
| Nissan Motor Co., Ltd |
| Mercedes-Benz USA, LLC |
| Volkswagen AG |
| Hyundai Motor Company |
| Others |
Cost & Logistics Intelligence
Concentration of critical battery material processing in a few international regions exerts significant influence on downstream vehicle pricing and profit margins for North American OEMs. This upstream control directly impacts the cost structure of high-performance EVs.
Pricing Analysis
Long-term offtake agreements for critical battery materials heavily influence the transactional pricing model for high-performance electric vehicles. Price differentiation stems from advanced in-cabin technology and superior powertrain efficiency, commanding a brand premium for luxury segments. Pricing pressure on OEMs intensifies due to raw material volatility for lithium and cobalt. Luxury car enthusiasts exhibit lower price sensitivity, while private owners' adoption is more responsive to US Inflation Reduction Act tax credits.
Supply Chain Analysis
Geopolitical risks stemming from concentrated battery cell manufacturing in specific international regions pose a significant challenge to North American automotive OEMs. The supply chain relies heavily on lithium, cobalt, and nickel, primarily sourced and processed from a few key countries. Commodity price volatility for these critical materials creates production cost instability. Vehicle distribution primarily occurs through established dealership networks, alongside direct-to-consumer models for dedicated EV pioneers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American high-performance EV market faces a critical talent gap, particularly in battery chemistry and advanced software engineering. This scarcity of specialized expertise shapes competitive dynamics and strategic opportunities for all market participants.
For Market Incumbents:
Harden existing manufacturing capabilities by retooling for 800-volt architectures and silicon carbide inverters, countering efficiency gains from dedicated EV pioneers. Secure long-term battery material supply through strategic partnerships and upstream investments, mitigating raw material volatility risks. Invest in specialized talent for thermal management and software engineering to maintain competitive advantage against emerging technology. This proactive stance defends against margin pressure from rising input costs and rapid technological shifts.
For New Entrants and Emerging Players:
Build out differentiated software ecosystems that unlock performance features and unique in-cabin experiences, targeting specific niche segments like adventure-focused consumers. Electrify underserved vehicle categories such as full-size SUVs and purpose-built off-road vehicles to capture untapped demand. Focus initial market entry on regions with strong enthusiast demand and developing charging infrastructure, leveraging a direct-to-consumer model. This strategy allows for agile innovation and avoids direct competition with established mass-market players.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with early-stage battery technology developers and specialized software providers focused on vehicle operating systems. The long-term viability of high-performance EVs remains strong, driven by sustained consumer demand for cutting-edge technology. Identify acquisition targets offering proprietary power electronics or advanced battery management systems. A key signal to watch is the successful commercialization of solid-state battery technology, which could fundamentally reshape the market.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Chain Security | Ensures stable production and cost control amidst raw material volatility for North American OEMs. |
| Software-Defined Vehicle Investment | Unlocks recurring revenue streams and continuous performance upgrades, enhancing customer loyalty for manufacturers. |
| 800-Volt Architecture Adoption | Improves charging speed and powertrain efficiency, critical for sustained high-performance EV capabilities. |
| Niche EV Segment Electrification | Captures untapped demand in segments like electric pickup trucks, expanding market reach for new entrants. |
| Charging Infrastructure Partnerships | Addresses range anxiety and expands reliable high-speed DC fast charging availability across North America. |
Research Approach
The analysis maps high-performance Battery Electric Vehicles, advanced Powertrain Technology, and Charging Infrastructure, each validated through primary interviews with OEM platform engineers, battery material suppliers, and charging network operators. This primary intelligence was triangulated with extensive secondary research, including US Inflation Reduction Act documents, EPA emissions standards, and vehicle registration data. A blend of top-down market sizing and bottom-up validation ensured robust data integrity.
Assumptions regarding battery technology advancements and regulatory stability were held fixed, while consumer adoption rates and infrastructure deployment varied across scenarios over the projection horizon. The quantitative model incorporated segmentation dimensions including product type, powertrain technology, end user, and charging infrastructure. Compound annual growth rates were derived from market share projections and regression analysis. Key forecast inputs included battery energy density improvements and charging network expansion rates.
Practitioners should monitor raw material price volatility and geopolitical shifts for early signals that could necessitate forecast revisions. The analysis reflects assumptions current at the time of publication, acknowledging potential impacts from evolving charging standard interoperability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Mexico Electric Car Market