
 US Automotive High Performance Electric Vehicle Market | 2026-2036
US Automotive High Performance Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive High Performance Electric Vehicle Market Intelligence
The Environmental Protection Agency's (EPA) increasingly stringent emissions standards for light-duty vehicles is broadening the addressable market for high-performance EVs. Tesla leverages its Supercharger network and established brand to maintain a significant market position. Rivian specializes in the electric SUV and truck segments, targeting a distinct adventure-focused consumer base. Ford competes directly with its electric Mustang Mach-E and F-150 Lightning models, adapting iconic nameplates for the EV era.
US automotive high-performance electric vehicles are defined by advanced powertrain capabilities, often achieving 0-60 mph acceleration under 4.5 seconds with battery packs over 80 kWh. They deliver driving dynamics superior to many internal combustion engine counterparts. Within vehicle types, luxury sedans and electric SUVs command the largest share of new registrations. In battery technology, development of solid-state options is accelerating, promising significant range and safety improvements over existing Lithium-ion chemistries.
The National Highway Traffic Safety Administration (NHTSA) imposes critical safety standards for EV battery packs and overall vehicle structures. The Inflation Reduction Act (IRA) directly shapes consumer demand through its domestic manufacturing and sourcing requirements for tax credits. Consequently, automaker strategy now hinges on securing compliant battery supply chains to maintain price competitiveness for US buyers.
Market Dynamics
The competitive landscape of the US high-performance electric vehicle market is shaped by the dual pressures of federal policy and state-level mandates. The Inflation Reduction Act's tax credit structure incentivizes domestic battery and vehicle assembly, directly influencing automaker supply chain strategies.
Growth Catalysts
- Stricter EPA Standards:The Environmental Protection Agency's progressively tightening emissions regulations for light-duty vehicles compel automakers to expand their EV portfolios, increasing the availability of high-performance models to meet fleet-wide compliance targets.
- Battery Technology Advancement:Continuous improvements in the energy density of Lithium-ion battery packs enable longer range and faster acceleration, directly addressing key performance metrics for consumers in the high-performance segment.
- State-Level Mandates:Aggressive zero-emission vehicle (ZEV) mandates and substantial investments in charging infrastructure, particularly in California, create concentrated zones of high demand and accelerate adoption within the state.
Market Restraints
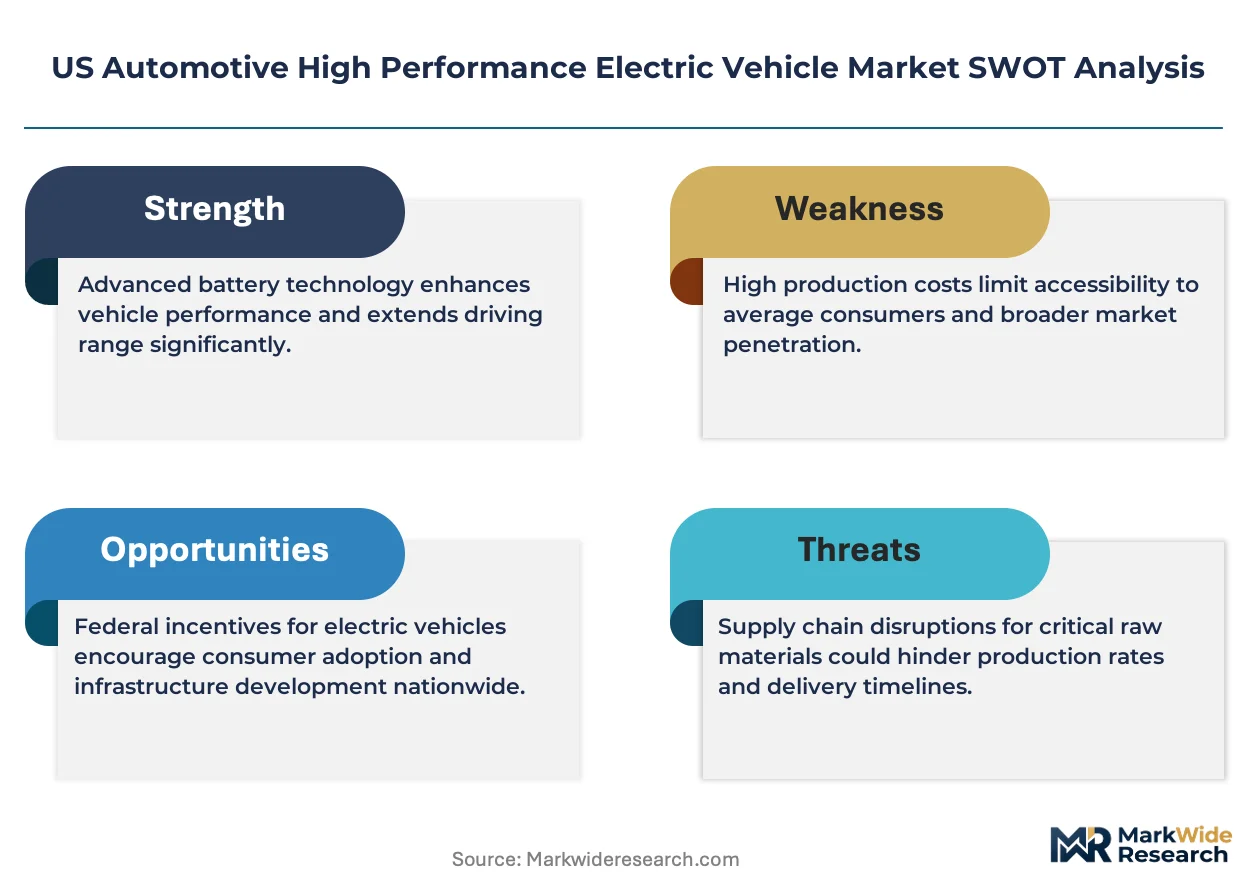
- Raw Material Cost Volatility:The price of critical battery minerals, including lithium and cobalt, remains volatile and high, which translates directly to higher manufacturing costs and elevated vehicle sticker prices for consumers.
- Battery Supply Chain Concentration:A heavy reliance on foreign sources for the processing of essential battery materials creates significant supply chain risks for US automakers, potentially leading to production delays and cost overruns.
- Charging Infrastructure Gaps:A lack of sufficient and reliable high-speed DC fast charging stations in many rural areas and along certain interstate corridors in the US limits the practicality of long-distance travel for high-performance EV owners.
Strategic Opportunities
- Geographic Expansion:Automakers have a significant opportunity to target market expansion in states across the Midwest and Southeast, where EV adoption has historically lagged but is now poised for growth with expanding charging networks.
- Commercial Vehicle Segments:Development of high-performance electric light-duty trucks and cargo vans for commercial fleet operators presents a major growth vector, appealing to businesses focused on total cost of ownership and vehicle uptime.
- Domestic Supply Chain Localization:The IRA's domestic content requirements create a clear opportunity for automakers that successfully onshore battery cell and pack manufacturing to gain a significant pricing advantage through federal tax credits.
Industry Challenges
- Manufacturing Retooling Costs:The immense capital investment required to convert legacy internal combustion engine assembly plants to support EV platform production presents a substantial financial hurdle for established automakers.
- Specialized Talent Shortages:A deficit of skilled battery engineers, software developers, and vehicle technicians in the US workforce creates operational bottlenecks in research, development, and after-sales service for advanced EVs.
- Regulatory Compliance Complexity:Navigating the intricate and evolving battery sourcing and assembly rules stipulated by the Inflation Reduction Act to maintain eligibility for consumer tax credits is a major operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive High Performance Electric Vehicle Market |
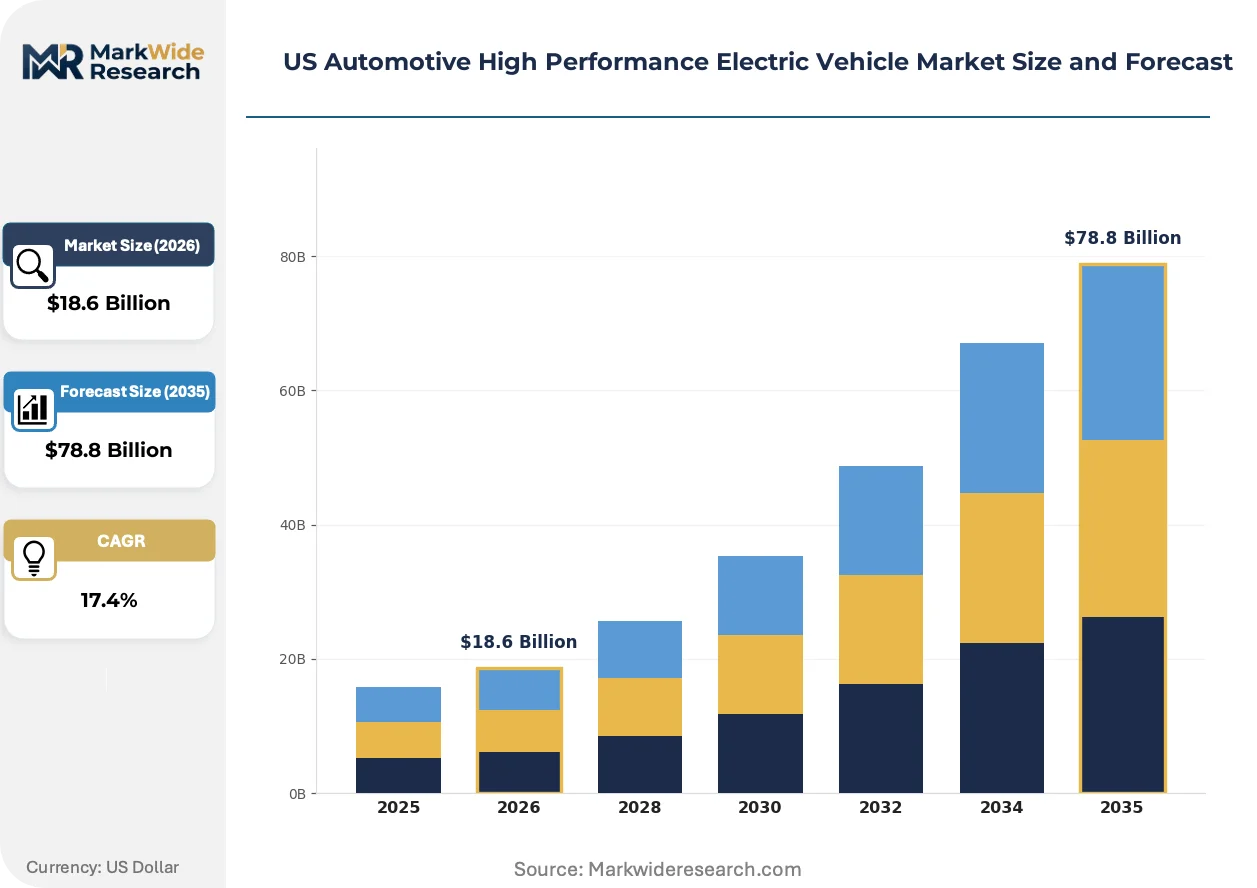
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $78.8 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sports Cars, Luxury Sedans, Electric SUVs, Performance Coupes, Electric Roadsters Battery Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Lithium Polymer, Flow Batteries Charging Infrastructure: Fast Chargers, Level 2 Chargers, Wireless Charging, Home Charging Stations, Public Charging Networks End User: Private Owners, Fleet Operators, Specialty Dealers, Performance Tuners, Ride-Sharing Services |
| Companies Covered | Rivian, Hyundai, Tesla, Honda, GMC, Chevrolet, Lucid Group, Cadillac, Ford, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive High Performance Electric Vehicle Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware-centric performance metrics to software-enabled capabilities. This shift is reshaping how vehicle performance is defined, delivered, and monetized over the vehicle's lifecycle, with an emphasis on battery efficiency and charging speed.
An 800-volt battery architecture enables significantly faster charging speeds and improved thermal management for sustained power output. Luxury and performance-oriented automakers are rapidly adopting this technology to differentiate their premium models. The advancement is consolidating the definition of "high-performance" to include charging velocity and consistent power delivery, moving beyond simple acceleration metrics.
New safety guidance from the National Highway Traffic Safety Administration (NHTSA) is placing greater scrutiny on EV battery pack integrity during collisions and thermal runaway events. This regulatory focus compels automakers to engineer more robust battery enclosures and sophisticated battery management systems. Electric SUV and pickup truck segments are most impacted, as their larger battery packs require more advanced structural and safety solutions.
A notable behavioral shift sees consumers valuing over-the-air (OTA) software updates as a primary vehicle feature, allowing for performance enhancements and new functionalities post-purchase. This disrupts the traditional automotive model where performance is static, enabling automakers to offer performance-as-a-service through subscriptions. This trend is most prominent in tech-forward US markets like the West Coast and Northeast corridor.
US Automotive High Performance Electric Vehicle Market Segmentation
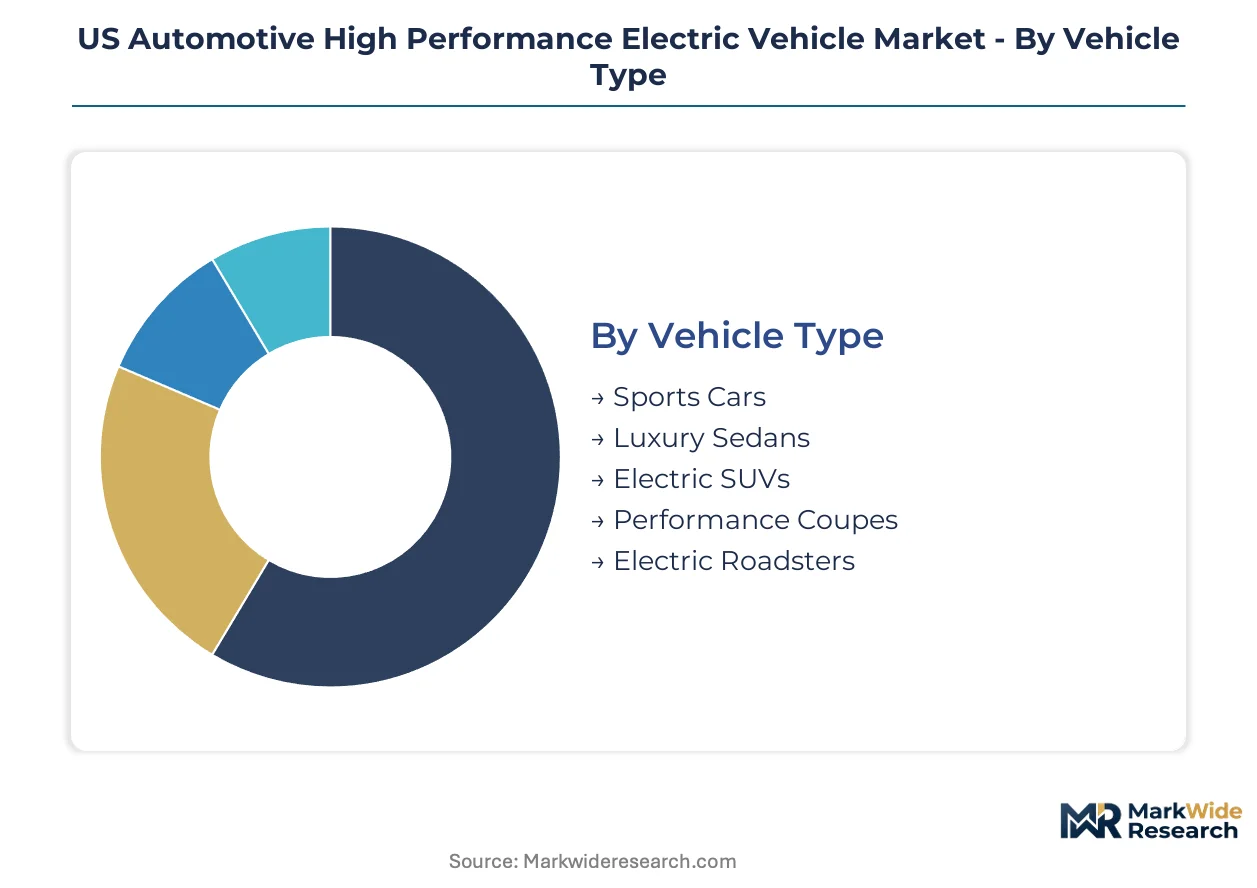
The US automotive high-performance electric vehicle market segments reflect distinct technological capabilities and consumer adoption patterns. Analyzing these categories reveals where innovation concentrates and how regulatory frameworks influence market dynamics. Understanding these divisions helps stakeholders identify key growth vectors and address specific market needs.
Vehicle Type:
The regulatory burden for new vehicle launches often depends on the vehicle's classification, impacting testing and approval processes by the NHTSA.
- Electric SUVs:These vehicles offer a blend of utility, space, and performance, often appealing to families and fleet operators. Demand is particularly pronounced in California, driven by state-level mandates and extensive charging network availability.
- Luxury Sedans:This segment commands a significant share of new registrations, offering advanced driving dynamics and premium features. Consumers in urban centers and the Northeast corridor prioritize these models for their sophisticated technology and comfort.
- Sports Cars:Focused on pure driving exhilaration, these models prioritize acceleration and handling.
- Performance Coupes:This category balances sporty aesthetics with strong electric powertrain capabilities.
- Electric Roadsters:Open-top electric vehicles designed for an engaging, performance-oriented driving experience.
Leading the category by volume: Electric SUVs. Growing fastest: Luxury Sedans.
Battery Technology:
The maturity and commercial viability of different battery technologies directly influence vehicle range, charging speed, and overall cost structures for US buyers.
- Lithium-ion:This chemistry remains the dominant power source for high-performance EVs, balancing energy density with established manufacturing processes. Automakers face challenges with raw material cost volatility and supply chain concentration for these batteries.
- Solid State:An emerging technology promising significant improvements in energy density, safety, and charging times for future EV generations. Development is accelerating, offering a strategic opportunity for enhanced vehicle performance.
- Nickel-Metal Hydride:An older, less energy-dense battery chemistry, largely superseded in high-performance applications.
- Lithium Polymer:Offers design flexibility but typically provides lower energy density compared to advanced Lithium-ion formulations.
- Flow Batteries:Primarily in research and development, these batteries are not yet commercially viable for automotive applications.
Lithium-ion technology holds the largest market share. Solid State battery development is gaining momentum.
Charging Infrastructure:
Customer use patterns and the availability of reliable charging solutions dictate the practicality and convenience of high-performance EV ownership across the US.
- Fast Chargers:Essential for enabling long-distance travel and minimizing charging times for high-performance electric vehicles. Deployment is concentrated in California, but significant gaps persist in many rural areas and interstate corridors.
- Home Charging Stations:Represent the primary and most convenient charging solution for most private owners, facilitating daily vehicle use. The Inflation Reduction Act provides incentives that support the installation of these systems.
- Level 2 Chargers:Widely available at public and workplace locations, offering a balance of charging speed and accessibility.
- Wireless Charging:An innovative technology offering convenience, though its power delivery capabilities are still developing for high-performance EVs.
- Public Charging Networks:Critical for urban mobility and interstate travel, but reliability and availability vary significantly across different US regions.
Fast Chargers are essential for long-haul practicality. Home Charging Stations represent the most common point of use.
End User:
Different customer types exhibit distinct purchasing motivations and utilization patterns for high-performance electric vehicles, influencing product development and sales strategies.
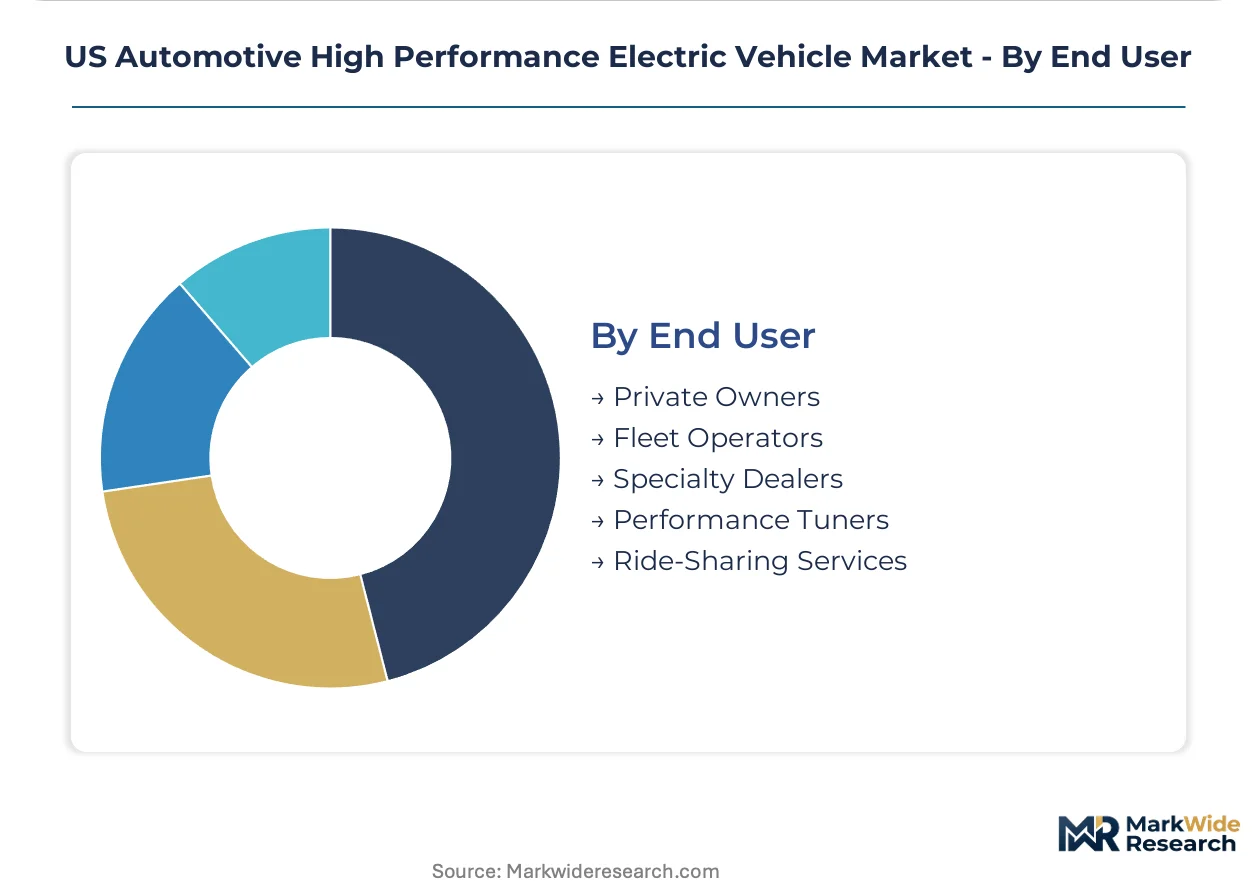
- Private Owners:These individual consumers prioritize acceleration, luxury, and advanced technological features in their vehicle choices. Demand is particularly strong in tech-forward US markets like the West Coast and Northeast corridor.
- Fleet Operators:Businesses adopting high-performance electric SUVs and light-duty trucks for commercial operations. Their decisions are influenced by total cost of ownership, vehicle uptime, and environmental compliance, especially with stricter EPA standards.
- Specialty Dealers:Cater to niche markets for highly customized or exclusive high-performance electric vehicle models.
- Performance Tuners:Aftermarket specialists who modify and enhance the performance capabilities of electric vehicles.
- Ride-Sharing Services:Show limited current adoption of high-performance EVs due to higher acquisition costs and specific operational requirements.
Private Owners constitute the largest segment. Fleet Operators show significant expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's extensive charging infrastructure and state-level mandates drive significant demand for high-performance electric vehicles. This concentration of early adopters and supportive policies establishes a strong foundation for market expansion. The state's aggressive zero-emission vehicle targets further accelerate EV adoption.
California
Demand for electric SUVs and luxury sedans is pronounced, driven by environmental consciousness and tech-forward consumer bases. The California Air Resources Board (CARB) mandates stringent zero-emission vehicle (ZEV) requirements for automakers. Silicon Valley and Los Angeles represent key hubs for both EV innovation and high-performance EV registrations.
Northeast Corridor
Urban centers and affluent populations in the Northeast prioritize sophisticated technology and advanced driving dynamics in luxury EV sedans. States like New York and Massachusetts offer various incentives, including purchase rebates and charging infrastructure grants. Boston and New York City exhibit high concentrations of early adopters and premium EV sales.
Texas
Growing interest in high-performance electric trucks and SUVs defines the Texas market, appealing to consumers seeking utility and power. The state's expanding charging networks, though still developing, are critical for supporting long-distance travel. Austin and Dallas are emerging as significant growth areas for EV registrations and related infrastructure development.
Southeast
Fleet operators increasingly adopt high-performance electric SUVs and light-duty trucks across the Southeast, driven by total cost of ownership benefits. States such as Georgia and Florida are investing in public charging solutions and offering tax incentives for EV purchases. Atlanta and Orlando are experiencing notable increases in EV sales and charging station deployments.
US Automotive High Performance Electric Vehicle Market Key Industry Players
Premium-margin players sit above commodity-margin players across powertrain innovation and brand perception in the US high-performance EV market. The competitive structure is characterized by a blend of established automotive manufacturers and specialized electric vehicle disruptors. Strategic archetypes include luxury performance innovators, utility-focused adventure vehicle developers, and traditional automotive giants adapting iconic models. Automakers are pursuing significant capital investment in manufacturing retooling and strategically securing compliant domestic battery supply chains to maintain price competitiveness.
Within the luxury performance innovator archetype, Tesla represents a company driving advancements in battery technology and software-enabled vehicle features. Tesla leverages its extensive Supercharger network and established brand to maintain a significant market presence among private owners. Rivian exemplifies the utility-focused disruptor, specializing in electric SUVs and trucks that target an adventure-oriented consumer base and fleet operators. Ford, a traditional automotive giant, adapts its iconic nameplates like the Mustang Mach-E and F-150 Lightning, competing directly in the performance EV segment with a broad appeal.
| Leading Market Players |
|---|
| Rivian |
| Hyundai |
| Tesla |
| Honda |
| GMC |
| Chevrolet |
| Lucid Group |
| Cadillac |
| Ford |
| Others |
Cost & Logistics Intelligence
Established automotive giants and specialized EV disruptors are channeling significant investment into securing compliant battery supply chains, directly influencing vehicle pricing and market competitiveness. This strategic focus aims to stabilize input costs and leverage tax incentives, which in turn affects the final sticker price for US buyers.
Pricing Analysis
Value-based pricing for high-performance electric vehicles is anchored in advanced powertrain capabilities and software-enabled features. Price differentiation stems from brand premium, sophisticated 800-volt architectures, and customization levels offered by manufacturers. Pricing pressure continues to trend upward due to persistent raw material cost volatility and substantial research and development investments in next-generation battery technologies. Fleet operators exhibit the highest price sensitivity, driven by total cost of ownership, while private luxury buyers are less sensitive to initial vehicle costs.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China, South Korea, and Japan significantly impacts the supply of critical battery components for the US market. The supply chain draws from raw material dependencies on lithium, cobalt, and nickel. A primary structural risk involves the heavy reliance on foreign processing of essential battery materials, creating potential production delays. Distribution runs through both direct-to-consumer models, exemplified by Tesla and Rivian, and traditional dealership networks utilized by Ford and other legacy automakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players aggressively pursuing upstream control over battery material sourcing and processing to secure competitive advantages.
For Market Incumbents:Deepen domestic battery supply chain partnerships to mitigate the growing regulatory compliance risks imposed by the Inflation Reduction Act. Retool legacy internal combustion engine assembly plants to accelerate EV platform production, countering the agility of specialized EV disruptors. Invest strategically in advanced manufacturing processes for next-generation solid-state battery technologies. Prioritize securing long-term contracts for critical minerals to stabilize production costs.
For New Entrants and Emerging Players:Begin with niche segments such as adventure-focused electric SUVs or specific commercial fleet applications where utility and performance are paramount. Target underpenetrated geographic areas like the Midwest and Southeast, leveraging expanding charging networks. Offer unique software-defined vehicle features and performance-as-a-service models as a distinct go-to-market angle. Focus on rapid iteration and over-the-air updates to differentiate product offerings.
For Investors and Strategic Acquirers:Distressed-cycle entries favor battery technology innovators in the US, offering long-term viability over the coming decade. Focus on firms with proprietary solid-state battery development or advanced thermal management systems that promise significant range and safety improvements. Watch for regulatory clarity on domestic content requirements for IRA tax credits as a key inflection indicator for investment decisions. Seek out companies with established intellectual property in battery management systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures critical raw materials and components, ensuring stable production for electric vehicles. |
| Software-Defined Vehicle Investment | Enables over-the-air updates and unlocks new performance-as-a-service revenue streams. |
| Charging Infrastructure Partnership | Expands network access, directly reducing range anxiety for high-performance EV owners. |
| Geographic Manufacturing Footprint | Optimizes production for regional demand while leveraging federal and state tax incentives. |
| Platform Standardization | Reduces research and development costs, accelerating new electric vehicle model development cycles. |
Research Approach
Document review covered EPA emissions standards, NHTSA safety guidelines, and IRA legislative texts, complemented by interviews with industry stakeholders. Engaged OEM platform engineers, battery material suppliers, charging network operators, and fleet procurement managers provided primary insights. Secondary validation involved vehicle registration databases, industry association reports, and financial disclosures. Bottom-up and top-down triangulation ensured data integrity and comprehensive market understanding.
The model produced detailed market projections across the analysis window, segmenting by vehicle type, battery technology, charging infrastructure, and end-user categories. CAGR derivation considered historical trends and future growth catalysts, including regulatory shifts and technological advancements. Industry-specific forecast inputs included EV adoption rates, battery cost reduction curves, and public charging station deployment schedules. This framework provided a robust quantitative outlook.
Underlying measurement precision varies by segment; luxury sedans and electric SUVs carry tighter precision than sports cars. Forecasts reflect assumptions regarding technological advancements and regulatory stability within the US market. Material deviation in raw material pricing or federal policy triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Vietnam Electric Vehicle Market