
 Electric Vehicle Relay Market | 2026-2036
Electric Vehicle Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Relay Market Foresight
Modular relay packaging for integrated battery management units is hardening as the default procurement specification for EV platforms. TE Connectivity Ltd. leverages its automotive connector heritage to anchor high-voltage relay distribution across European OEM supply chains. Panasonic Corporation specializes in compact solid-state configurations that sustain thermal performance under 800-volt architectures. Robert Bosch GmbH dominates electromechanical relay production through backward integration into contact material processing.
An electric vehicle relay is a switching device engineered to manage current flow between 12 volts and 1,000 volts in traction systems, typically employing silver-nickel or silver-tin oxide contact materials to withstand arc erosion across millions of duty cycles. Its primary purpose is to isolate battery packs, control charging paths, and protect onboard power electronics from fault conditions. High-voltage relays command the dominant share of value given their role in 400-volt and 800-volt platforms, while solid-state relay adoption is accelerating fastest in charging station infrastructure where switching speed and cycle life outweigh electromechanical cost advantages. Power management applications concentrate the largest volume demand, though battery systems represent the deepest margin pool as cell-to-pack architectures multiply relay counts per vehicle.
FDA oversight of automotive-grade materials remains indirect, yet EPA tailpipe regulations and NHTSA safety mandates in the United States compress development timelines for relay qualification. China's MIIT enforces GB standards for high-voltage isolation that foreign suppliers must satisfy for NEV component certification. The EU's F-Gas Regulation and REACH chemical restrictions are reshaping contact material compositions across the supply base. Stakeholders must monitor how solid-state technology maturation alters the electromechanical-to-hybrid transition point in their product roadmaps.
Market Dynamics
The transition from 400-volt to 800-volt EV architectures is compressing relay qualification timelines while multiplying contact material specifications per platform. Battery pack designers now demand switching components that sustain higher thermal loads without expanding footprint, forcing simultaneous advances in arc quenching and miniaturization.
Growth Catalysts
- China's NEV Mandates:MIIT-enforced GB standards for high-voltage isolation are accelerating domestic certification of foreign relay suppliers. Battery-electric commercial fleets in Jiangsu province are procuring high-current switching components at scale.
- Cell-to-Pack Architectures:The elimination of module housings multiplies relay counts per battery system. Automotive OEMs specify distributed switching nodes that isolate individual cell groups.
- Solid-State Relay Maturation:Silicon carbide power semiconductors are penetrating charging station infrastructure where switching speed outweighs electromechanical cost advantages. Thermal management advances sustain 800-volt operation.
Market Restraints
- Silver-Nickel Contact Volatility:Precious metal price swings compress margin predictability for electromechanical relay producers. Contact material processing requires captive supply agreements or backward integration into refining.
- Jiangsu-Zhejiang Concentration:Domestic Chinese capacity expansion is creating regional oversupply that pressures export pricing. Foreign suppliers face localization requirements under dual carbon compliance frameworks.
- Solid-State Substitution Threshold:Electromechanical relays retain cost advantage below 200-ampere switching loads. Hybrid architectures delay full solid-state adoption in traction applications.
Strategic Opportunities
- India's PLI Scheme for Automotive:Component localization incentives under the Production Linked Incentive scheme attract relay manufacturing investment. Domestic EV assembly growth creates captive demand for high-voltage switching.
- Vehicle-to-Grid Integration:Bidirectional charging protocols require relays rated for continuous cycling at elevated currents. Residential energy storage coupling extends relay duty cycles beyond drivetrain applications.
- EU F-Gas and REACH Alignment:Contact material composition restrictions are reshaping supplier qualification. Early compliance with ECHA substance restrictions secures preferential positioning with European OEMs.
Industry Challenges
- 800-Volt Arc Quenching Expertise:The talent pool for high-voltage relay design remains concentrated among legacy automotive electrical suppliers. Electromagnetic simulation capabilities require specialized engineering hires.
- GB Standard Certification Timelines:China's MIIT testing protocols for NEV components extend qualification cycles. Foreign suppliers face documentation requirements that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Relay Market |
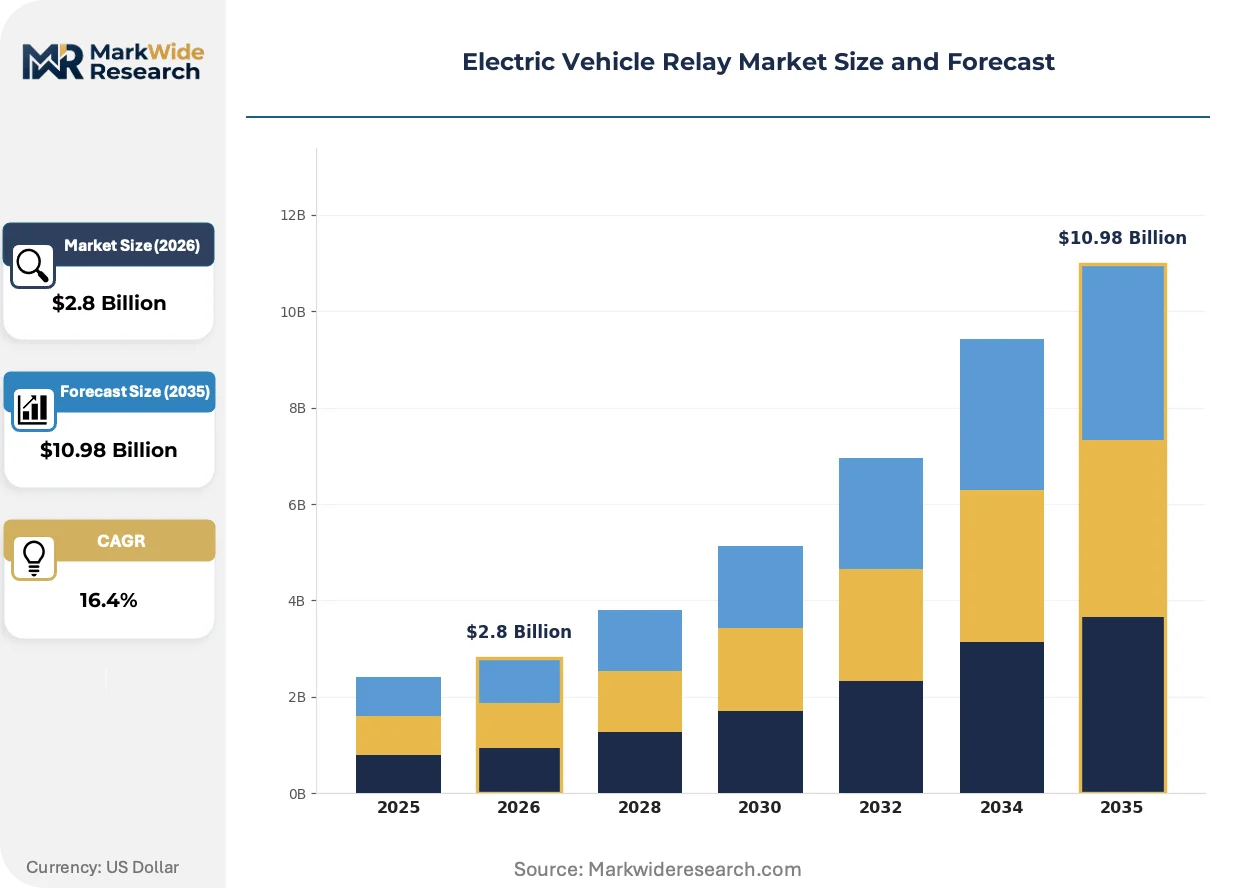
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Voltage Relay, Low-Voltage Relay, Solid-State Relay, Miniature Relay Technology: Electromechanical, Hybrid, Solid-State, Fiber Optic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Manufacturers Application: Power Management, Charging Stations, Battery Systems, Onboard Systems |
| Companies Covered | Fujitsu Limited, Robert Bosch GmbH, TE Connectivity Ltd., Mitsubishi Electric Corporation, HELLA GmbH & Co. KGaA, Panasonic Corporation, Omron Corporation, Eaton Corporation plc, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Relay Market Shifts & Advancements
Arc chute geometry optimization and ceramic housing materials are converging to extend relay cycle life under 800-volt stress. The competitive frontier has shifted from contact material purity to thermal simulation accuracy and predictive failure modeling.
Hybrid electromechanical-solid-state architectures are rewriting the trade-off between switching speed and cost in battery disconnect applications. Tier 1 suppliers are adopting these configurations for 800-volt platforms where fault isolation speed is non-negotiable. The technology is compressing the traditional electromechanical relay's dominance in traction systems above 400 volts.
REACH chemical restrictions and the EU F-Gas Regulation are forcing contact material substitutions across the supply base. Silver-tin oxide formulations are displacing cadmium-bearing alternatives in European-qualified components. Relay producers serving German OEMs are reformulating contact rivets to satisfy ECHA substance restrictions while maintaining arc erosion resistance.
Fleet procurement of battery-electric commercial vehicles is consolidating relay specifications around modular battery management integration. Logistics operators in California and the Netherlands are specifying unified switching platforms across mixed vehicle classes. This specification compression is squeezing component diversity and rewarding suppliers with broad automotive and commercial vehicle certifications.
Electric Vehicle Relay Market Segmentation
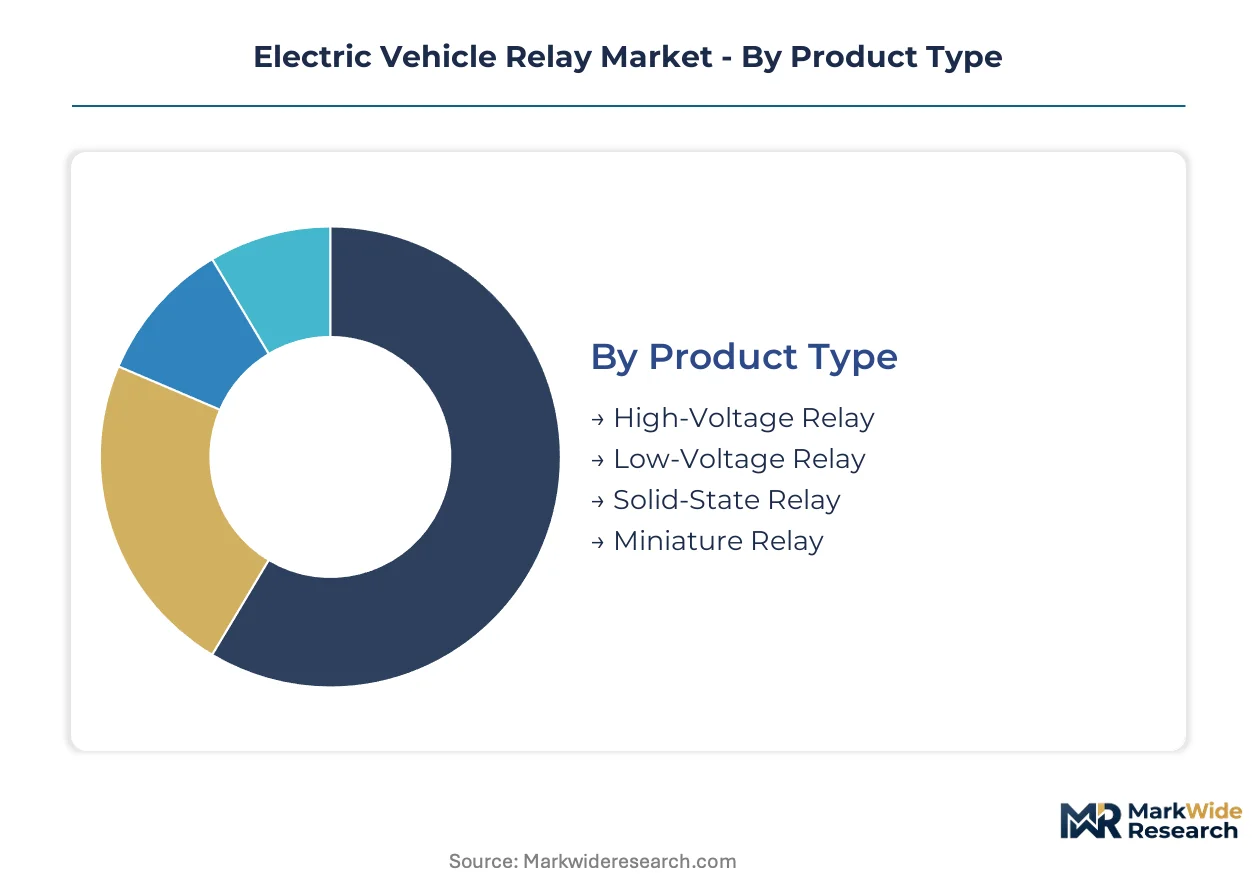
Segmentation in the Electric Vehicle Relay Market reveals how component specifications diverge across voltage tiers and integration depths. Product architecture choices determine whether relays function as standalone switching modules or embed within larger battery management systems.
Product Type:
Integration depth varies sharply across voltage classes, with high-voltage variants demanding standalone housing and low-voltage units embedding directly into circuit boards.
- High-Voltage Relay:Engineered for 400-volt to 1,000-volt traction systems using ceramic housings and silver-nickel contacts. Demand concentrates in Jiangsu province battery pack assembly where 800-volt platforms are scaling fastest under China's dual carbon compliance timelines.
- Solid-State Relay:Silicon carbide-based switching eliminates mechanical wear and enables microsecond fault isolation. Charging station infrastructure in the Netherlands and California is absorbing volumes where cycle life outweighs electromechanical cost advantages.
- Low-Voltage Relay:12-volt to 48-volt auxiliary switching for HVAC and lighting subsystems embeds into printed circuit assemblies.
- Miniature Relay:Compact form factors serve distributed cell monitoring nodes in cell-to-pack architectures.
Volume placements concentrate in High-Voltage Relay; the faster expansion belongs to Solid-State Relay.
Technology:
Cost stratification separates mature electromechanical production from premium hybrid and solid-state configurations requiring semiconductor fabrication partnerships.
- Electromechanical:Mature contact physics using silver-tin oxide rivets dominates traction applications below 200 amperes. Robert Bosch GmbH's captive contact material processing anchors cost structures in this segment.
- Hybrid:Combines electromechanical contacts with solid-state pre-charge circuits for 800-volt battery disconnect. European OEMs specify these architectures where fault isolation speed is non-negotiable.
- Solid-State:Full semiconductor switching without moving parts serves high-frequency cycling in bidirectional charging applications.
- Fiber Optic:Isolated signal transmission for high-EMI environments in motor control enclosures.
Electromechanical captures current volume leadership; hybrid configurations are climbing the fastest as 800-volt platforms multiply.
End User:
Customer type determines specification authority, with OEMs driving platform-level decisions and Tier-1 suppliers managing component qualification burden.
- OEMs:Platform architects specify relay performance envelopes across vehicle classes. Tesla and BYD internalize battery disconnect relay selection for vertical control over thermal management integration.
- Tier-1 Suppliers:Battery system integrators consolidate relay procurement under module supply contracts. Contemporary Amperex Technology and LG Energy Solution negotiate volume commitments that shape contact material specifications.
- Aftermarket Providers:Replacement demand for failed high-voltage disconnect units serves secondary vehicle markets.
- Vehicle Manufacturers:Commercial fleet operators specify unified switching platforms across mixed truck and bus classes.
Tier-1 Suppliers dominate current placements; OEM direct procurement is gaining share fastest as cell-to-pack architectures simplify supply tiers.
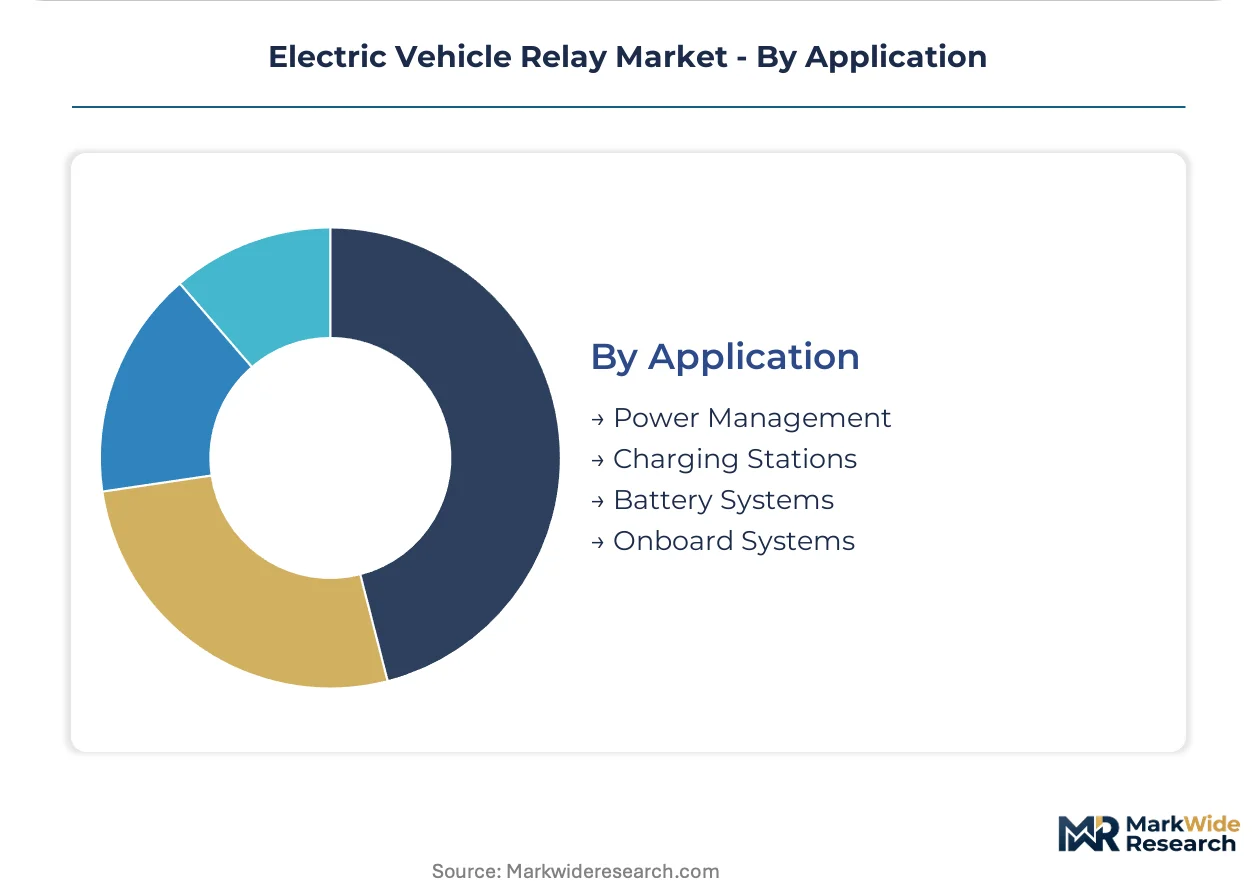
Application:
Functional role dictates thermal cycling severity, with battery system relays experiencing the deepest thermal stress and charging station units facing the highest switching frequency.
- Battery Systems:Disconnect and pre-charge functions isolate cell groups during fault conditions. Cell-to-pack architectures in Zhejiang manufacturing corridors multiply relay counts per vehicle as module housings disappear.
- Charging Stations:Continuous cycling at elevated currents for vehicle-to-grid protocols demands solid-state thermal performance. ChargePoint and ABB E-mobility specifications are compressing electromechanical share in this application.
- Power Management:Distribution of traction power to inverter and motor subsystems.
- Onboard Systems:Auxiliary power routing for thermal management and infotainment loads.
Power Management holds volume concentration; Battery Systems represent the steepest expansion trajectory as pack architectures evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Jiangsu and Zhejiang manufacturing corridors while consumption spreads across multiple EV deployment zones. The regional map reflects this supply-demand asymmetry.
China
Battery-electric commercial fleets in Jiangsu province are procuring high-current switching components at scale under MIIT-enforced GB standards for high-voltage isolation. The dual carbon goals tighten product certification requirements for foreign suppliers seeking NEV component qualification. Zhejiang manufacturing corridors host the fastest-scaling domestic relay capacity for cell-to-pack architectures.
Germany
European OEM supply chains anchor high-voltage relay distribution through automotive connector heritage networks. The EU F-Gas Regulation and ECHA REACH chemical restrictions are reshaping contact material compositions for silver-tin oxide formulations. Bavaria-based battery system integrators specify distributed switching nodes that isolate individual cell groups.
United States
EPA tailpipe regulations and NHTSA safety mandates compress development timelines for relay qualification in 800-volt platform deployments. California logistics operators specify unified switching platforms across mixed battery-electric truck and bus classes. The Pacific Northwest hosts charging station infrastructure absorbing solid-state relay volumes where cycle life outweighs electromechanical cost advantages.
Japan
METI industrial policy supports compact solid-state configurations that sustain thermal performance under elevated voltage architectures. Domestic OEMs internalize battery disconnect relay selection for vertical control over thermal management integration. Kanto-based semiconductor fabrication partnerships enable hybrid electromechanical-solid-state architectures for fault isolation speed.
India
The Production Linked Incentive scheme for automotive components attracts relay manufacturing investment toward localization requirements. Maharashtra and Gujarat domestic EV assembly growth creates captive demand for high-voltage switching across Tier-1 supplier consolidation. BIS standards alignment pressures contact material specification reformulation for market entry.
Electric Vehicle Relay Market Competitive Landscape
The competitive structure tilts toward diversified electrical component conglomerates with captive material processing capabilities. Tier-1 battery system integrators consolidate procurement under module supply contracts, compressing component diversity. Three archetypes dominate: automotive electrical heritage suppliers, semiconductor fabrication partners, and diversified industrial conglomerates. Capacity expansion in Jiangsu-Zhejiang corridors and strategic partnerships for 800-volt qualification are the dominant competitive moves.
Among diversified industrial conglomerates, Robert Bosch GmbH, TE Connectivity Ltd., and Panasonic Corporation exemplify the three strategic vectors. Bosch represents backward integration into contact material processing for electromechanical cost structures. TE Connectivity anchors high-voltage relay distribution across European OEM supply chains through automotive connector heritage. Panasonic occupies a position in compact solid-state configurations for thermal performance under 800-volt stress.
| Leading Market Players |
|---|
| Fujitsu Limited |
| Robert Bosch GmbH |
| TE Connectivity Ltd. |
| Mitsubishi Electric Corporation |
| HELLA GmbH & Co. KGaA |
| Panasonic Corporation |
| Omron Corporation |
| Eaton Corporation plc |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Silver-nickel contact material costs cascade through three distinct pricing tiers, from raw metal procurement in Chinese refining corridors to finished relay shipments bound for European OEM module integrators. Jiangsu province's captive smelting capacity anchors the cost floor, while GB standard certification premiums separate domestic-qualified from export-grade units.
Pricing Analysis
Margin tightening in standard-grade electromechanical relays reflects Jiangsu-Zhejiang oversupply and aggressive localization mandates under dual carbon frameworks. Three-tier pricing structure across premium, standard, and economy levels stratifies by GB certification status and arc quenching performance tier. Cost compression accelerates in high-volume battery system procurement as CATL and LG Energy Solution consolidate relay counts under unified module contracts. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, whereas 800-volt platform engineers prioritize fault isolation speed over unit cost.
Supply Chain Analysis
Specialized electromagnetic simulation talent pools in Germany and Japan constrain relay design capacity expansion despite Jiangsu's manufacturing scale. Ceramic housing fabrication draws from Chinese alumina processing clusters, silver-nickel contacts rest on South Korean precious metal refining, and silicon carbide substrates hinge on Taiwanese semiconductor foundries. Single-source vulnerability concentrates in 800-volt arc quenching expertise held by legacy automotive electrical suppliers. Distribution runs through Tier 1 battery system integrators who consolidate component procurement under cell-to-pack architecture contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle relay market is becoming a vertical-integration race where control over contact material processing and 800-volt qualification timelines determines margin capture. Players are pursuing backward integration into silver-nickel refining and captive ceramic housing production as the decisive upstream lever.
For Market Incumbents: Anticipate solid-state substitution thresholds by locking in long-term silver supply agreements before precious metal volatility intensifies. Prioritize GB standard pre-certification in Jiangsu testing facilities to preempt foreign competitor entry under tightening MIIT timelines. Defensive consolidation should target hybrid architecture R&D partnerships with silicon carbide semiconductor fabricators.
For New Entrants and Emerging Players: Solid-state thermal management IP offers the most penetrable wedge for charging station infrastructure specifications in California and the Netherlands. Bidirectional vehicle-to-grid relay applications remain underpenetrated by established electromechanical suppliers. A technology-first go-to-market angle should lead with microsecond fault isolation benchmarks rather than cost parity claims.
For Investors and Strategic Acquirers: First announcements of 1000-volt platform architectures by major OEMs is the leading indicator that hybrid relay configurations will capture premium positioning. Long-term viability centers on suppliers with simultaneous electromechanical heritage and semiconductor fabrication partnerships. The acquisition target archetype is mid-cap relay specialists with captive contact material processing and existing GB standard qualification. Watch for MIIT documentation requirement simplifications as the inflection signal for foreign supplier market entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Pre-Certification | MIIT qualification timelines compress competitive windows for foreign suppliers seeking Jiangsu market entry. |
| Silver-Nickel Backward Integration | Captive refining capacity insulates margin structures from London Metal Exchange price volatility. |
| Hybrid Architecture R&D Partnership | Silicon carbide semiconductor collaborations enable 800-volt fault isolation speed specifications. |
| Cell-to-Pack Module Integration | Distributed switching node designs multiply relay counts per vehicle as module housings disappear. |
| Charging Infrastructure Specification Capture | Solid-state thermal performance benchmarks secure preferential positioning with ChargePoint and ABB E-mobility. |
Research Methodology
Document review covered SEC automotive supplier filings, MIIT GB standard documentation, and IHS Markit vehicle production databases, complemented by interviews with Tier 1 battery system procurement directors, OEM platform engineers, and aftermarket distributors. Primary fieldwork engaged relay design specialists at European automotive electrical heritage suppliers and ceramic housing manufacturers in Zhejiang corridors. Secondary validation drew from ECHA REACH substance restriction updates, EU F-Gas Regulation implementation guidance, and customs trade data for silver-nickel contact material flows. Bottom-up unit demand modeling triangulated against top-down EV production forecasts across the analysis window.
Cross-referencing historical relay adoption patterns against panel input from semiconductor fabrication partners and thermal management specialists shaped the analytical framework. Segmentation dimensions modeled include voltage class, integration depth, propulsion architecture, and regional regulatory cluster. CAGRs derived from curve-fitting historical price-volume relationships and projecting content-per-vehicle trajectories as cell-to-pack architectures mature. Industry-specific forecast inputs incorporated 800-volt platform rollout schedules and solid-state thermal performance advancement curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt precious metal price spikes or sudden MIIT certification requirement modifications. Forecasts reflect assumptions about dual carbon policy continuity, REACH chemical restriction phase-in timelines, and silicon carbide substrate supply expansion. Material deviation in GB standard enforcement intensity or solid-state cost crossover points warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Used EV Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
France E-Bike Market