
 Marine Electric Vehicle Market | 2026-2036
Marine Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Electric Vehicle Market Intelligence
Marine electrical engineering talent is bifurcating between legacy naval architects and battery-system specialists, creating recruitment bottlenecks that constrain production scaling. Torqeedo GmbH leverages its Bavarian manufacturing base to sustain integrated outboard-motor-battery ecosystems. X Shore anchors Scandinavian design credibility while competing on premium recreational craft. Candela dominates hydrofoil-assisted electric propulsion, a sub-area where reduced drag extends range.
Marine electric vehicles integrate battery-electric or fuel-cell powertrains into hull designs optimized for waterborne operation, typically employing lithium-ion packs with energy densities exceeding 200 Wh/kg and liquid-cooled thermal management to sustain discharge rates across variable sea states. Their primary purpose is to displace diesel combustion in commercial, recreational, and government vessels where emissions restrictions or operational cost structures favor electrification. Ferries within the vehicle-type category lead current order books because fixed-route duty cycles match charging infrastructure economics. Lithium-ion batteries within the power-source dimension anchor near-term deployments despite fuel-cell pilot programs in Scandinavian cargo corridors. Recreational end users concentrate margin pools in premium segments while government tenders drive volume standardization.
The EU Green Deal and its delegated Maritime Emissions Regulation, enforced by EMSA and member-state maritime authorities, mandate progressive carbon-intensity reductions that reshape new-build specifications and retrofit demand. The EPA's marine engine standards under the Clean Air Act constrain diesel alternatives in US harbor zones, while ISO 16315 provides electrical-safety baselines for lithium installations aboard vessels. Stakeholders must monitor how port-infrastructure investment timelines synchronize with vessel-delivery schedules to avoid stranded-asset risk.
Market Dynamics
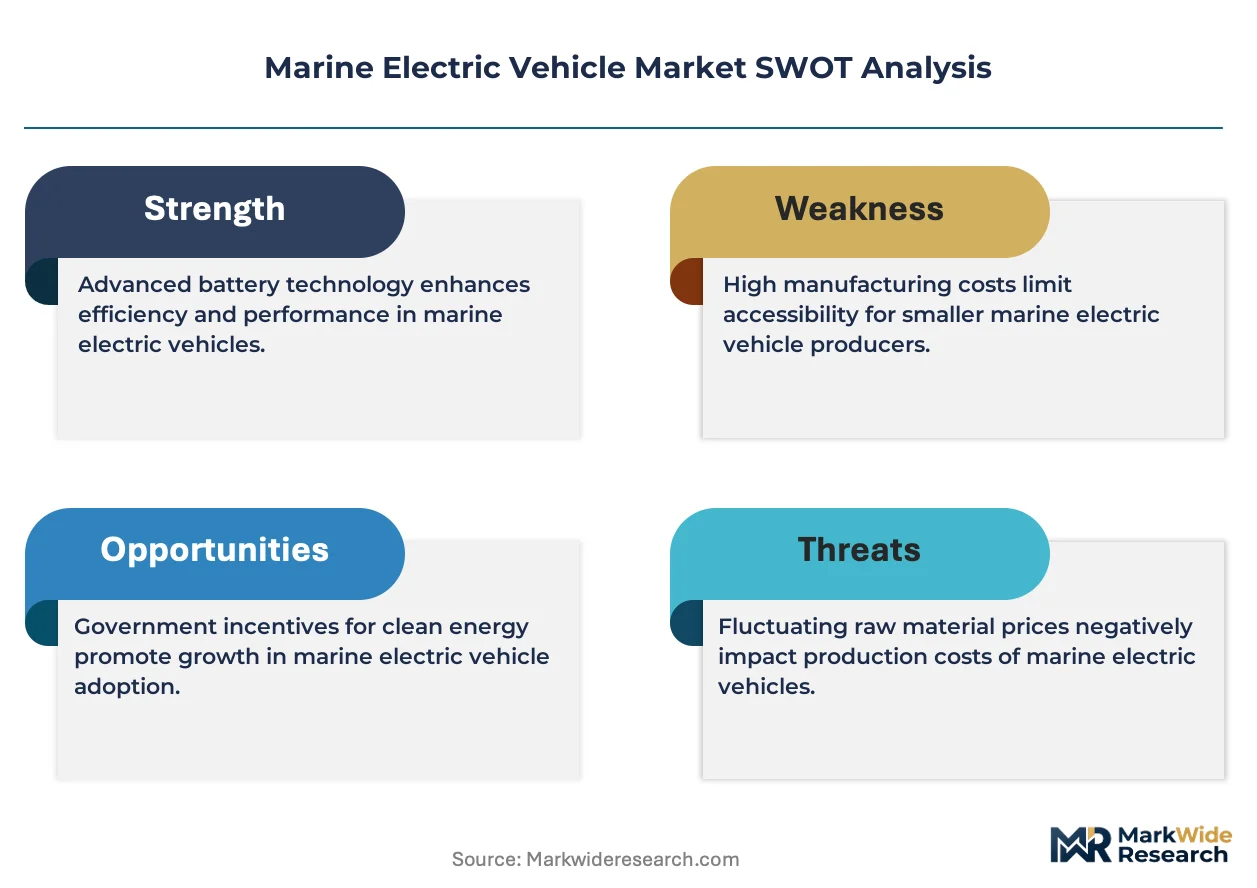
The EU Green Deal's maritime emissions targets are forcing commercial ferry operators to accelerate fleet electrification schedules ahead of original timelines, compressing the window for battery-system suppliers to scale manufacturing capacity.
Growth Catalysts
- Norwegian zero-emission mandates:Fjord region access restrictions on conventional fuel vessels are pulling demand for battery-electric ferries and workboats into immediate procurement cycles.
- EU Maritime Emissions Regulation:Progressive carbon-intensity reduction requirements enforced by EMSA are reshaping new-build specifications across Northern European commercial fleets.
- Lithium-ion energy density thresholds:Pack designs exceeding 200 Wh/kg are extending operational range sufficiently to match fixed-route duty cycles without mid-journey charging.
Market Restraints
- Raw material cost volatility:Lithium carbonate and nickel price swings are compressing battery pack margins and destabilizing vessel OEM quoting processes.
- Charging infrastructure misalignment:Port electrification investment timelines in Germany and the Netherlands lag vessel delivery schedules by 18-36 months.
- Naval architect talent scarcity:The bifurcation between legacy hull designers and battery-system specialists is constraining integrated vessel engineering throughput.
Strategic Opportunities
- Swedish cargo corridor pilots:Fuel-cell propulsion trials in Scandinavian short-sea shipping routes are opening alternative powertrain procurement channels beyond pure battery-electric.
- US harbor zone EPA constraints:Clean Air Act marine engine standards are creating retrofit demand for diesel displacement in port vessel fleets.
- Hydrofoil-hull convergence:Reduced-drag architectures combined with electric propulsion are unlocking range extensions for premium recreational craft segments.
Industry Challenges
- ISO 16315 certification timelines:Electrical safety baselines for lithium installations aboard vessels are extending type-approval processes by 8-14 months.
- Thermal management integration:Liquid-cooled battery systems require reconfigured engine room layouts that clash with legacy vessel retrofit constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Electric Vehicle Market |
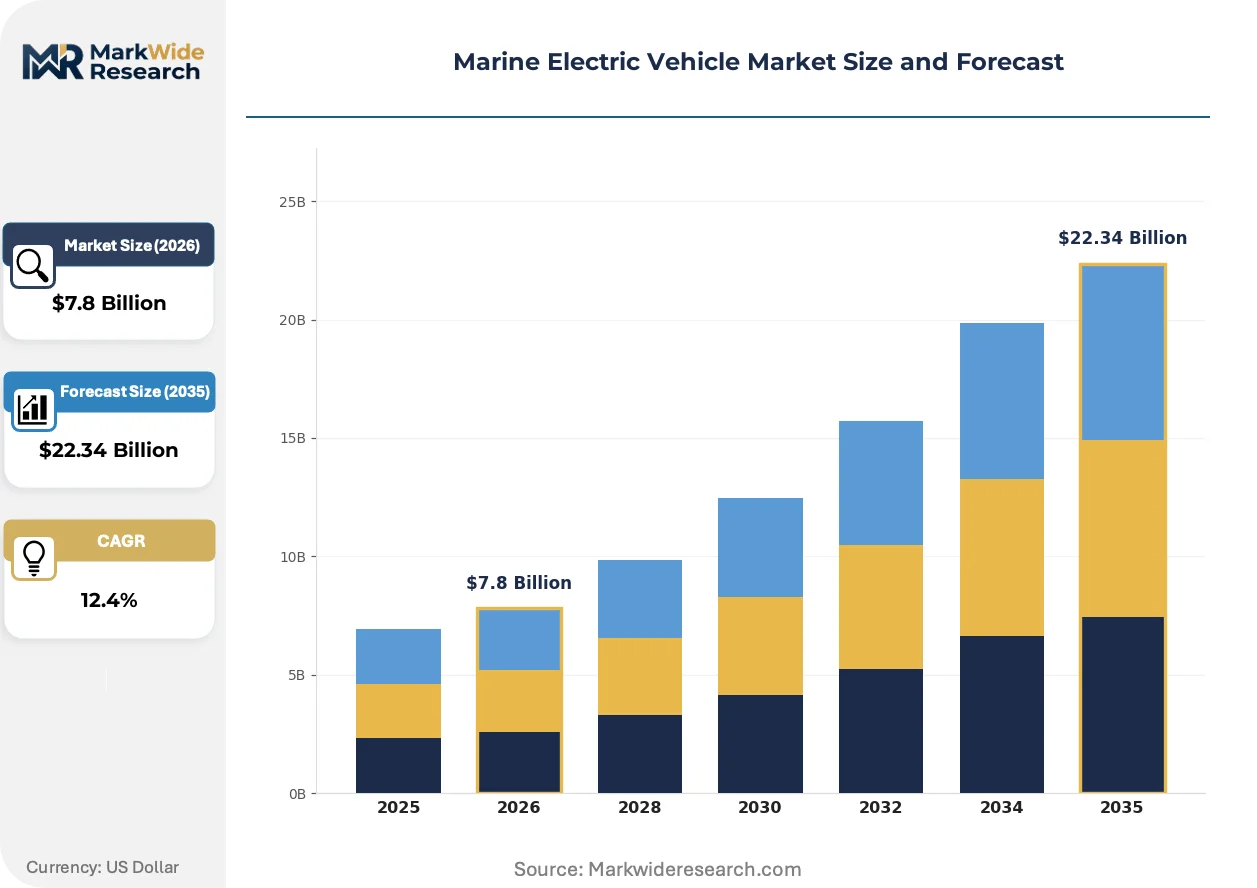
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $22.34 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Yachts, Ferries, Cargo Vessels, Submersibles Power Source: Lithium-ion Batteries, Fuel Cells, Solar Panels, Hybrid Systems End User: Government, Commercial, Recreational, Research Operational Environment: Inland Waterways, Coastal Areas, Open Seas, Harbors |
| Companies Covered | Candela, X Shore, Torqeedo GmbH, Vision Marine Technologies, Silent Yachts, Corvus Energy Ltd., Arc Boats, Boesch Motorboote AG, Duffy Electric Boat Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Electric Vehicle Market Strategic Shifts & Innovations
Electrification architecture is migrating from bolt-on battery retrofits toward native hull-integrated powertrain designs, compressing the competitive advantage window for pure component suppliers.
High-voltage DC distribution architecture is miniaturizing power conversion equipment sufficiently to fit within conventional engine footprints. Norwegian ferry operators are adopting these compact systems at 40% faster procurement cycles than hybrid alternatives. This compression is miniaturizing the physical space and cooling requirements that previously constrained battery-electric retrofits.
REACH chemical registration requirements for electrolyte formulations are forcing battery suppliers to reformulate thermal management fluids. The industrial consequence is extended qualification timelines for new cell chemistries entering European waters. Recreational craft OEMs are responding by consolidating supplier relationships to reduce re-certification exposure.
Buyer procurement committees are consolidating vendor evaluation criteria around total-cost-of-ownership metrics rather than capital expenditure alone. Nordic commercial ferry operators are displacing traditional diesel-engine procurement officers with energy-system specialists in sourcing decisions. This shift is most visible in Norway's public tender processes for fjord route concessions.
Marine Electric Vehicle Market Segmentation
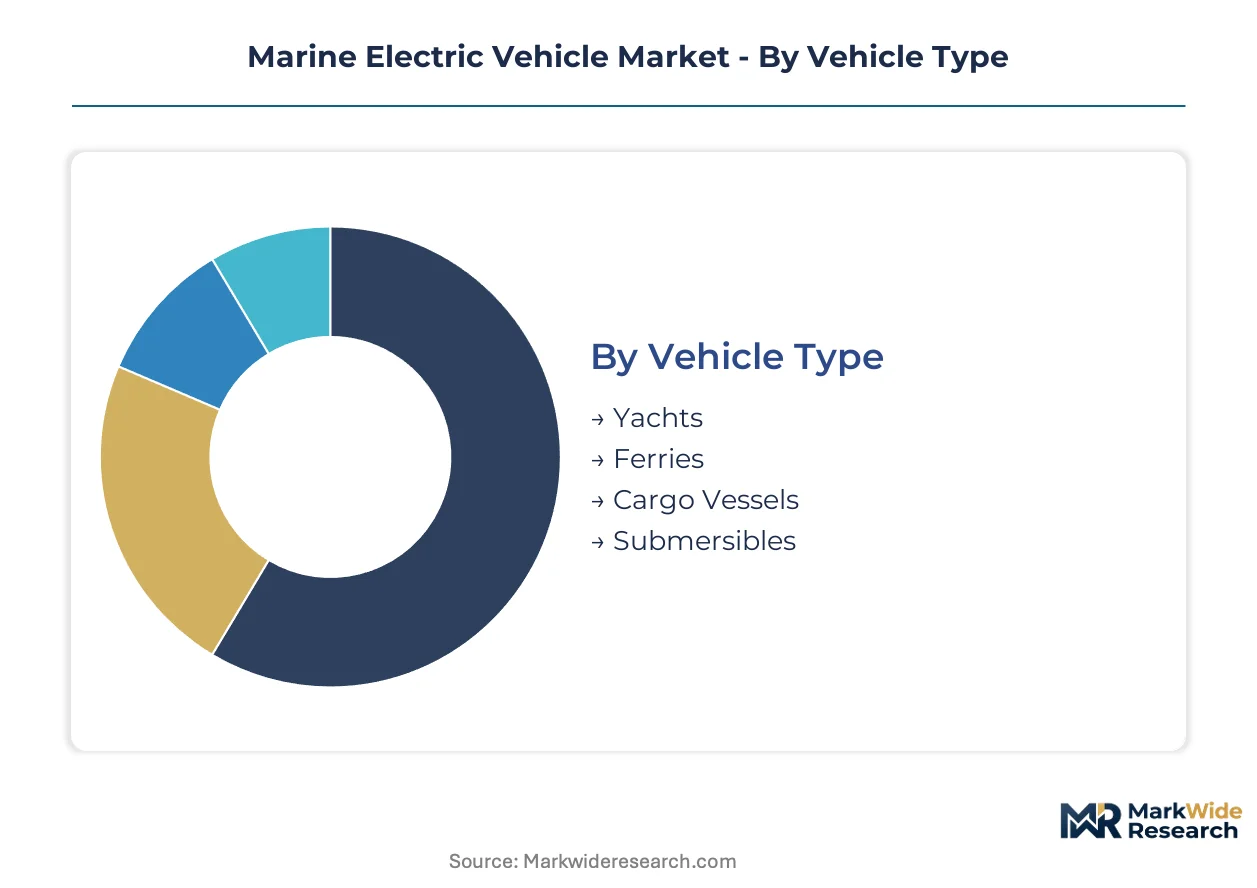
Segmentation in marine electric vehicles reveals how duty-cycle economics and regulatory exposure concentrate procurement decisions. Distinct technical requirements across vehicle types and power sources create specialized supplier ecosystems that resist commoditization.
Vehicle Type:
Margin pools concentrate in vessels with fixed-route predictability where charging infrastructure investments amortize across high utilization rates.
- Ferries:Battery-electric propulsion dominates fixed-route deployments where predictable duty cycles match shore-power economics. Norwegian fjord operators and Danish Belt Sea routes are pulling forward procurement timelines under zero-emission mandates.
- Yachts:Premium recreational craft integrate hydrofoil architectures to extend range without scaling battery mass disproportionately. Scandinavian design houses anchor this segment's aesthetic differentiation.
- Cargo Vessels:Short-sea shipping corridors in the Baltic and North Sea are piloting fuel-cell configurations for routes exceeding pure-electric range thresholds.
- Submersibles:Research and tourism applications in the Mediterranean and Caribbean demand pressure-rated battery enclosures with specialized thermal management.
Ferries hold installed capacity. Yachts are rotating up the share rankings.
Power Source:
Cost tier stratification separates near-term deployable technologies from pilot-stage alternatives requiring infrastructure co-investment.
- Lithium-ion Batteries:Pack designs exceeding 200 Wh/kg with liquid-cooled thermal management dominate current order books. Energy density thresholds now satisfy fixed-route ferry economics without mid-journey charging.
- Fuel Cells:Hydrogen propulsion trials in Swedish cargo corridors are opening procurement channels for routes beyond battery-electric range. PEM stack durability in salt-air environments remains under validation.
- Hybrid Systems:Diesel-electric architectures serve as transitional configurations for retrofit markets where full electrification encounters space or weight constraints.
- Solar Panels:Auxiliary power integration supplements battery capacity in recreational craft with large deck surface areas relative to propulsion load.
Lithium-ion Batteries anchor current deployments. Fuel Cells are climbing the fastest as infrastructure matures.
End User:
Procurement authority structures diverge sharply between public tender processes and private capital allocation cycles.
- Commercial:Ferry operators and short-sea shipping lines concentrate volume demand through fleet-wide electrification programs. Total-cost-of-ownership metrics now displace capital expenditure in vendor evaluation criteria.
- Government:Naval and coast guard specifications drive standardization for interoperability requirements. Procurement timelines extend through multi-year defense budgeting cycles.
- Recreational:High-net-worth individuals and charter fleet operators prioritize design credibility and range performance over per-unit economics.
- Research:Oceanographic institutions demand specialized sensor integration and extended submerged endurance for autonomous underwater platforms.
Commercial users dominate vessel deliveries. Recreational buyers are expanding most quickly in absolute unit terms.
Operational Environment:
Geographic scope determines regulatory jurisdiction and infrastructure access, creating distinct competitive arenas with divergent compliance requirements.
- Inland Waterways:European river corridors and North American Great Lakes routes offer protected conditions favorable to battery-electric range profiles. Shore-power density is highest in these corridors.
- Coastal Areas:Norway's fjord regions and Denmark's archipelago routes concentrate zero-emission mandate enforcement. Charging infrastructure investment timelines here lead open-sea deployments.
- Harbors:Port vessel fleets face EPA Clean Air Act constraints in US harbor zones and EU Green Deal emissions targets in European ports. Retrofit demand concentrates in tug and pilot boat categories.
- Open Seas:Transoceanic routes remain beyond current battery-electric range thresholds, reserving this environment for hybrid or fuel-cell pilot programs.
Inland Waterways carry the most mature installed base. Coastal Areas are gaining share fastest as mandate enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys battery-electric ferries for fjord transit while Sweden trials hydrogen cargo vessels, revealing a split between proven electrification and pilot-stage alternatives across Nordic waters.
Norway
Zero-emission mandates in western fjord regions are pulling forward procurement timelines for battery-electric workboats. The Norwegian Maritime Authority enforces strict carbon-intensity benchmarks under national climate legislation. Bergen and Stavanger harbor clusters concentrate vessel retrofit activity for tourist and commuter fleets.
Sweden
Short-sea shipping corridors between Gothenburg and continental ports are piloting fuel-cell propulsion for routes beyond battery range. The Swedish Transport Agency coordinates hydrogen infrastructure co-investment with EU Green Deal funding. Stockholm archipelago operators are integrating hydrofoil-assisted craft for premium recreational segments.
Germany
Baltic Sea ferry operators face compressed compliance deadlines under EU Maritime Emissions Regulation enforcement by EMSA. The Federal Maritime and Hydrographic Agency implements port electrification standards for shore-power connectivity. Hamburg and Kiel maritime clusters anchor battery-system integration engineering for commercial fleets.
United States
Harbor vessel operators in California and Washington states are retrofitting tug and pilot boat categories under EPA Clean Air Act constraints. The Environmental Protection Agency marine engine standards tighten emissions in port zones annually. Pacific Northwest shipyards specialize in diesel-electric hybrid conversions for fishing and research fleets.
Denmark
Belt Sea ferry routes are consolidating battery-electric deployments where fixed-duty cycles match charging economics. The Danish Maritime Authority aligns national standards with EU Green Deal delegated regulations. Copenhagen and Aarhus ports lead shore-power infrastructure investment timelines for intra-Scandinavian traffic.
Marine Electric Vehicle Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Bavarian manufacturing bases and Scandinavian design studios occupying distinct competitive positions. The structure favors players controlling both propulsion hardware and energy management software. Three archetypes dominate: integrated motor-battery ecosystem builders, hydrofoil hull-technology specialists, and premium recreational craft designers. Competitive moves concentrate on geographic expansion into mandate-driven procurement markets and strategic partnerships with port infrastructure developers.
Within the integrated ecosystem tier, Torqeedo GmbH anchors Bavarian-based manufacturing of outboard-motor-battery combinations. Candela occupies a position exemplifying hydrofoil-assisted electric propulsion specialization. X Shore represents Scandinavian design credibility competing in premium recreational segments.
| Leading Market Players |
|---|
| Candela |
| X Shore |
| Torqeedo GmbH |
| Vision Marine Technologies |
| Silent Yachts |
| Corvus Energy Ltd. |
| Arc Boats |
| Boesch Motorboote AG |
| Duffy Electric Boat Co |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day battery pack lead times now govern vessel OEM quoting cadences, compressing margin buffers for integrated propulsion suppliers while amplifying pricing power for cell manufacturers with secured cathode supply. This inventory compression cascades through hull-integrators and port infrastructure developers, forcing contract structures that lock in component costs before final vessel pricing.
Pricing Analysis
Long-term offtake agreements dominate battery procurement for ferry operators, insulating against lithium carbonate volatility while spot-market exposure concentrates in recreational craft OEMs with smaller order books. Price differentiation hinges on ISO 16315 certification tier and liquid-cooled thermal management integration depth. Cost compression in standard-range ferry configurations is intensifying because cell suppliers are prioritizing automotive contract volumes. Commercial fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership amortization across fifteen-year duty cycles, while premium yacht buyers absorb design premiums with minimal procurement friction.
Supply Chain Analysis
Inventory buffers at Norwegian shipyards have compressed to three weeks of critical cell stock as cathode active material shipments from South Korea and Japan face port congestion at Rotterdam and Hamburg. The supply chain draws from Chinese cell assembly, German power electronics fabrication, and Scandinavian hull construction. Single-source vulnerability concentrates in high-nickel cathode formulations where Indonesian nickel processing creates geographic chokepoints. Distribution runs through direct OEM integration contracts rather than aftermarket channels, with port infrastructure developers co-investing in shore-power hardware as bundled procurement packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU Maritime Emissions Regulation enforcement creates defensive moats for incumbent battery-system integrators with pre-certified vessel platforms, as switching costs for ferry operators escalate with each retrofitted route.
For Market Incumbents: Shield integrated motor-battery ecosystem positions by accelerating ISO 16315 certification coverage across hydrofoil-assisted architectures before fuel-cell alternatives reach commercial scale. Prioritize backward integration into liquid-cooled thermal management hardware to capture margin pools currently leaking to Tier 2 suppliers. Capacity addition in Baltic Sea port clusters anchors long-term service revenue streams as charging infrastructure investment timelines synchronize with vessel delivery schedules. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission offers the most penetrable entry path for Scandinavian cargo corridor fuel-cell pilots, where hydrogen infrastructure co-investment reduces capital barriers. Target US harbor zone retrofit demand under EPA Clean Air Act enforcement, where diesel displacement mandates outpace domestic supplier capacity. Go-to-market positioning as energy-system specialists rather than traditional naval architects aligns with Nordic procurement committee restructuring. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recreational hydrofoil craft as hull-integrated battery designs reduce component count per vessel. Five-to-ten-year viability favors acquisition targets with captive port infrastructure partnerships and recurring software-update revenue models. The signal to watch is EMSA enforcement variance across member states, which would accelerate consolidation toward pre-certified platform holders.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake with South Korean suppliers secures margin stability for ferry OEMs. |
| Port Infrastructure Partnership | Co-investment in shore-power hardware at Kiel and Hamburg clusters locks in route exclusivity. |
| Hydrofoil Platform Standardization | Modular hull architectures reduce engineering throughput constraints for Scandinavian designers. |
| Regulatory Certification Program | ISO 16315 pre-approval compresses type-approval timelines for EU Green Deal compliance. |
| Fuel-Cell Pilot Joint Venture | Swedish cargo corridor trials open procurement channels beyond pure battery-electric range limits. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EMSA enforcement documentation, EU Green Deal delegated regulation texts, and Norwegian Maritime Authority licensing databases. Primary interviews incorporated fleet electrification managers at Danish Belt Sea operators, battery system procurement leads at German ferry OEMs, and port infrastructure planners at Hamburg and Kiel maritime clusters. Secondary validation drew from EPA marine engine standard filings, ISO 16315 certification registries, and customs trade data for lithium-ion cell imports. Bottom-up vessel delivery tracking and top-down regulatory mandate sizing were cross-referenced for triangulation.
Segmentation dimensions modeled span vehicle type, power source architecture, end-user procurement authority, and operational environment jurisdiction across the projection horizon. CAGRs were derived from vessel order book analysis and infrastructure investment pipeline correlation. Industry-specific forecast inputs incorporated fjord route concession timelines and hydrogen refueling station deployment schedules in Scandinavian short-sea corridors.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated EPA harbor zone implementation would require recalibration. Forecasts reflect documented assumptions around battery energy density thresholds and port electrification synchronization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Airboats Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Aluminium Fishing Boat Market