
 Denmark Solar E-Bike Market | 2026-2036
Denmark Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Solar E-Bike Market Insights
Modular battery-solar panel bundling is consolidating as the dominant configuration pattern across Danish retail channels. CUBE Bikes leverages integrated frame-embedded photovoltaic cells to differentiate its premium positioning. Royal Dutch Gazelle anchors the commuter segment through established dealer networks in Jutland and Funen. Nørdic Bikes specializes in lightweight Scandinavian-designed frames that appeal to design-conscious urban riders.
A solar e-bike integrates photovoltaic cells into frame surfaces or detachable panels to supplement lithium-ion battery packs, typically achieving 15-30% charge extension under optimal Nordic summer irradiance conditions. The primary commercial purpose is reducing grid dependency for last-mile commuters and delivery operators in high-latitude cycling economies. City E-Bikes dominate volume as Copenhagen's employer-subsidized cycle schemes mature, while Cargo E-Bikes capture expanding margin pools from last-mile logistics operators replacing diesel vans. Lithium-phosphate chemistry is displacing conventional lithium-ion in fleet deployments where thermal stability outweighs energy density priorities.
Denmark's Road Traffic Act enforcement through the Danish Road Directorate shapes motor-assisted speed limits and lighting mandates, while EU CE marking requirements govern electrical safety compliance for cross-border component sourcing. The Danish Energy Agency's building-integrated solar incentives indirectly reduce panel costs for e-bike manufacturers sourcing domestically. Stakeholders must monitor whether proposed EU battery passport regulations will impose traceability burdens on small-scale Danish assemblers sourcing cells from non-EU suppliers.
Market Dynamics
Denmark's solar e-bike market is restructuring around employer-subsidized cycle-to-work schemes that now cover photovoltaic-equipped models, compressing adoption timelines for urban commuters and last-mile logistics operators across Zealand's metropolitan corridor.
Growth Catalysts
- Employer-subsidized cycle schemes:Copenhagen's municipal employers now extend pre-tax salary sacrifice benefits to solar-augmented e-bikes, accelerating workforce adoption among knowledge-sector commuters.
- Danish Road Directorate enforcement:Clarified motor-assisted speed limits under the Road Traffic Act reduce legal uncertainty for fleet operators deploying solar e-bikes in commercial delivery.
- Perovskite cell integration:Laboratory partnerships between Danish technical universities and frame manufacturers are improving photovoltaic efficiency under Nordic diffuse-light conditions.
Market Restraints
- Lithium cell supply concentration:Danish assemblers depend on non-EU suppliers for lithium-phosphate battery cells, exposing margins to raw material volatility and currency fluctuation.
- High-latitude irradiance limitation:Copenhagen's winter solar yield drops below practical charging thresholds for four months, constraining year-round grid-independence claims.
- EU battery passport traceability:Proposed regulations will impose documentation burdens on small-scale Danish manufacturers sourcing cells from Asian suppliers without established chain-of-custody systems.
Strategic Opportunities
- Danish Energy Agency building-integrated solar incentives:Domestic panel manufacturers can redirect production capacity toward e-bike applications, reducing import dependency for photovoltaic components.
- Roskilde-Frederiksberg logistics corridor:Uncaptured demand exists among regional parcel distributors seeking diesel van replacement for sub-10-kilometer delivery routes.
- Modular battery-solar bundling:Retail channel innovation enabling consumer upgrade paths from standard e-bikes to photovoltaic-augmented configurations extends addressable market without full replacement cycles.
Industry Challenges
- Photovoltaic integration engineering talent:Shortage of specialists combining lightweight frame design with embedded electronics manufacturing constrains product development velocity for domestic assemblers.
- CE marking compliance timelines:Cross-border electrical safety certification for novel frame-embedded cell configurations delays commercialization by six to twelve months for innovative designs.
- Dealer network technical training:Established Jutland and Funen retail channels lack servicing capability for integrated solar systems, creating after-sales service gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Solar E-Bike Market |
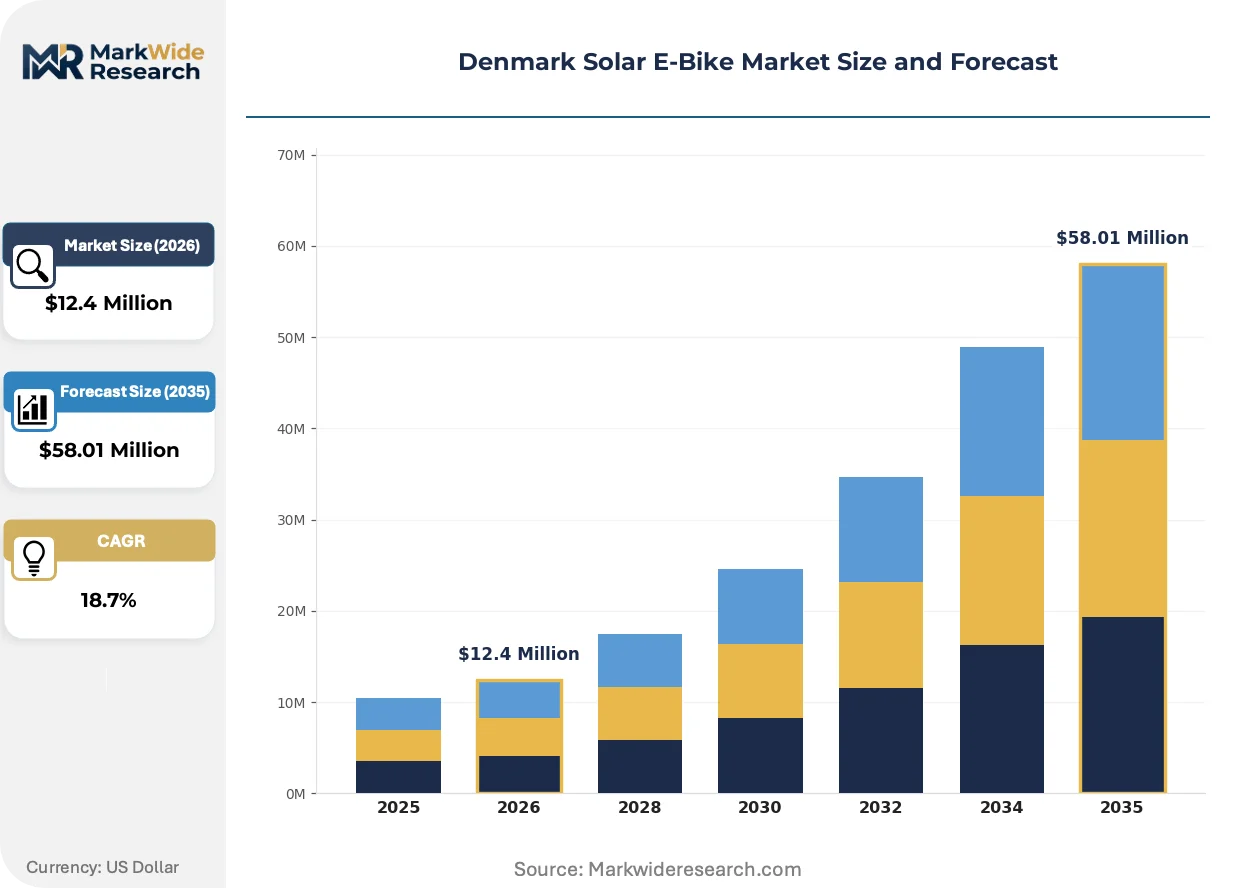
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $58.01 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Cargo E-Bikes, Folding E-Bikes Battery Type: Lithium-ion, Lead-acid, Lithium-phosphate, Lithium-polymer Power Rating: 250W, 500W, 750W, 1000W Charging Method: Solar Charging, Grid Charging, Hybrid Charging, Wireless Charging |
| Companies Covered | Giant Manufacturing Co. Ltd, CUBE Bikes, Royal Dutch Gazelle, Principia Bikes, Van Moof, Winther A/S, Batavus Intercycle Corporation, Nørdic Bikes, Accell Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Solar E-Bike Market Trends and Innovations
Photovoltaic integration is evolving from accessory attachment to structural frame embedding, while regulatory clarity and procurement model shifts are compressing commercial adoption cycles for Danish fleet operators.
Perovskite-enhanced photovoltaic cells are absorbing incremental efficiency gains under Denmark's diffuse Nordic light conditions. Fleet procurement managers at Copenhagen-area logistics operators are specifying these cells in new tenders issued since 2024. The technology is absorbing margin pressure from battery cost volatility by reducing rated battery capacity requirements for equivalent range specifications.
EU battery passport regulations are mandating cell-level traceability documentation for energy storage systems above 2 kWh capacity. Danish assemblers sourcing lithium-phosphate cells from non-EU suppliers must restructure procurement contracts to include supply chain disclosure. The regulation most affects small-scale Zealand-based manufacturers without captive cell production or established supplier audit protocols.
Outcome-based fleet service contracts are replacing outright equipment purchases among regional parcel distributors. Copenhagen-based logistics operators now contract for guaranteed daily kilometer coverage rather than asset ownership, shifting capital burden to leasing providers. This procurement evolution is most visible in the Roskilde-Frederiksberg corridor where diesel van replacement programs are accelerating.
Denmark Solar E-Bike Market Segmentation
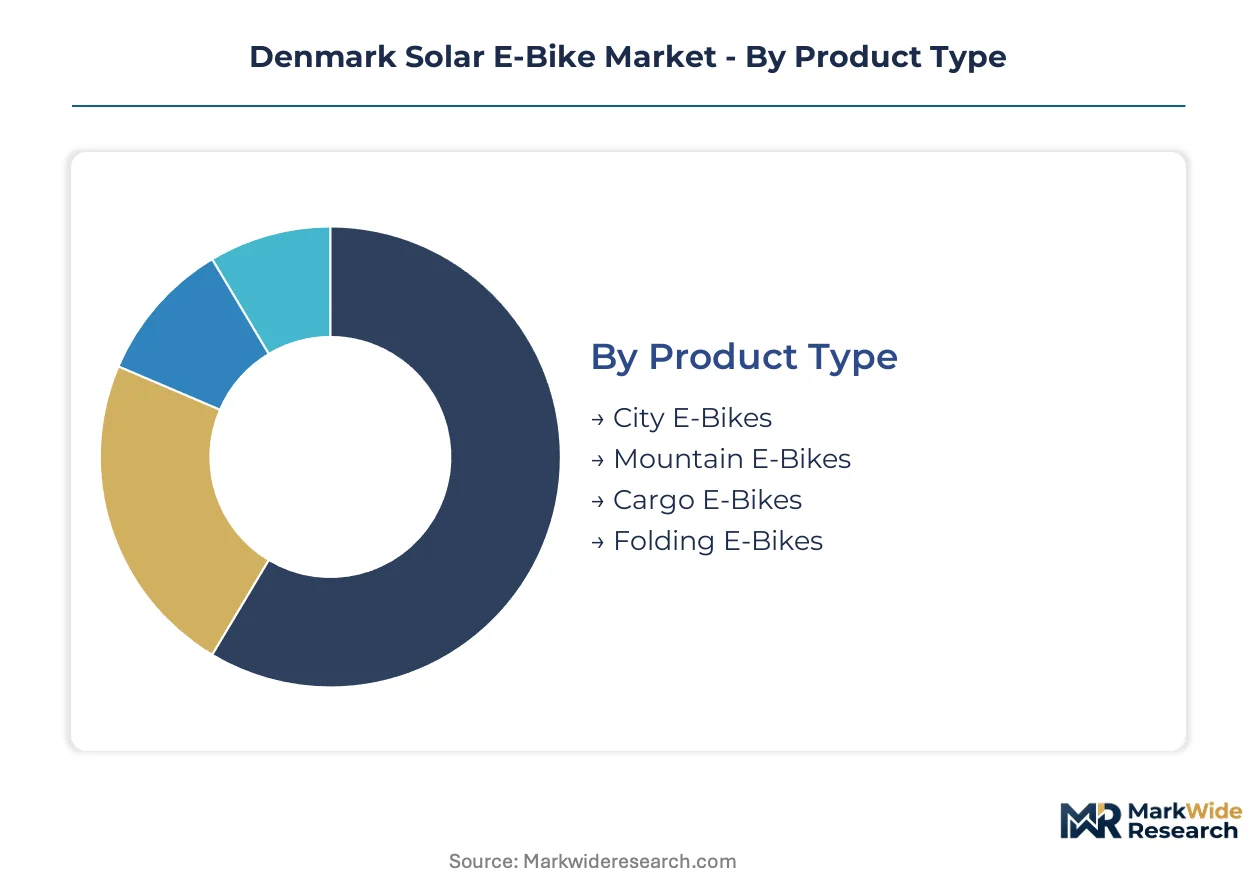
Photovoltaic integration creates divergent technical requirements across rider profiles and operational contexts. Segment boundaries in Denmark reflect the tension between urban commuting optimization and commercial fleet durability demands.
Product Type:
Frame geometry and load-bearing specifications determine photovoltaic cell placement feasibility and solar yield per kilometer.
- City E-Bikes:Step-through frames accommodate roof-mounted or handlebar-integrated panels for Copenhagen's knowledge-sector commuters. Employer-subsidized cycle schemes concentrate procurement through municipal procurement frameworks.
- Cargo E-Bikes:Extended wheelbases support larger surface-area panel arrays on flatbed configurations. Last-mile logistics operators in the Roskilde-Frederiksberg corridor specify these for diesel van replacement programs.
- Mountain E-Bikes:Suspension travel and frame flexing limit embedded cell durability; most configurations use detachable auxiliary panels.
- Folding E-Bikes:Compact hinge mechanisms constrain panel surface area; solar augmentation remains accessory-based rather than integrated.
Mature deployment sits with City E-Bikes. Newer deployment is concentrated in Cargo E-Bikes.
Battery Type:
Chemistry selection trades energy density against thermal stability and cycle longevity under Nordic temperature swings.
- Lithium-phosphate:Superior thermal stability suits fleet operators running continuous discharge cycles through Copenhagen's variable seasons. The chemistry absorbs margin pressure from cell supply volatility through extended cycle life.
- Lithium-ion:Higher energy density serves weight-conscious urban commuters prioritizing range over cycle count. Individual purchasers in Zealand's metropolitan corridor dominate this segment.
- Lithium-polymer:Flexible form factors enable curved frame integration for design-forward Scandinavian manufacturers.
- Lead-acid:Cost floor positioning for price-sensitive entrants; minimal photovoltaic pairing due to weight penalties.
Mature deployment sits with Lithium-ion. Newer deployment is concentrated in Lithium-phosphate.
Power Rating:
Motor output thresholds align with Danish Road Directorate speed limit enforcement and employer liability frameworks.
- 250W:The legal ceiling for motor-assisted operation without registration under the Road Traffic Act. Copenhagen municipal employers specify this rating exclusively for subsidy-eligible schemes.
- 500W:Commercial delivery operators in the Roskilde-Frederiksberg logistics corridor seek this threshold for loaded cargo acceleration.
- 750W:Agricultural and industrial applications outside urban speed-restricted zones.
- 1000W:Specialized towing configurations for commercial fleet auxiliary power units.
Mature deployment sits with 250W. Newer deployment is concentrated in 500W.
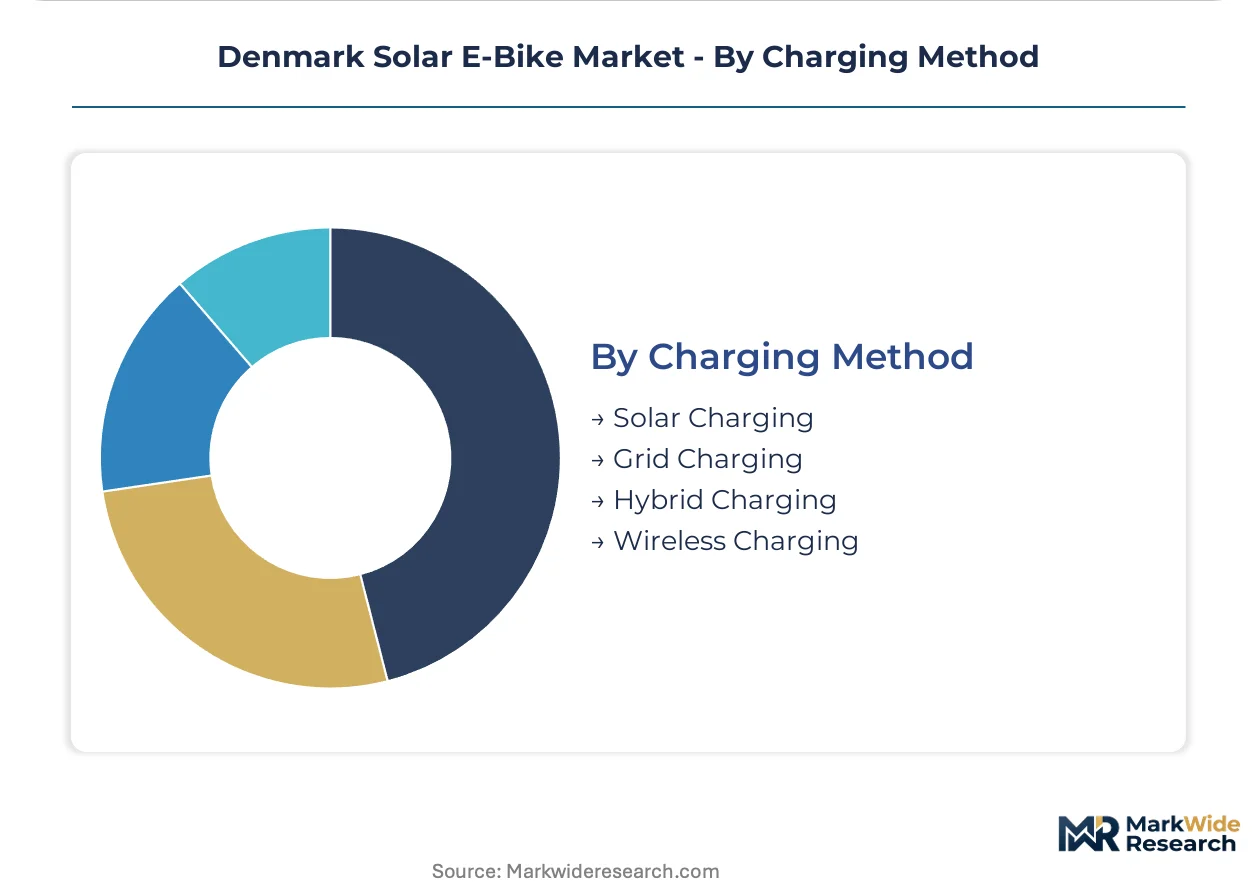
Charging Method:
Energy input architecture determines grid dependency claims and total cost of ownership positioning.
- Hybrid Charging:Simultaneous solar supplementation during grid charging extends effective range without infrastructure dependency. Fleet operators specify this for guaranteed daily kilometer coverage contracts.
- Solar Charging:Standalone photovoltaic dependency appeals to off-grid recreational users and sustainability-marketed consumer segments.
- Grid Charging:Baseline configuration for cost-minimized procurement; solar retrofit pathways through modular bundling.
- Wireless Charging:Inductive pad integration at Copenhagen employer facilities enables opportunity charging without connector wear.
Mature deployment sits with Grid Charging. Newer deployment is concentrated in Hybrid Charging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish solar e-bike production concentrates in Zealand's metropolitan corridor, while consumption spreads across Jutland and Funen through established dealer networks. The domestic manufacturing base remains specialized, with component sourcing extending to German and Dutch suppliers.
Zealand Metropolitan Corridor
Copenhagen's employer-subsidized cycle schemes drive concentrated demand for photovoltaic-equipped city e-bikes among knowledge-sector commuters. The Danish Road Directorate enforces motor-assisted speed limits under the Road Traffic Act, shaping fleet procurement specifications. Roskilde-Frederiksberg logistics operators deploy cargo configurations for last-mile diesel van replacement.
North Jutland
Aalborg's technical university partnerships advance perovskite cell efficiency research for Nordic diffuse-light conditions. The Danish Energy Agency's building-integrated solar incentives indirectly reduce panel costs for regional assemblers. Aarhus anchors dealer network density for commuter-oriented lithium-ion configurations.
South Jutland
Border proximity to German supply chains facilitates lithium-phosphate cell import for fleet operators prioritizing thermal stability. Esbjerg's port infrastructure supports photovoltaic component logistics from Asian suppliers. Regional parcel distributors specify hybrid charging architectures for guaranteed daily kilometer coverage.
Funen
Odense's manufacturing heritage sustains lightweight frame fabrication for design-forward Scandinavian brands. CE marking compliance timelines for novel frame-embedded cells delay commercialization by six to twelve months for innovative local designs. The island's cycling culture supports premium consumer segments seeking integrated solar augmentation.
Denmark Solar E-Bike Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Denmark's solar e-bike market, creating a tiered structure where scale advantages clash with design differentiation. The vendor base spans multinational bicycle manufacturers, regional assemblers, and domestic design houses. Three archetypes dominate: integrated frame-embedded innovators, established dealer-network incumbents, and lightweight Scandinavian design specialists. Competitive moves center on modular battery-solar bundling retail innovation and perovskite cell integration partnerships with technical universities.
Within the integrated photovoltaic tier, CUBE Bikes represents frame-embedded cell differentiation, while Royal Dutch Gazelle anchors commuter segment penetration through Jutland and Funen dealer networks. Nørdic Bikes occupies a design-specialist position emphasizing lightweight Scandinavian frames for urban riders. These three exemplify the strategic tension between technology integration, distribution scale, and aesthetic positioning that defines competitive dynamics in Denmark's high-latitude cycling economy.
| Leading Market Players |
|---|
| Giant Manufacturing Co. Ltd |
| CUBE Bikes |
| Royal Dutch Gazelle |
| Principia Bikes |
| Van Moof |
| Winther A/S |
| Batavus Intercycle Corporation |
| Nørdic Bikes |
| Accell Group |
| Others |
Pricing and Supply Chain Analysis
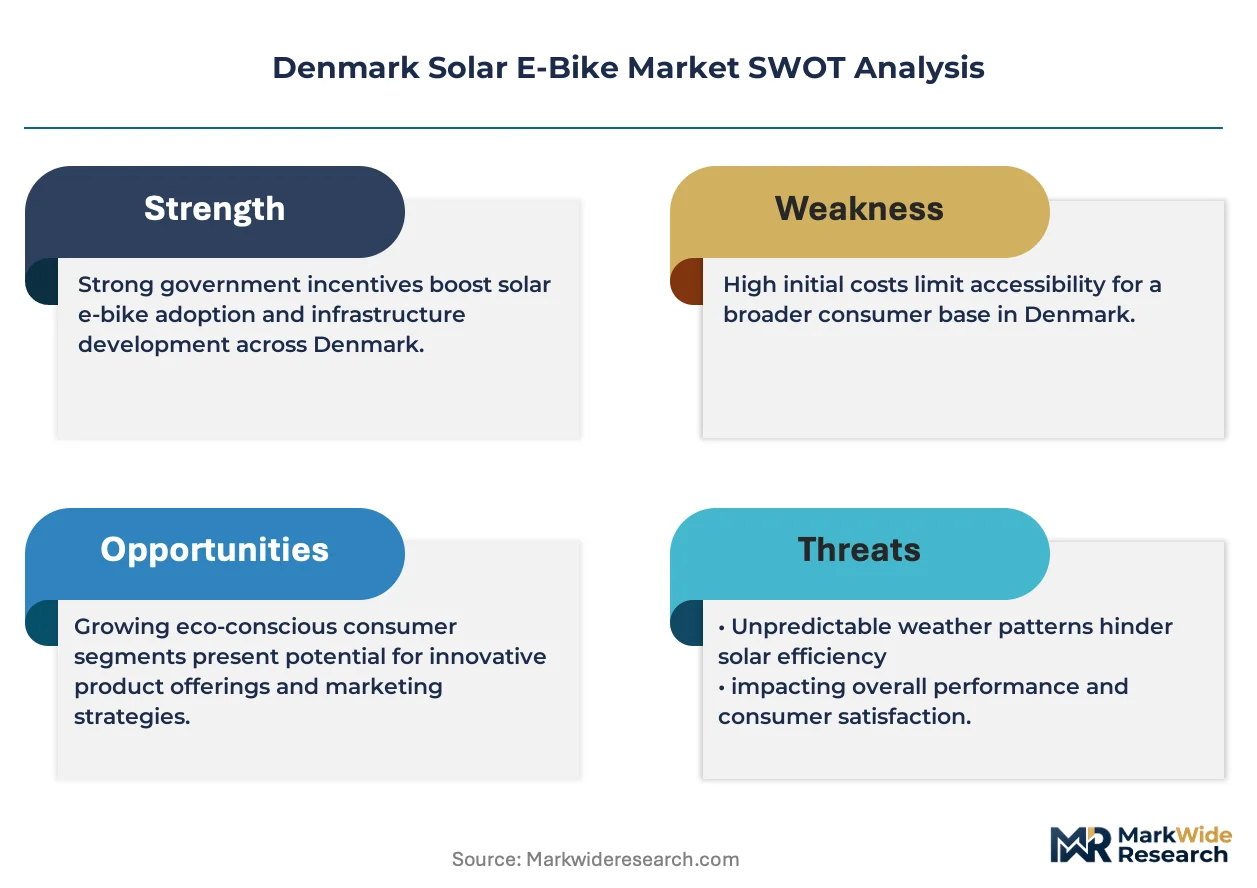
Employer-subsidized cycle scheme procurement concentrates demand among municipal employers and logistics operators, compressing margin structures toward volume-contract pricing with bundled service obligations. This buyer concentration shifts negotiating power toward fleet-scale purchasers and away from individual retail channels.
Pricing Analysis
Margin tightening in the commuter segment reflects lithium-phosphate cell import volatility and CE marking compliance delays for frame-embedded configurations. Three-tier pricing structure across premium, standard, and economy levels separates CUBE's integrated photovoltaic positioning from Gazelle's dealer-network volume play and Nørdic's design-premium tier. Price differentiation rests on panel integration depth and after-sales service bundling. Fleet operators exhibit lowest price sensitivity due to outcome-based contract structures, while individual consumers in Funen and Jutland retail channels drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-fleet channels handle employer-subsidized scheme demand, while established dealer networks in Jutland and Funen serve individual purchasers. Component sourcing draws from German frame suppliers, Dutch electrical system providers, and Asian lithium-phosphate cell manufacturers. Raw material dependencies center on photovoltaic silicon, rare-earth magnet materials for hub motors, and lithium carbonate for battery chemistry. Single-source vulnerability concentrates in non-EU cell supply, exposing Danish assemblers to currency fluctuation and chain-of-custody documentation gaps under pending EU battery passport requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's solar e-bike market is consolidating around employer-subsidized procurement scale, forcing sub-scale assemblers toward specialty positioning or exit as lithium cell supply concentration and compliance burdens escalate.
For Market Incumbents: Extend perovskite research partnerships with Aalborg and Copenhagen technical universities to lock in Nordic diffuse-light efficiency advantages before cell integration talent shortages worsen. Deepen backward integration into domestic panel manufacturing through Danish Energy Agency incentive capture, reducing import dependency as EU battery passport traceability requirements approach. Anchor fleet service contract capabilities in the Roskilde-Frederiksberg corridor to defend against outcome-based procurement shifts. For New Entrants and Emerging Players: Begin with modular battery-solar bundling retail innovation in Zealand's metropolitan corridor, where upgrade-path demand from standard e-bike owners outpaces full-replacement cycles. Target cargo configurations for regional parcel distributors seeking diesel van replacement, as this segment shows lowest penetration and highest margin tolerance for guaranteed daily kilometer coverage. Pursue direct technical training partnerships with Jutland dealer networks to close after-sales service gaps that constrain integrated system adoption. For Investors and Strategic Acquirers: Distressed-cycle entries favor lightweight frame design specialists with established Scandinavian aesthetic positioning and captive university research relationships in North Jutland. Long-term viability hinges on photovoltaic integration engineering capabilities that outlast commodity battery supply volatility. Monitor CE marking compliance timeline compression as inflection indicator—six-to-twelve month certification delays currently filter speculative entrants, but regulatory clarity acceleration would reshape competitive entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Cell Research Partnership | Aalborg technical university collaborations improve Nordic diffuse-light photovoltaic efficiency for frame-embedded applications. |
| Backward Integration into Panel Manufacturing | Danish Energy Agency building-integrated solar incentives enable domestic production capacity redirection toward e-bike components. |
| Outcome-Based Fleet Service Contract Expansion | Roskilde-Frederiksberg logistics operators now procure guaranteed kilometer coverage rather than asset ownership. |
| Dealer Network Technical Training Investment | Jutland and Funen retail channels require solar system servicing capability to close after-sales gaps. |
| EU Battery Passport Compliance Infrastructure | Cell-level traceability documentation systems must integrate with non-EU supplier procurement contracts. |
Research Methodology
Document review covered Danish Road Directorate enforcement guidelines, EU CE marking requirements, and Danish Energy Agency incentive frameworks, complemented by interviews with fleet procurement managers at Copenhagen-area logistics operators, technical directors at frame manufacturers, and retail channel heads across Jutland dealer networks. Secondary validation incorporated customs trade data for lithium-phosphate cell imports, technical university research partnership disclosures, and municipal employer subsidy program documentation. Bottom-up unit economics triangulated against top-down market sizing across product type, battery chemistry, and power rating dimensions.
Segment-level projections across the analysis window reflect modeled adoption curves for employer-subsidized cycle schemes, perovskite cell efficiency improvement timelines, and fleet procurement contract penetration rates. CAGRs derive from compounding annual unit growth assumptions adjusted for seasonal irradiance variation and regulatory compliance delay distributions. Modeled dimensions include frame geometry category, battery chemistry tier, motor power rating threshold, and charging architecture type, with cross-segment elasticity effects for modular upgrade pathways.
Underlying measurement precision varies by segment; City E-Bike employer scheme volumes carry tighter precision than emerging Cargo E-Bike fleet deployments where outcome-based contract structures complicate unit attribution. Forecasts reflect assumptions regarding perovskite laboratory-to-production transfer timelines, EU battery passport implementation schedules, and lithium cell supply contract renewal patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Hybrid EV Conversion Kit Market