
 Quantum Dot Solar Cell Market | 2026-2036
Quantum Dot Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Dot Solar Cell Market Insights
Asset-light leasing and power-purchase agreement financing is fragmenting competitive barriers in quantum dot solar deployment. QD Solar leverages specialized colloidal synthesis expertise to sustain technology leadership in cadmium-free formulations. Samsung Electronics anchors South Korean supply chains through in-house semiconductor-grade quantum dot production. First Solar competes in thin-film integration by extending its CdTe manufacturing knowledge toward quantum dot tandem architectures.
Quantum dot solar cells employ semiconductor nanocrystals tunable across the visible and infrared spectrum, typically synthesized through hot-injection colloidal chemistry with diameters of 2-10 nanometers for bandgap engineering from 1.0 to 2.0 eV. These devices capture low-energy photons that silicon wastes, primarily serving utility and commercial installations seeking levelized cost breakthroughs. Perovskite quantum dot technology leads research intensity due to solution-processability and defect tolerance, while building-integrated photovoltaics represents the fastest-growing application as architects embed semitransparent quantum dot coatings into glass facades. Flexible panel form factors occupy emerging margin pools in portable and off-grid segments where weight constraints dominate rigid substrate alternatives.
The EPA administers production tax credits under the Inflation Reduction Act that directly reduce quantum dot project financing costs, while NHTSA fleet electrification mandates indirectly boost solar-powered charging infrastructure demand. China's MIIT enforces GB standards for cadmium content that reshape quantum dot material choices for export-bound manufacturers. South Korea's MFDS and KATS coordinate perovskite stability testing protocols that determine which formulations achieve commercial certification. Stakeholders must monitor which regulatory jurisdiction first mandates quantum dot recycling standards, as this will dictate where capital-intensive manufacturing capacity locates.
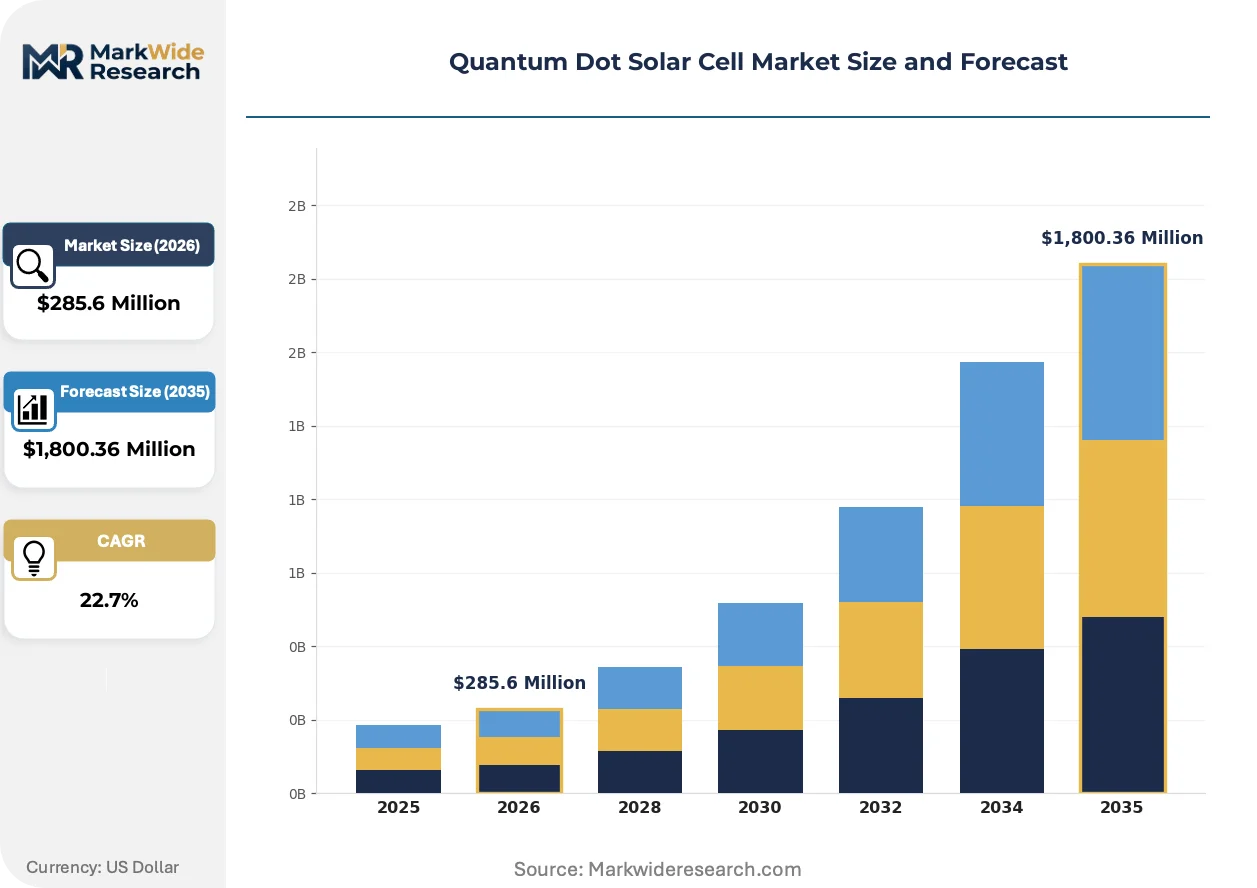
Market Dynamics
Conversion efficiency breakthroughs in tandem architectures are compressing the cost-per-watt gap between quantum dot modules and incumbent silicon, forcing capital reallocation across utility-scale procurement desks.
Growth Catalysts
- Inflation Reduction Act tax credits:The EPA-administered production tax credits directly reduce project financing costs for quantum dot installations in the United States, accelerating utility developer adoption timelines.
- Building-integrated photovoltaics:Architects in Germany and South Korea specify semitransparent quantum dot coatings for glass facades, creating non-utility demand channels that bypass traditional solar farm economics.
- Perovskite quantum dot synthesis:Solution-processable formulations with defect tolerance are achieving commercial certification thresholds faster than earlier colloidal chemistries, compressing R&D-to-deployment cycles.
Market Restraints
- Cadmium content restrictions:China's MIIT enforces GB standards that force export-bound manufacturers to reformulate quantum dot materials, raising compliance costs and limiting supplier flexibility.
- East Asian supply concentration:Semiconductor-grade quantum dot production clusters in South Korea, Japan, and China create geographic vulnerability to trade policy disruptions and input bottlenecks.
- Encapsulation stability gaps:Perovskite quantum dots degrade under thermal cycling faster than silicon alternatives, restricting deployment to temperate climates and controlled environments.
Strategic Opportunities
- Off-grid portable segments:Flexible panel form factors address weight constraints in military and expeditionary applications where rigid silicon substrates fail, opening margin pools outside utility procurement.
- South Korean certification protocols:MFDS and KATS coordination on perovskite stability testing creates first-mover advantage for formulations achieving commercial approval ahead of rival jurisdictions.
- Quantum dot-silicon tandems:Integration with existing CdTe manufacturing knowledge enables thin-film producers to capture infrared spectrum photons without full process retooling.
Industry Challenges
- Colloidal synthesis talent scarcity:Hot-injection chemistry expertise concentrates in academic and national laboratory settings, constraining manufacturing scale-up for commercial production lines.
- Recycling standard uncertainty:No jurisdiction has mandated quantum dot end-of-life protocols, leaving capital-intensive manufacturing location decisions exposed to future regulatory retroactivity.
- Net metering rule fragmentation:US state-level variations in interconnection policy create project approval delays that compress developer returns and financing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Dot Solar Cell Market |
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $1,800.36 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hybrid, CdSe, PbS, Perovskite Application: Building-Integrated Photovoltaics, Concentrated Solar Power, Portable Devices, Off-Grid Systems Form Factor: Flexible Panels, Rigid Panels, Coating Solutions, Modules End User: Residential, Commercial, Industrial, Utilities |
| Companies Covered | QD Solar, Nanosys, Samsung Electronics, LG Chem, Oxford PV, First Solar, SunPower Corporation, Hanwha Q CELLS, Quantum Materials Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Dot Solar Cell Market Trends and Innovations
Hot-injection colloidal synthesis methods are enabling bandgap engineering precision that was previously unattainable, compressing the performance gap between laboratory demonstrations and field-deployed modules.
Perovskite quantum dot technology is collapsing the historical trade-off between solution-processability and thermal stability that plagued earlier nanocrystal formulations. Utility-scale developers in California and Texas are piloting tandem architectures that layer perovskite quantum dots atop silicon cells to harvest infrared photons. This convergence is collapsing the levelized cost threshold that previously confined quantum dots to niche building-integrated applications.
The EU's F-Gas Regulation and REACH restrictions on hazardous substances are forcing cadmium-free formulation priorities across export-oriented manufacturers. South Korean producers have retooled synthesis lines to eliminate heavy metal content ahead of anticipated European import standards. German and Dutch project developers now specify cadmium-free quantum dots in tender documents, shifting competitive advantage toward suppliers with established green chemistry capabilities.
Power-purchase agreement structures are displacing direct equipment purchases among commercial and industrial buyers seeking to offload technology risk. Asset-light leasing models from specialized financiers are fragmenting traditional competitive barriers that favored vertically integrated solar developers. This shift is most visible in Japan, where METI feed-in-tariff reductions have forced commercial rooftop owners toward third-party ownership structures that prioritize module performance guarantees over upfront capital efficiency.
Quantum Dot Solar Cell Market Segmentation
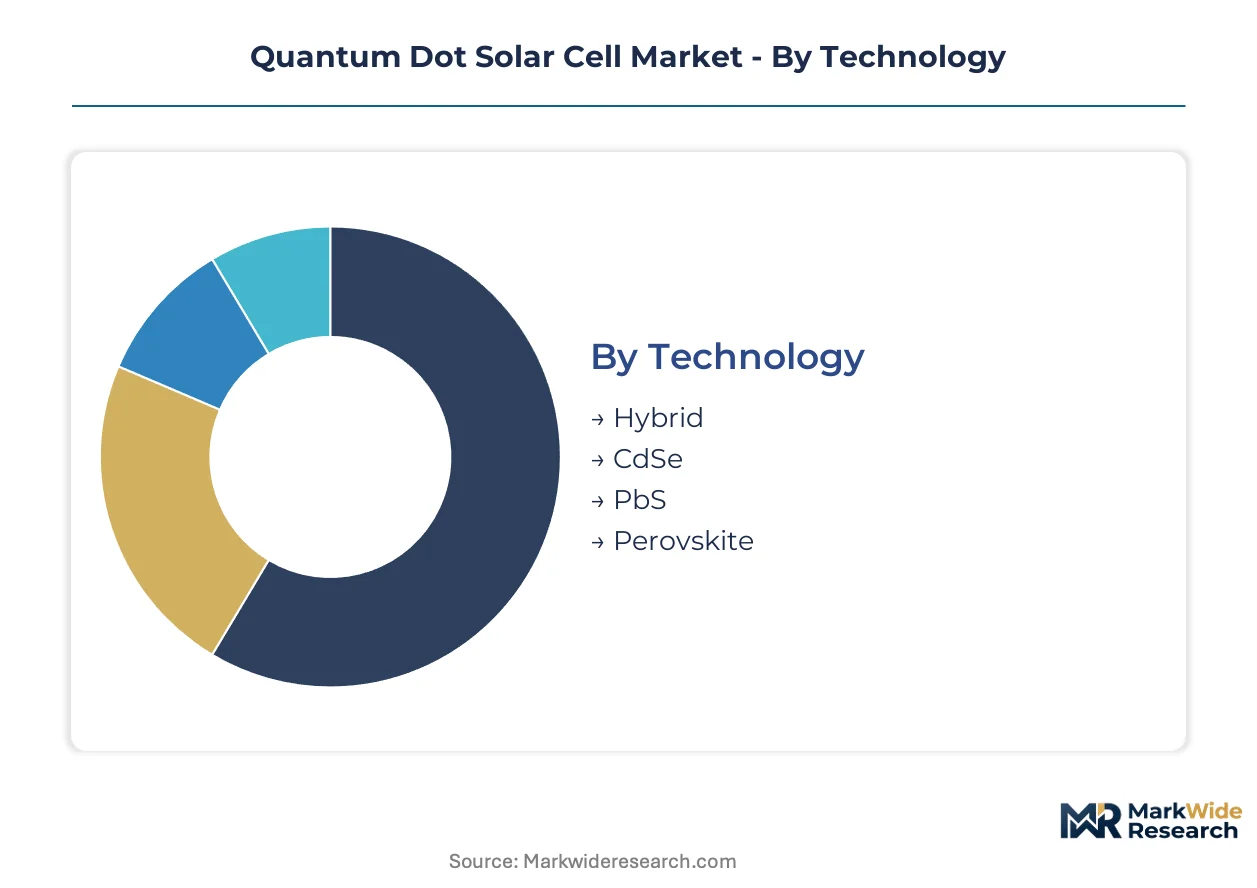
Technology choices in quantum dot solar cells determine bandgap tunability, manufacturing complexity, and regulatory compliance pathways. Application and form factor segmentation reveals divergent customer priorities between utility-scale procurement and specialized deployment environments.
Technology:
Materials science maturity spans decades-old colloidal chemistries to emergent perovskite architectures with distinct stability profiles.
- Perovskite:Solution-processable nanocrystals with defect tolerance enable rapid R&D-to-deployment compression. South Korean manufacturers under MFDS certification protocols concentrate pilot production for building-integrated installations.
- CdSe:Cadmium selenide quantum dots deliver mature hot-injection synthesis infrastructure and precise bandgap engineering across 1.5-2.0 eV range. China's MIIT GB standards on cadmium content force export-bound producers toward reformulation or market exclusion.
- Hybrid:Multi-material architectures combine infrared-harvesting PbS cores with visible-absorbing shells. Japanese national laboratories anchor fundamental research.
- PbS:Lead sulfide nanocrystals access sub-1.2 eV bandgaps for tandem silicon integration. Thermal cycling degradation restricts deployment to temperate climates.
Perovskite handles the majority of research throughput; CdSe remains the fastest mover on commercial share.
Application:
End-use environments impose divergent constraints on encapsulation durability, weight tolerance, and architectural integration requirements.
- Building-Integrated Photovoltaics:Semitransparent quantum dot coatings embed directly into glass facades for simultaneous energy generation and daylight transmission. German and Dutch architects specify cadmium-free formulations under REACH restrictions.
- Portable Devices:Flexible form factors address weight constraints in military and expeditionary power systems. Off-grid demand concentrates in Japanese disaster preparedness procurement.
- Concentrated Solar Power:Quantum dot spectral conversion layers boost efficiency in high-irradiance environments. Utility developers in Texas and California pilot tandem architectures.
- Off-Grid Systems:Remote installations prioritize reliability over conversion efficiency maximization. African and Southeast Asian rural electrification programs drive volume.
Building-Integrated Photovoltaics commands premium pricing; Portable Devices is expanding most quickly on share.
Form Factor:
Substrate flexibility determines installation labor requirements, transportation economics, and applicable regulatory certification pathways.
- Coating Solutions:Direct-deposition quantum dot inks enable retrofit of existing glass infrastructure without full panel replacement. South Korean construction integrators specify for commercial facade projects.
- Flexible Panels:Polymer substrates reduce weight by 60-80% versus glass alternatives. Military and marine applications in Japan and the United States drive procurement.
- Modules:Standardized framing accelerates utility-scale deployment timelines. First Solar's CdTe manufacturing knowledge transfers to tandem quantum dot integration.
- Rigid Panels:Glass-glass encapsulation delivers maximum environmental protection for rooftop installations. Residential segment in Germany favors proven durability.
Modules dominate utility throughput; Coating Solutions shows steepest expansion trajectory in commercial segments.
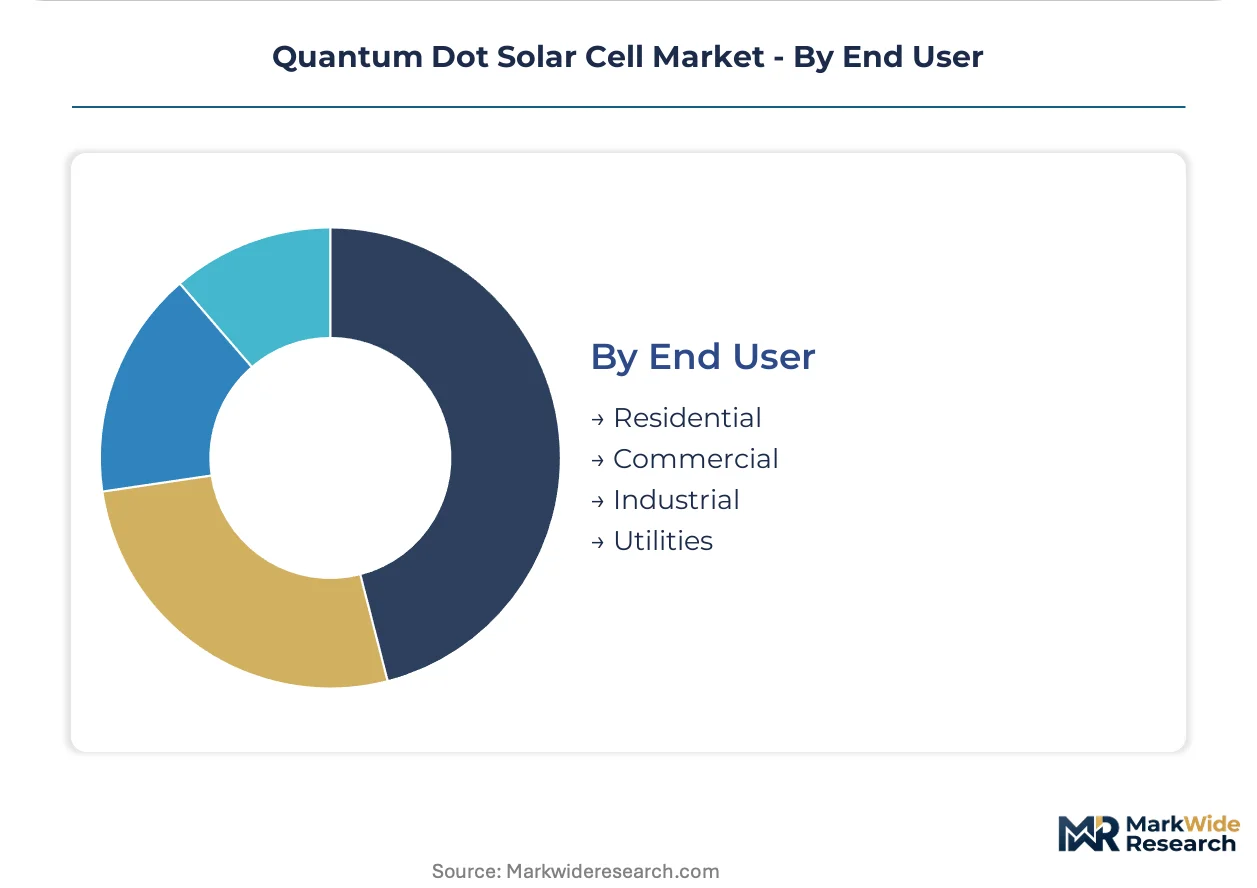
End User:
Customer scale determines financing structure preference, performance guarantee requirements, and technology risk tolerance.
- Utilities:Gigawatt-scale procurement desks prioritize levelized cost minimization over conversion efficiency records. IRA tax credits administered by the EPA accelerate project approval timelines.
- Commercial:Power-purchase agreement structures displace direct equipment purchases. Japanese METI feed-in-tariff reductions force third-party ownership models.
- Industrial:On-site generation targets peak demand charge reduction. Texas and California manufacturing facilities pilot perovskite-silicon tandems.
- Residential:Distributed rooftop installations face interconnection delays from fragmented US state-level net metering rules. German residential segment leads European adoption.
Utilities anchor volume demand; Commercial is climbing the fastest on financing innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's production tax credits under the Inflation Reduction Act are accelerating quantum dot project approvals in the United States. South Korea's MFDS certification protocols create competitive advantage for perovskite formulations. China's MIIT cadmium content standards reshape material choices for export-bound manufacturers.
United States
Utility-scale developers in California and Texas are piloting tandem perovskite-silicon architectures to harvest infrared photons. The EPA-administered IRA tax credits directly reduce project financing costs, compressing developer adoption timelines. Austin and San Diego clusters anchor field demonstration programs for commercial building-integrated installations.
South Korea
Samsung Electronics anchors domestic supply chains through in-house semiconductor-grade quantum dot production. The MFDS coordinates with KATS on perovskite stability testing protocols that determine commercial certification eligibility. Seoul metropolitan area manufacturers concentrate pilot production lines for building-integrated facade applications.
China
Export-bound manufacturers face reformulation pressures from MIIT-enforced GB standards on cadmium content in quantum dot materials. Yangtze River Delta production clusters retool synthesis lines to maintain European market access under REACH restrictions. Suzhou and Shanghai facilities lead cadmium-free formulation scale-up.
Germany
Architects in Berlin and Munich specify semitransparent quantum dot coatings for glass facades under EU F-Gas Regulation and REACH hazardous substance restrictions. The national building code integration of photovoltaic mandates creates non-utility demand channels. Bavarian research institutes anchor fundamental perovskite stability studies.
Japan
METI feed-in-tariff reductions force commercial rooftop owners toward third-party ownership structures prioritizing performance guarantees. Portable flexible panel demand concentrates in disaster preparedness procurement for off-grid resilience. Osaka-Kobe industrial corridor hosts thin-film integration research for tandem architectures.
Quantum Dot Solar Cell Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: colloidal synthesis specialists with captive material science expertise, diversified electronics conglomerates leveraging in-house semiconductor capabilities, and thin-film incumbents extending existing manufacturing knowledge toward tandem architectures. Competitive moves center on certification racing under divergent national protocols and synthesis capacity expansion near East Asian manufacturing clusters.
Within the synthesis-specialist tier, QD Solar represents the cadmium-free formulation priority that German and Dutch project developers now specify in tender documents. Samsung Electronics exemplifies the electronics conglomerate archetype, anchoring South Korean supply chain concentration through captive quantum dot production. First Solar occupies the thin-film incumbent position, transferring CdTe manufacturing knowledge toward quantum dot tandem integration without full process retooling.
| Leading Market Players |
|---|
| QD Solar |
| Nanosys |
| Samsung Electronics |
| LG Chem |
| Oxford PV |
| First Solar |
| SunPower Corporation |
| Hanwha Q CELLS |
| Quantum Materials Corp |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in South Korean perovskite pilot lines is compressing supplier margins while elevating price premiums for MFDS-certified formulations, forcing buyers into longer offtake commitments to secure allocation.
Pricing Analysis
Certification level under MFDS and KATS protocols creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects stability testing rigor, with commercial-grade perovskite quantum dots commanding substantial premiums over laboratory-scale batches. Cost compression in cadmium-free CdSe formulations is intensifying because Chinese manufacturers retool to satisfy REACH export requirements. Utility procurement desks show lowest price sensitivity, while portable device integrators in Japanese disaster preparedness programs operate under severe budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for export-bound quantum dot manufacturers. Production gravity centers on South Korea, Japan, and China, with Yangtze River Delta synthesis clusters feeding global module assembly. Raw material dependencies include indium phosphide precursors, lead halide salts, and semiconductor-grade solvents sourced from specialized chemical suppliers. Distribution runs through East Asian electronics conglomerates with captive quantum dot production, bypassing merchant market spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
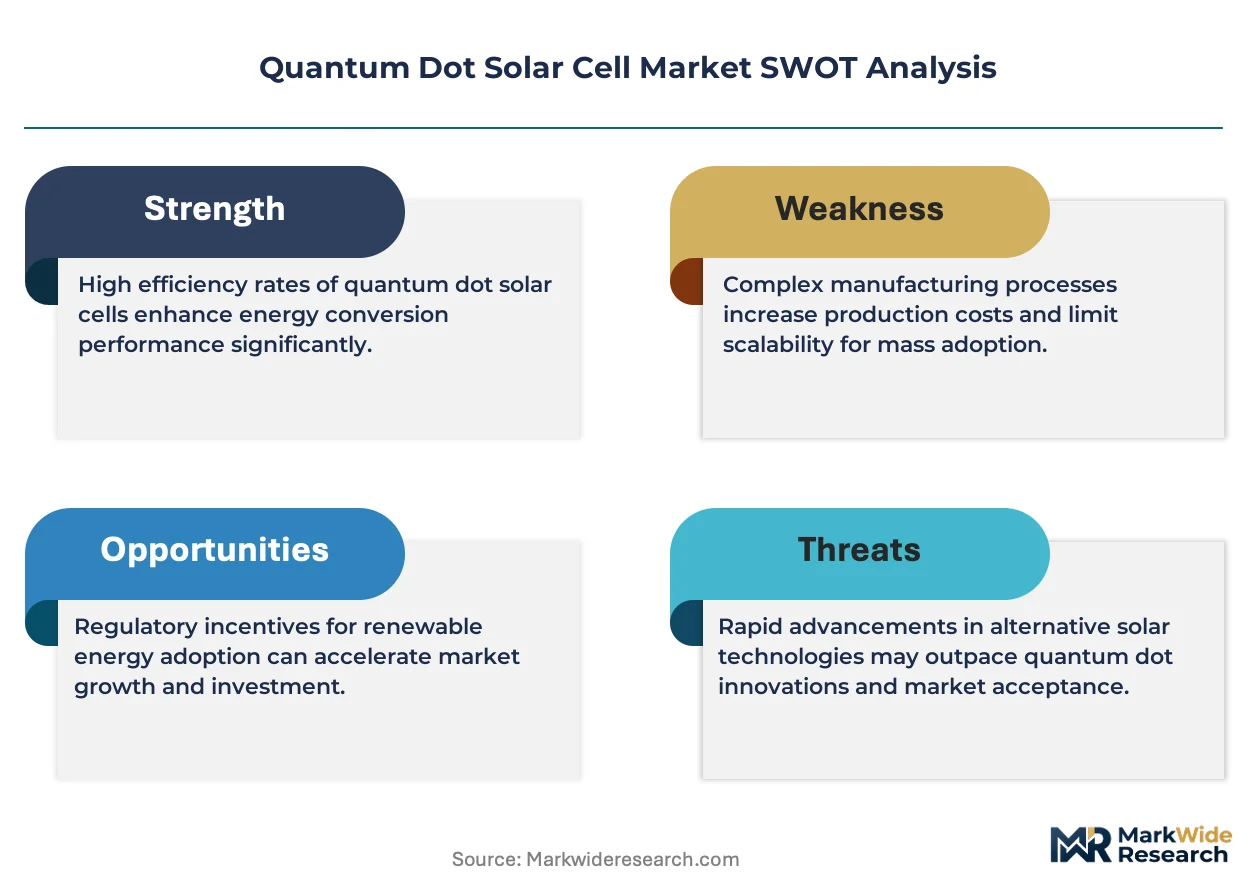
This market sits in early-cycle expansion as IRA tax credits compress utility developer adoption timelines from demonstration to deployment.
For Market Incumbents: Harden certification moats by accelerating MFDS stability protocol compliance ahead of rival jurisdictions. Deepen upstream control over colloidal synthesis talent pools through national laboratory partnerships. Defend against thin-film incumbents transferring CdTe manufacturing knowledge by locking exclusive tandem architecture supply agreements with silicon cell producers. For New Entrants and Emerging Players: Pursue off-grid portable segments where weight constraints exclude rigid silicon alternatives and military procurement budgets tolerate premium pricing. German building-integrated photovoltaic specifications under REACH restrictions offer the most penetrable white-space for cadmium-free formulation specialists. Lead with coating solution retrofit value propositions that avoid full panel replacement capex. For Investors and Strategic Acquirers: Long-term, this sits as a materials science platform play because quantum dot expertise transfers across display, solar, and sensing applications with minimal retooling. Acquisition targets should emphasize colloidal synthesis specialists with established green chemistry capabilities rather than capital-intensive module assemblers. Watch South Korean perovskite commercial certification timelines as the signal for manufacturing scale-up inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Stability Certification | MFDS approval unlocks commercial deployment in South Korean building-integrated installations. |
| Cadmium-Free Formulation Scale-Up | Yangtze River Delta retooling preserves European market access under REACH restrictions. |
| Tandem Architecture Partnership | CdTe manufacturers capture infrared spectrum without full process abandonment. |
| Flexible Panel Military Procurement | Japanese disaster preparedness programs create premium margin pools outside utility procurement. |
| Colloidal Synthesis Talent Acquisition | National laboratory partnerships constrain competitor manufacturing scale-up velocity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility procurement desks, commercial rooftop developers, colloidal synthesis chemists, and building-integrated photovoltaic architects. Secondary validation drew from EPA IRA implementation guidance, MFDS certification protocol documents, MIIT GB standard filings, and ECHA REACH restriction updates. Bottom-up module shipment estimates triangulated against top-down project finance database tracking.
Calibration against historical efficiency improvement curves and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology chemistry, application environment, form factor substrate, and end-user scale tier. CAGRs derived from installed capacity build-out assumptions under varying tax credit and net metering policy scenarios, with perovskite stability degradation rates as a critical sensitivity input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by thin-film incumbents or electronics conglomerates with captive quantum dot production would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
3D Projector Market
Optoelectronics
Laser Diode Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Laser Projection Market
Optoelectronics
Laser Projector Market