
 Japan Optoelectronics Market | 2026-2036
Japan Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Optoelectronics Market Insights
Aftermarket service revenue for optical component calibration and laser system maintenance is reconfiguring margin pools away from pure hardware sales toward recurring technical service contracts. Sony Corporation leverages its CMOS image sensor dominance to anchor premium positioning in industrial machine vision. Hamamatsu Photonics sustains leadership in photomultiplier tubes and scientific light detection through deep vertical integration of crystal growth and vacuum tube manufacturing. Mitsubishi Electric Corporation competes in high-power laser modules for factory automation, extending its factory-floor channel control across Japanese automotive and electronics plants.
Optoelectronics encompasses devices that source, detect, or control light across ultraviolet through infrared wavelengths, typically fabricated from III-V compound semiconductors such as gallium arsenide and indium phosphide using metal-organic chemical vapor deposition processes. These components convert electrical signals to optical output or vice versa, enabling fiber-optic communications, precision sensing, and solid-state illumination. LED products occupy the largest installed base within the product type dimension, though laser diodes capture expanding share as LiDAR and optical communications power requirements intensify. Active optoelectronics leads the technology split due to its indispensable role in signal generation and amplification, while passive optoelectronics maintains stable demand in connector and coupler applications where thermal reliability matters most.
METI's industrial standards framework and JIS certification requirements shape component interoperability benchmarks for domestic optoelectronic equipment, while PMDA guidelines govern medical imaging device classifications that constrain market access for non-compliant suppliers. The country's national pharmaceutical regulator maintains stringent optical performance thresholds for endoscopic and diagnostic imaging systems, filtering out lower-tier component vendors. Stakeholders must monitor how Japan's semiconductor equipment export controls and evolving Green Transformation procurement rules redirect domestic fab capacity toward optoelectronic chip production.
Market Dynamics
Automotive OEMs in Japan are accelerating LiDAR integration for autonomous driving platforms, compressing development cycles and forcing tier-one suppliers to reconfigure optical component sourcing patterns around real-time sensor fusion requirements.
Growth Catalysts
- METI Green Transformation policy:Procurement mandates for domestic optoelectronic chip production are redirecting fab capacity toward III-V compound semiconductor manufacturing for industrial sensing applications.
- Osaka-Kyoto photonics corridor:Concentrated precision manufacturing ecosystems and university research clusters are shortening prototype-to-production timelines for laser diode modules.
- LiDAR adoption in autonomous vehicles:Optical sensing system specifications from Japanese automotive assemblers are pulling demand for high-power laser diodes and photodetector arrays.
Market Restraints
- Indium phosphide substrate volatility:Concentrated supply from single-source crystal growers creates input cost instability for III-V epitaxy houses serving the Japanese market.
- PMDA optical performance thresholds:Stringent medical imaging device classifications filter out non-compliant component vendors, constraining supplier base expansion for endoscopic system integrators.
- Silicon photonics substitution:CMOS-compatible optical interconnects threaten discrete compound semiconductor solutions in datacom applications below 400G.
Strategic Opportunities
- Kansai precision manufacturing ecosystem:Untapped calibration and maintenance service contracts for installed laser systems offer recurring revenue streams beyond hardware sales.
- Optical sensing in factory automation:Convergence of machine vision with collaborative robotics creates white space for CMOS image sensor modules in electronics assembly plants.
- JIS certification alignment:Industrial standards framework interoperability benchmarks enable domestic component vendors to capture replacement demand from non-compliant imports.
Industry Challenges
- Vacuum tube engineering talent scarcity:Photomultiplier tube manufacturing requires specialized glass-to-metal sealing expertise that is aging out of the Japanese workforce without adequate replacement pipelines.
- Metal-organic chemical vapor deposition capex intensity:Reactor equipment for III-V epitaxy demands capital commitments that strain mid-tier foundry balance sheets.
- Legacy fiber-optic infrastructure integration:New active optoelectronic components must interoperate with installed passive connector systems governed by outdated JIS specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Optoelectronics Market |
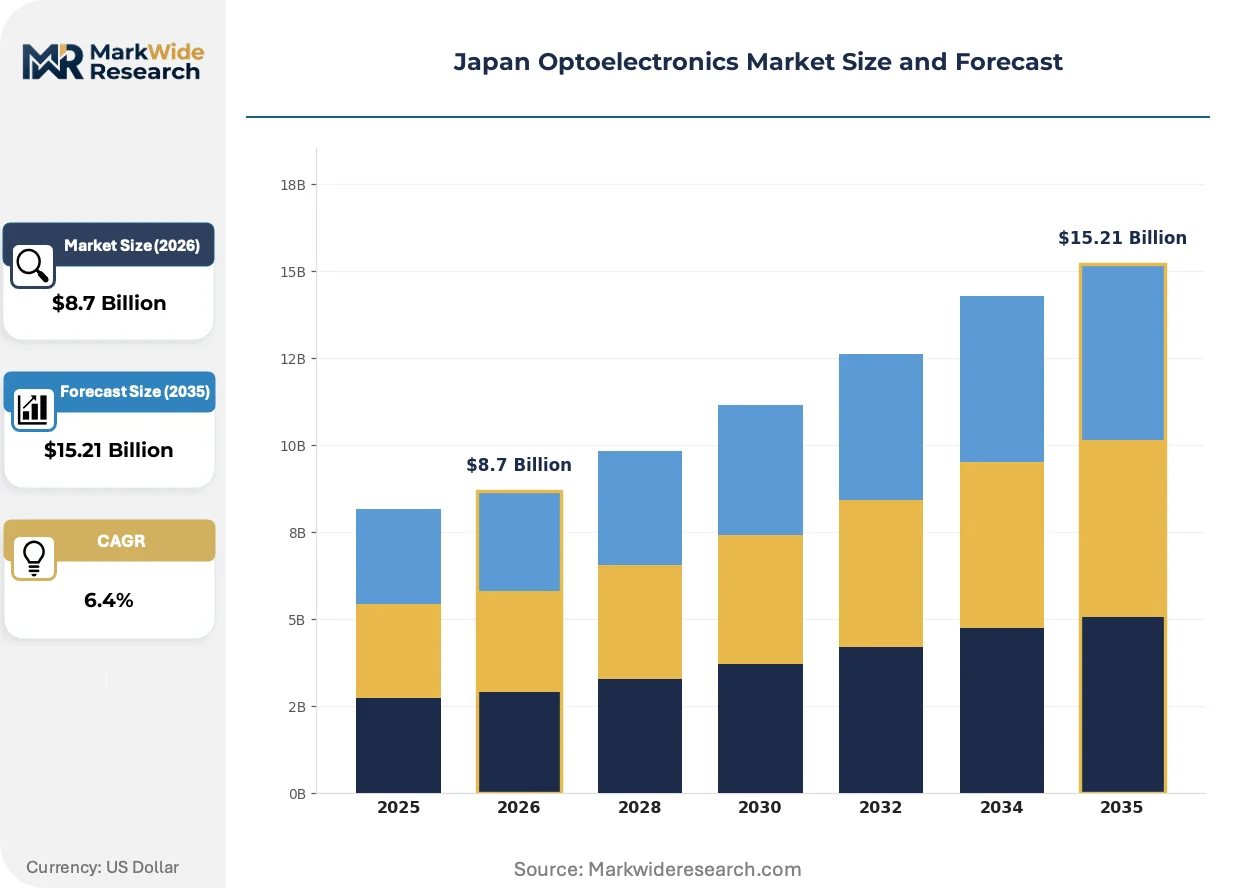
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diodes, Photodetectors, Optical Sensors Application: Consumer Electronics, Telecommunications, Automotive, Industrial Technology: Active Optoelectronics, Passive Optoelectronics, Analog Optical Processing, Digital Optical Processing End User: Telecom Providers, Manufacturing Firms, Automotive OEMs, Medical Institutions |
| Companies Covered | Panasonic Corporation, Sony Corporation, Mitsubishi Electric Corporation, Omron Corporation, Keyence Corporation, Hamamatsu Photonics, Toshiba Corporation, Fujitsu Limited, Stanley Electric Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Optoelectronics Market Trends and Innovations
Silicon carbide substrate integration with gallium nitride epitaxy is compressing thermal management requirements for high-power laser modules, while METI semiconductor reshoring incentives accelerate domestic process equipment deployment.
Co-packaged optics architectures are digitizing signal routing between switches and transceivers in hyperscale datacenters. Japanese telecommunications equipment manufacturers are qualifying these modules for 800G transmission trials. The technology is digitizing traditional discrete component supply chains into integrated photonic assembly operations.
METI export control frameworks for semiconductor manufacturing equipment are tightening licensing requirements for metal-organic chemical vapor deposition systems. Domestic tool builders face compliance documentation burdens that extend sales cycles. The regulation most affects optoelectronic chip foundries seeking to upgrade reactor capacity for indium phosphide production.
Aftermarket service unbundling is separating optical component calibration from original equipment sales in industrial machine vision. System integrators in Aichi and Shizuoka prefectures now procure sensors and maintenance contracts through distinct vendor relationships. The pattern concentrates in automotive inspection line deployments where uptime guarantees override capital procurement preferences.
Japan Optoelectronics Market Segmentation
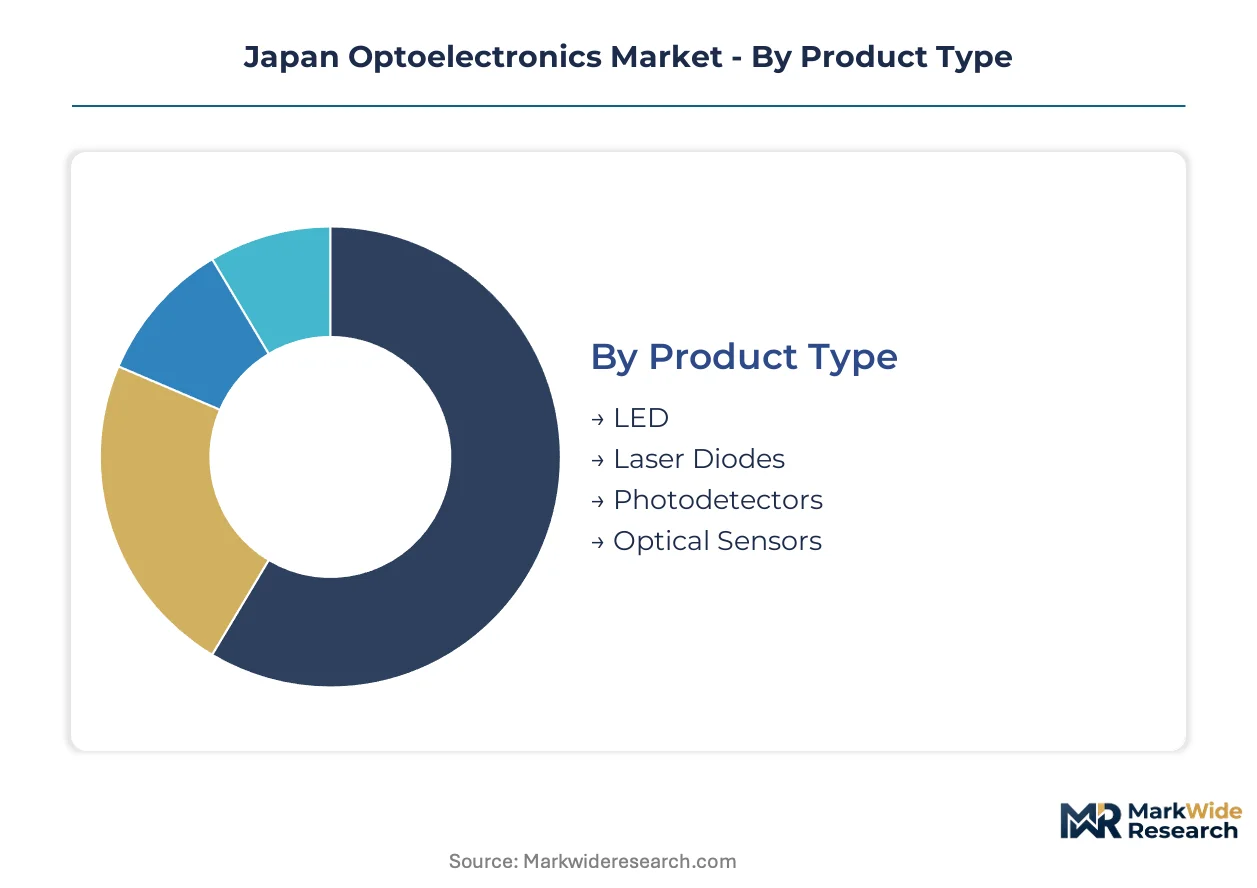
Optoelectronics spans heterogeneous device physics and deployment contexts across Japan. Component specifications diverge sharply between consumer-facing illumination and industrial sensing applications. Understanding these segment boundaries clarifies where procurement budgets concentrate and where technical standards create vendor lock-in.
Product Type:
Use-case spectrum stretches from ambient lighting in residential fixtures to precision LiDAR emitters in autonomous vehicle prototypes.
- LED:Solid-state illumination fabricated from gallium nitride epitaxy on sapphire or silicon carbide substrates. Demand concentrates in Osaka Prefecture residential retrofit programs and commercial building efficiency mandates under METI Green Transformation procurement rules. Thermal management and phosphor conversion efficiency differentiate premium architectural products from commodity replacement lamps.
- Laser Diodes:Coherent light sources operating across visible through infrared wavelengths, manufactured via metal-organic chemical vapor deposition of indium phosphide or gallium arsenide heterostructures. Automotive OEMs in Aichi Prefecture specify these for LiDAR and optical sensing systems in Level 3 autonomous driving platforms. Wavelength stability and beam quality metrics filter supplier qualification lists.
- Photodetectors:Semiconductor junction devices converting optical signals to electrical current. Machine vision integrators in Kyoto Prefecture deploy silicon PIN and avalanche photodiodes for factory automation inspection lines.
- Optical Sensors:Integrated modules combining light sources, detectors, and signal conditioning electronics. Medical device manufacturers serving PMDA-regulated endoscopic imaging systems source these through validated domestic supply chains.
The dominant share belongs to LED, while Laser Diodes is closing the gap fastest.
Application:
Cost tier stratification separates high-volume consumer shipments from low-volume, high-margin industrial contracts.
- Consumer Electronics:Smartphone displays, camera modules, and ambient lighting systems. Domestic brands in Tokyo and Osaka metropolitan areas drive specification-setting for CMOS image sensor integration.
- Telecommunications:Fiber-optic transceivers and wavelength-division multiplexing equipment. NTT and regional carriers in the Kansai corridor qualify coherent optical modules for 800G backbone trials.
- Automotive:LiDAR emitters, cabin monitoring cameras, and head-up display projectors. Toyota, Honda, and Nissan assemblers in Aichi, Shizuoka, and Tochigi prefectures source through tier-one optical component suppliers.
- Industrial:Machine vision, laser marking, and precision measurement systems. Electronics assembly plants in Kyoto and Osaka deploy these for defect detection and robotic guidance.
Consumer Electronics captures the highest shipment volumes, though Automotive commands the steepest expansion trajectory.
Technology:
Volume concentration favors established active device architectures over emerging processing paradigms.
- Active Optoelectronics:Components generating or amplifying optical signals through electrical excitation, including laser diodes, LEDs, and semiconductor optical amplifiers. Foundry capacity at domestic III-V epitaxy houses in the Osaka-Kyoto corridor concentrates here.
- Passive Optoelectronics:Connectors, couplers, splitters, and isolators manipulating light without electrical conversion. NTT's legacy fiber infrastructure in the Kanto region sustains replacement demand.
- Analog Optical Processing:Continuous-wave signal manipulation for microwave photonics and radio-over-fiber applications. Defense and aerospace contractors in Nagoya specify these for radar signal distribution.
- Digital Optical Processing:Optical computing kernels and photonic integrated circuits for AI inference acceleration. University research clusters in Kyoto and Tsukuba pilot these for next-generation datacenter interconnects.
Active Optoelectronics retains the dominant technology share, while Digital Optical Processing is gaining share fastest.
End User:
Customer type determines procurement sophistication and contract structure complexity.
- Telecom Providers:NTT, KDDI, and SoftBank drive standardization for optical transceiver form factors. Their central procurement offices in Tokyo and Osaka enforce interoperability testing.
- Manufacturing Firms:Electronics assemblers and precision equipment builders in the Kansai corridor purchase machine vision and laser processing systems. These buyers prioritize uptime guarantees over capital expenditure minimization.
- Automotive OEMs:Tier-one optical component specifications cascade from Toyota, Honda, Nissan, and Subaru engineering centers. Their Aichi and Shizuoka operations demand automotive-grade qualification data.
- Medical Institutions:Hospitals and diagnostic imaging centers procure PMDA-compliant endoscopic and surgical visualization systems. Olympus and Fujifilm supply chains dominate this segment.
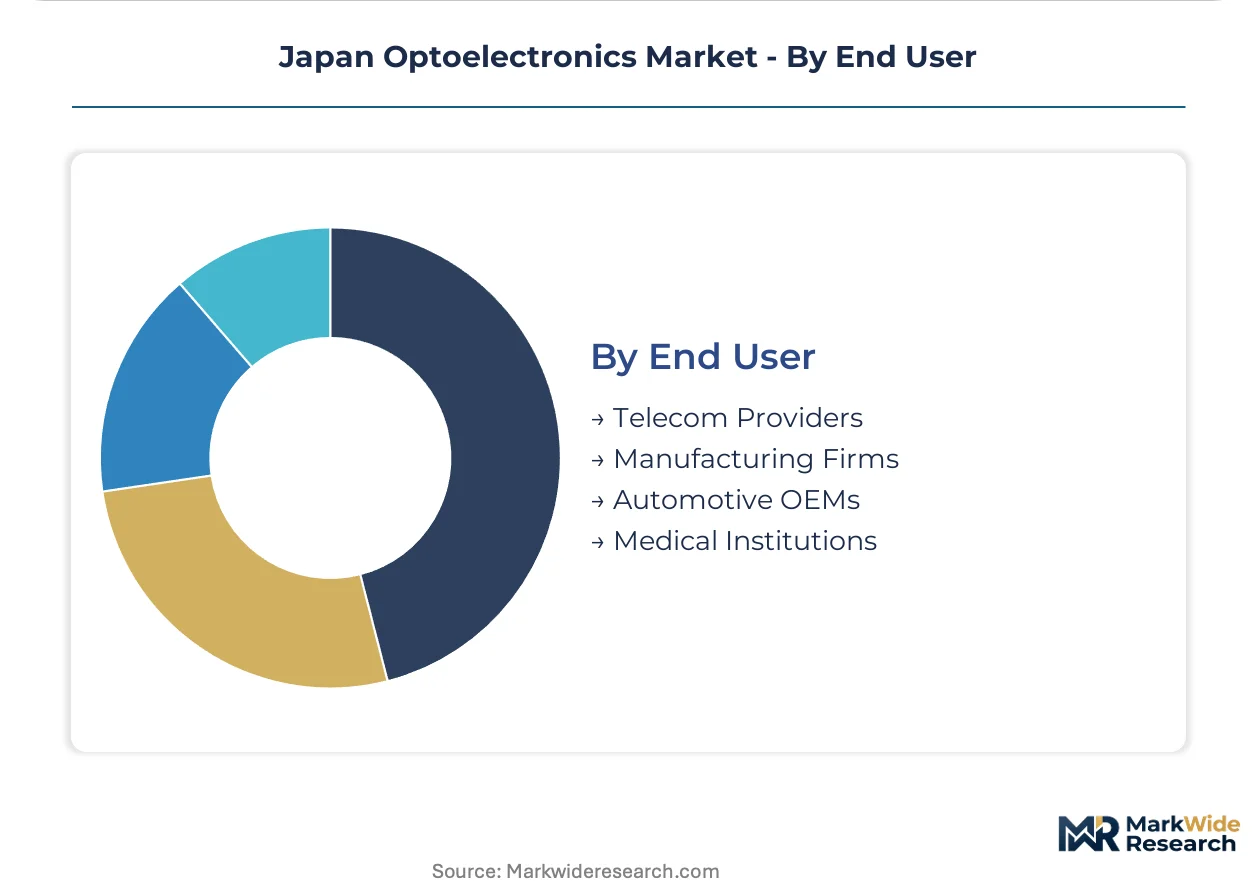
Telecom Providers command the largest procurement budgets, though Automotive OEMs are expanding their share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in consumer electronics segments demonstrate acute price sensitivity, while automotive and medical end users absorb premium pricing for qualified components. Industrial procurement sits between these poles, prioritizing uptime guarantees over capital minimization. This elasticity gradient shapes regional production strategies across Japanese manufacturing clusters.
Kanto/Tokyo
NTT and KDDI central procurement offices drive optical transceiver standardization for 800G backbone trials. METI semiconductor reshoring incentives redirect domestic fab capacity toward III-V compound semiconductor manufacturing. The Tsukuba research corridor pilots photonic integrated circuits for next-generation datacenter interconnects.
Kansai/Osaka
Osaka Prefecture residential retrofit programs and commercial building efficiency mandates concentrate LED demand under Green Transformation procurement rules. Hamamatsu Photonics anchors photomultiplier tube production through in-house crystal growth operations. The Osaka-Kyoto photonics corridor shortens prototype-to-production timelines for laser diode modules serving industrial sensing.
Chubu/Nagoya
Toyota, Honda, and Nissan engineering centers cascade tier-one optical component specifications for LiDAR and cabin monitoring systems. PMDA guidelines govern medical imaging device classifications filtering supplier bases for endoscopic system integrators. Aichi and Shizuoka prefecture operations demand automotive-grade qualification data from component vendors.
Kyushu
Electronics assembly plants deploy machine vision systems for defect detection and robotic guidance in precision manufacturing. JIS certification requirements shape component interoperability benchmarks for domestic optoelectronic equipment. Fukuoka and Saga prefectures host CMOS image sensor module integration facilities serving factory automation demand.
Japan Optoelectronics Market Competitive Landscape
Capability concentration sits with specialized photonics houses possessing captive crystal growth and vacuum tube expertise; scale advantage sits with diversified electronics conglomerates controlling factory-floor distribution channels. The market structures around three tiers: premium component specialists, integrated industrial equipment suppliers, and commodity optoelectronic assemblers. Dominant competitive moves include backward integration into substrate manufacturing and strategic partnerships for LiDAR system co-development.
Within the premium component tier, Hamamatsu Photonics and Sony Corporation exemplify divergent specialization strategies—Hamamatsu through scientific light detection vertical integration, Sony through CMOS image sensor dominance in industrial machine vision. Mitsubishi Electric Corporation occupies a position bridging component supply and factory automation system integration. These three entities represent the competitive archetypes shaping procurement patterns across Japanese automotive and electronics plants.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Sony Corporation |
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Keyence Corporation |
| Hamamatsu Photonics |
| Toshiba Corporation |
| Fujitsu Limited |
| Stanley Electric Co |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at domestic III-V epitaxy houses in the Osaka-Kyoto corridor is compressing lead times for indium phosphide laser diode modules and amplifying pricing power among qualified suppliers serving automotive LiDAR programs. METI semiconductor reshoring incentives are redirecting investment toward captive substrate production, yet capacity lags behind demand from Aichi Prefecture OEMs.
Pricing Analysis
Aftermarket service contracts for optical component calibration and laser system maintenance now capture the dominant share of lifetime value across industrial machine vision deployments. Pricing stratifies across JIS-certified premium tiers, automotive-grade qualification levels, and standard commercial grades, with certification investment acting as the primary differentiation driver. Cost compression in commodity LED replacement lamps is intensifying because of import competition from Southeast Asian assemblers. Consumer electronics buyers demonstrate acute price sensitivity, while medical device manufacturers absorb premium pricing for PMDA-compliant optical sensors.
Supply Chain Analysis
Indium phosphide and gallium arsenide substrate supply feeds from Japan, the United States, and China, with crystal growth operations concentrated among single-source specialty vendors. Metal-organic precursors, sapphire substrates, and vacuum tube glass-to-metal seals constitute critical input dependencies. Single-source vulnerability in photomultiplier tube engineering talent creates unreplaceable bottlenecks for scientific light detection equipment. Distribution runs through tier-one automotive suppliers and factory automation system integrators who enforce qualification data requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application requirements—spanning PMDA-regulated medical imaging, automotive-grade LiDAR, and industrial machine vision—is carving out specialized niches for component vendors with targeted certification investments. The divergence in technical standards prevents commoditization and rewards focused capability development.
For Market Incumbents: Harden market position by deepening backward integration into indium phosphide crystal growth and securing captive supply of metal-organic precursors against substrate volatility. Expand JIS certification alignment to capture replacement demand from non-compliant imports while reinforcing channel control through factory-floor service contracts in Aichi and Shizuoka prefectures.
For New Entrants and Emerging Players: Mid-tier calibration and maintenance service contracts for installed laser systems in the Kansai precision manufacturing ecosystem represent the most penetrable entry point. Optical sensing modules for collaborative robotics in Kyoto electronics assembly plants offer a second white-space target. A go-to-market strategy anchored through university research cluster partnerships enables rapid prototype-to-production qualification.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized photonics houses possessing captive crystal growth and vacuum tube expertise with defensible scientific light detection franchises. Long-term viability hinges on sustained R&D intensity across the analysis window rather than scale economies in commodity segments. Watch for METI export control enforcement tightening as the inflection signal for domestic tool builder consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captive indium phosphide crystal growth insulates margins from single-source supply volatility. |
| JIS Certification Investment | Industrial standards alignment unlocks replacement demand from non-compliant import suppliers. |
| LiDAR System Co-Development Partnership | Automotive OEM collaboration secures tier-one qualification status for laser diode modules. |
| Aftermarket Service Unbundling | Separate calibration contracts generate recurring revenue beyond hardware sales in machine vision. |
| Photonics Corridor Cluster Expansion | Osaka-Kyoto proximity shortens prototyping cycles for industrial sensing applications. |
Research Methodology
A standing panel of III-V epitaxy house process engineers, automotive Tier 1 supplier procurement managers, factory automation system integrators, and PMDA regulatory affairs specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from METI industrial policy filings, JIS standards documentation, semiconductor equipment trade data, and domestic OEM qualification databases. Bottom-up shipment analysis across LED, laser diode, and photodetector product categories triangulated against top-down manufacturing capacity assessments.
Scenario-bracketing around METI Green Transformation procurement enforcement and silicon photonics substitution risk framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application, technology, and end user, with additional granularity on certification tier and regional manufacturing cluster. CAGRs derived from installed base growth rates and replacement cycle analysis, incorporating automotive LiDAR adoption curves and datacenter optical interconnect demand as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates, indium commodity pricing, or automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution timelines. Cross-checking against NTT and KDDI optical transceiver procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Light Projector Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Laser Projection Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
China Optical Detector Market