
 Ingaas Avalanche Photodiode Market | 2026-2036
Ingaas Avalanche Photodiode Market Size, Share, and Industry Trends Forecast 2026-2036
Ingaas Avalanche Photodiode Market Analysis
Aftermarket calibration and repair revenue is fragmenting across regional service networks as OEMs pull maintenance contracts in-house. Hamamatsu Photonics leverages its vertically integrated fabrication facilities in Japan to control wafer supply. Excelitas Technologies anchors North American defense contracts through ITAR-compliant packaging capabilities. Thorlabs, Inc. competes in research-grade instrumentation with configurable gain modules for laboratory environments.
An indium gallium arsenide avalanche photodiode is a compound semiconductor detector operating in the near-infrared spectrum from 900 to 1700 nanometers, fabricated through metal-organic chemical vapor deposition on indium phosphide substrates to achieve internal multiplication factors exceeding 10. The device converts weak optical signals into measurable electrical current for precision timing and photon counting in low-light industrial systems. Single-photon variants command premium positioning in quantum computing receiver chains where dark count rates below 100 Hz define performance tiers. Sensing applications through lidar systems expand fastest as automotive and aerial mapping programs scale receiver volume. Geiger mode architectures remain concentrated in defense and research budgets where cost sensitivity sits lowest.
FDA device classification rules govern medical imaging applications incorporating InGaAS detectors into ophthalmic and endoscopic instruments. REACH substance restrictions in Europe constrain indium and gallium sourcing through supply chain due diligence mandates. FCC spectrum allocations for free-space optical links shape telecommunications deployment timelines for receiver component qualification. Stakeholders must weigh dual-use export controls against commercial volume targets when allocating R&D across defense and civilian product lines.
Market Dynamics
Lidar receiver deployment for automotive and aerial mapping programs is concentrating volume demand among photodiode suppliers, while REACH substance restrictions in Europe constrain indium and gallium sourcing through supply chain due diligence mandates.
Growth Catalysts
- Telecommunications infrastructure:FCC spectrum allocations for free-space optical links are accelerating receiver component qualification timelines across North American networks.
- REACH compliance:European material sourcing requirements are forcing supply chain transparency upgrades that favor qualified InGaAs vendors with documented provenance systems.
- Quantum computing:Single-photon detector variants with sub-100 Hz dark count rates are pulling premium positioning in receiver chains for photon-counting applications.
Market Restraints
- Indium supply concentration:Primary indium refining capacity clusters in Chinese smelting operations, exposing wafer fabrication to geopolitical supply interruptions.
- ITAR packaging requirements:Defense-qualified hermetic sealing adds 40-60% cost premiums that constrain dual-use product line economics.
- Silicon photonics substitution:Silicon-germanium detectors at 1550 nm are capturing cost-sensitive telecommunications slots below 10 Gbps.
Strategic Opportunities
- Domestic lidar manufacturing:China's concentrated demand expansion offers captive volume agreements for photodiode suppliers with localized packaging capabilities.
- Medical imaging integration:FDA device classification pathways for ophthalmic instruments create regulated revenue streams with extended product lifecycles.
- Geiger mode defense applications:Research and military budgets with low cost sensitivity sustain premium pricing for specialized architectures.
Industry Challenges
- Compound semiconductor fabrication talent:Metal-organic chemical vapor deposition expertise resides in aging workforces at Japanese and European foundries.
- Dual-use export control navigation:EAR and ITAR classification reviews extend qualification timelines for products spanning civilian and defense end-uses.
- Wafer-scale integration complexity:Hybridizing InGaAs absorption layers with silicon readout circuits demands heterogeneous packaging capabilities few vendors possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ingaas Avalanche Photodiode Market |
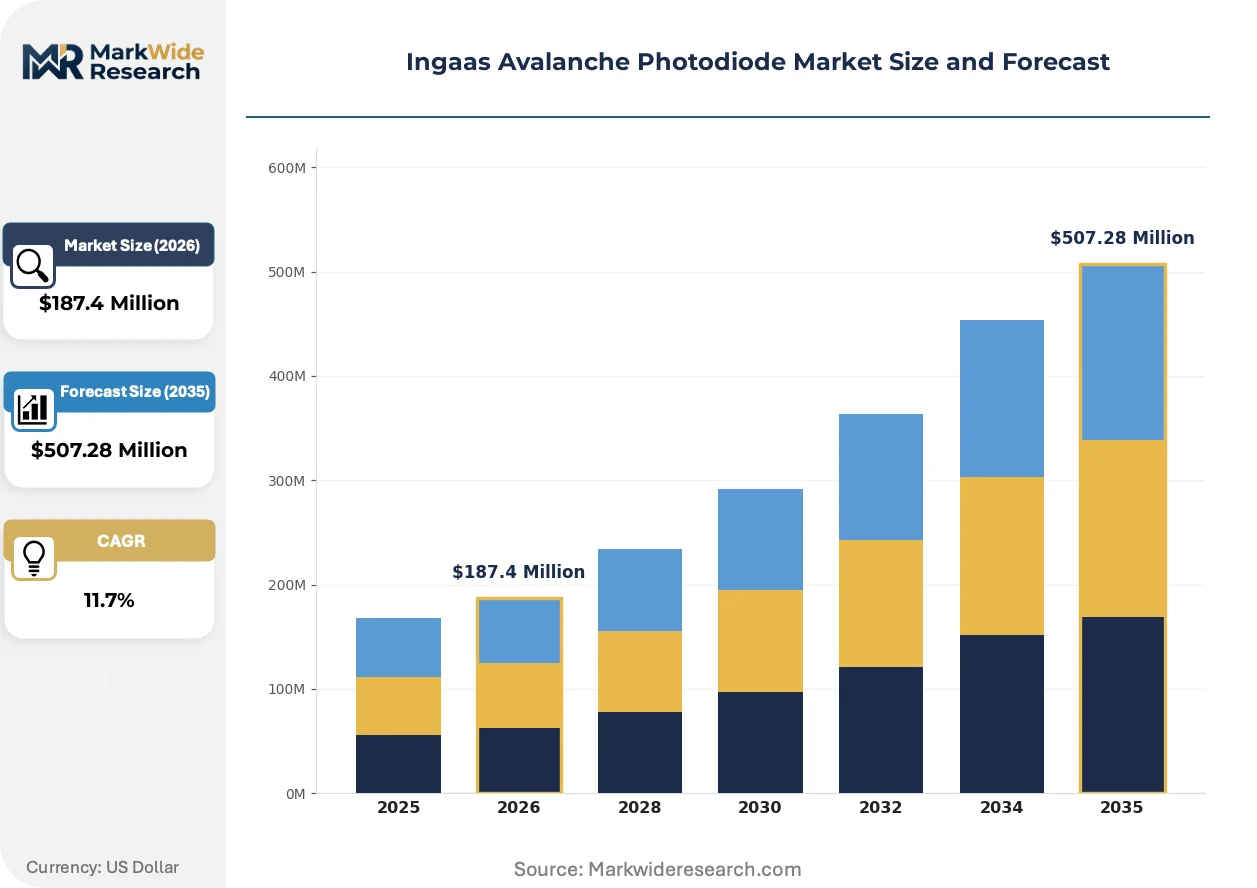
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Photon, Multi-Photon, Linear, Geiger Mode Technology: Optical Communication, Sensing Applications, Imaging, Spectroscopy End User: Telecommunications, Defense, Medical Devices, Research Institutions Application: Data Acquisition, Lidar Systems, Quantum Computing, Environmental Monitoring |
| Companies Covered | Hamamatsu Photonics, Laser Components DG, Inc., First Sensor, OSI Optoelectronics, Excelitas Technologies, Albis Optoelectronics AG, Renesas Electronics Corporation, Kyosemi Corporation, Thorlabs, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ingaas Avalanche Photodiode Market Emerging Trajectories
Receiver architecture evolution is compressing the performance gap between research-grade and industrial-grade photodiodes, while regulatory chemistry restrictions and procurement centralization reshape competitive positioning.
Single-photon avalanche diode arrays with integrated time-to-digital conversion are rendering obsolete discrete-component receiver assemblies in quantum key distribution systems. Banking and defense communication networks in Switzerland and South Korea are specifying these monolithic solutions for metropolitan fiber links. The shift collapses subsystem vendor margins while concentrating value capture at the die fabrication level.
REACH Annex XIV substance restrictions are tightening indium compound reporting thresholds across European electronics supply chains. Component distributors in Germany and France now require full material disclosure certificates for photodiode shipments above 1 ton annual volume. Suppliers without documented conflict-mineral-free sourcing are losing qualified supplier status with automotive tier-1 integrators.
Automotive lidar procurement is consolidating from module-level sourcing toward die-level contracts with direct wafer supply agreements. Tier-1 sensor integrators in Michigan and Bavaria are bypassing traditional photodiode distributors to secure multi-year foundry allocations. This disintermediation compresses channel margins while locking volume commitments to vertically integrated manufacturers with captive epitaxy capacity.
Ingaas Avalanche Photodiode Market Segmentation
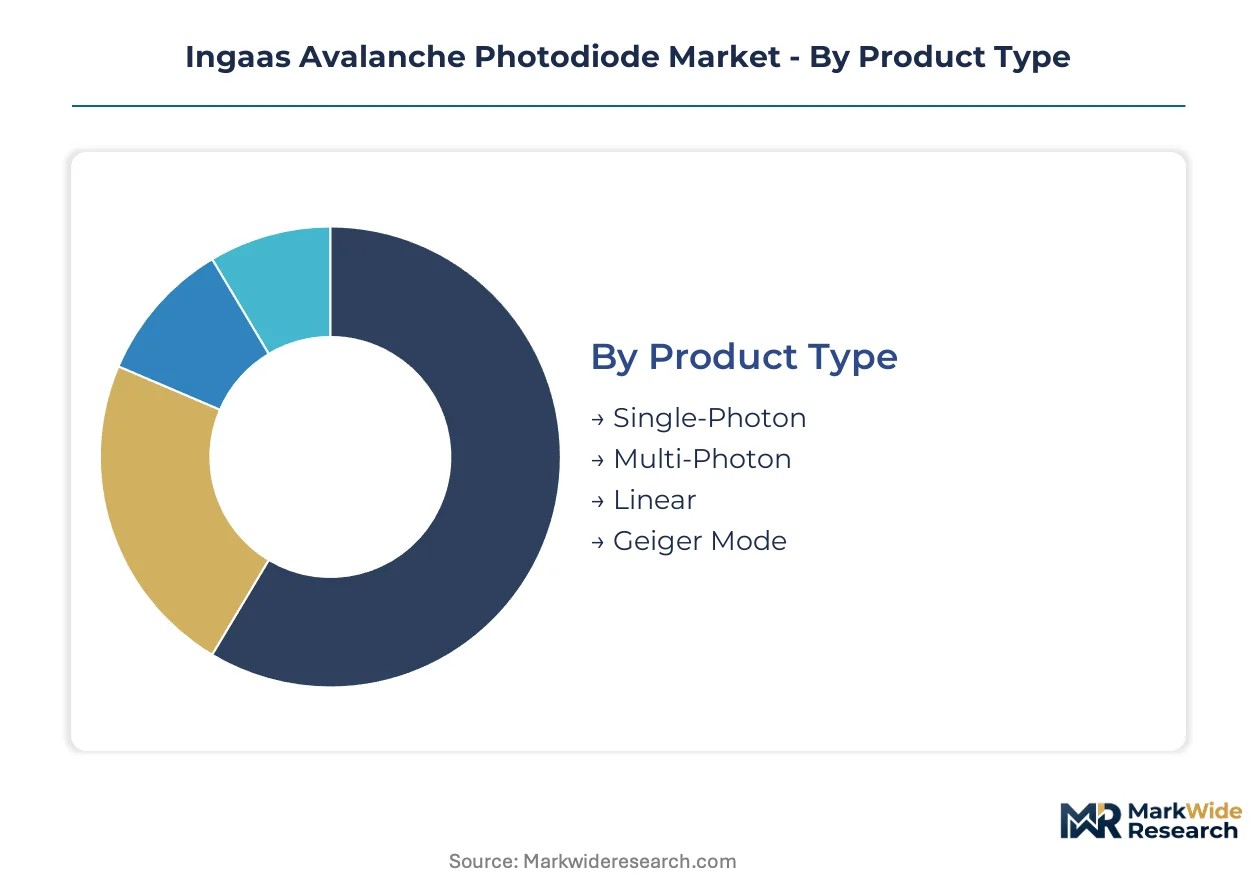
Receiver architecture choices in InGaAs avalanche photodiodes cascade through calibration protocols, field service requirements, and replacement part logistics. Segmentation by performance tier and integration depth determines aftermarket revenue capture and customer lock-in durability.
Product Type:
After-sales intensity varies sharply across product architectures, with single-photon variants demanding specialized cryogenic service contracts while linear-mode units rely on standard field replacement programs.
- Single-Photon:These detectors achieve dark count rates below 100 Hz through thermoelectric cooling integration. Swiss banking networks and South Korean defense communication programs specify these for quantum key distribution infrastructure.
- Multi-Photon:Arrays with integrated time-to-digital conversion collapse discrete-component assemblies into monolithic solutions. Metropolitan fiber links in Geneva and Seoul are standardizing on these for photon-counting receiver chains.
- Linear:Standard analog output devices serve cost-sensitive telecommunications slots below 10 Gbps.
- Geiger Mode:Specialized architectures with passive quenching circuits concentrate in research and military budgets where hermetic sealing premiums are absorbed.
By volume, Linear leads. By growth pace, Single-Photon is ahead.
Technology:
Cost tier separation across technology categories reflects substrate material grades and epitaxial layer complexity rather than simple feature differentiation.
- Optical Communication:Receiver components for free-space optical links operate at 1550 nm with FCC spectrum allocation compliance. North American network qualification timelines are compressing as 400G deployment accelerates.
- Sensing Applications:Automotive lidar and aerial mapping programs concentrate volume demand. Tier-1 sensor integrators in Michigan and Bavaria are securing multi-year foundry allocations through direct wafer supply agreements.
- Imaging:FDA device classification governs ophthalmic and endoscopic instrument integration.
- Spectroscopy:Laboratory-grade instrumentation demands configurable gain modules for precision timing applications.
By revenue concentration, Sensing Applications dominates. By margin expansion, Optical Communication is climbing the fastest.
End User:
Customer type dictates procurement channel structure, with defense programs requiring ITAR-compliant packaging and medical device manufacturers demanding extended lifecycle guarantees.
- Telecommunications:Carrier procurement centralization favors vendors with documented REACH compliance and conflict-mineral-free sourcing certificates.
- Defense:EAR and ITAR classification reviews extend qualification timelines for dual-use products spanning civilian and military end-uses.
- Medical Devices:Regulated revenue streams with extended product lifecycles create stable aftermarket service contracts.
- Research Institutions:Budget volatility concentrates in academic procurement cycles with irregular volume patterns.
By contract value, Defense leads. By volume expansion, Telecommunications is gaining share fastest.
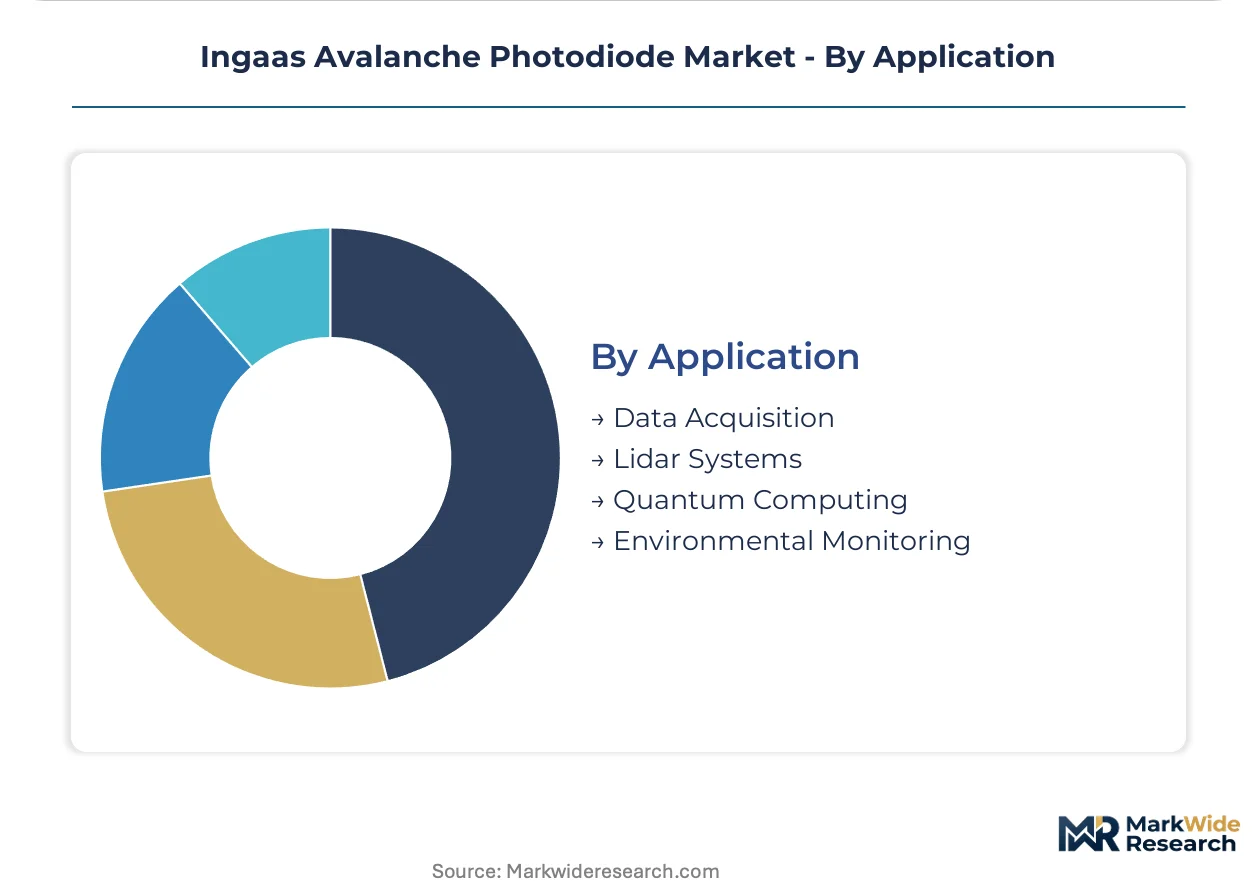
Application:
Application maturity determines whether pricing power resides at the die fabrication level or with subsystem integrators.
- Data Acquisition:Industrial automation and precision measurement systems require standard gain modules with field-replaceable packaging.
- Lidar Systems:Procurement consolidation from module-level toward die-level contracts is disintermediating traditional photodiode distributors. China's domestic manufacturing expansion offers captive volume agreements for suppliers with localized capabilities.
- Quantum Computing:Single-photon detector variants command premium positioning in receiver chains where performance tiers are defined by dark count specifications.
- Environmental Monitoring:Distributed sensing networks for atmospheric and oceanographic research operate on intermittent funding cycles with long procurement horizons.
By installed base, Data Acquisition leads. By investment intensity, Quantum Computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys InGaAs avalanche photodiodes predominantly for automotive lidar manufacturing, while the United States concentrates consumption in defense-qualified receiver chains and Switzerland anchors quantum key distribution infrastructure with single-photon variants.
United States
FCC spectrum allocations for free-space optical links at 1550 nm accelerate receiver qualification timelines across carrier networks. ITAR-compliant packaging requirements from the Department of State govern defense procurement, adding certification premiums to hermetic sealing. Michigan-based tier-1 sensor integrators are consolidating procurement from module-level toward direct die-level contracts with captive foundry allocations.
China
Domestic lidar manufacturing expansion concentrates volume demand for automotive receiver components. MIIT industrial policy prioritizes compound semiconductor self-sufficiency through domestic epitaxy capacity subsidies. Yangtze River Delta fabrication clusters in Shanghai and Suzhou are absorbing multi-year wafer supply agreements from vertically integrated photodiode suppliers.
Germany
REACH Annex XIV substance restrictions tighten indium compound reporting thresholds across electronics supply chains. ECHA compliance mandates full material disclosure certificates for automotive tier-1 integrators above 1 ton annual volume. Bavaria-based sensor manufacturers are bypassing traditional distributors to secure direct foundry allocations for lidar receiver die.
Switzerland
Banking network procurement for quantum key distribution infrastructure specifies single-photon detector arrays with sub-100 Hz dark count rates. Swissmedic device classification pathways govern medical imaging integration for ophthalmic instruments. Geneva metropolitan fiber links are standardizing on monolithic receiver solutions with integrated time-to-digital conversion.
South Korea
Defense communication programs specify single-photon avalanche diodes for metropolitan fiber link security. MFDS medical device regulations create extended lifecycle requirements for endoscopic instrument integration. Seoul-based banking networks are deploying quantum key distribution infrastructure with premium-tier receiver specifications.
Ingaas Avalanche Photodiode Market Vendor Landscape
Capability concentration sits with vertically integrated Japanese and European fabricators possessing captive metal-organic chemical vapor deposition capacity; scale advantage sits with North American defense contractors leveraging ITAR-compliant packaging infrastructure. The market structures around three tiers: premium single-photon specialists, mid-tier sensing application suppliers, and cost-focused telecommunications component vendors. Dominant competitive moves include backward integration into indium phosphide substrate supply and geographic expansion through localized packaging joint ventures in Chinese manufacturing zones.
Among Japanese photonics specialists, Hamamatsu Photonics K.K. exemplifies the vertically integrated archetype with in-house epitaxy control, while Thorlabs, Inc. occupies a position within the research-grade instrumentation tier configurable for laboratory environments. Excelitas Technologies Corp. anchors the North American defense-qualified segment through ITAR-compliant packaging capabilities. These three entities represent distinct competitive vectors: captive wafer supply, configurable gain module specialization, and regulatory-certified hermetic sealing respectively.
| Leading Market Players |
|---|
| Hamamatsu Photonics |
| Laser Components DG, Inc. |
| First Sensor |
| OSI Optoelectronics |
| Excelitas Technologies |
| Albis Optoelectronics AG |
| Renesas Electronics Corporation |
| Kyosemi Corporation |
| Thorlabs, Inc. |
| Others |
Supply Flow & Price Mechanics
Indium supply concentration in Chinese smelting operations creates simultaneous pricing tier compression at the commodity wafer level and premium expansion for qualified vendors with documented provenance systems. REACH compliance mandates in Europe and ITAR packaging requirements in the United States force a dual-track supply chain structure where certified channels command 40-60% cost premiums over standard commercial lanes.
Pricing Analysis
Long-term offtake agreements dominate volume procurement for automotive lidar programs, while spot purchasing persists for research-grade instrumentation with irregular demand patterns. Price differentiation hinges on ITAR certification tier and captive epitaxy capability, with defense-qualified hermetic sealing absorbing cost premiums that silicon photonics substitutes are eroding in telecommunications slots below 10 Gbps. Pricing pressure stems from silicon-germanium detector displacement in cost-sensitive carrier networks. Telecommunications procurement teams exhibit highest price sensitivity; quantum computing receiver chains show least.
Supply Chain Analysis
Primary indium refining capacity clusters in China, with secondary concentration in South Korean and Japanese wafer fabrication facilities. Metal-organic chemical vapor deposition expertise, indium phosphide substrates, and thermoelectric cooling modules constitute critical input dependencies. Single-source vulnerability in Chinese smelting operations exposes fabrication schedules to geopolitical interruption. Distribution runs through tier-1 sensor integrators in Michigan and Bavaria consolidating toward direct die-level contracts, bypassing traditional photodiode distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive lidar procurement centralization and quantum computing receiver deployment constitute a high-growth disruption driven by FCC spectrum allocation acceleration for free-space optical links.
For Market Incumbents: Pre-empt silicon photonics substitution in telecommunications by securing multi-year foundry allocations with automotive tier-1 integrators in Bavaria and Michigan. Deepen backward integration into indium phosphide substrate supply to control wafer cost position against Chinese smelting concentration risk. ITAR-compliant packaging infrastructure anchors defense revenue streams that offset margin compression in commercial slots. For New Entrants and Emerging Players: Establish a beachhead in medical imaging instrumentation where FDA device classification creates regulated barriers to rapid incumbent response. Target ophthalmic and endoscopic applications with extended lifecycle guarantees that incumbent defense contractors underserve. Lead with conflict-mineral-free sourcing certificates to capture European automotive tier-1 procurement mandates. For Investors and Strategic Acquirers: REACH Annex XIV substance restrictions reshape the acquisition landscape toward vendors with documented supply chain transparency systems. Five-to-ten year viability favors vertically integrated fabricators with captive metal-organic chemical vapor deposition capacity over fabless assembly operations. Watch for MIIT industrial policy announcements on compound semiconductor self-sufficiency subsidies as inflection signals for Chinese manufacturing zone joint venture valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive indium phosphide wafer production insulates margin position against Chinese smelting concentration. |
| ITAR-Compliant Packaging Certification | Defense-qualified hermetic sealing unlocks Department of State-governed procurement with premium absorption capacity. |
| Localized Packaging Joint Venture | Yangtze River Delta fabrication clusters absorb multi-year supply agreements from domestic lidar manufacturing expansion. |
| Single-Photon Array Product Launch | Swiss banking networks and South Korean defense programs specify sub-100 Hz dark count rate performance tiers. |
| REACH Compliance Documentation System | Full material disclosure certificates secure qualified supplier status with German and French automotive tier-1 integrators. |
Methodological Framework
A spread of perspectives from epitaxy process engineers, tier-1 sensor procurement directors, defense contracting officers, and quantum computing receiver architects converged on the working assumptions. Primary fieldwork with metal-organic chemical vapor deposition specialists and hospital biomedical engineering departments combined with secondary validation from FCC spectrum allocation filings, ECHA REACH substance databases, FDA device classification records, and SEC supplier disclosure documents. Bottom-up wafer demand modeling and top-down telecommunications infrastructure capex analysis provided triangulation anchors.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture tier, integration depth, end-use regulatory cluster, and geographic manufacturing hub. CAGRs derived from volume trajectory analysis against carrier network deployment schedules and automotive lidar platform adoption curves. Forecast inputs incorporated FCC qualification timeline compression and MIIT industrial policy subsidy trajectories.
Stress conditions across indium price volatility, REACH enforcement intensity, and silicon photonics substitution pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding telecommunications infrastructure buildout and defense procurement continuity. Geopolitical supply interruption or accelerated silicon-germanium detector maturation could revise trajectory assumptions. Cross-checking against hyperscaler free-space optical link capex disclosures and automotive OEM lidar platform roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Optoelectronics Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market