
 Dot Matrix Display Market | 2026-2036
Dot Matrix Display Market Size, Share, and Industry Trends Forecast 2026-2036
Dot Matrix Display Market Foresight
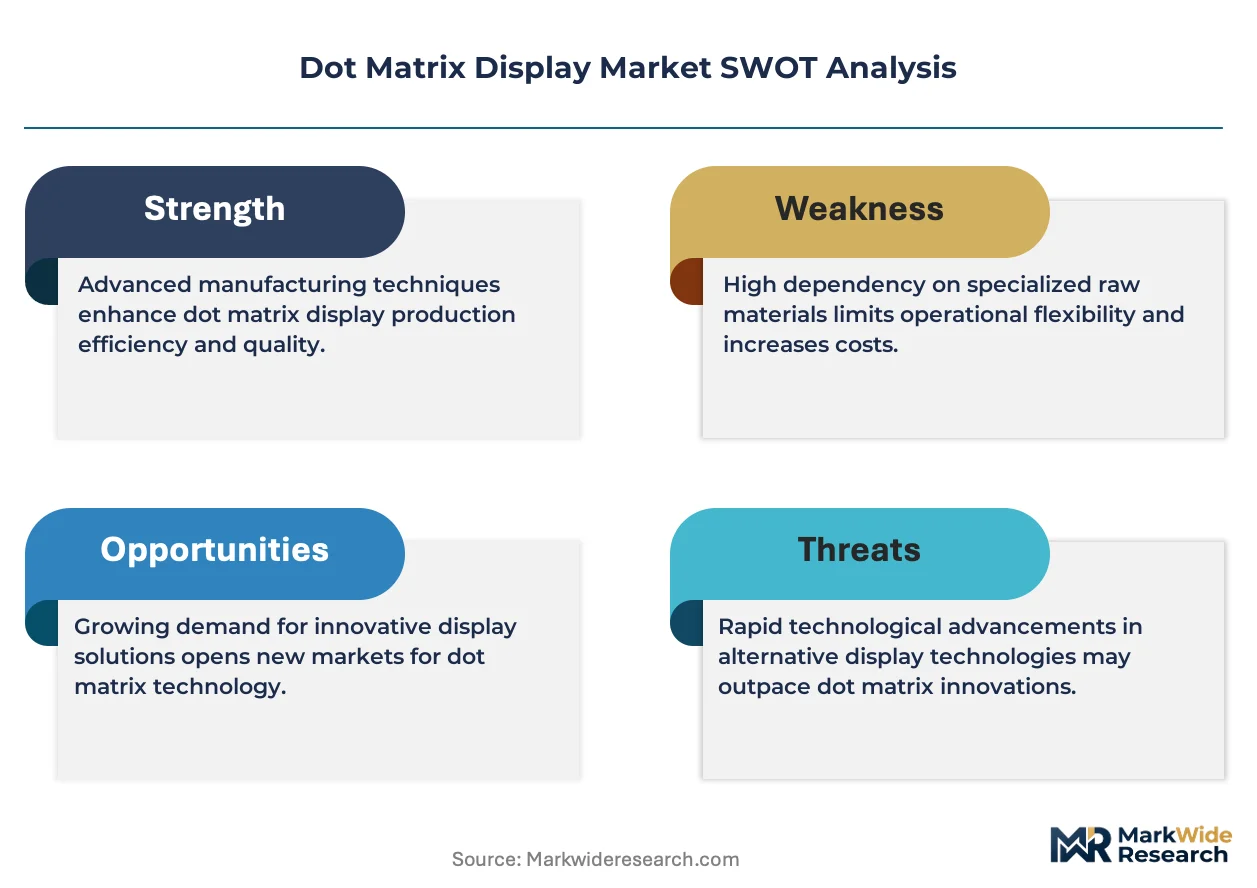
The EU Green Deal is decoupling dot matrix display procurement from legacy energy-intensive designs across European industrial buyers. Samsung Electronics leverages in-house semiconductor production to sustain cost advantages in LED matrix modules. BOE Technology Group anchors its position through captive glass substrate supply and scale manufacturing in China. Panasonic Corporation differentiates via specialized ruggedized displays for factory floor environments.
A dot matrix display arranges pixels in a grid formation where individual elements activate to form characters, symbols, or graphics, typically employing LED or LCD technologies with driver ICs scanning rows and columns at refresh rates of 60-120 Hz for persistent visual output. Industrial control panels and ticketing systems represent mature volume segments with stable replacement cycles, while advertising displays command premium pricing for multicolor outdoor-rated units. LED technology dominates manufacturing scale and cost structure, though OLED dot matrix configurations are gaining traction in miniature display applications requiring high contrast ratios.
REACH and RoHS frameworks in Europe restrict hazardous substances in display electronics, compelling component redesigns and supply chain audits for market access. China's GB standards and MIIT regulations mandate electromagnetic compatibility testing for networked display installations in transportation infrastructure. The US FCC certifies RF emissions from wireless-connected dot matrix signage in retail and sports venues. Stakeholders must weigh regional certification burdens against localized production incentives when configuring manufacturing footprints.
Market Dynamics
Industrial automation's push toward energy-efficient human-machine interfaces is compressing replacement cycles for legacy cathode ray tube and vacuum fluorescent displays across factory floors worldwide.
Growth Catalysts
- EU Green Deal ecodesign mandates:European manufacturers must phase out high-consumption display technologies in industrial equipment, creating replacement demand for low-power LED matrix alternatives.
- Factory automation densification:Automotive and electronics manufacturing lines in Germany and Japan are deploying ruggedized dot matrix panels for real-time production monitoring at workstation density levels previously unsupported.
- Transportation infrastructure digitization:Railway stations, airports, and bus terminals across India and China are installing networked passenger information displays with GB standard electromagnetic compatibility certification.
Market Restraints
- Driver IC supply concentration:Taiwan and South Korea foundries control critical semiconductor components for LED matrix scanning circuits, exposing display assemblers to foundry allocation volatility.
- LCD panel price erosion:Mass-produced thin-film transistor LCD modules for consumer electronics are undercutting industrial-grade dot matrix pricing in cost-sensitive signage applications.
- REACH substance restrictions:ECHA's evolving candidate list of substances of very high concern forces iterative redesign of display housings, solder materials, and backlight components for European market access.
Strategic Opportunities
- India transportation modernization:Metro rail expansions in Delhi, Mumbai, and Bangalore are tendering large-format passenger information display systems with localized content management requirements.
- OLED miniature integration:Wearable medical devices and handheld instrumentation are converging organic light-emitting diode dot matrix technology with flexible substrate manufacturing for high-contrast portable readouts.
- US IRA clean manufacturing incentives:Domestic production credits for energy-efficient industrial equipment are attracting display module assembly investment to serve North American automation OEMs.
Industry Challenges
- Embedded firmware expertise scarcity:Industrial display vendors struggle to recruit engineers proficient in real-time operating systems and low-level driver development for legacy protocol compatibility.
- Multi-jurisdiction certification sequencing:FCC, CE marking, and GB standard testing for wireless-connected signage creates 6-12 month product launch timelines that compress competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dot Matrix Display Market |
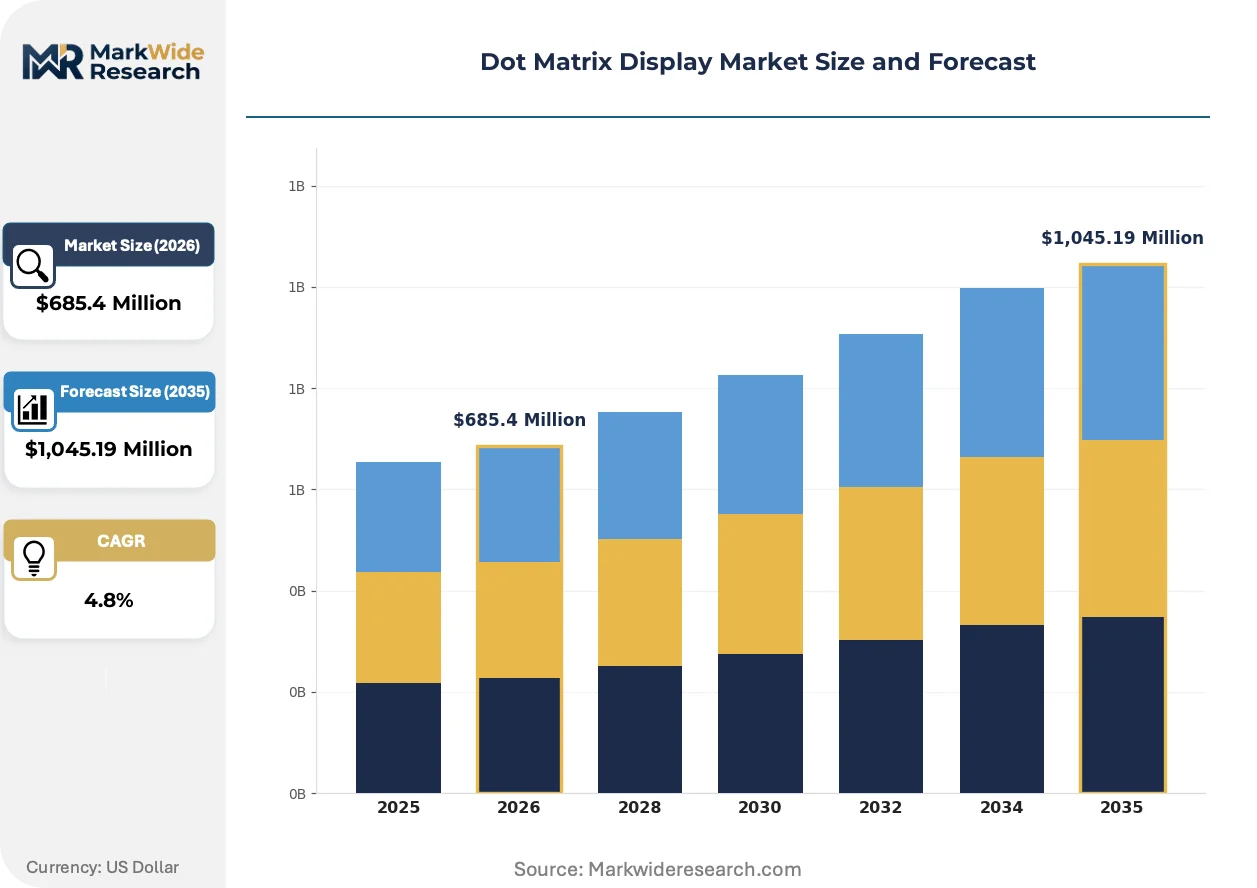
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, Miniature Display Application: Scoreboards, Advertising Displays, Industrial Control Panels, Ticketing Systems End User: Retail, Transportation, Manufacturing, Sports Technology: Single Color, Multicolor, Analog, Digital |
| Companies Covered | Samsung Electronics, LG Display, BOE Technology Group, AU Optronics Corporation, Sony Corporation, Panasonic Corporation, Sharp Corporation, TCL China Star Optoelectronics Technology, Innolux Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dot Matrix Display Market Shifts & Advancements
Active matrix addressing architectures and solid-state illumination sources are displacing passive multiplexed designs across premium industrial segments, while regulatory pressure on operating power consumption accelerates technology turnover.
Chip-on-glass driver integration is overtaking traditional tape-automated bonding interconnection methods in mid-size industrial panels. Semiconductor manufacturers are embedding row and column drivers directly onto the glass substrate edge, reducing module thickness and improving vibration resistance for factory floor deployments. This integration is overtaking conventional flex-cable assembly approaches in applications above 5-inch diagonal, compressing bill-of-material costs and enabling narrower display bezels for space-constrained control enclosures.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of flame-retardant plastics in display housings sold into European industrial markets. ECHA's 2023 updates to restricted substance thresholds compelled resin suppliers to develop halogen-free alternatives with equivalent UL94 V-0 ratings. German automotive production equipment manufacturers are absorbing these material cost premiums while pushing Asian molders to accelerate certified compound availability.
Specification consolidation among systems integrators is compressing vendor diversity in mature industrial segments. Large automation OEMs in Japan and Germany are reducing qualified supplier lists for human-machine interface components, favoring display vendors with captive semiconductor sourcing and multi-continent technical support footprints. This concentration is most visible in semiconductor fabrication equipment, where tool builders require 15-year component availability guarantees that eliminate smaller module assemblers from consideration.
Dot Matrix Display Market Segmentation
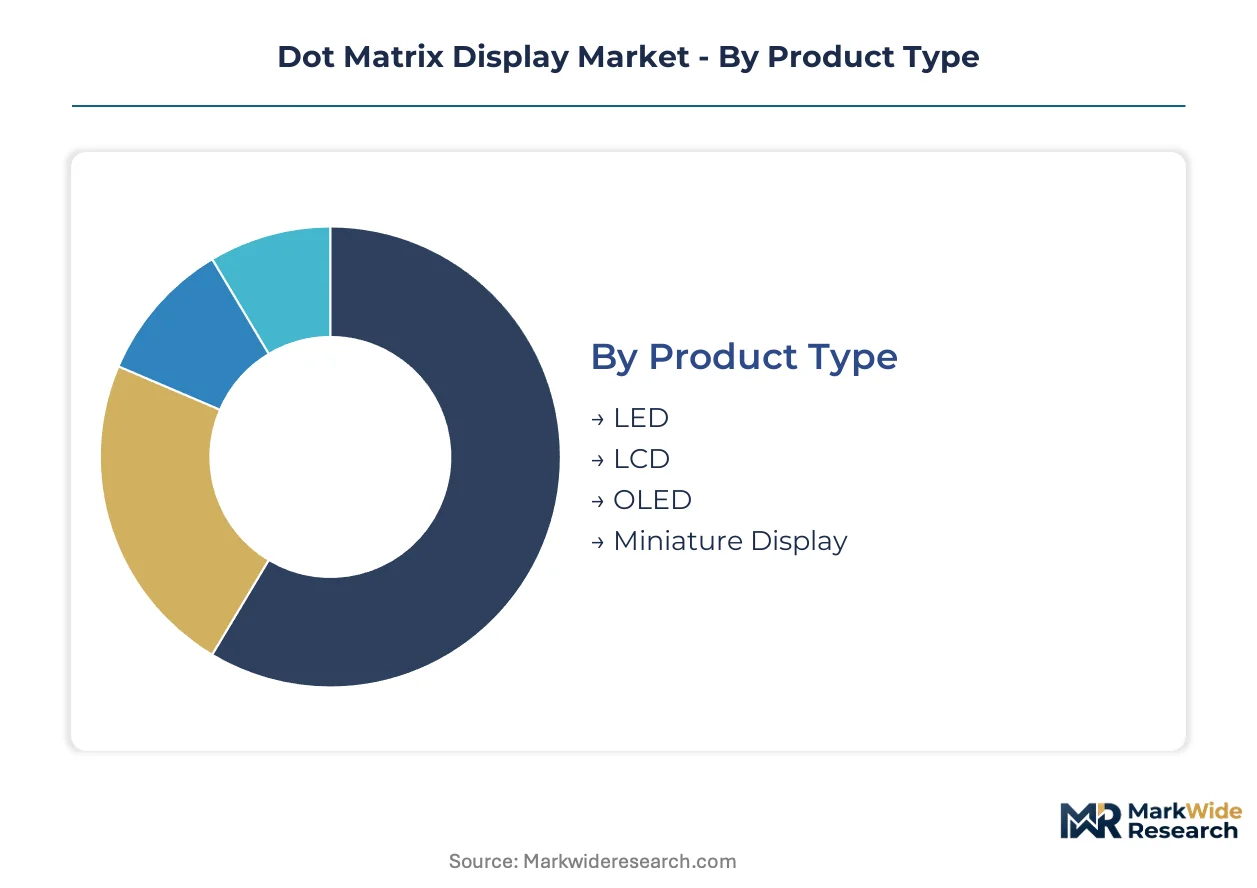
Dot matrix display procurement splits across incompatible technical specifications, regulatory certification requirements, and environmental operating conditions. Segment boundaries determine qualified vendor pools, replacement cycle timing, and margin structures for component suppliers.
Product Type:
Upgrade cycles from legacy cathode ray tube and vacuum fluorescent displays create divergent replacement timelines across display technologies.
- LED:Semiconductor-based illumination with 50,000-100,000 hour operational lifespan dominates factory floor and outdoor signage applications. German automotive production equipment manufacturers specify LED matrix panels for workstation-level human-machine interfaces under EU Green Deal ecodesign mandates phasing out higher-consumption alternatives.
- LCD:Thin-film transistor liquid crystal configurations with LED backlighting occupy cost-sensitive indoor ticketing and retail price display segments. Mass-produced consumer electronics panels from Chinese glass substrate fabs are compressing pricing for industrial-grade alternatives in India railway station passenger information systems.
- OLED:Organic electroluminescent layers enable sub-millimeter module thickness for wearable medical instrumentation and handheld test equipment.
- Miniature Display:Sub-2-inch diagonal configurations with integrated driver ASICs serve portable instrumentation requiring low power draw and wide viewing angles.
Volume placements concentrate in LED configurations; the faster expansion belongs to OLED miniature formats.
Application:
Operating environment severity and connectivity requirements separate premium-specified segments from commodity replacement markets.
- Industrial Control Panels:Ruggedized enclosures with IP65+ sealing and vibration-rated driver IC mounting serve factory automation OEMs in Japan and Germany. Panasonic Corporation specializes in these deployments, qualifying modules for 15-year component availability guarantees demanded by semiconductor fabrication equipment builders.
- Advertising Displays:Outdoor-rated multicolor LED matrices with wireless content management and FCC-certified RF emissions command pricing premiums for retail and sports venue installations. US IRA clean manufacturing incentives are attracting module assembly investment to serve North American digital signage integrators.
- Scoreboards:Large-format monochrome or limited-color configurations with remote diagnostics for stadium and arena operators.
- Ticketing Systems:Compact alphanumeric displays with serial protocol compatibility for legacy railway and bus terminal infrastructure.
Industrial control panels generate the steadiest replacement demand; advertising displays carry the highest average selling prices.
End User:
Procurement authority centralization and technical specification complexity vary sharply across buyer categories.
- Manufacturing:Automation OEMs and systems integrators in Germany and Japan consolidate qualified supplier lists, favoring vendors with captive semiconductor sourcing and multi-continent technical support. Specification consolidation is eliminating smaller module assemblers from consideration in semiconductor fabrication equipment.
- Transportation:Metro rail authorities in Delhi, Mumbai, and Bangalore tender passenger information display systems with localized content management and GB standard electromagnetic compatibility certification requirements.
- Retail:Price-sensitive deployments of basic alphanumeric displays for point-of-sale and inventory management.
- Sports:Venue operators requiring outdoor-rated wireless-connected signage with FCC certification for real-time score and advertising content.
Manufacturing buyers enforce the strictest qualification protocols; transportation authorities are expanding tender volumes most aggressively.
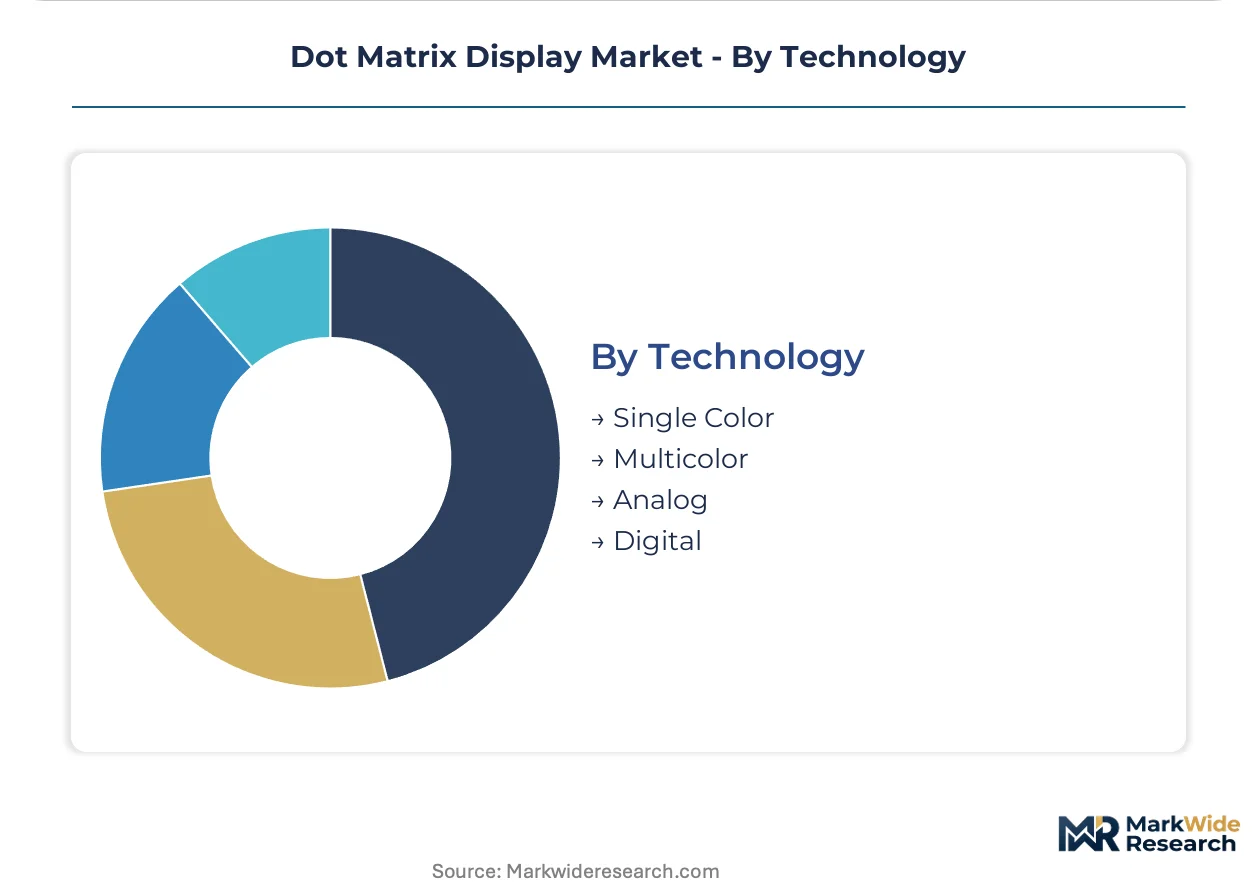
Technology:
Addressing architecture and color capability determine driver IC complexity and manufacturing cost structures.
- Multicolor:Separate red, green, and blue LED dice or OLED subpixels with individual current control enable full-color graphics and video playback. Active matrix addressing with embedded row and column drivers is displacing passive multiplexed designs in premium industrial segments.
- Digital:Binary input signal processing with microcontroller-based refresh control simplifies integration with modern industrial networks.
- Single Color:Monochrome LED or LCD configurations with reduced driver channel count for basic alphanumeric readouts in cost-constrained applications.
- Analog:Voltage-level input signaling for legacy equipment retrofit compatibility in mature industrial installations.
Multicolor configurations command the widest specification premiums; digital addressing is displacing analog interfaces fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors industrial dot matrix display procurement through its dense concentration of automotive production equipment manufacturers and factory automation integrators demanding ruggedized human-machine interfaces.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify LED matrix panels for workstation-level production monitoring. EU Green Deal ecodesign mandates from Brussels accelerate phase-out of vacuum fluorescent displays across Munich and Stuttgart industrial corridors. Siemens and Bosch automation divisions in Nuremberg consolidate qualified supplier lists for 15-year component availability guarantees.
China
MIIT electromagnetic compatibility certification requirements govern networked passenger information displays across Beijing and Shanghai metro expansions. GB standards enforcement compels driver IC redesigns for railway station installations in Guangzhou and Shenzhen. BOE Technology Group leverages captive glass substrate supply from Hefei and Beijing fabs to compress module costs for domestic transportation tenders.
United States
IRA clean manufacturing incentives attract display module assembly investment to serve North American automation OEMs. FCC certifies RF emissions from wireless-connected signage in Dallas sports venues and Chicago retail districts. Detroit automotive production equipment builders specify ruggedized panels for factory floor human-machine interfaces under OSHA workplace safety frameworks.
Japan
METI industrial efficiency programs promote LED matrix adoption in Nagoya automotive manufacturing lines and Osaka electronics assembly plants. JIS standards govern vibration resistance specifications for semiconductor fabrication equipment displays in Tokyo and Yokohama clusters. Panasonic Corporation specializes in ruggedized deployments qualifying for extended component availability guarantees demanded by tool builders.
India
Metro rail expansions in Delhi, Mumbai, and Bangalore tender large-format passenger information display systems with localized content management requirements. BIS certification mandates electromagnetic compatibility testing for networked installations under CEA grid integration rules. PLI scheme incentives for electronics manufacturing attract module assembly investment to serve domestic transportation infrastructure modernization.
Dot Matrix Display Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and captive semiconductor sourcing. The vendor base stratifies into three tiers: diversified electronics conglomerates with in-house driver IC production, specialized display module assemblers dependent on external foundry supply, and regional fabricators serving cost-constrained replacement markets. Competitive moves concentrate on backward integration into semiconductor components and multi-continent technical support footprint expansion.
Within the diversified conglomerate tier, Samsung Electronics and LG Display exemplify players leveraging captive semiconductor production to sustain cost advantages in LED matrix modules. BOE Technology Group anchors the scale-manufacturing archetype through upstream control over glass substrate supply. Panasonic Corporation occupies a position representing specialized ruggedization expertise for factory floor deployments.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| BOE Technology Group |
| AU Optronics Corporation |
| Sony Corporation |
| Panasonic Corporation |
| Sharp Corporation |
| TCL China Star Optoelectronics Technology |
| Innolux Corporation |
| Others |
Supply & Pricing Matrix
Chip-on-glass driver integration is compressing module thickness and assembly labor simultaneously, concentrating cost advantages among display vendors with captive semiconductor fabrication while forcing dependent assemblers toward thinner margins. This manufacturing-method transition feeds back into procurement patterns, as German automotive OEMs and Japanese semiconductor equipment builders now mandate integrated driver architectures for new human-machine interface qualifications.
Pricing Analysis
Uptime guarantees and 15-year component availability commitments anchor value-based pricing for industrial control panel displays. Pricing stratifies across premium ruggedized tiers with IP65+ sealing and extended-life driver ICs, standard industrial-grade modules for indoor factory floors, and economy alphanumeric configurations for basic ticketing systems. Cost compression in the economy tier intensifies because mass-produced Chinese LCD panels are undercutting dedicated dot matrix alternatives in India's railway station tenders. Transportation authorities exhibit the highest price sensitivity due to tender-based procurement, while semiconductor fabrication equipment builders accept substantial premiums for availability guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries controlling LED matrix driver IC production. Display module assembly draws from Chinese glass substrate fabs, Japanese precision equipment suppliers, and German automotive qualification laboratories. Tariff exposure on semiconductor components represents the dominant structural risk as trade policy shifts affect foundry allocation priorities. Distribution runs through direct OEM relationships for industrial control panels and systems integrator networks for transportation infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dot matrix display sector is executing a technology-transition phase as active matrix addressing architectures displace passive multiplexed designs across premium industrial segments. LED and OLED configurations are systematically replacing legacy cathode ray tube and vacuum fluorescent displays under regulatory pressure from EU Green Deal ecodesign mandates.
For Market Incumbents: Acquire captive driver IC design capabilities to secure foundry allocation priority against Taiwan and South Korea supply concentration. Incumbent vendors must deepen backward integration into semiconductor components while expanding multi-continent technical support footprints to meet German and Japanese automation OEM supplier consolidation requirements. The threat of LCD panel price erosion in cost-sensitive signage applications demands defensive certification investment in REACH-compliant halogen-free housing materials. For New Entrants and Emerging Players: IRA clean manufacturing incentives in the United States open a window for domestic module assembly investment serving North American automation OEMs. New entrants should penetrate the India transportation modernization segment through localized content management partnerships with Delhi, Mumbai, and Bangalore metro authorities. A regulatory-compliant go-to-market angle emphasizing BIS electromagnetic compatibility certification and PLI scheme qualification accelerates tender access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electronics conglomerates seeking captive semiconductor sourcing. Long-term viability favors vendors with upstream control over glass substrate supply and in-house driver IC production capacity. The signal to watch is foundry allocation volatility for LED matrix scanning circuits, which would accelerate consolidation among dependent module assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Captive semiconductor production insulates against Taiwan and South Korea foundry allocation volatility. |
| Multi-Continent Technical Support Expansion | German and Japanese automation OEMs mandate 15-year availability guarantees eliminating smaller assemblers. |
| REACH-Compliant Material Reformulation | ECHA halogen-free housing requirements secure European industrial market access against regulatory exclusion. |
| Localized Module Assembly Investment | US IRA clean manufacturing credits attract production capacity to serve domestic automation OEM demand. |
| Active Matrix Addressing Architecture Migration | Premium industrial segments displace passive multiplexed designs under EU Green Deal power consumption pressure. |
Research Methodology
Document review covered regulatory filings with ECHA, FCC equipment authorization databases, and MIIT electromagnetic compatibility certifications, complemented by interviews with display module procurement directors at German automotive OEMs, Japanese semiconductor fabrication equipment builders, and India metro rail project engineers. Secondary validation drew from EU Green Deal implementation guidance, GB standards documentation, and industrial automation trade association technical specifications. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification of volume and value estimates.
Historical shipment data cross-referenced against panel input from driver IC suppliers and glass substrate manufacturers established baseline trajectories. Segmentation dimensions modeled include display technology type, addressing architecture, application environment severity, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis of legacy cathode ray tube and vacuum fluorescent displays overlaid with EU ecodesign mandate phase-out schedules. Industry-specific inputs incorporated foundry capacity allocation patterns and REACH substance restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for OLED miniature integration in wearable medical devices would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency, foundry capacity expansion rates, and India transportation infrastructure tender execution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Material Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Smart Display Market
Display Technologies
Global Display Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
OLED Panel Market
Display Technologies
Global Transparent Display Market
Display Technologies
Computer Monitor Market
Display Technologies
North America Industrial Display Market
Display Technologies
Field Emission Display Market
Display Technologies
Display Control and Management System Market
Display Technologies
Electrochromic Window Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Industrial Display Market