
 3D Projector Market | 2026-2036
3D Projector Market Size, Share, and Industry Trends Forecast 2026-2036
3D Projector Market Intelligence
Leasing and projector-as-a-service models is fragmenting the competitive landscape by lowering capital barriers for mid-sized cinema operators and corporate buyers. Sony Corporation leverages its cinema-grade SXRD panel technology to anchor premium theatrical deployments worldwide. Seiko Epson Corporation sustains dominance in education and museum verticals through high-brightness 3LCD platforms with low total cost of ownership. Optoma Corporation competes aggressively on price-performance in home theater and simulation segments with compact DLP architectures.
A 3D projector is an optical display engine that modulates light through digital micromirror devices (DLP), liquid crystal panels (LCD/LCOS), or laser-phosphor solid-state illumination to render stereoscopic imagery via active shutter or passive polarization glasses, with brightness ratings typically spanning 2,000 to 50,000 lumens depending on venue scale. Its primary commercial purpose is delivering immersive visual experiences for entertainment, training, and public exhibition where depth perception enhances engagement or operational fidelity. DLP technology leads in cinema and simulation applications where high contrast and frame-sequential 3D precision matter most, while laser projection represents the fastest-expanding light source category as venues retire mercury lamp inventories. Museum exhibits and theme parks concentrate margin pools because these end users prioritize color accuracy and reliability over unit cost.
FCC equipment authorization rules in the United States govern radio-frequency emissions from wireless-enabled projectors, while the EU F-Gas Regulation and RoHS directives restrict hazardous substances and fluorinated greenhouse gases in laser-illuminated units sold across Europe. EMA and national health regulators indirectly shape demand by certifying simulation systems for surgical training, which embeds 3D projection as a validated instructional component. Stakeholders must monitor how evolving energy efficiency standards and right-to-repair legislation affect hardware refresh cycles and aftermarket service economics.
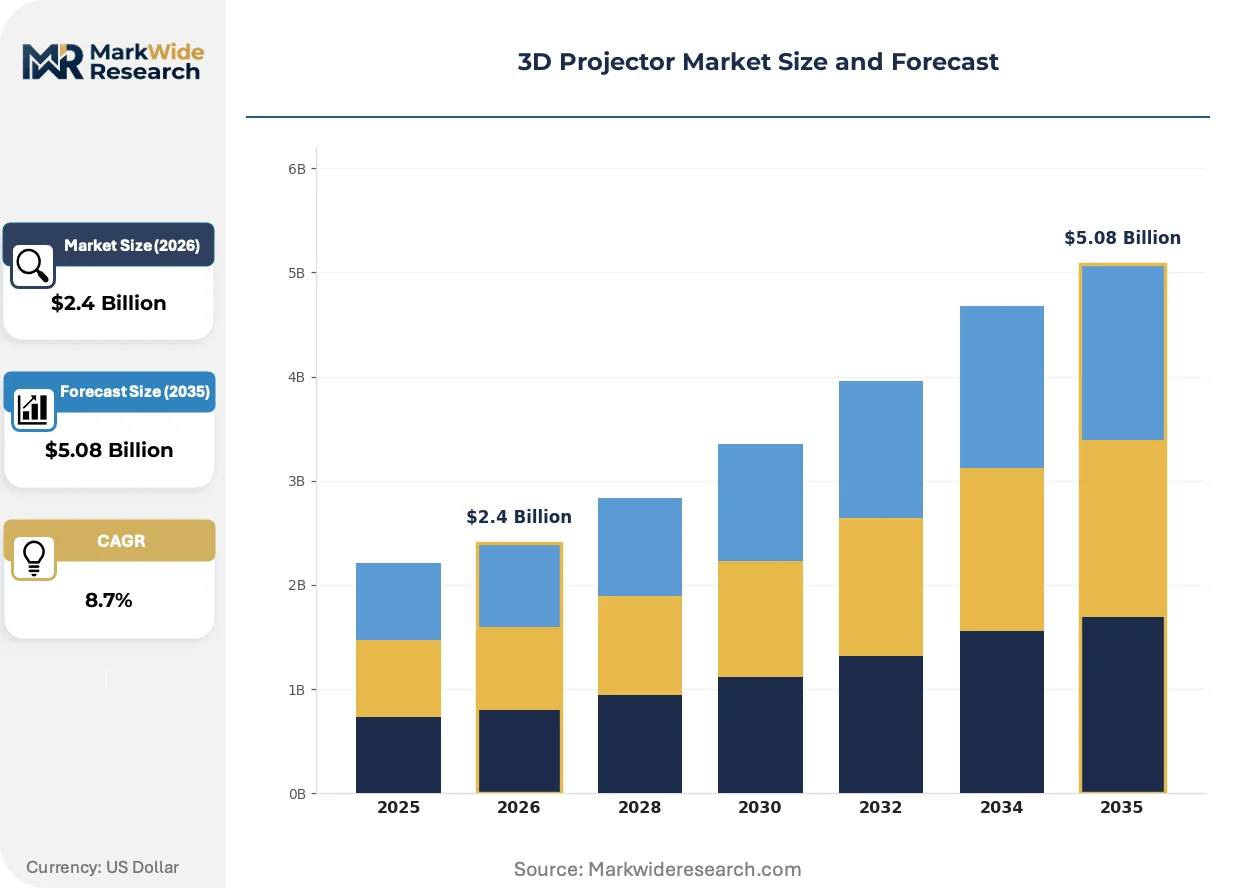
Market Dynamics
Laser-phosphor solid-state illumination is collapsing the installed base of mercury lamp projectors as venue operators face simultaneous pressure from energy efficiency mandates and total cost-of-ownership scrutiny. This technology transition reconfigures supplier relationships, service revenue models, and buyer procurement criteria across cinema, simulation, and exhibition verticals.
Growth Catalysts
- China's dual carbon goals under MEE:National energy intensity targets force public venues and commercial exhibitors to retire lamp-based systems, accelerating replacement demand for laser-illuminated 3D projectors in multiplex chains and museum complexes.
- Defense and aviation simulation centers:Training fidelity requirements in Germany, the United Kingdom, and France sustain procurement of high-brightness stereoscopic projection for mission-critical rehearsal environments.
- Leasing and projector-as-a-service models:Capital barrier reduction enables mid-sized cinema operators and corporate buyers to access premium 3D projection without upfront hardware acquisition.
Market Restraints
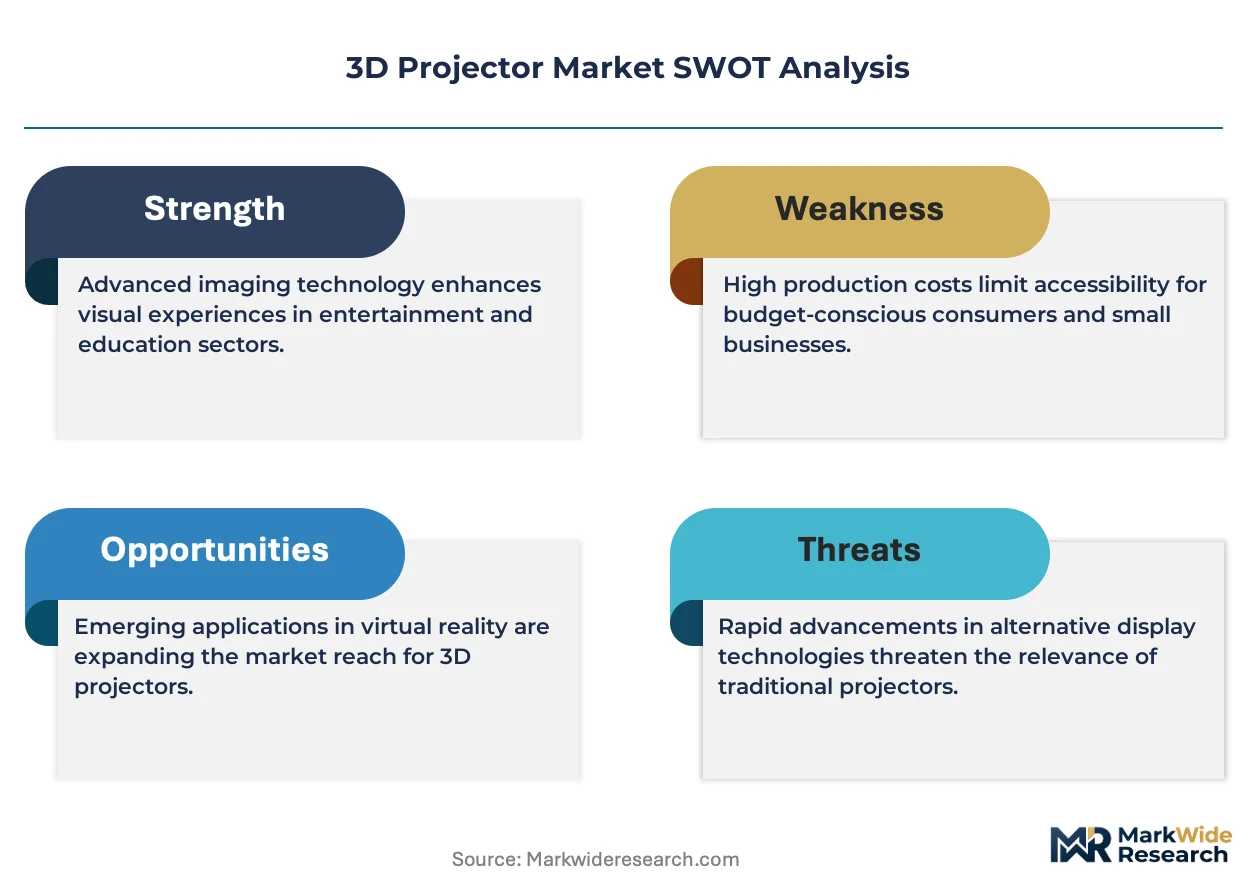
- Laser diode supply concentration:Solid-state illumination engines depend on specialized semiconductor foundries concentrated in East Asia, creating vulnerability to input bottlenecks and price volatility.
- EU F-Gas Regulation compliance costs:Restrictions on fluorinated greenhouse gases in laser-illuminated units sold across Europe impose certification burdens and design constraints on manufacturers serving that market.
- Active shutter glasses ecosystem dependency:Frame-sequential 3D systems require synchronized eyewear supply chains subject to radio-frequency emission regulations including FCC equipment authorization in the United States.
Strategic Opportunities
- Underpenetrated Indian cinema infrastructure:Multiplex operators expanding 3D screen counts present volume opportunity for projection hardware vendors with localized service networks.
- EMA-certified surgical simulation systems:Regulatory validation of 3D projection as an instructional component in medical training creates defensible niche demand with premium pricing tolerance.
- Laser-3LCD convergence:Hybrid solid-state illumination with three-panel liquid crystal architectures enables new performance tiers in education and museum verticals previously dominated by lamp-based alternatives.
Industry Challenges
- Optical calibration specialist scarcity:Stereoscopic alignment and colorimetric certification require technicians with cross-disciplinary expertise in photonics and display metrology that outpaces vocational training pipeline output.
- Legacy DLP inventory integration:Frame-sequential 3D systems face compatibility friction when interfacing with newer polarization-based passive glasses infrastructure in renovated exhibition spaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Projector Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Projection Technology: DLP, LCD, Laser, LED, LCOS Application: Home Theater, Education, Corporate Training, Simulation, Museum Exhibits End User: Cinemas, Schools, Corporate Offices, Simulation Centers, Theme Parks Connectivity Type: HDMI, USB, VGA, Wi-Fi, Bluetooth |
| Companies Covered | Sony Corporation, Seiko Epson Corporation, Panasonic Corporation, Optoma Corporation, BenQ Corporation, ViewSonic Corporation, Barco, Acer Inc., NEC Display Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Projector Market Strategic Shifts & Innovations
Solid-state illumination architectures and wireless content distribution protocols are compressing hardware refresh cycles while fragmenting traditional vendor-customer relationships. These forces reshape how projection technology is specified, procured, and maintained across venue types.
RGB laser light engines with discrete red, green, and blue diode arrays are collapsing the brightness-per-watt economics that previously favored lamp-based systems in large-venue deployments. Cinema exhibitors in premium multiplex configurations adopt these engines fastest, with museum and theme park operators following as maintenance cost differentials compound. The structural consequence compresses aftermarket lamp revenue pools while shifting margin capture toward semiconductor suppliers and thermal management subsystem vendors.
The EU F-Gas Regulation and RoHS directives restrict hazardous substances and fluorinated greenhouse gases in laser-illuminated units sold across Europe, forcing redesign of cooling systems and sealing architectures. Manufacturers serving European markets must requalify thermal pathways and refrigerant alternatives, adding six to eighteen months to product launch timelines. Simulation system integrators in Germany and France report procurement delays as they await certified hardware variants compliant with these phased restrictions.
Subscription-based hardware access with bundled maintenance and content licensing is displacing outright purchase in mid-market corporate and education segments. Systems integrators and regional AV distributors now compete directly with manufacturer-direct service arms for recurring revenue relationships. This pattern concentrates in North American and Western European markets where IT procurement departments prefer operational expenditure classification for display infrastructure.
3D Projector Market Segmentation
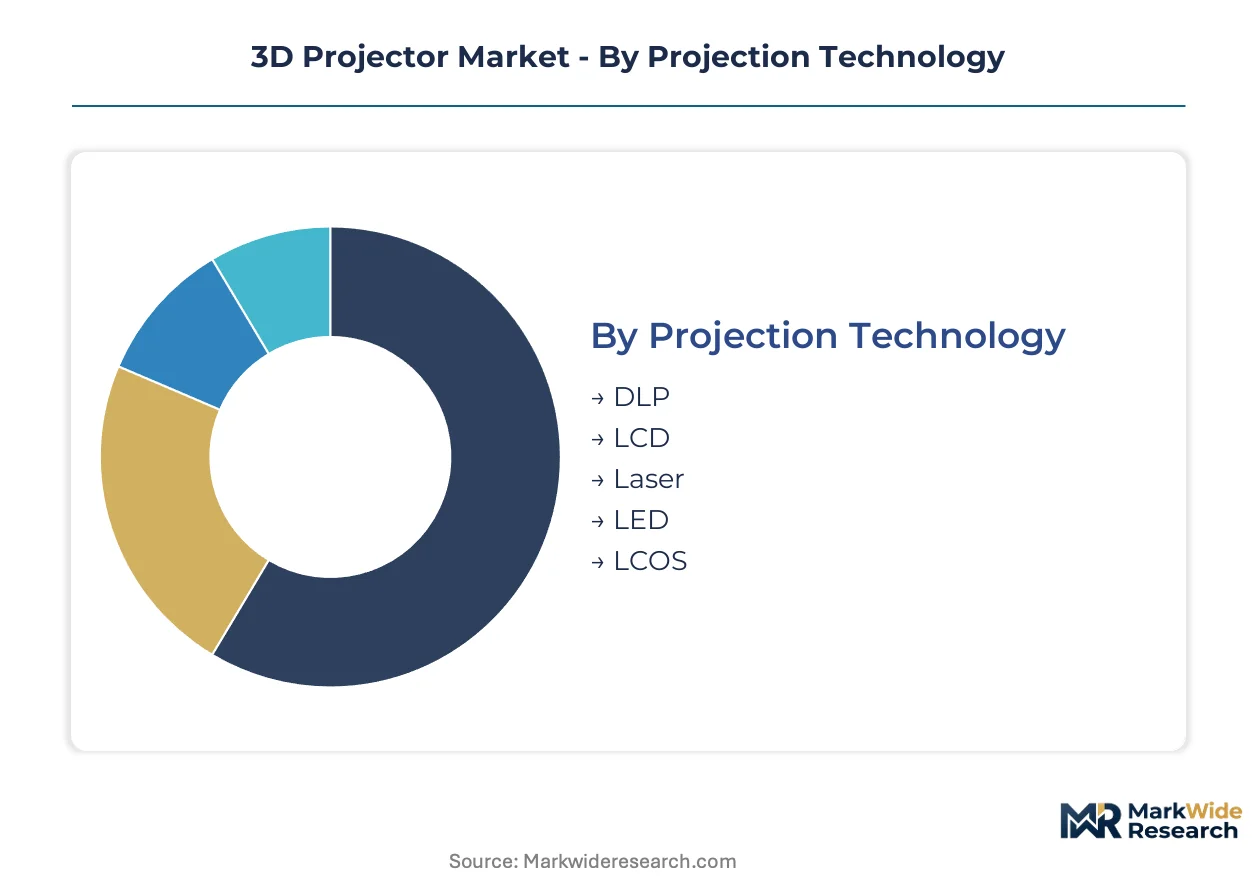
Segmentation in the 3D projector market reveals distinct service intensity profiles across technologies and end uses. Cinema and simulation deployments demand specialized calibration support, while education and corporate segments prioritize swap-out simplicity over technical intervention.
Projection Technology:
After-sales service intensity varies sharply by illumination architecture and panel complexity, with laser-phosphor systems requiring thermal management expertise that lamp-based units never needed.
- Laser:Solid-state illumination with discrete diode arrays eliminates lamp replacement cycles but demands specialized thermal pathway maintenance and phosphor wheel refurbishment. Cinema exhibitors in India and China concentrate procurement here as energy efficiency mandates accelerate mercury lamp retirement.
- DLP:Digital micromirror devices with frame-sequential 3D precision dominate simulation centers in Germany and the United Kingdom where contrast ratios and motion fidelity are non-negotiable. The sealed optical engine reduces particulate contamination service calls compared to LCD alternatives.
- LCD:Three-panel liquid crystal architectures sustain Epson's grip on education and museum verticals through color brightness advantages and lower unit economics. Dust filter maintenance and polarizer degradation drive predictable service schedules.
- LCOS:Liquid crystal on silicon enables highest native resolution for premium home theater and medical visualization with reflective panel technology requiring precision alignment during installation.
- LED:Discrete RGB LED arrays serve compact portable applications and entry-level home theater with minimal thermal management but limited brightness headroom for large venues.
Laser holds the largest share; momentum sits with DLP in mission-critical training environments.
Application:
Cost tier stratification separates capital-intensive permanent installations from refresh-cycle-sensitive provisional deployments.
- Simulation:Defense and aviation training systems in France and the United Kingdom require stereoscopic alignment certification and continuous colorimetric validation. EMA regulatory recognition for surgical rehearsal applications sustains premium pricing tolerance.
- Cinema:Multiplex operators face simultaneous pressure from China's MEE carbon intensity targets and total cost-of-ownership scrutiny, compressing lamp inventory replacement timelines.
- Museum Exhibits:Color accuracy and 24/7 reliability priorities concentrate margin pools here despite lower unit volumes than education or corporate segments.
- Education:High-brightness 3LCD platforms dominate through low total cost of ownership and standardized mounting infrastructure across K-12 and higher education facilities.
- Home Theater:Price-performance competition from Optoma and compact DLP architectures fragment vendor relationships in consumer channels.
Simulation commands premium service attach rates; museum exhibits are climbing fastest on cultural infrastructure investment.
End User:
Customer type determines procurement modality, with leasing and projector-as-a-service models penetrating mid-sized operators previously excluded from premium hardware access.
- Cinemas:Multiplex chains in India expand 3D screen counts while negotiating service-level agreements that bundle maintenance with content licensing.
- Simulation Centers:Mission-critical rehearsal environments in Germany and France sustain direct manufacturer relationships bypassing traditional distribution.
- Theme Parks:Outdoor and high-ambient-light installations demand IP-rated sealing and rapid-response service networks.
- Schools:Bulk procurement through regional education authorities favors standardized 3LCD platforms with swap-unit logistics.
- Corporate Offices:IT procurement departments prefer operational expenditure classification, accelerating subscription-based hardware access in North American and Western European markets.
Cinemas represent the largest installed base; simulation centers are gaining share fastest on defense training budgets.
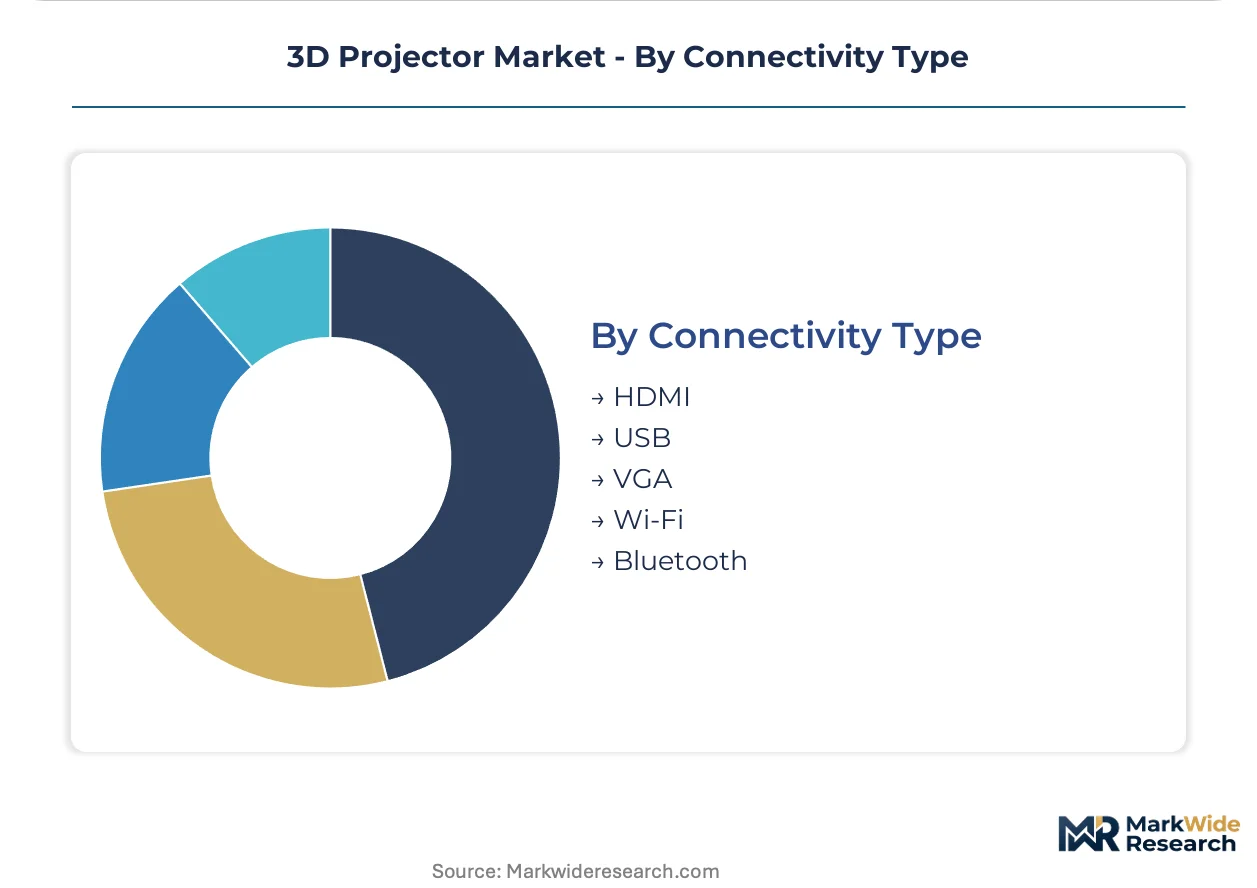
Connectivity Type:
Volume concentration in wireless protocols is displacing legacy wired infrastructure, though regulatory fragmentation complicates radio-frequency certification.
- HDMI:Remains the dominant physical interface for 4K and high-frame-rate 3D content distribution in cinema and simulation.
- Wi-Fi:Wireless content streaming enables flexible corporate and education deployments but triggers FCC equipment authorization requirements in the United States.
- Bluetooth:Synchronized active shutter glasses and peripheral control dominate home theater and museum interactive exhibits.
- USB:Direct media playback and firmware update pathways persist in education and portable applications.
- VGA:Legacy analog support lingers in institutional refresh cycles where full infrastructure replacement is capital-constrained.
HDMI retains the largest share; Wi-Fi is expanding most quickly on flexible deployment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in projection hardware tilt toward net importing in Western Europe and North America, while East Asian manufacturing clusters supply laser diode engines and DLP chipsets to assembly facilities worldwide. Currency volatility and shipping cost fluctuations are compressing margin structures for distributors serving secondary markets.
China
MEE dual carbon mandates are forcing multiplex chains and museum complexes to retire mercury lamp inventories at accelerated rates. MIIT energy efficiency standards for commercial display equipment now require laser-phosphor illumination in new public venue installations. Manufacturing concentrates in the Yangtze River Delta, where Shenzhen-based integrators are scaling RGB laser engine production for domestic cinema retrofit programs.
United States
FCC equipment authorization rules govern radio-frequency emissions from wireless-enabled projectors deployed in corporate training centers and museum exhibits. Defense simulation procurement through FAA-certified training facilities sustains demand for high-brightness stereoscopic systems. Installation clusters in Greater Los Angeles and Orlando serve theme park and entertainment production verticals with specialized calibration support networks.
Germany
EU F-Gas Regulation compliance costs are forcing redesign of cooling systems in laser-illuminated units, extending product launch timelines by six to eighteen months. KBA and federal defense procurement channels sustain mission-critical simulation center investments in aviation and tactical rehearsal applications. Industrial concentration in Bavaria and Baden-Württemberg hosts systems integrators serving EMA-certified medical training facilities.
India
Multiplex operators expanding 3D screen counts are driving volume procurement of projection hardware with localized service-level agreements. BIS certification requirements for electronic display equipment are tightening import documentation for laser-illuminated systems. Deployment concentrates in Maharashtra and Karnataka, where Mumbai and Bangalore-based cinema chains negotiate bundled maintenance contracts with hardware vendors.
United Kingdom
RoHS directive restrictions on hazardous substances in laser-illuminated units align with NHS procurement standards for surgical simulation systems. Defense training budgets through the Ministry of Defence sustain stereoscopic projection demand for mission-critical rehearsal environments. London and Southeast England cluster simulation integrators serving aviation and medical certification programs with continuous colorimetric validation requirements.
3D Projector Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in semiconductor and optical subsystems. The vendor base separates into three strata: multinational electronics conglomerates with captive display technology, specialized projection OEMs focused on narrow verticals, and regional AV distributors assembling white-label configurations. Consolidation pressure concentrates in the middle tier as recurring-revenue service models displace transactional hardware sales. Strategic moves cluster on technology licensing partnerships and backward integration into laser diode supply.
Among Japan-based electronics conglomerates, Sony Corporation and Seiko Epson Corporation exemplify divergent platform strategies. Sony anchors premium theatrical deployments through proprietary panel technology, while Epson sustains dominance in education and museum verticals through high-brightness liquid crystal architectures. Optoma Corporation represents the specialized OEM tier, competing aggressively on price-performance in home theater and simulation segments with compact digital micromirror configurations.
| Leading Market Players |
|---|
| Sony Corporation |
| Seiko Epson Corporation |
| Panasonic Corporation |
| Optoma Corporation |
| BenQ Corporation |
| ViewSonic Corporation |
| Barco |
| Acer Inc. |
| NEC Display Solutions |
| Others |
Cost & Logistics Intelligence
Overcapacity in Yangtze River Delta laser engine foundries compresses supplier margins while enabling aggressive pricing postures for downstream integrators serving Indian cinema chains and European simulation centers. This utilization dynamic forces component vendors toward bundled service contracts that recover margin through recurring thermal pathway maintenance rather than upfront hardware premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the 3D projector market. Price differentiation rests on certification grade for EMA-compliant surgical simulation systems and volume scale for multiplex chain procurement in India. Cost compression in mid-brightness education segments is intensifying because Epson and Optoma compete aggressively on total cost-of-ownership metrics. Corporate training departments show least price sensitivity where laser-phosphor reliability justifies premium positioning, while K-12 education authorities remain most sensitive to per-unit capital outlay.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for laser diode sourcing. Manufacturing concentrates in China, Taiwan, and Japan for solid-state illumination engines and DLP chipsets. Raw material dependencies include gallium nitride substrates, rare-earth phosphors, and precision optical glass from German suppliers. Single-source vulnerability in specialized semiconductor foundries creates procurement bottlenecks during capacity constraints. Distribution runs through regional AV integrators in Western Europe and North America, with manufacturer-direct service arms capturing recurring revenue relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D projector market sits in early-cycle expansion as China's MEE dual carbon mandates force accelerated lamp-to-laser replacement timelines across public venue infrastructure.
For Market Incumbents: Pre-empt margin erosion in education verticals by backward integration into laser diode supply partnerships with Yangtze River Delta foundries. Defend against emerging white-label competitors by embedding proprietary thermal management IP into service-level agreements that extend contract duration. For New Entrants and Emerging Players: Pursue underpenetrated Indian cinema infrastructure where multiplex operators seek localized service networks without legacy lamp inventory obligations. Target mid-tier corporate training facilities with subscription-based hardware access models that convert capital expenditure to operational expenditure classification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among simulation system integrators serving EMA-certified medical training facilities with continuous calibration obligations. Long-term viability favors acquisition targets with captive laser-phosphor refurbishment capabilities and established relationships with defense procurement channels in Germany and France. Monitor MIIT energy efficiency standard revisions as inflection signals for replacement demand velocity in China.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Phosphor Platform Migration | MEE carbon mandates in China accelerate mercury lamp retirement across multiplex chains. |
| Projector-as-a-Service Launch | Corporate IT departments in North America prefer operational expenditure classification for display infrastructure. |
| EMA Certification Investment | Surgical simulation systems command premium pricing tolerance through regulatory validation. |
| Regional Service Network Expansion | Indian cinema operators demand localized maintenance capabilities for laser-illuminated deployments. |
| Laser Diode Supply Partnership | Taiwanese and Chinese foundry relationships secure thermal engine availability amid capacity constraints. |
Research Approach
The analysis maps laser-illuminated, DLP, LCD, and LCOS projection architectures, each validated through cinema technology officers, simulation center procurement leads, museum exhibit designers, and education facility managers. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Sony and Epson, MIIT energy efficiency disclosures, EMA certification databases, and Indian BIS import documentation. Bottom-up unit economics triangulated against top-down venue installation counts across China, India, Germany, and the United States.
Assumptions held China's dual carbon enforcement trajectory and laser diode cost curves fixed while varying cinema screen expansion rates and simulation training budget allocations across defense and medical verticals. Segmentation dimensions modeled include illumination technology, application vertical, end-user procurement modality, and regional regulatory cluster. CAGRs derived from installed base turnover analysis and replacement cycle compression in lamp-to-laser transitions. Industry-specific inputs encompassed EMA certification timelines and FCC equipment authorization processing durations.
Sensitivities concentrate around MIIT standard enforcement consistency and laser diode foundry capacity utilization in Taiwan. Forecasts reflect documented assumptions regarding energy efficiency mandate adoption and defense training budget stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Laser Projector Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
EPON ONU Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Laser Projection Market