
 Laser Projector Market | 2026-2036
Laser Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Projector Market Outlook
Optical engineering talent scarcity is reorganizing competitive dynamics across the laser projector industry. Epson leverages its in-house liquid crystal panel fabrication to sustain margin control in the education and corporate segments. Samsung dominates consumer mindshare through its lifestyle-oriented ultra-short-throw designs, while Hisense competes aggressively on laser TV price positioning in North American and European retail channels.
Laser projectors employ coherent light sources—typically semiconductor laser diodes or solid-state laser modules—to generate images through DLP, LCoS, or 3LCD modulation, achieving brightness levels from 2,000 to 60,000 lumens with operational lifespans exceeding 20,000 hours. The technology segment splits between phosphor-based systems, which anchor mainstream brightness-per-dollar economics in business presentation and education, and multicolor RGB architectures, which command premium positioning in cinema and large venue applications where DCI-P3 and Rec. 2020 color accuracy determine procurement decisions. Home theater represents the fastest-expanding application dimension, driven by living-room replacement of flat-panel displays with ambient-light-rejecting laser TV configurations.
FCC equipment authorization requirements in the United States govern laser emission safety classifications for consumer projectors, while CE marking under the EU RoHS and REACH frameworks restricts hazardous substance content in diode manufacturing. China's GB standards, administered by SAMR, mandate specific laser product safety testing that shapes market access for imported and domestic brands alike. Stakeholders must monitor evolving IEC 60825-1 laser safety classification revisions and their downstream impact on product design thresholds and regional certification timelines.
Market Dynamics
The laser projector market is experiencing a fundamental transition from lamp-based to solid-state illumination systems, driven by cinema operators and large-venue operators seeking reduced maintenance cycles and enhanced color reproduction capabilities.
Growth Catalysts
- GB Standards Compliance:China's SAMR-mandated laser safety testing protocols are accelerating domestic manufacturing quality upgrades, creating export-ready supply capacity for global brands.
- RGB Laser Architecture:Multicolor diode packaging advances are extending color gamut performance beyond Rec. 2020 thresholds, enabling premium positioning in cinema and broadcast monitoring applications.
- Home Theater Migration:Living-room replacement of flat-panel displays with ambient-light-rejecting laser TV configurations is generating volume demand in residential segments.
Market Restraints
- Blue Laser Diode Concentration:Nichia and OSRAM control critical gallium nitride epitaxy capacity, creating single-source vulnerability for RGB system manufacturers.
- Phosphor Wheel Thermal Degradation:Phosphor-based systems face luminance decay thresholds that limit operational lifespan in high-duty-cycle commercial deployments.
- IEC 60825-1 Revision Uncertainty:Pending laser safety classification updates are extending product recertification timelines and freezing R&D allocation decisions.
Strategic Opportunities
- India Education Infrastructure:Central government smart classroom initiatives under the Ministry of Education are creating tender-driven volume demand for 3,000-5,000 lumen classroom projectors.
- Automotive HUD Convergence:MEMS scanning mirror integration with compact laser modules is opening augmented reality windshield projection for premium vehicle platforms.
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in cooling systems is favoring laser illumination over lamp-based alternatives in climate-controlled venue applications.
Industry Challenges
- Optical Engineering Talent Scarcity:Waveguide design and coherent beam combination expertise concentrates in Japanese and German research clusters, constraining product development velocity elsewhere.
- DCI Certification Timelines:Digital Cinema Initiatives compliance testing for RGB laser cinema projectors extends 18-24 months, delaying revenue recognition for new platform launches.
- Legacy Protocol Integration:SDI and HDMI 2.1 signal handling requirements complicate firmware architecture for hybrid broadcast-cinema deployment scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Projector Market |
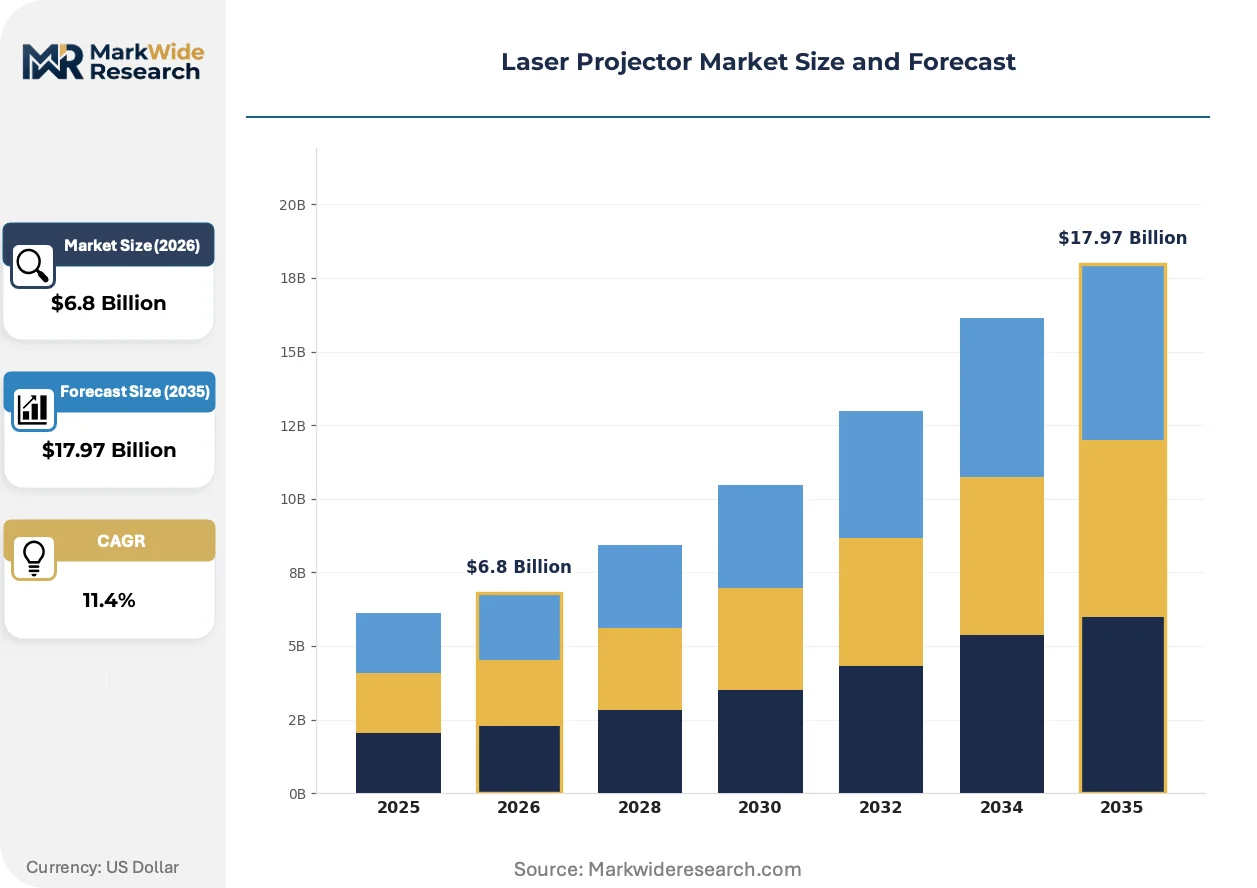
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Theater, Business Presentation, Education, Large Venue Technology: Single-Diode, Multicolor, Hybrid, Phosphor Application: Concerts, Corporate Events, Cinemas, Art Installations End User: Entertainers, Educators, Corporations, Museums |
| Companies Covered | Samsung, Epson, Hisense, NexiGo, TCL, XGIMI, JMGO, Aurzen, AWOL Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Projector Market Strategic Shifts
Active developments across diode packaging, thermal management, and optical modulation are compressing form factors while extending performance envelopes. These shifts are redistributing competitive advantage across the value chain.
Multichip laser diode arrays are miniaturizing. These devices consolidate red, green, and blue emitters into single packages with shared thermal substrates and integrated beam-combining optics. Cinema projector OEMs are adopting them to reduce optical engine volume by 40 percent while maintaining 30,000-lumen output. This compression is enabling ceiling-mount installations in smaller auditorium footprints previously served by lamp-based systems.
REACH substance restrictions are tightening. ECHA's candidate list expansion for SVHCs now covers specific rare-earth phosphors used in yellow-laser conversion wheels. European projector manufacturers are reformulating wheel compositions or shifting to direct-emitting architectures to maintain market access. The regulatory pressure is accelerating RGB adoption in business and education segments where phosphor economics previously dominated.
Subscription-based illumination service models are emerging. Large-venue operators in North America are contracting for lumen-hour delivery rather than capital equipment purchase, transferring diode replacement risk to manufacturers or third-party lessors. This reconfiguration compresses sales cycles for new installations while extending customer lifetime value capture for suppliers with captive service networks.
Laser Projector Market Segmentation
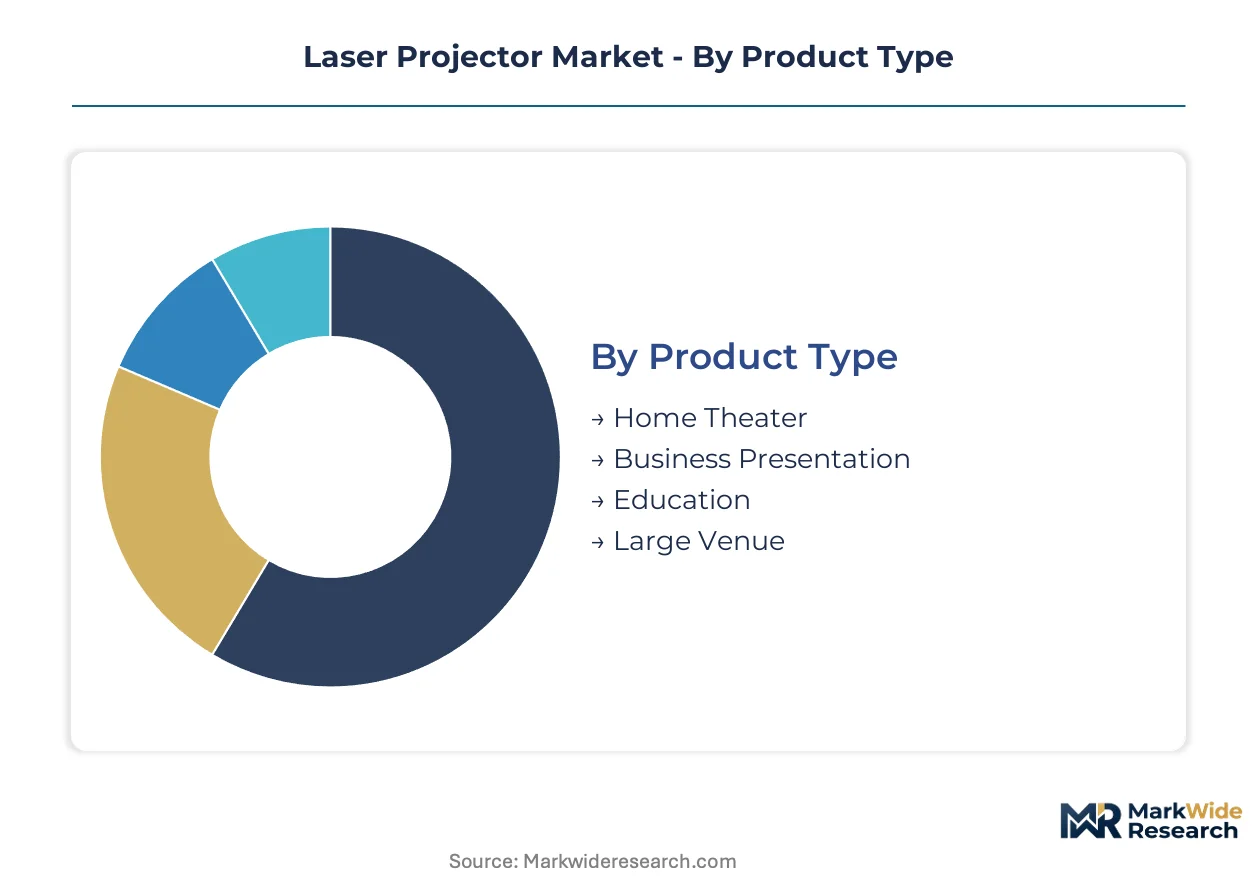
Laser projector procurement decisions diverge sharply across use cases, with brightness thresholds, color gamut requirements, and duty-cycle demands creating distinct specification clusters. Manufacturers configure optical engines, thermal systems, and modulation architectures differently for each segment, preventing platform standardization.
Product Type:
FCC laser safety classifications and CE marking requirements under RoHS and REACH frameworks create divergent compliance burdens across residential, commercial, and institutional deployments.
- Home Theater:Ambient-light-rejecting screen pairings with ultra-short-throw optical engines dominate living-room installations. Demand concentrates in China and the United States where XGIMI, JMGO, and Hisense compete on laser TV price positioning; Samsung's lifestyle-oriented designs sustain premium consumer mindshare through industrial design differentiation.
- Business Presentation:Phosphor-based systems anchor mainstream brightness-per-dollar economics in conference rooms and huddle spaces. Procurement prioritizes 3,000-4,000 lumen output with instant-on reliability; Epson leverages in-house liquid crystal panel fabrication to sustain margin control against DLP competitors.
- Education:India's Ministry of Education smart classroom initiatives generate tender-driven volume demand for 3,000-5,000 lumen classroom projectors with sealed optical engines for dust-prone environments.
- Large Venue:RGB laser architectures command premium positioning where 30,000-60,000 lumen output and DCI-P3 color accuracy determine procurement; cinema operators accelerate lamp-to-laser replacement cycles.
Business Presentation handles the majority of throughput; Home Theater is expanding most quickly on share.
Technology:
Cost tier stratification separates premium multicolor systems from mainstream phosphor economics, with hybrid architectures bridging mid-market price-performance requirements.
- Single-Diode:Blue laser diode excitation of yellow phosphor wheels delivers 2,000-6,000 lumens at lowest bill-of-materials cost. Thermal degradation thresholds limit operational lifespan in high-duty-cycle commercial deployments; Nichia and OSRAM control critical gallium nitride epitaxy capacity.
- Multicolor:Direct red, green, and blue emitter architectures achieve Rec. 2020 color gamut performance for cinema and broadcast monitoring. Barco and Christie deploy these systems in premium auditorium installations where DCI certification compliance extends 18-24 month product launch timelines.
- Hybrid:Combined phosphor and direct-emitter configurations balance cost and color performance for corporate and higher-education markets.
- Phosphor:Yellow-laser conversion wheels face ECHA SVHC restrictions on specific rare-earth phosphors, accelerating European manufacturer migration toward direct-emitting architectures.
Phosphor systems command volume leadership; Multicolor platforms are gaining share fastest in revenue terms.
Application:
Customer type differentiation separates capital-equipment purchasers from subscription-based lumen-hour service contracts, reshaping vendor cash flow profiles.
- Concerts:Touring productions demand ruggedized chassis with rapid rigging interfaces and redundant optical engines; RGB systems displace legacy lamp-based rigs in major North American and European venues.
- Corporate Events:Rental houses prioritize brightness-per-weight ratios and standardized lens throw ranges for rapid deployment flexibility.
- Cinemas:Digital Cinema Initiatives compliance testing constrains product roadmaps; China's GB standards administered by SAMR mandate specific laser safety testing that shapes market access for imported and domestic brands.
- Art Installations:Museums and galleries specify silent operation and precise color calibration for archival projection; long operational lifespans exceed 20,000 hours to minimize conservation disruption.
Cinemas anchor replacement-cycle revenue; Art Installations represent the steepest expansion trajectory in institutional procurement.
End User:
Volume concentration versus margin capture creates divergent vendor targeting strategies across entertainment, education, corporate, and cultural institutions.
- Entertainers:Production companies and touring artists prioritize reliability warranties and rapid field service networks over upfront equipment cost.
- Educators:K-12 and higher-education procurement operates through centralized tender processes with extended payment terms; India's state-level education departments aggregate demand for price leverage.
- Corporations:Enterprise IT departments standardize on specific brightness and connectivity specifications across global facility footprints; HDMI 2.1 and SDI protocol handling complicates firmware architecture for hybrid deployment scenarios.
- Museums:Curatorial and conservation staff specify color accuracy metrics and thermal management to protect sensitive exhibition materials; operational silence requirements exceed typical commercial specifications.
Corporations drive standardization-led volume; Museums command the highest specification premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through vertical integration in laser diode manufacturing, while European buyers absorb 15-25% premiums for REACH-compliant phosphor formulations. This asymmetry shapes procurement patterns across cinema, education, and residential segments.
United States
FCC equipment authorization requirements govern laser emission safety classifications for consumer projectors, creating compliance barriers for imported brands. Cinema operators in Los Angeles and New York accelerate lamp-to-laser replacement cycles, prioritizing DCI-certified RGB architectures for premium auditorium installations.
China
Domestic brands XGIMI and JMGO drive mass-market penetration through aggressive laser TV price positioning. SAMR-administered GB standards mandate specific laser product safety testing that shapes market access for both imported and domestic manufacturers, while Yangtze River Delta fabrication clusters supply critical gallium nitride epitaxy capacity.
Germany
ECHA's REACH candidate list expansion for SVHCs now covers specific rare-earth phosphors used in yellow-laser conversion wheels, forcing reformulation or architecture shifts. Munich and Stuttgart host concentrated optical engineering talent pools specializing in waveguide design and coherent beam combination.
India
Central government smart classroom initiatives under the Ministry of Education generate tender-driven volume demand for 3,000-5,000 lumen classroom projectors. BIS certification requirements and state-level education department aggregation create procurement complexity that favors established supplier relationships.
Japan
METI-supported research clusters concentrate multicolor laser diode packaging expertise that extends color gamut beyond Rec. 2020 thresholds. Osaka and Nagoya fabrication facilities supply critical emitter arrays to global cinema projector OEMs, maintaining technological leadership in RGB architectures.
Laser Projector Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Japanese and German firms anchor premium RGB laser cinema systems through optical engineering depth, while Chinese manufacturers capture volume through aggressive price positioning in consumer laser TV segments. Korean electronics conglomerates occupy a middle tier leveraging display brand equity. Consolidation pressures concentrate in phosphor-based business presentation segments where margin compression is most severe. Strategic moves center on backward integration into diode supply and geographic expansion through localized certification partnerships.
Among Asian electronics conglomerates, Samsung exemplifies lifestyle-oriented industrial design differentiation, while Hisense occupies a position in aggressive price-tier competition for North American and European retail channels. Epson represents the vertically integrated liquid crystal fabrication archetype, sustaining margin control through captive panel supply against DLP-based competitors. These three anchors illustrate how divergent capability foundations—display brand equity, manufacturing scale, and component integration—produce distinct competitive positioning within the same technology generation.
| Leading Market Players |
|---|
| Samsung |
| Epson |
| Hisense |
| NexiGo |
| TCL |
| XGIMI |
| JMGO |
| Aurzen |
| AWOL Vision |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with gallium nitride epitaxy suppliers lock in diode access and price visibility for RGB laser projector manufacturers, insulating against Nichia and OSRAM supply constraints while freezing input costs across multi-year production cycles.
Pricing Analysis
The customization-premium spread spans wide in laser projectors, with configured-to-order RGB cinema systems commanding substantial premiums over standard phosphor-based education units. Three-tier pricing structure across premium, standard, and economy levels reflects DCI certification status and emitter architecture complexity. Cost compression in phosphor-based business segments is intensifying because Chinese domestic brands flood retail channels with aggressive laser TV positioning. Education procurement departments exhibit highest price sensitivity, while museum conservators accept premiums for silent operation and color calibration precision.
Supply Chain Analysis
Strategic stockpiling of blue laser diodes dominates inventory strategy among tier-one projector OEMs, buffering against single-source vulnerability in gallium nitride epitaxy. Manufacturing concentrates in China, Japan, and Germany, with Yangtze River Delta fabrication clusters feeding domestic brands and Osaka-Nagoya arrays supplying global cinema OEMs. The supply chain draws from rare-earth phosphors, precision optical components, and MEMS scanning mirrors. Tariff exposure on Chinese-manufactured consumer units threatens North American retail margins. Distribution runs through specialized AV integrators for cinema and large-venue deployments, while consumer laser TV moves through electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating in laser projectors as India's Ministry of Education aggregates tender demand across state-level departments, compressing vendor margins while favoring established suppliers with BIS certification and service networks.
For Market Incumbents: Fortify captive diode supply through backward integration into gallium nitride epitaxy or long-term offtake agreements with Japanese suppliers, defending against emerging Chinese entrants with state-subsidized fabrication capacity. Deepen certification investment in DCI compliance and SAMR GB standards to extend product launch timelines as a competitive moat. Prioritize channel control in European markets where REACH phosphor restrictions accelerate architecture shifts toward RGB systems. For New Entrants and Emerging Players: Subscription-based illumination service gaps in North American large-venue operations offer entry points where incumbents cling to capital-equipment sales models. Target museum and gallery segments with silent-operation specifications that established vendors under-serve with standard commercial designs. Penetrate through direct curator relationships and conservation-grade color calibration capabilities rather than competing on brightness-per-dollar in saturated education tenders. For Investors and Strategic Acquirers: Optical engineering boutiques with waveguide design and coherent beam combination expertise represent prime acquisition targets as talent scarcity constrains product development velocity across the industry. Long-term viability hinges on securing RGB architecture roadmaps as phosphor economics face regulatory pressure and thermal degradation limits. Watch for IEC 60825-1 laser safety classification revisions as an inflection indicator that would force recertification investments and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Supply | Captive gallium nitride epitaxy capacity insulates against Nichia and OSRAM concentration risk. |
| DCI Certification Acceleration | Compressed 18-24 month compliance timelines enable faster revenue recognition for RGB cinema platforms. |
| Subscription Service Model Launch | Lumen-hour contracting transfers diode replacement risk from operators to manufacturers with service networks. |
| Phosphor-Free Architecture Transition | Direct-emitter designs secure REACH-compliant market access as ECHA restricts rare-earth conversion wheels. |
| India Education Tender Positioning | BIS certification and state-level relationship depth capture volume from Ministry of Education smart classroom initiatives. |
Study Parameters
The analysis maps phosphor-based, multicolor RGB, and hybrid optical engine architectures, each validated through primary interviews with cinema procurement directors, optical engineering leads, education ministry tender officials, and AV integration specialists, combined with secondary validation against SEC filings, customs trade records, DCI certification databases, and SAMR GB standards documentation. Bottom-up unit shipment modeling and top-down value triangulation cross-verify segment outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window, with segmentation modeling spanning brightness tier, emitter architecture, application vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics, lamp-to-laser transition rates, and subscription service adoption patterns. Forecast inputs include diode packaging cost trajectories, REACH substance restriction timelines, and India education infrastructure budget allocations.
Forecasts assume regulatory continuity in FCC laser safety classifications, EU REACH and RoHS frameworks, and China's SAMR-administered GB standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as IEC 60825-1 revision timelines and India state-level tender aggregation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
China Optoelectronics Market