
 Global Indium Phosphide (Inp) Wafers Market | 2026-2036
Global Indium Phosphide (Inp) Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indium Phosphide (Inp) Wafers Market Outlook
JIS standards certification for compound semiconductor substrates is unwinding the competitive field, favoring suppliers with multi-year qualification track records. Sumitomo Electric Industries leverages vertical integration from crystal growth through polished substrates to sustain pricing power in epitaxial-grade material. AXT anchors North American supply through its California and China manufacturing footprint, while Freiberger Compound Materials specializes in custom-diameter wafers for defense and research accounts.
Indium phosphide wafers are single-crystal III-V compound semiconductor substrates with lattice-matched epitaxial growth surfaces, typically manufactured via liquid-encapsulated Czochralski pulling followed by chemo-mechanical polishing to angstrom-level roughness. These wafers serve as foundation platforms for photonic integrated circuits operating at 1310-1550 nm wavelengths, enabling terabit-scale optical transmission. Epitaxial wafers command the deepest margin pools because foundries pay premiums for epi-ready surfaces that eliminate in-house pre-processing steps. Photonic integration technology leads application growth as co-packaged optics architectures displace discrete component assemblies in datacenter switches.
The U.S. EPA governs gallium and indium compound reporting under TSCA Section 8, while REACH restricts arsenic and phosphorus precursor chemicals in European wafer fabrication facilities. Japan's METI coordinates national compound semiconductor roadmaps that direct public R&D funding toward indium phosphide photonics for 6G backhaul. Stakeholders must monitor how export control classifications for epitaxial deposition equipment reshape cross-border supply arrangements.
Market Dynamics
Co-packaged optics architectures are compressing the transition timeline from discrete photonic assemblies to integrated indium phosphide platforms, forcing foundries to accelerate qualification cycles for epitaxial-grade substrates.
Growth Catalysts
- Hyperscale datacenter interconnect builds:Cloud operators in the United States and Japan are pulling wafer volumes for 800G/1.6T transceiver modules, creating sustained demand for 3-inch and 4-inch diameter substrates.
- EU F-Gas Regulation:Process chemistry restrictions are favoring indium phosphide over alternative III-V materials in European photonics fabrication, tightening specifications for precursor handling and waste recovery.
- China's dual carbon goals:Energy efficiency mandates for telecommunications infrastructure are accelerating deployment of indium phosphide-based optical engines in 5G backhaul networks.
Market Restraints
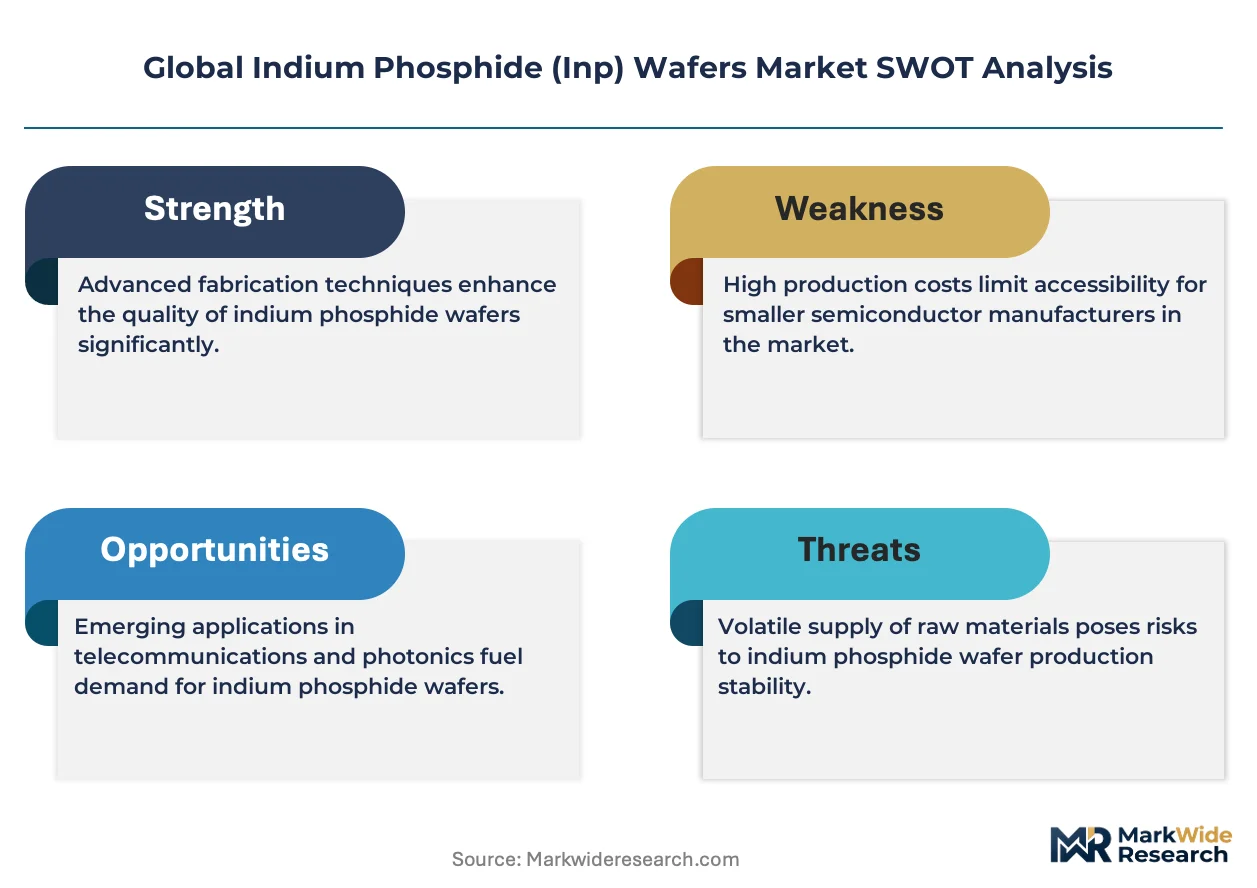
- Indium metal price volatility:Primary indium supply concentrates in Chinese smelter operations, exposing wafer manufacturers to concentrate availability shocks and LME price swings.
- Liquid-encapsulated Czochralski furnace concentration:Crystal growth equipment for 100mm+ diameter ingots is controlled by a limited vendor base in Germany and Japan, creating single-source dependencies.
- Arsenic precursor restrictions under REACH:European wafer fabrication facilities face elevated compliance costs for arsine and phosphine handling, compressing margin pools for non-vertically integrated polishers.
Strategic Opportunities
- 6G backhaul photonics in Japan:METI-coordinated national roadmaps are directing public R&D funding toward indium phosphide platforms for sub-terahertz wireless-optical convergence.
- Defense and research custom diameters:Non-standard wafer formats for quantum photonics and sensing applications command pricing premiums outside commoditized telecom volumes.
- Co-packaged optics in AI clusters:GPU-to-GPU optical interconnect requirements are creating new specification tiers for low-defect-density epitaxial material.
Industry Challenges
- JIS standards certification timelines:Multi-year qualification tracks for compound semiconductor substrates are extending sales cycles and freezing out newer entrants without established foundry relationships.
- Chemo-mechanical polishing capex intensity:Angstrom-level surface roughness requirements demand specialized slurry handling and metrology equipment, elevating barrier-to-entry for capacity expansion.
- Export control alignment for epitaxial deposition equipment:Cross-border supply arrangements for MOCVD and MBE systems face reclassification risks, complicating multi-site manufacturing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indium Phosphide (Inp) Wafers Market |
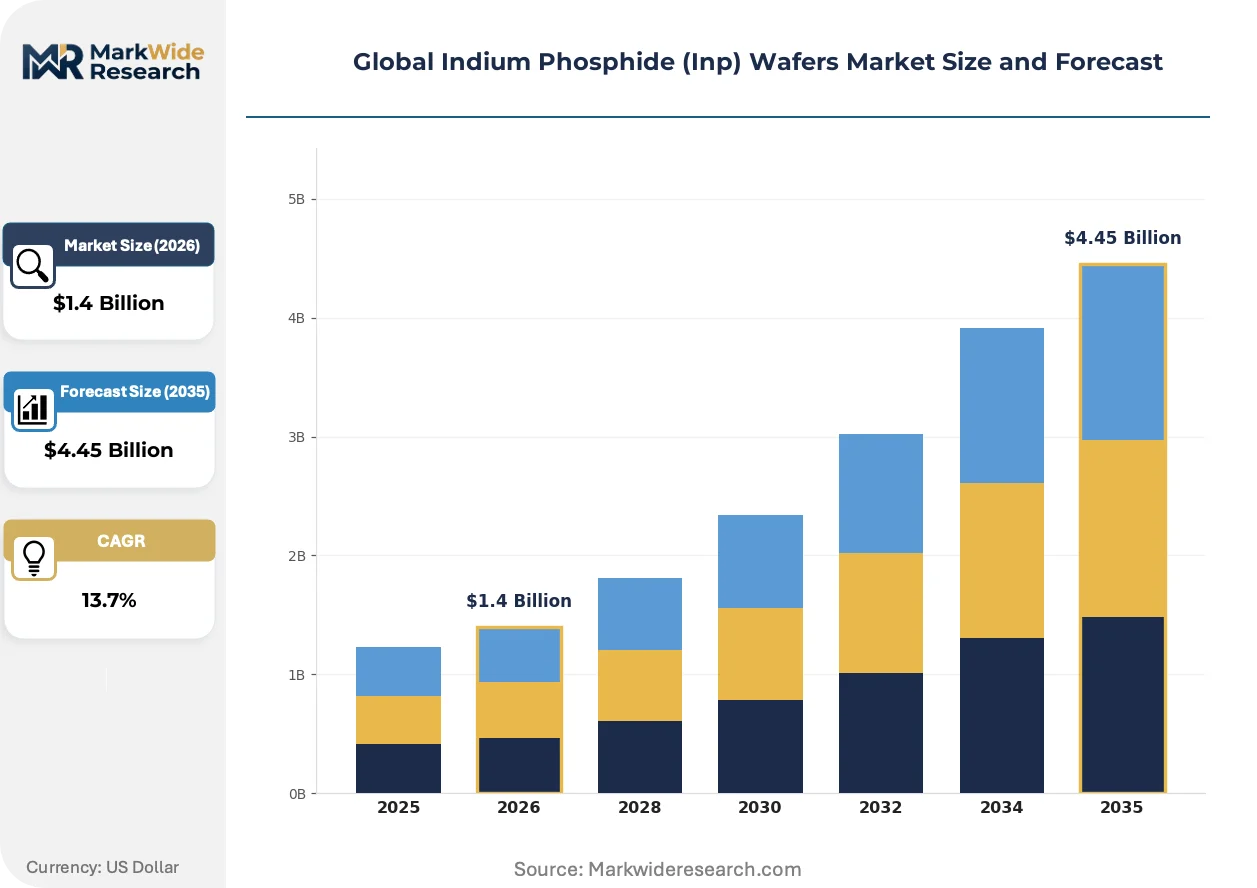
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Wafers, Epitaxial Wafers, Substrate Wafers, High-Purity Wafers Application: Telecommunications, Detectors, Laser Diodes, Photovoltaics End User: Semiconductor Industry, Research Laboratories, Telecommunications Providers, Electronics Manufacturers Technology: Heterogeneous Integration, Photonic Integration, SOI Technology, High-Frequency Devices |
| Companies Covered | Sumitomo Electric Industries, AXT, JX Nippon Mining & Metals Corporation, IQE, Freiberger Compound Materials, Xiamen Powerway Advanced Material, Wafer Technology, IntelliEPI, II-VI Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indium Phosphide (Inp) Wafers Market Strategic Shifts
Photonic integration is compressing component counts while elevating substrate performance requirements, reshaping how foundries specify epitaxial material.
Monolithic indium phosphide photonic integrated circuits are miniaturizing transceiver footprints by embedding lasers, modulators, and detectors on single chips. Hyperscale switch vendors are adopting these platforms for 51.2T switch generations, collapsing the traditional discrete component supply chain into vertically integrated substrate-to-module relationships.
Japan's METI is coordinating national compound semiconductor roadmaps that direct public R&D funding toward indium phosphide photonics for 6G backhaul. This industrial policy is concentrating wafer procurement decisions around domestic qualification standards, tightening JIS certification requirements for foreign substrate suppliers seeking access to NTT and KDDI supply chains.
Foundry procurement is consolidating around epi-ready specifications that eliminate in-house pre-processing steps. Tier-one compound semiconductor foundries in Germany and the United States are shifting volume commitments toward suppliers with captive epitaxial growth capabilities, marginalizing polish-only vendors in the substrate tier.
Global Indium Phosphide (Inp) Wafers Market Segmentation
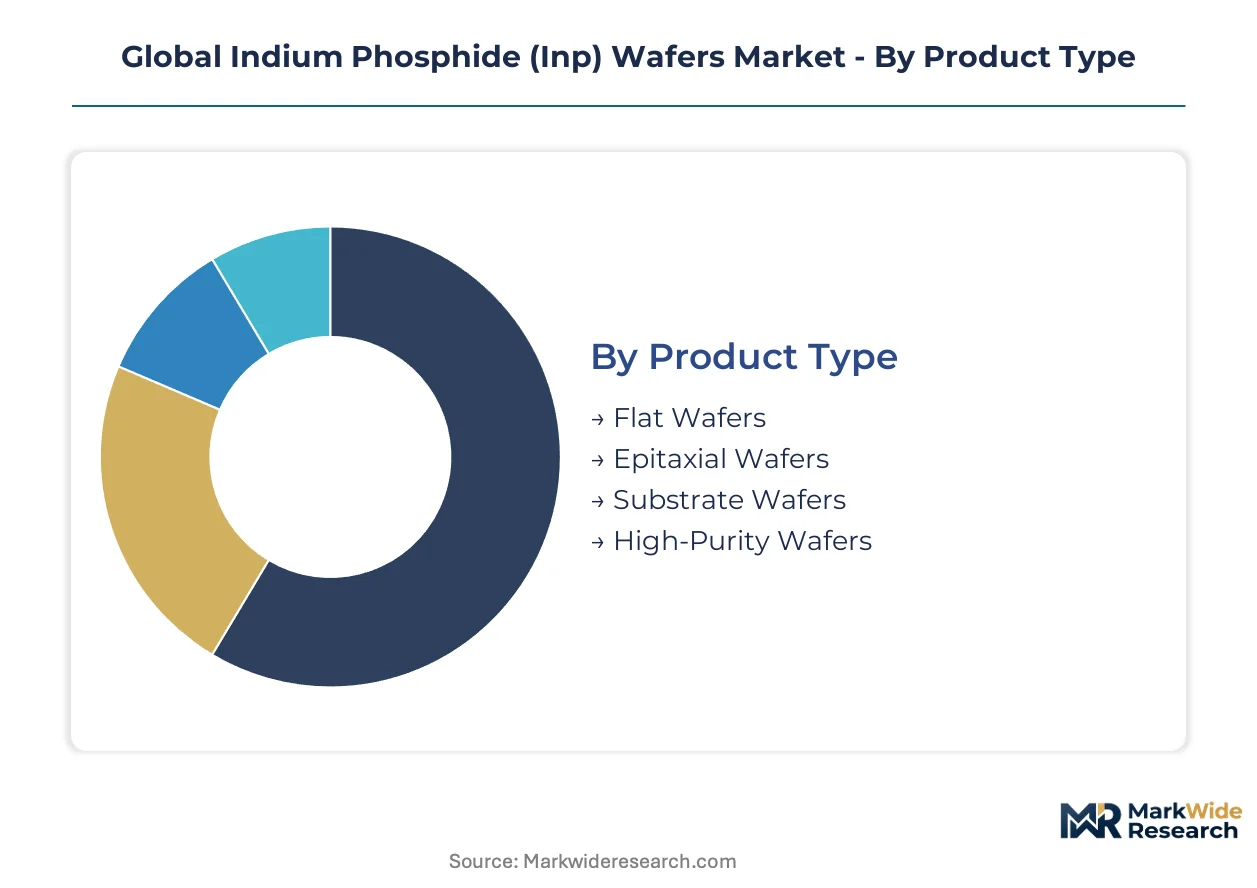
Segmentation in indium phosphide wafers reveals how value migrates toward epitaxial-ready surfaces and photonic integration architectures. Procurement patterns diverge sharply between commodity substrate volumes and premium epi-grade material qualified for hyperscale datacenter programs.
Product Type:
Margin pools concentrate in material grades that eliminate downstream processing steps for compound semiconductor foundries.
- Epitaxial Wafers:Epi-ready surfaces with atomic-level roughness control command the deepest commercial premiums. Foundries in Japan and Germany pay substantial markups for substrates pre-qualified for direct MOCVD growth, bypassing in-house chemo-mechanical polishing and defect mapping.
- Flat Wafers:Standard polished substrates without epitaxial layers serve cost-sensitive research and prototype markets. Demand concentrates in defense contracting channels where custom diameters and non-standard specifications override price sensitivity.
- Substrate Wafers:As-grown ingot slices for captive epitaxial operations at vertically integrated device manufacturers.
- High-Purity Wafers:Ultra-low residual dopant material for quantum photonics and sensing applications requiring carrier concentration below 10^15 cm^-3.
The dominant share belongs to Epitaxial Wafers, while High-Purity Wafers is closing the gap fastest.
Application:
Application mix tracks the shift from discrete optical components toward monolithic photonic integrated circuits in datacenter infrastructure.
- Telecommunications:Optical transceivers for 800G/1.6T datacenter interconnect and 5G/6G backhaul consume the majority of 3-inch and 4-inch diameter volumes. China's dual carbon goals and Japan's METI roadmaps are accelerating deployment of indium phosphide-based engines in energy-efficient network architectures.
- Laser Diodes:Distributed feedback lasers and electro-absorption modulated lasers for coherent transmission systems. Specifications from NTT and KDDI in Japan are tightening linewidth and power requirements for next-generation metro networks.
- Detectors:PIN and avalanche photodiodes for optical receivers in high-speed data links.
- Photovoltaics:Concentrator and space-grade multi-junction cells leveraging indium phosphide lattice matching for III-V tandem structures.
Telecommunications holds the volume base, with Laser Diodes expanding most quickly as coherent modulation schemes proliferate.
End User:
Customer type determines qualification timelines and contract structures across the substrate tier.
- Semiconductor Industry:Compound semiconductor foundries and IDMs driving standardization around JIS-certified epi-ready specifications. Multi-year qualification tracks favor incumbent suppliers with established crystal growth and polishing capabilities.
- Research Laboratories:National laboratories and university consortia purchasing small-lot custom diameters for quantum photonics and terahertz device development.
- Telecommunications Providers:NTT, KDDI, and vertically integrated optical module divisions specifying substrate requirements for captive transceiver production.
- Electronics Manufacturers:Consumer and industrial device makers with intermittent demand for specialized photonic components.
Semiconductor Industry accounts for the dominant procurement volume, while Research Laboratories command the steepest pricing premiums per wafer.
Technology:
Technology segmentation tracks how device architectures are reshaping substrate performance requirements.
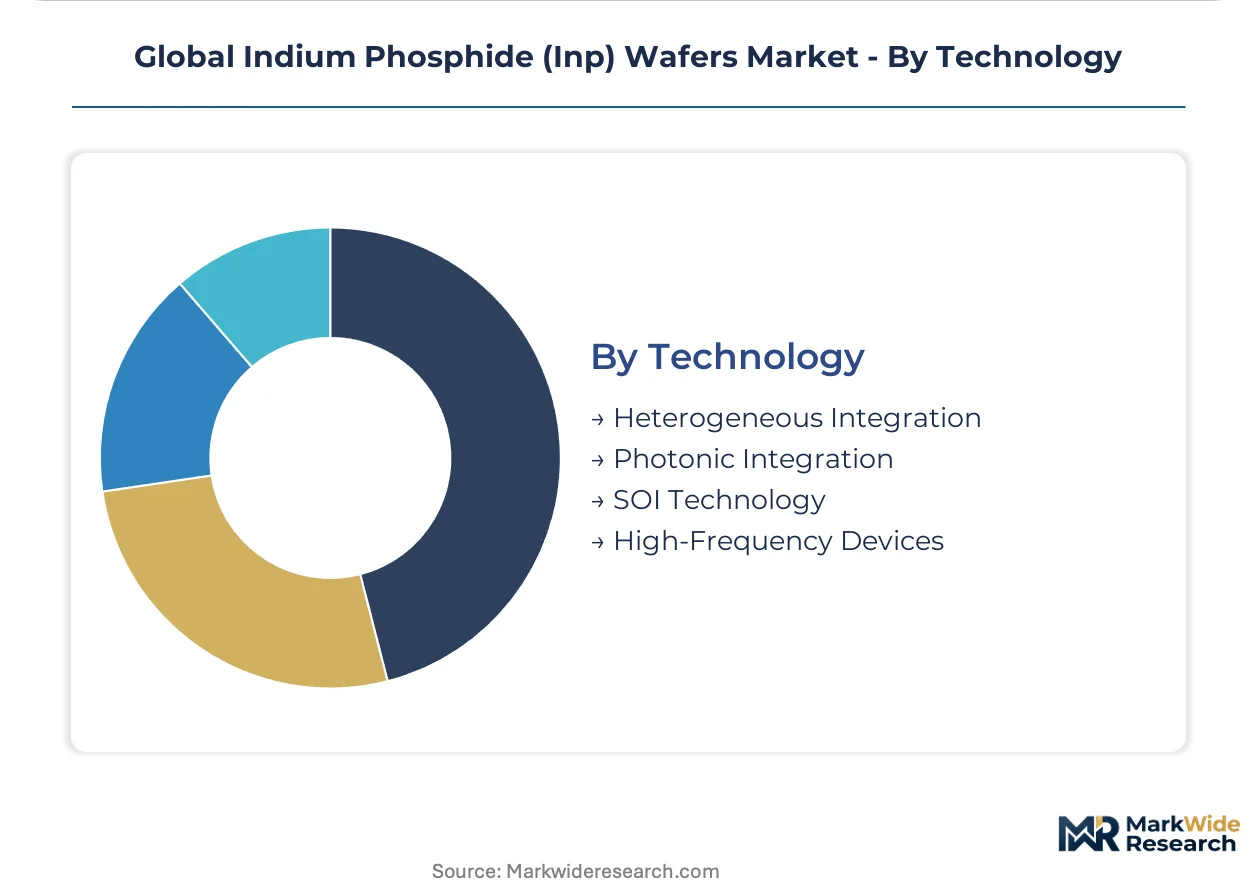
- Photonic Integration:Monolithic integration of lasers, modulators, and detectors on single indium phosphide chips is collapsing component counts in 51.2T switch generations. Co-packaged optics architectures are creating new specification tiers for low-defect-density epitaxial material qualified for AI cluster interconnects.
- Heterogeneous Integration:Wafer-scale bonding of indium phosphide active layers to silicon photonics interposers. Foundries in the United States and Germany are driving process development for hybrid integration platforms.
- High-Frequency Devices:HEMT and HBT structures for millimeter-wave and sub-terahertz applications in 6G backhaul research programs.
- SOI Technology:Silicon-on-insulator integration approaches competing for certain photonic functions outside indium phosphide's wavelength sweet spot.
Photonic Integration leads technology-driven demand, with Heterogeneous Integration climbing fastest as hybrid silicon-indium phosphide platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound semiconductor foundries cluster in Japan, Germany, and the United States, where JIS certification requirements and multi-year qualification tracks concentrate procurement decisions around established suppliers with proven crystal growth and polishing capabilities.
United States
Hyperscale cloud operators in Silicon Valley and the Pacific Northwest are pulling wafer volumes for 800G/1.6T transceiver modules, creating sustained demand for 3-inch and 4-inch diameter substrates. The EPA governs gallium and indium compound reporting under TSCA Section 8, tightening process chemistry documentation for fabrication facilities. Greater Boston hosts research consortia developing co-packaged optics architectures for AI cluster interconnects.
Japan
NTT and KDDI are specifying substrate requirements for captive transceiver production, tightening linewidth and power requirements for next-generation metro networks. METI coordinates national compound semiconductor roadmaps directing public R&D funding toward indium phosphide photonics for 6G backhaul. Tokyo-Yokohama corridor foundries concentrate qualification decisions around JIS-certified epi-ready specifications.
Germany
Tier-one compound semiconductor foundries are shifting volume commitments toward suppliers with captive epitaxial growth capabilities, marginalizing polish-only vendors in the substrate tier. The EU F-Gas Regulation restricts arsenic and phosphorus precursor chemicals, elevating compliance costs for wafer fabrication facilities. Freiburg anchors specialized production of custom-diameter wafers for defense and research accounts.
China
Energy efficiency mandates for telecommunications infrastructure are accelerating deployment of indium phosphide-based optical engines in 5G backhaul networks. Dual carbon goals are tightening process chemistry standards across smelter operations that supply primary indium metal. Xiamen hosts substrate manufacturers serving domestic compound semiconductor foundries with multi-inch diameter capabilities.
United Kingdom
Research laboratories and national consortia are purchasing small-lot custom diameters for quantum photonics and terahertz device development, commanding steepest pricing premiums per wafer. REACH restrictions on arsenic precursor handling compress margin pools for non-vertically integrated polishers. Cambridge-Oxford corridor concentrates epitaxial deposition equipment development facing export control reclassification risks.
Global Indium Phosphide (Inp) Wafers Market Competitive Environment
Player mix skews toward vertically integrated crystal growers with captive polishing and epitaxial capabilities, creating a tiered structure where JIS certification and multi-year foundry relationships serve as primary barriers to entry. Three archetypes dominate: Japanese conglomerates with full-stack substrate-to-device integration, North American specialists leveraging dual-hemisphere manufacturing footprints, and European custom-diameter producers serving defense and research niches. Competitive moves concentrate on backward integration into indium metal sourcing and strategic partnerships with MOCVD equipment vendors to secure epitaxial deposition capacity.
Within the premium-tier vector, Sumitomo Electric Industries occupies a position exemplifying full vertical control from crystal growth through polished substrates. AXT anchors North American supply through its California and China manufacturing footprint, representing the dual-hemisphere archetype. Freiberger Compound Materials sits within the European specialist tier, exemplifying custom-diameter production for non-commoditized applications.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| AXT |
| JX Nippon Mining & Metals Corporation |
| IQE |
| Freiberger Compound Materials |
| Xiamen Powerway Advanced Material |
| Wafer Technology |
| IntelliEPI |
| II-VI Incorporated |
| Others |
Value Chain & Pricing Dynamics
Silicon photonics substitution in datacenter transceivers is compressing indium phosphide wafer premiums while simultaneously redrawing supply geography toward China-based substrate manufacturers and Japanese crystal growth specialists. This displacement dynamic forces incumbent suppliers to defend pricing power through JIS certification moats as buyers arbitrage between III-V compound and silicon-based photonic platforms.
Pricing Analysis
Cost-plus contracts indexed to LME indium metal pricing dominate long-term wafer offtake agreements between Japanese crystal growers and German compound semiconductor foundries. Three-tier pricing structure across epitaxial-grade, epi-ready, and research-grade specifications reflects JIS certification status and captive polishing capability. Cost compression in standard-diameter substrates is intensifying because Chinese manufacturers are expanding 3-inch and 4-inch capacity. Research laboratories purchasing custom-diameter formats exhibit the lowest price sensitivity, while telecom module assemblers drive the hardest volume negotiations.
Supply Chain Analysis
German liquid-encapsulated Czochralski furnace exports to Japan and China underwrite the entire 100mm+ diameter ingot supply base for photonics-grade material. Primary indium concentrates in Chinese smelter operations, while crystal growth equipment manufacturing anchors in Germany and Japan. Single-source vulnerability pervades the epitaxial deposition equipment tier, where MOCVD system exports face tightening multilateral controls. Distribution runs through vertically integrated substrate-to-device suppliers rather than independent merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium phosphide wafer incumbents face a substitution defense against silicon photonics platforms that threaten to capture 800G transceiver volumes through hybrid integration architectures.
For Market Incumbents: Secure captive indium metal sourcing through offtake agreements with Chinese concentrate producers to buffer LME price volatility. Deepen backward integration into epitaxial deposition equipment partnerships with MOCVD vendors to lock in capacity allocation ahead of export control tightening. For New Entrants and Emerging Players: JIS certification fast-tracks through Japanese foundry qualification programs represent the most penetrable entry vector for non-vertically integrated polishers. Target defense and quantum photonics research accounts in the United Kingdom and Germany where custom-diameter premiums offset low volume scale. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated crystal growers with captive polishing and epitaxial capabilities over polish-only merchant vendors. The signal to watch is METI funding disbursement velocity for 6G backhaul photonics programs as an inflection indicator for Japanese domestic procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Concentrate Supply | Captive metal sourcing insulates margins against LME volatility and Chinese export policy shifts. |
| JIS Certification Investment | Multi-year qualification tracks with NTT and KDDI create switching costs that freeze out non-certified entrants. |
| Epitaxial Deposition Equipment Partnership | Strategic alliances with MOCVD vendors secure capacity allocation ahead of multilateral export control reclassification. |
| Custom-Diameter Defense Specialization | Non-standard wafer formats for quantum photonics command pricing premiums outside commoditized telecom volumes. |
| Dual-Hemisphere Manufacturing Footprint | California-China production configuration hedges tariff exposure and satisfies divergent regulatory compliance requirements. |
Study Parameters
The analysis maps epitaxial wafer, flat wafer, substrate wafer, and high-purity wafer sub-sectors, each validated through compound semiconductor foundry procurement managers, crystal growth equipment engineers, and epitaxial deposition technologists. Primary interviews with JIS certification auditors and METI program officers combined with secondary validation from SEC filings, customs trade records, and national compound semiconductor roadmap documents. Bottom-up wafer volume estimates triangulated against top-down photonics device production forecasts.
Consistency checks against hyperscaler datacenter capex disclosures and optical transceiver module shipment data validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product grade tier, application architecture, end-user qualification status, and regional foundry cluster. CAGRs derived from demand elasticity analysis for 800G/1.6T transceiver deployment and 6G backhaul photonics funding trajectories.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale datacenter buildouts and stable indium concentrate supply would require recalibration. Forecasts reflect assumptions regarding JIS certification timeline stability and export control classification continuity. Practitioners should keep alternative scenarios live as silicon photonics hybrid integration maturity and Chinese dual carbon policy enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
3D Projector Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Quantum Cascade Lasers Market