
 Optoelectronic Development Tools Market | 2026-2036
Optoelectronic Development Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Optoelectronic Development Tools Market Analytics
The EU Green Deal is restructuring procurement priorities across European optoelectronics labs, forcing development tool vendors to certify energy efficiency in LED and photovoltaic testing modules. Broadcom leverages its vertical integration across optical communications to sustain R&D tool partnerships with major foundries. ams OSRAM AG anchors its development platform strategy on automotive lighting qualification, where regulatory compliance cycles drive recurring tool upgrades. Samsung Electronics dominates Asia-Pacific foundry tool procurement through captive demand from its display and memory divisions.
Optoelectronic development tools encompass hardware and software systems for designing, simulating, and validating light-emitting and light-sensing components, typically operating across wavelength ranges from ultraviolet to infrared with nanometer-scale precision in optical alignment. These tools serve semiconductor fabs and research institutions that must verify electro-optical conversion efficiency, spectral purity, and thermal stability before volume manufacturing. Development boards and evaluation kits capture the largest revenue pool as they represent the mandatory first step in any custom optoelectronic design cycle, while software platforms are expanding fastest as physics-based simulation replaces physical prototyping. Semiconductor manufacturers constitute the most concentrated buyer segment, though research institutions command premium pricing for multi-technology platforms spanning laser diodes through optical sensors.
FDA device qualification rules in the United States and EU MDR standards in Europe compel medical device developers to maintain traceable calibration records on photonic testing equipment, directly shaping tool feature requirements. China's GB standards and NMPA optical device regulations add a third compliance layer for vendors accessing its medical and automotive markets. South Korea's MFDS and METI in Japan enforce additional spectral safety testing protocols that filter market entry. Stakeholders must monitor which regulatory bodies adopt harmonized IEC standards versus maintaining national deviations, as this determines whether single-platform certification strategies remain viable or fragment into geography-specific product variants.
Market Dynamics
Semiconductor foundries are compressing photonic prototyping cycles from months to weeks, forcing development tool vendors to integrate real-time spectral calibration and thermal modeling into single-platform workflows.
Growth Catalysts
- EU Green Deal energy mandates:LED and photovoltaic testing modules now require certified efficiency verification, creating mandatory upgrade cycles across European optoelectronics labs.
- Automotive LiDAR qualification:Safety-critical optical sensors for autonomous vehicles demand traceable calibration chains from development through production.
- South Korea's semiconductor cluster concentration:Samsung's captive display and memory divisions generate sustained procurement of multi-wavelength evaluation platforms.
Market Restraints
- Precision optical component costs:Nanometer-scale alignment systems depend on rare-earth doped fibers and stabilized laser sources with volatile supply chains concentrated in China and Japan.
- Regulatory fragmentation:IEC harmonization remains incomplete as FDA device qualification rules, EU MDR standards, and China's GB standards impose non-overlapping calibration documentation requirements.
- Technical bandwidth limitations:Existing development boards struggle to simulate terahertz-range electro-optical interactions, constraining next-generation communications prototyping.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fabrication incentives are attracting optoelectronics R&D investment, creating demand for localized development tool distribution and training infrastructure.
- Software-physics convergence:Cloud-based electromagnetic simulation paired with AI-accelerated thermal modeling is expanding into mid-tier research institutions previously priced out of physical prototyping.
- Medical device traceability mandates:FDA and EU MDR calibration record requirements are opening premium service contracts for audit-ready testing documentation.
Industry Challenges
- Multi-physics simulation expertise:Tool vendors face acute shortages of engineers capable of integrating optical, thermal, and electrical domain modeling into unified software architectures.
- Cross-border certification timelines:Simultaneous FDA, NMPA, and MFDS approval processes for photonic medical devices extend product launch windows by 18-24 months.
- Legacy fab equipment integration:New optical sensor prototyping platforms must interface with decades-old semiconductor process control systems without disrupting production line uptime guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optoelectronic Development Tools Market |
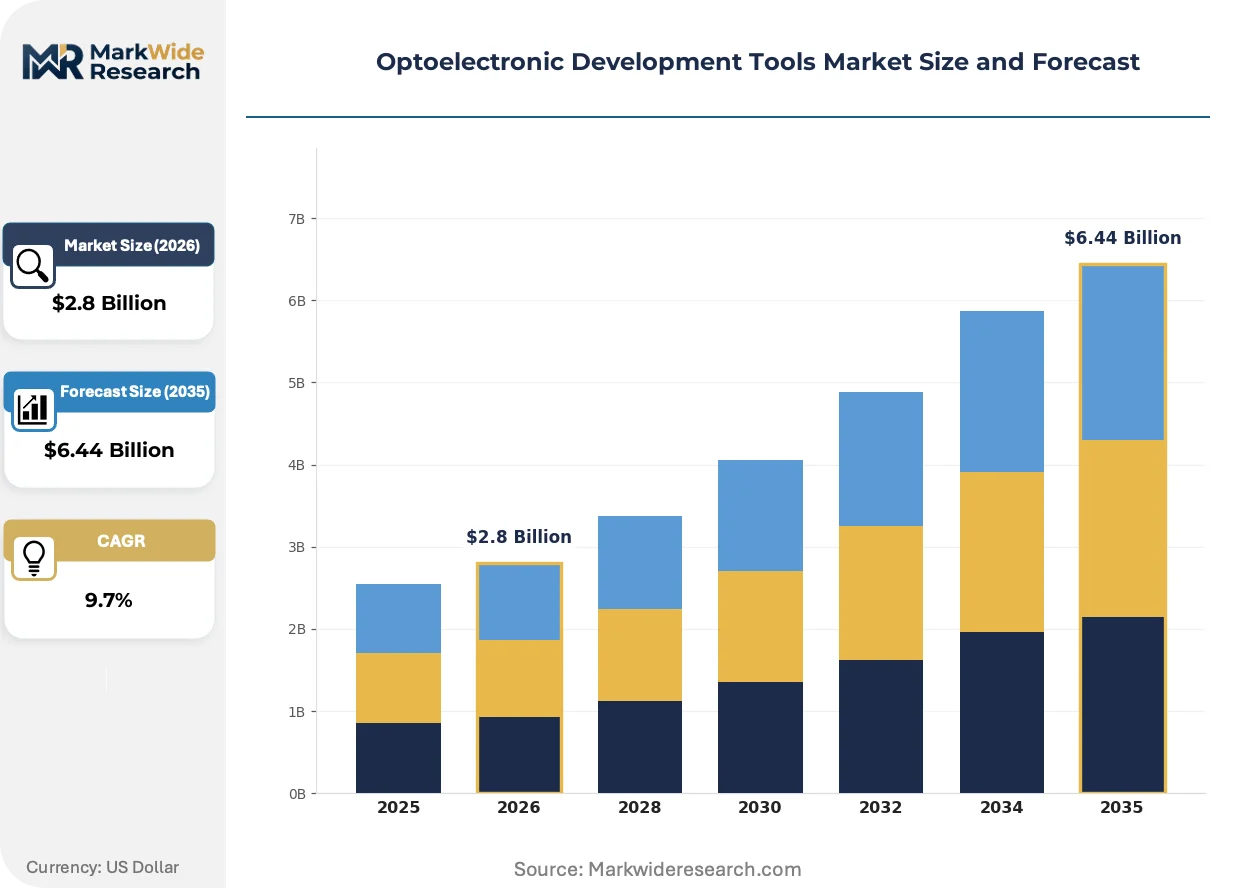
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Development Boards, Evaluation Kits, Prototyping Tools, Software Platforms End User: Semiconductor Manufacturers, Research Institutions, System Integrators, Educational Institutions Technology: LED, Laser Diodes, Photovoltaics, Optical Sensors Application: Consumer Electronics, Telecommunications, Automotive Lighting, Medical Devices |
| Companies Covered | Broadcom, ams OSRAM AG, Samsung Electronics, Hamamatsu Photonics, Lumentum Holdings, Coherent, Texas Instruments, Intel, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optoelectronic Development Tools Market Evolving Landscape
Physics-based simulation software is displacing physical prototyping across early-stage optoelectronic design, compressing development timelines and reshaping how semiconductor fabs allocate capital between hardware and digital tooling.
Silicon photonics process design kits are expanding into high-volume communications applications as foundries standardize passive and active optical component libraries. Data center operators and telecom equipment manufacturers now specify PDK-compatible designs from initial concept, collapsing the traditional handoff between research prototyping and manufacturing transfer. This convergence is expanding into automotive sensing and medical imaging, where electro-optical integration density requirements now match communications-grade specifications.
EU MDR and FDA device qualification rules are mandating traceable calibration records across photonic testing equipment used in medical device development. Manufacturers must now embed automated audit trails and blockchain-anchored documentation into development platforms, not as optional features but as baseline compliance architecture. European and North American medical device developers are responding by consolidating vendor relationships around platforms with pre-validated regulatory modules.
Subscription-based access to cloud simulation clusters is displacing perpetual software licenses and dedicated on-premise hardware installations among mid-tier research institutions. Universities and regional semiconductor consortia in Germany, South Korea, and the United States now pool computational resources through shared platform agreements, unbundling high-performance optical modeling from capital-intensive infrastructure ownership. This model is concentrating most visibly in photonics research hubs where federal funding agencies prioritize collaborative facility access over individual laboratory equipment grants.
Optoelectronic Development Tools Market Segmentation
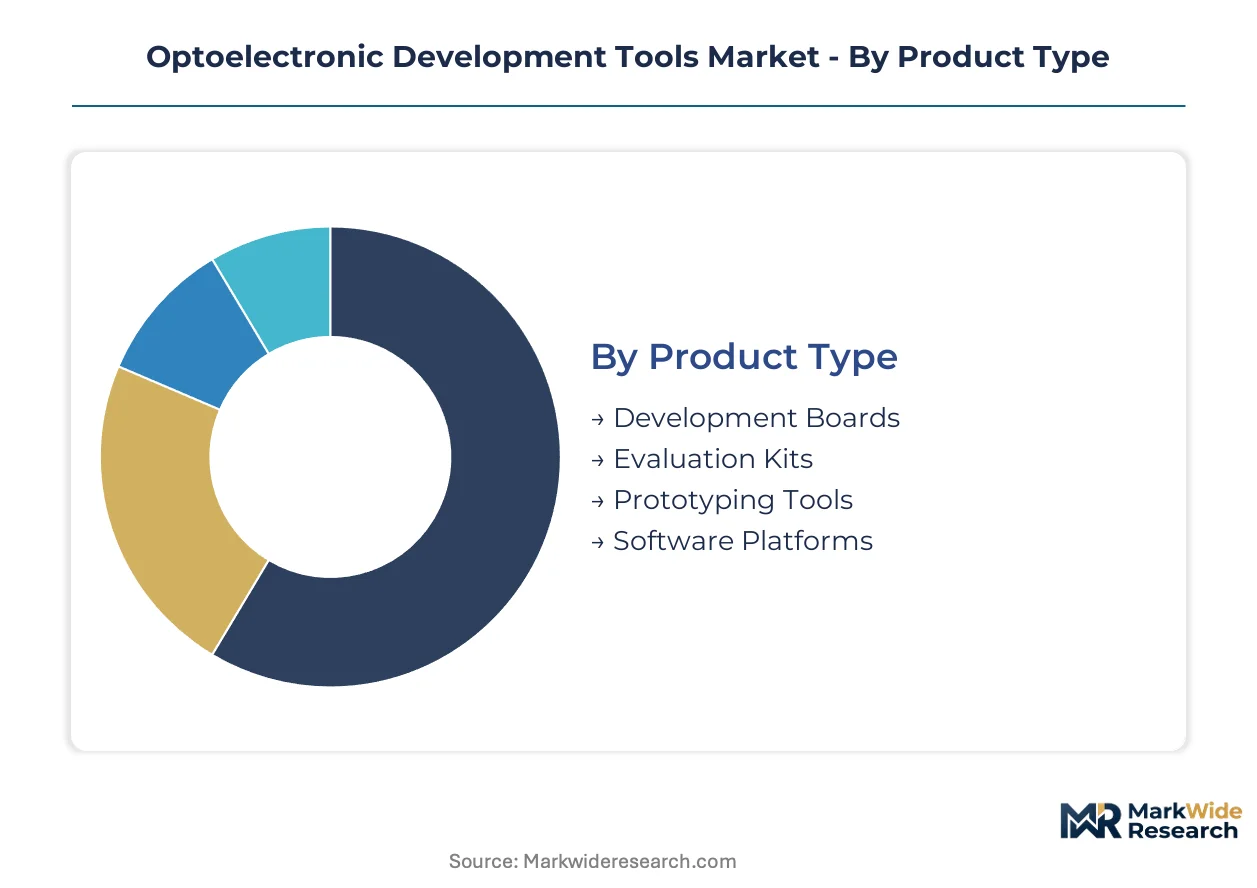
Optoelectronic development tools fragment across four dimensions that determine procurement cycles, pricing power, and vendor relationships. Product type dictates capital intensity and upgrade frequency. End-user concentration shapes contract structures and service attachment rates. Technology alignment determines regulatory compliance burdens. Application verticals impose distinct certification timelines and performance thresholds.
Product Type:
Cost tier separates buyers into perpetual-license hardware purchasers versus subscription-oriented software adopters, with hybrid procurement emerging among mid-scale semiconductor fabs.
- Development Boards:These modular hardware platforms integrate photonic components with programmable logic for real-time electro-optical testing. Semiconductor manufacturers in Germany and South Korea drive procurement through captive R&D divisions that require rapid iteration cycles for optical sensor validation. Volume sits with Development Boards; growth tilts toward Software Platforms.
- Evaluation Kits:Pre-configured component assemblies enable standardized performance benchmarking across wavelength and thermal parameters. Research institutions in the United States command premium configurations spanning ultraviolet through infrared ranges to support multi-project grant portfolios. These kits anchor initial vendor relationships that expand into enterprise-wide tool contracts.
- Prototyping Tools:Customizable optical alignment systems with nanometer-scale precision serve foundries bridging research and pilot production.
- Software Platforms:Cloud-deployed electromagnetic simulation environments are displacing dedicated hardware installations among mid-tier research consortia.
Hardware procurement concentrates in established fabrication hubs; software subscriptions are expanding most quickly among institutions with limited capital allocation flexibility.
End User:
Application maturity distinguishes volume buyers with standardized procurement protocols from premium buyers requiring multi-technology platform integration.
- Semiconductor Manufacturers:Foundries and IDMs operate the most concentrated procurement budgets, specifying traceable calibration chains from development through production. Samsung's captive display and memory divisions in South Korea generate sustained demand for multi-wavelength evaluation platforms that interface with legacy process control systems. These buyers negotiate enterprise licenses with mandatory uptime guarantees and 24-hour technical response.
- Research Institutions:Universities and national laboratories command premium pricing for platforms spanning laser diodes through optical sensors, often funded through federal grants prioritizing collaborative facility access. Germany's Fraunhofer network and U.S. National Science Foundation centers pool computational resources through shared platform agreements.
- System Integrators:Contract manufacturers serving automotive and medical device OEMs require development tools with pre-validated regulatory modules for FDA and EU MDR compliance.
- Educational Institutions:Undergraduate photonics programs drive entry-level kit demand with constrained budgets and standardized curriculum requirements.
Procurement scale favors Semiconductor Manufacturers; pricing power and service margins concentrate with Research Institutions.
Technology:
Regulatory exposure varies sharply across this category, with medical and automotive applications imposing distinct compliance architectures on testing equipment.
- LED:Solid-state emitters spanning visible through ultraviolet wavelengths require thermal stability verification under EU Green Deal energy efficiency mandates. European optoelectronics labs now mandate certified efficiency verification modules, forcing upgrade cycles across existing installations. These mandates are restructuring procurement priorities and consolidating vendor relationships around platforms with embedded compliance documentation.
- Optical Sensors:Photodetectors and image sensors for LiDAR and medical imaging demand traceable calibration chains from development through production. Automotive qualification protocols in Germany and the United States require spectral safety testing that filters market entry for non-compliant tool vendors.
- Laser Diodes:Coherent light sources for communications and sensing applications require precision wavelength stabilization and power calibration.
- Photovoltaics:Solar cell characterization tools face efficiency verification requirements under EU renewable energy directives.
LED tools command the largest installed base; Optical Sensors are climbing the fastest on autonomous vehicle and medical imaging demand.
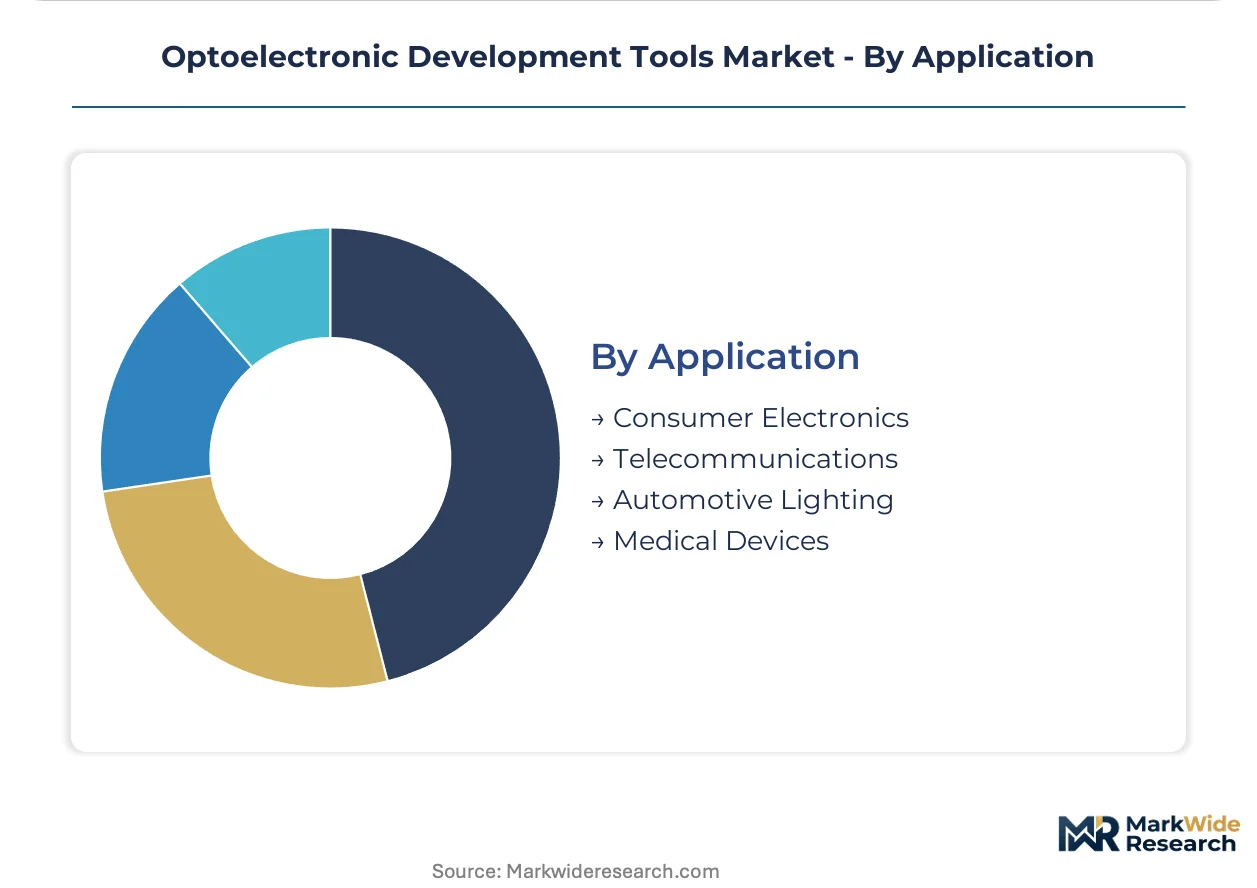
Application:
Certification timeline intensity separates this category, with medical and automotive verticals imposing 18-24 month approval processes that reshape vendor selection criteria.
- Automotive Lighting:Headlamp and interior illumination systems require qualification under ECE regulations in Europe and FMVSS standards in the United States. ams OSRAM AG anchors its development platform strategy on this vertical, where regulatory compliance cycles drive recurring tool upgrades and long-term service contracts.
- Medical Devices:Photonic diagnostic and therapeutic equipment faces FDA device qualification rules and EU MDR standards mandating automated audit trails and blockchain-anchored documentation. Manufacturers must embed these capabilities as baseline compliance architecture, not optional features, consolidating procurement around pre-validated platforms.
- Consumer Electronics:Display and camera module development drives high-volume, price-sensitive procurement with compressed product cycles.
- Telecommunications:Datacenter interconnect and fiber optic component testing requires silicon photonics process design kit compatibility.
Revenue scale sits with Consumer Electronics; margin expansion and contract durability tilt toward Medical Devices and Automotive Lighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dresden's Silicon Saxony corridor anchors European optoelectronics R&D concentration, with Fraunhofer institutes and GlobalFoundries operations driving sustained procurement of multi-wavelength evaluation platforms. South Korea's Pangyo Techno Valley and China's Yangtze River Delta fabrication clusters generate parallel demand spikes for development board integration with legacy process control systems.
United States
Automotive LiDAR qualification protocols and medical device traceability mandates drive concentrated demand from Detroit autonomous vehicle labs and Boston photonics corridors. FDA device qualification rules compel developers to maintain blockchain-anchored calibration documentation, reshaping vendor selection toward pre-validated platforms. Austin and Phoenix semiconductor fabrication expansions absorb multi-physics simulation tools for silicon photonics process design kit standardization.
Germany
EU Green Deal energy efficiency mandates force mandatory upgrade cycles across LED and photovoltaic testing installations in Munich and Berlin research consortia. ECE automotive lighting regulations sustain recurring tool procurement from ams OSRAM AG's development platform partnerships. Fraunhofer network facilities pool computational resources through shared platform agreements, concentrating software subscription growth among mid-tier institutions.
South Korea
Samsung Electronics' captive display and memory divisions generate sustained procurement of nanometer-scale optical alignment systems through Seoul and Suwon R&D campuses. MFDS spectral safety testing protocols filter market entry for non-compliant photonic medical device vendors. Busan-Ulsan semiconductor cluster expansions absorb real-time spectral calibration modules as foundries compress prototyping cycles from months to weeks.
China
NMPA optical device regulations and GB standards impose third compliance layer requirements on photonic testing equipment accessing medical and automotive markets. Yangtze River Delta fabrication hubs in Shanghai and Suzhou drive volume procurement of development boards for consumer electronics camera module validation. Beijing-Tianjin-Hebei corridor research institutes face pricing pressure from volatile rare-earth doped fiber supply chains concentrated in domestic mining regions.
Japan
METI-enforced spectral safety testing protocols and JIS standards sustain premium pricing for traceable calibration chains in Yokohama and Osaka optical communications labs. Hamamatsu Photonics anchors domestic demand for ultraviolet through infrared evaluation kits serving multi-project grant portfolios. Nagoya automotive sensor corridors absorb LiDAR prototyping tools as Tier 1 suppliers qualify for ECE and FMVSS export compliance.
Optoelectronic Development Tools Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive semiconductor demand. Consolidation pressure concentrates around foundry-aligned tool vendors capable of integrating real-time spectral calibration with legacy process control systems. Three archetypes dominate: vertically integrated chipmakers leveraging internal demand, specialized photonics component suppliers anchoring automotive qualification workflows, and cloud-physics convergence platforms serving subscription-oriented research consortia. Strategic moves center on silicon photonics process design kit standardization partnerships and regulatory pre-validation bundling for medical device traceability mandates.
Among diversified semiconductor fabricators, Broadcom exemplifies the foundry-partnership archetype through optical communications vertical integration, while Samsung Electronics occupies a position as scale-driven captive demand generator for multi-wavelength platforms. Texas Instruments represents the precision analog tier serving industrial and automotive qualification channels with development board standardization. ams OSRAM AG anchors the automotive lighting specialization vector where regulatory compliance cycles sustain recurring upgrade revenue.
| Leading Market Players |
|---|
| Broadcom |
| ams OSRAM AG |
| Samsung Electronics |
| Hamamatsu Photonics |
| Lumentum Holdings |
| Coherent |
| Texas Instruments |
| Intel |
| Vishay Intertechnology |
| Others |
Value Network & Pricing Analysis
Captive backward integration into rare-earth doped fiber and stabilized laser source production anchors pricing power for vendors serving nanometer-scale alignment systems, while outsourced component sourcing exposes mid-tier toolmakers to volatile input costs from China and Japan.
Pricing Analysis
Uptime-guarantee contracts tied to foundry production yield anchor value-based pricing for enterprise-tier development platforms. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor manufacturers with 24-hour technical response mandates from research institutions pooling shared platform agreements. Cost compression in entry-level evaluation kits is intensifying because educational procurement budgets face federal funding constraints. System integrators serving automotive OEMs exhibit lowest price sensitivity due to embedded regulatory pre-validation requirements.
Supply Chain Analysis
Specialized optical engineering talent shortages in Germany, South Korea, and the United States constrain production scaling for precision alignment system manufacturers. Rare-earth doped fibers, stabilized laser sources, and nanometer-grade motion controllers feed from concentrated mining and fabrication facilities in China and Japan. Single-source vulnerability in stabilized laser source supply chains threatens production continuity for vendors without dual-qualified component vendors. Distribution runs through direct foundry partnerships and regional semiconductor consortia with pooled procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over rare-earth doped fiber supply and captive foundry relationships determines sustainable margin capture.
For Market Incumbents: Extend silicon photonics process design kit standardization partnerships to lock in foundry-aligned procurement cycles before emerging cloud-physics platforms displace hardware-centric revenue streams. Deepen backward integration into stabilized laser source production to offset rare-earth supply volatility from Chinese mining concentration. Fortify regulatory pre-validation bundling for FDA and EU MDR compliance to defend service contract pricing power. For New Entrants and Emerging Players: AI-accelerated thermal modeling software offers the most penetrable wedge against established hardware vendors, particularly among mid-tier German and South Korean research consortia priced out of physical prototyping infrastructure. Target India's PLI scheme beneficiaries with localized training and distribution partnerships as domestic fabrication incentives attract optoelectronics R&D investment. Lead with subscription-based cloud simulation access to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified semiconductor fabricators seeking captive development tool capabilities for internal R&D divisions. Long-term viability favors vendors with demonstrated silicon photonics PDK partnerships and regulatory pre-validation architectures across multiple geographies. Watch for harmonization progress between FDA, NMPA, and MFDS calibration documentation standards as inflection indicator for platform consolidation versus fragmentation strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics PDK Standardization | Foundry partnerships with GlobalFoundries and Samsung collapse research-to-manufacturing handoff timelines. |
| Regulatory Pre-Validation Bundling | FDA and EU MDR audit trail modules differentiate platforms for Boston and Munich medical device corridors. |
| Cloud-Physics Convergence Platform Launch | Subscription electromagnetic simulation displaces dedicated hardware among Fraunhofer network facilities. |
| Rare-Earth Supply Chain Backward Integration | Captive fiber production insulates vendors from Chinese export restriction volatility. |
| India PLI Localization Partnership | Dresden and Pangyo vendors establish training infrastructure for emerging domestic fabrication demand. |
Research Methodology
Independent corroboration across primary interviews with semiconductor fab process engineers, optical test equipment procurement managers, and photonics research directors, combined with secondary validation through SEC 10-K filings, EU Green Deal implementation reports, and NMPA optical device regulatory databases, underwrites the qualitative findings. Bottom-up demand modeling from individual foundry procurement cycles triangulates against top-down market sizing from equipment vendor revenue disclosures.
Rate-of-change decomposition across product type, end user concentration, technology alignment, and application vertical segmentation dimensions structures the analytical framework throughout the projection horizon. CAGRs derive from regression analysis against semiconductor capital expenditure cycles and regulatory mandate implementation timelines. Silicon photonics adoption curves and automotive LiDAR qualification protocol expansions serve as primary industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced foundry capacity expansions, sudden rare-earth export restrictions, and breakthrough terahertz-range simulation capabilities. Forecasts reflect documented assumptions regarding regulatory harmonization progress and sustained federal funding for collaborative research facility access. Material deviation in EU Green Deal enforcement intensity or FDA audit trail mandate timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Light Projector Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Laser Projector Market