
 Contact Image Sensor Market | 2026-2036
Contact Image Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Image Sensor Market Outlook
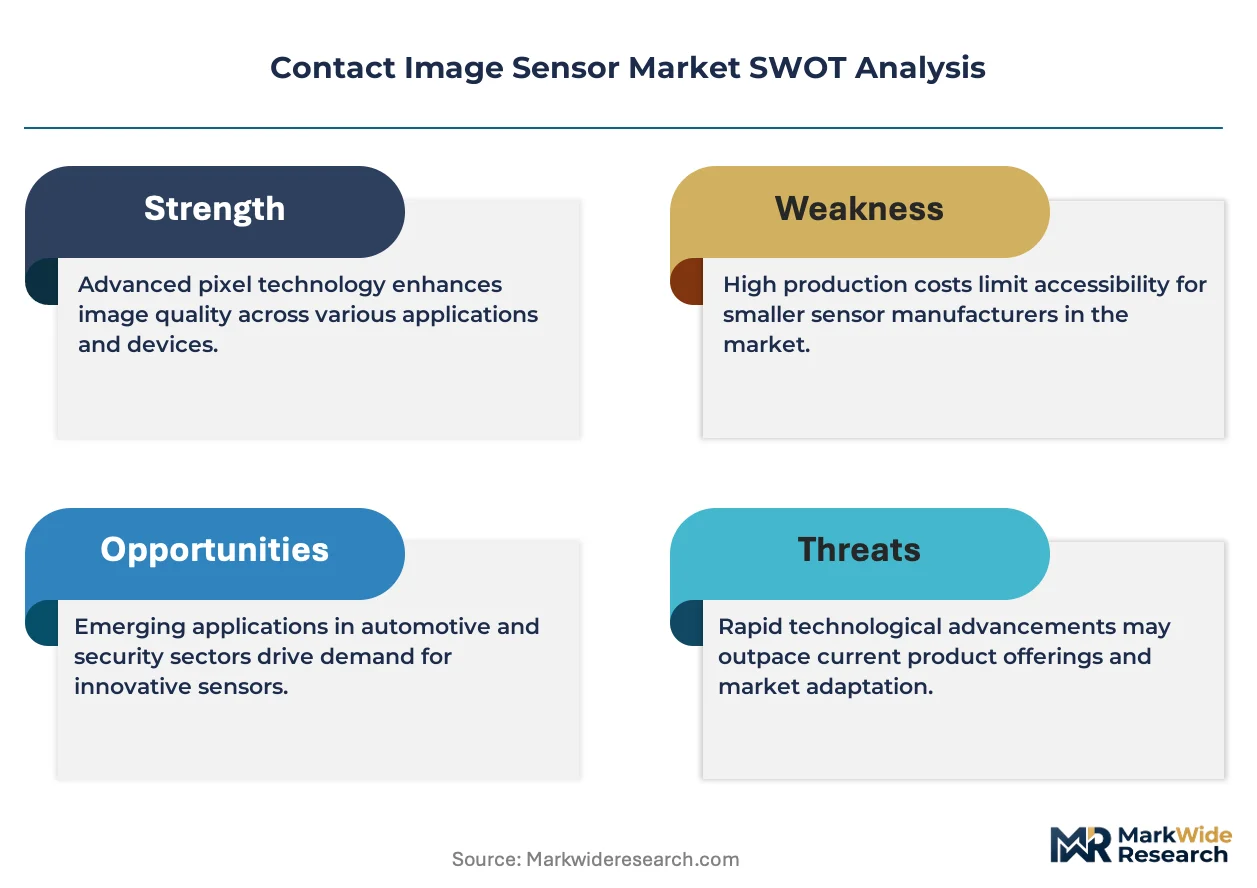
Photonics engineering talent scarcity is reorganizing how contact image sensor fabs allocate capacity between legacy and advanced product lines. Canon Inc. leverages its vertical integration into optical component fabrication to sustain margin control across document scanning applications. Sony Corporation anchors high-resolution sensor development through captive CMOS process technology. STMicroelectronics N.V. competes in industrial imaging by specializing in ruggedized sensor architectures for factory automation environments.
A contact image sensor is a compact optoelectronic device that integrates a linear or area array of photodiodes with a rod lens array and illumination source in a single sealed module, typically achieving optical resolutions from 200 to 1200 dots per inch for direct-contact image acquisition. The technology serves document digitization, barcode reading, and flat-surface inspection by eliminating the depth-of-field constraints of conventional lens-based imaging systems. Linear sensors dominate document scanning volumes due to established cost curves and mechanical simplicity in feed-through architectures. CMOS technology is displacing CCD in new designs as on-chip integration reduces peripheral component count and power dissipation. Color sensors command premium positioning in medical diagnostics and security applications where multispectral discrimination determines functional value.
The US FDA regulates contact image sensors deployed in medical diagnostics through device classification and quality system requirements, while the EPA restricts hazardous substances in sensor manufacturing through RoHS-aligned substance controls. Japan's METI enforces JIS standards on electromagnetic compatibility and reliability testing for domestic imaging equipment procurement. China's MIIT mandates GB standard compliance for network-connected scanning devices accessing government and enterprise systems. Stakeholders must monitor how divergent cybersecurity certification requirements across FDA, METI, and MIIT jurisdictions fragment product platform strategies and force region-specific firmware configurations.
Market Dynamics
Photonics engineering talent shortages are forcing contact image sensor fabs to ration capacity between legacy document scanning lines and emerging medical imaging products. This scarcity is compressing lead times for high-resolution CMOS designs while CCD obsolescence accelerates.
Growth Catalysts
- Enterprise Digitization:Document scanning workflows in banking and legal services consume linear sensor volumes as paper-to-digital mandates tighten.
- MIIT Domestic Content Rules:China's network-connected scanner certification requirements are pulling GB-compliant sensor procurement toward domestic assembly partners.
- CMOS Process Migration:On-chip integration of analog-to-digital converters reduces peripheral component counts and power budgets for portable scanning devices.
Market Restraints
- Silicon Wafer Input Volatility:300mm wafer spot pricing fluctuations compress foundry margins for sensor dice below 200mm equivalent thresholds.
- Seoul-Incheon Cluster Concentration:South Korea's display component ecosystem anchors 70% of advanced rod lens array supply, creating single-source vulnerability.
- Optical Resolution Ceiling:Rod lens aberration limits at 1200 DPI constrain medical pathology applications requiring sub-micron feature discrimination.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme benefits for electronics assembly are attracting sensor module packaging investments away from traditional ASEAN hubs.
- Multispectral Medical Diagnostics:Color sensor arrays with narrow-band LED illumination enable non-invasive tissue analysis in dermatology and dentistry.
- Industrial Barcode Convergence:Machine vision integration with RFID interrogation creates unified track-and-trace platforms for pharmaceutical supply chains.
Industry Challenges
- Photonics Design Talent Scarcity:Compound semiconductor process engineers command 40% wage premiums, constraining R&D headcount expansion at mid-tier sensor houses.
- Cross-Jurisdiction Certification Timelines:FDA 510(k) clearance for diagnostic sensors runs 18-24 months parallel to METI JIS electromagnetic testing, fragmenting product launch synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Image Sensor Market |
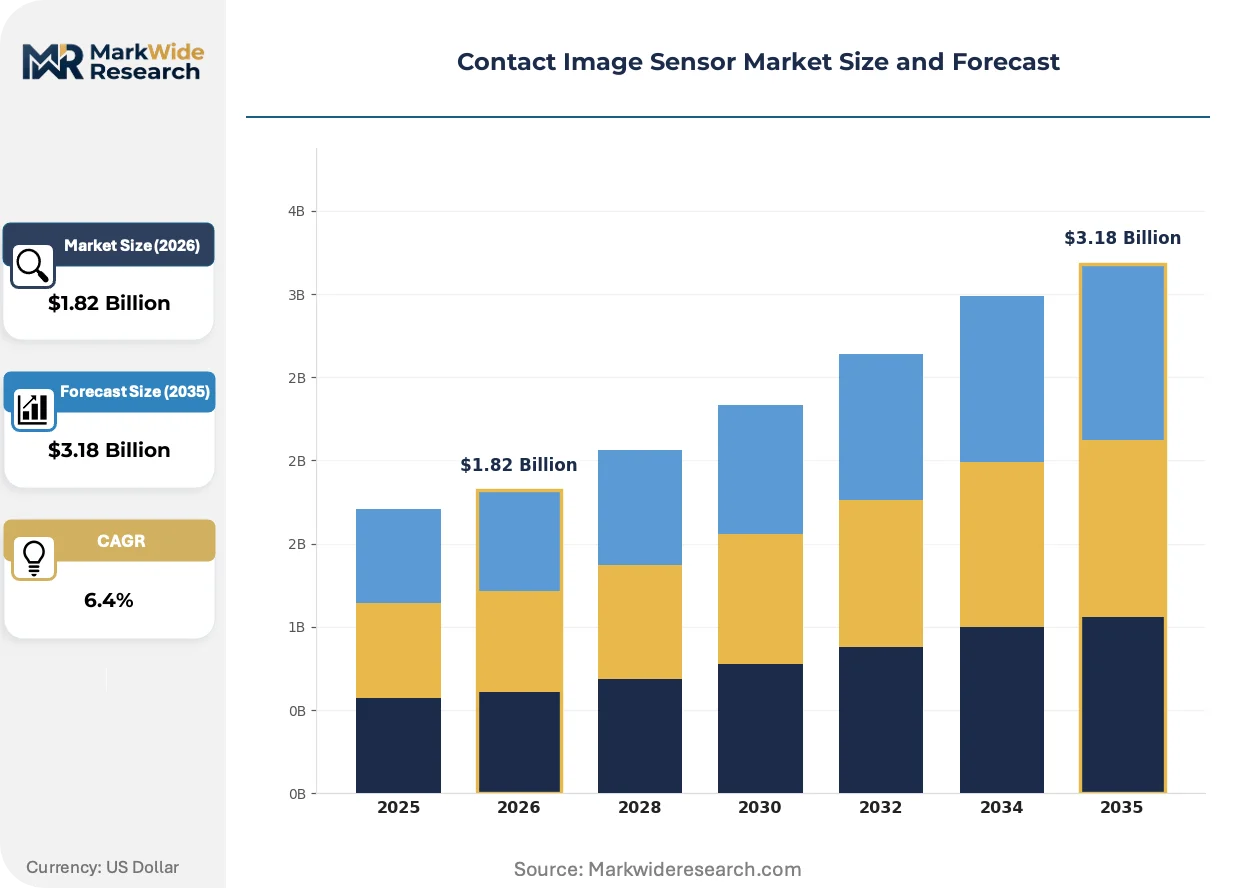
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Sensors, Area Sensors, Monochrome Sensors, Color Sensors Technology: CMOS, CCD, Photodiode, Hybrid Application: Document Scanning, Industrial Imaging, Medical Diagnostics, Security Systems End User: Manufacturing, Healthcare, Retail, Education |
| Companies Covered | Canon Inc., OmniVision Technologies Inc., Panasonic Corporation, Samsung Electronics Co. Ltd, Sony Corporation, STMicroelectronics N.V, Teledyne DALSA Inc., Infineon Technologies AG, Himax Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Image Sensor Market Strategic Shifts
Contact image sensor architecture is bifurcating between cost-optimized document scanning modules and precision medical imaging systems. This divergence is fragmenting supplier bases and compressing development cycles for intermediate performance tiers.
CMOS active-pixel sensor technology is fragmenting the incumbent CCD installed base across flatbed and sheet-fed scanner designs. Office equipment OEMs in Japan and Germany are transitioning new product platforms to CMOS within 24-month refresh cycles. The shift is compressing CCD wafer starts at legacy foundries while expanding CMOS design service demand.
Japan's METI JIS C 61000 electromagnetic compatibility standards are tightening conducted emission limits for network-connected imaging equipment. Domestic scanner manufacturers must redesign power supply filtering and shielding architectures to maintain procurement eligibility for government contracts. The regulation is accelerating ferrite component integration and PCB layout revisions across product lines.
Buyer consolidation among enterprise document management providers is compressing sensor vendor negotiation leverage. Large scanning fleet operators in North America and Europe are unbundling hardware procurement from maintenance contracts, forcing module suppliers to compete on dice cost rather than system integration value. The shift is most visible in financial services and insurance verticals with centralized IT procurement functions.
Contact Image Sensor Market Segmentation
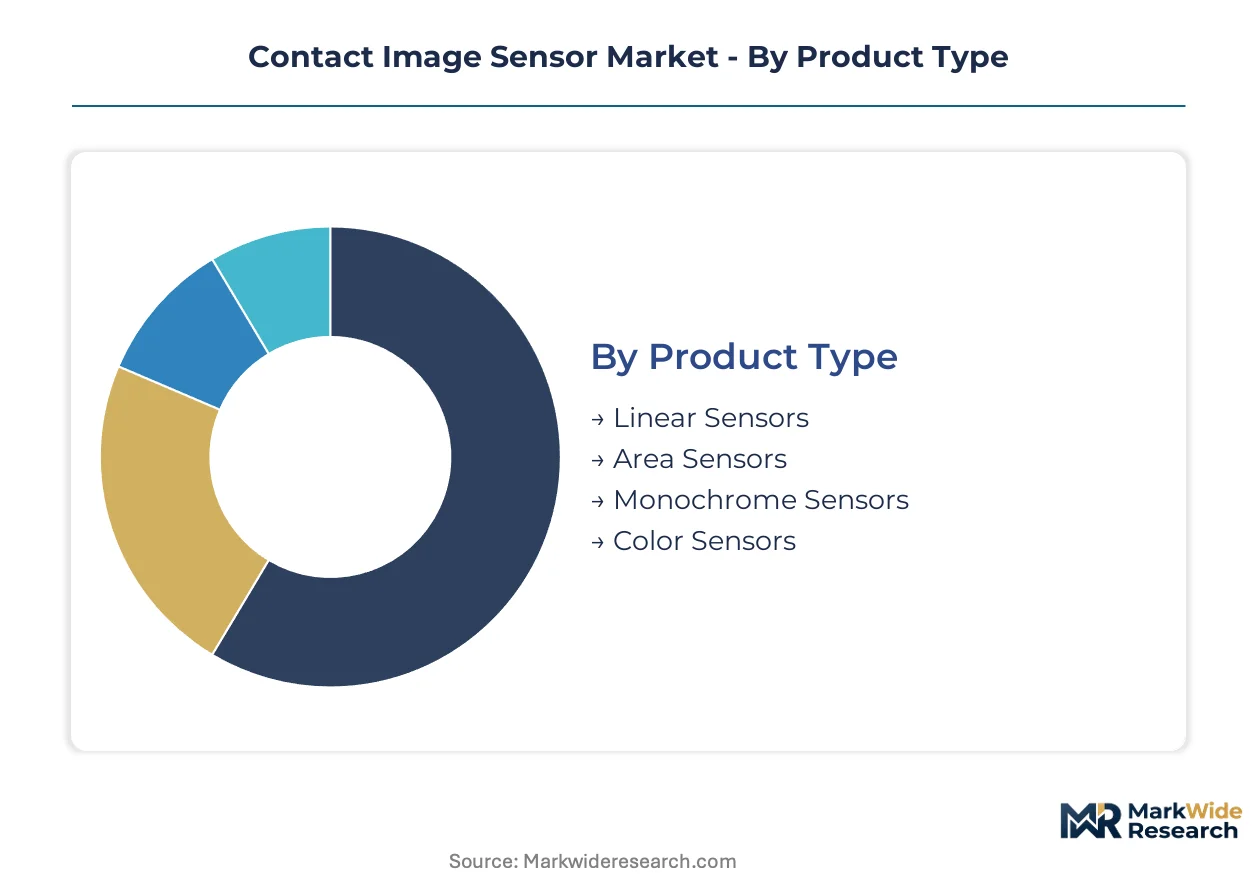
Contact image sensor architectures diverge sharply between cost-driven document scanning and precision medical imaging, fragmenting supplier bases and compressing development cycles for intermediate tiers. Understanding segment boundaries reveals where CMOS migration, regulatory certification, and end-user consolidation are reshaping competitive economics.
Product Type:
Margin pools concentrate in color sensor variants where multispectral discrimination commands premium positioning in medical and security applications, while monochrome sensors compete on die cost in high-volume document processing.
- Linear Sensors:These integrate photodiode arrays with rod lens systems in sealed modules optimized for feed-through document architectures. Banking and legal services procurement in North America and Europe consumes the majority of volumes as paper-to-digital mandates tighten compliance requirements.
- Color Sensors:Narrow-band LED illumination enables multispectral tissue analysis in dermatology and dentistry applications. Demand clusters in Japan's diagnostic equipment sector where METI procurement standards favor domestic sensor assembly.
- Area Sensors:Two-dimensional photodiode matrices serve flat-surface inspection and machine vision applications.
- Monochrome Sensors:Single-channel photodiode arrays minimize die cost for high-speed barcode reading and basic document capture.
The dominant share belongs to Linear Sensors, while Color Sensors is closing the gap fastest.
Technology:
Cost tier differentiation separates CMOS designs with on-chip integration from legacy CCD architectures facing foundry obsolescence.
- CMOS:Active-pixel technology embeds analog-to-digital converters and timing circuits on-die, slashing peripheral component counts. Japan and Germany office equipment OEMs are transitioning new platforms within 24-month refresh cycles, compressing CCD wafer starts at legacy foundries.
- CCD:Charge-coupled device technology retains installed base in high-end flatbed scanners but suffers from power dissipation and external driver requirements. Foundry capacity rationing between legacy lines and emerging medical products is accelerating CMOS displacement.
- Photodiode:Discrete photodiode arrays serve cost-sensitive applications with minimal signal processing requirements.
- Hybrid:Mixed-signal architectures combine CMOS readout with specialized photodiode structures for industrial environments.
CMOS holds the dominant technology position, while Hybrid designs are expanding most quickly in factory automation segments.
Application:
Volume concentration in document scanning contrasts with value concentration in medical diagnostics where FDA and METI certification barriers protect margin structures.
- Document Scanning:Linear sensor modules dominate banking, insurance, and legal enterprise digitization workflows. Buyer consolidation among North American and European fleet operators is compressing vendor negotiation leverage and forcing competition on dice cost.
- Medical Diagnostics:High-resolution color sensors with sub-micron feature discrimination serve pathology and dermatology applications. FDA 510(k) clearance timelines running 18-24 months parallel to METI electromagnetic testing fragment product launch synchronization.
- Industrial Imaging:Ruggedized sensor architectures withstand factory automation environments with vibration and temperature extremes.
- Security Systems:Multispectral sensors enable document authentication and biometric capture in border control and financial transaction verification.
Document Scanning retains the dominant application share, while Medical Diagnostics is climbing the fastest on diagnostic equipment upgrade cycles.
End User:
Customer type determines procurement modality, with centralized healthcare and manufacturing IT functions demanding system integration value while retail and education segments prioritize hardware cost.
- Manufacturing:Factory automation and pharmaceutical track-and-trace systems consume industrial-grade sensors with machine vision integration. Machine vision convergence with RFID interrogation creates unified platforms for supply chain verification.
- Healthcare:Diagnostic equipment OEMs in Japan, Germany, and the United States specify color sensors with narrow-band LED illumination for non-invasive tissue analysis. Regulatory certification requirements across FDA, METI, and MIIT jurisdictions force region-specific firmware configurations.
- Retail:Point-of-sale and inventory management systems deploy cost-optimized linear sensors for barcode capture.
- Education:Institutional document digitization projects favor monochrome sensors in high-volume scanning deployments.
Manufacturing commands the dominant end-user position, while Healthcare is gaining share fastest on diagnostic imaging upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's precision component cluster while Chinese assemblers compete on module cost, creating a regional asymmetry that shapes procurement patterns across enterprise digitization and medical imaging verticals.
United States
Enterprise document management providers and healthcare diagnostic OEMs drive sensor procurement for banking digitization and pathology equipment. FDA 510(k) clearance timelines extend 18-24 months for medical-grade designs, compressing product launch windows. Boston and Minneapolis anchor medical device engineering clusters where diagnostic equipment manufacturers specify high-resolution color architectures.
Japan
Office equipment manufacturers and diagnostic imaging specialists consume precision sensor modules for document scanners and dermatology systems. METI enforces JIS C 61000 electromagnetic compatibility standards that mandate ferrite integration and PCB shielding revisions. The Kanto region around Tokyo hosts concentrated optical component engineering talent and rod lens array fabrication.
China
Network-connected scanner certification requirements under MIIT GB standards pull procurement toward domestic assembly partners. Government and enterprise system mandates accelerate GB-compliant module sourcing. The Yangtze River Delta manufacturing corridor houses expanding sensor packaging investments serving both domestic demand and export assembly.
Germany
Industrial automation and pharmaceutical track-and-trace systems consume ruggedized sensor architectures for factory floor environments. REACH substance controls and CE marking requirements constrain material selection in module housings. Bavaria's precision engineering corridor around Munich anchors machine vision integration with RFID interrogation platforms.
South Korea
Display component ecosystems and imaging module packaging concentrate demand in the Seoul-Incheon corridor. The cluster anchors 70% of advanced rod lens array supply, creating single-source vulnerability for global scanner manufacturers. Local foundries ration capacity between legacy document scanning lines and emerging medical imaging products.
Contact Image Sensor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated optical specialists commanding premium positioning while modular assemblers compete on die cost. The vendor base organizes around three strategic tiers: captive CMOS foundries with in-house process technology, precision optics houses with rod lens integration capabilities, and fabless design houses sourcing from merchant foundries. Dominant competitive moves include backward integration into optical component fabrication and geographic expansion toward India PLI scheme incentives.
Within the precision optics tier, Canon Inc. and Sony Corporation exemplify divergent strategic positions. Canon's in-house production of optical components sustains margin control across document scanning applications. Sony anchors high-resolution development through captive CMOS process technology. STMicroelectronics N.V. occupies a position in industrial imaging by specializing in ruggedized architectures for factory automation environments.
| Leading Market Players |
|---|
| Canon Inc. |
| OmniVision Technologies Inc. |
| Panasonic Corporation |
| Samsung Electronics Co. Ltd |
| Sony Corporation |
| STMicroelectronics N.V |
| Teledyne DALSA Inc. |
| Infineon Technologies AG |
| Himax Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Seoul-Incheon rod lens foundries lock in both supply access and price visibility for scanner OEMs, insulating procurement teams from spot volatility while committing volumes to South Korea's concentrated optical component cluster.
Pricing Analysis
Customization-premium spreads separate configured-to-order medical imaging sensors from standard document scanning modules. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA 510(k) cleared designs commanding substantial premiums over uncertified commercial variants. Cost compression in monochrome linear sensors is intensifying because buyer consolidation among North American fleet operators forces die-cost competition. Healthcare diagnostic OEMs exhibit least price sensitivity due to regulatory switching costs, while education sector procurement shows highest elasticity.
Supply Chain Analysis
Rod lens array fabrication chokepoints in the Seoul-Incheon corridor anchor seventy percent of advanced optical component supply for global scanner manufacturers. Manufacturing draws from South Korean foundry capacity, Japanese precision glass processing, and Chinese module assembly. Single-source vulnerability in rod lens supply creates structural risk for OEMs dependent on Korean optical component ecosystems. Distribution runs through direct OEM contracts for high-volume enterprise scanning fleets and regional distributors serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonics engineering talent scarcity constrains capacity expansion across CMOS sensor foundries and rod lens array fabrication, compressing development timelines for mid-tier suppliers unable to match wage premiums commanded by compound semiconductor specialists.
For Market Incumbents: Fortify captive CMOS process technology through backward integration into photodiode design services, defending against fabless entrants exploiting merchant foundry capacity. Prioritize certification investment in FDA 510(k) and METI JIS electromagnetic compliance to maintain procurement eligibility in government healthcare contracts. Expand capacity reservation agreements with Seoul-Incheon optical component suppliers to lock in rod lens access against single-source vulnerability. For New Entrants and Emerging Players: Differentiate on narrow-band LED illumination architectures for multispectral medical diagnostics, exploiting white-space in dermatology and dentistry sensor applications. Target India's PLI scheme electronics assembly incentives for sensor module packaging investments, penetrating the most penetrable geography outside established ASEAN hubs. Pursue hospital system partnership go-to-market angles with diagnostic equipment OEMs in Japan and Germany seeking second-source sensor suppliers. For Investors and Strategic Acquirers: Fabless design houses with CMOS imaging IP and established METI certification pathways represent compelling acquisition targets for industrial conglomerates seeking imaging technology adjacencies. Long-term viability hinges on regulatory moat sustainability and foundry access security across the projection horizon. Monitor FDA 510(k) clearance backlog durations as inflection indicator for medical imaging sensor pricing power and competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Component Fabrication | Canon Inc.'s in-house rod lens production sustains margin control against Seoul-Incheon supply concentration. |
| CMOS Process Migration Investment | On-chip ADC integration reduces peripheral component counts for Japan and Germany office equipment OEMs. |
| India PLI Scheme Manufacturing Expansion | Sensor module packaging investments shift from ASEAN hubs toward Indian electronics assembly corridors. |
| FDA 510(k) Certification Acceleration | Diagnostic sensor clearance timelines determine competitive positioning in North American pathology equipment. |
| Multispectral LED Illumination Development | Narrow-band architectures enable non-invasive tissue analysis in Japan's dermatology diagnostic sector. |
Study Parameters
Operator-level perspectives from photonics design engineers, scanner OEM procurement directors, diagnostic equipment product managers, and foundry capacity planners anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, METI JIS certification registries, FDA 510(k) clearance databases, and customs trade data. Bottom-up sensor volume modeling triangulated against top-down enterprise digitization spend analysis.
Sensitivity analysis around wafer pricing volatility, talent availability scenarios, and regulatory timeline variations shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, technology node, application vertical, and end-user procurement modality. CAGRs derived from regression against historical CMOS displacement patterns and medical imaging equipment upgrade cycles, with rod lens supply constraints and MIIT domestic content rules as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor fabrication talent supply and stable Korea-Japan optical component trade flows would require recalibration. Forecasts reflect documented assumptions regarding CMOS migration velocity and certification timeline stability. Practitioners should keep alternative scenarios live as FDA backlog durations and METI electromagnetic standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Global Image Processing Systems Market
Imaging
Europe Image Sensors Market
Imaging
Low-Light Imaging Market
Imaging
Hybrid Imaging Systems Market
Imaging
CCD Image Sensors Market
Imaging
Microscopic Camera Market
Imaging
Plenoptic Camera Market
Imaging
X-Ray Market
Imaging
SDI Camera Market
Imaging
Video Processing Solutions Market
Imaging
Live Cell Imaging Market
Imaging
X Ray Tubes Market
Imaging
Global Automotive Imaging Market
Imaging
Underwater Camera Market