
 Taiwan Optoelectronics Market | 2026-2036
Taiwan Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Optoelectronics Market Insights
Market Context with Strategic Players
Photonics engineering talent pipelines is collapsing as universities struggle to replenish specialists trained in III-V compound semiconductor processing. LITE-ON Technology Corporation sustains domestic LED packaging dominance through captive phosphor formulation labs in Miaoli. Sony Corporation competes in CMOS image sensor supply to Taiwanese smartphone assemblers via foundry partnerships. Texas Instruments anchors analog optoelectronic component demand by controlling laser driver IC distribution channels across Kaohsiung industrial zones.
Technical Definition and Structural Segments
Optoelectronics encompasses devices that interconvert electrical and optical signals, typically fabricated from gallium arsenide, indium phosphide, or gallium nitride substrates with epitaxial layer thicknesses measured in nanometers; these components enable fiber-optic data transmission, solid-state illumination, and machine vision detection in automated manufacturing. LED products within the product type category dominate unit volume but face margin compression as epitaxial wafer costs fluctuate with rare earth supply constraints. Quantum dot technology within the technology dimension captures premium positioning for display backlighting applications, while optical sensors within the product type segment expand fastest as Taiwanese semiconductor equipment makers embed real-time metrology into lithography tools.
Regulatory Framework and Forward Outlook
Taiwan's Bureau of Standards, Metrology and Inspection enforces CNS certification for LED luminaires, while the Industrial Development Bureau administers optoelectronics industry subsidies under the Statute for Industrial Innovation; these frameworks compel domestic manufacturers to maintain IEC-compliant testing laboratories for export market access. The National Communications Commission regulates laser product emissions for telecommunications equipment deployment. Stakeholders must monitor how the Ministry of Economic Affairs recalibrates domestic content requirements for photonics procurement in defense and space applications.
Market Dynamics
Semiconductor equipment makers in Hsinchu Science Park are embedding optical sensors directly into lithography tools, creating captive demand that bypasses traditional distribution channels and compresses procurement cycles for discrete component suppliers.
Growth Catalysts
- Green Energy Retrofit Mandates:Taiwan's Industrial Development Bureau enforces LED upgrade requirements across public infrastructure, generating sustained replacement demand for solid-state illumination modules.
- Compound Semiconductor Talent Pipelines:Universities struggle to replenish III-V processing specialists, yet government subsidies under the Statute for Industrial Innovation fund dedicated photonics training centers in Miaoli and Tainan.
- Optical Sensor Integration:Taiwanese foundry equipment suppliers embed real-time metrology into process control systems, pulling demand for precision photonic components away from general-purpose distributors.
Market Restraints
- Rare Earth Supply Volatility:Epitaxial wafer costs fluctuate with dysprosium and terbium availability, squeezing margins on packaged LED products despite stable end-use pricing.
- CMOS Image Sensor Substitution:Sony Corporation's foundry partnerships enable smartphone assemblers to source high-performance imaging chips without domestic optical component procurement.
- Laser Emission Certification Friction:Taiwan's National Communications Commission imposes extended testing timelines for telecommunications laser products, delaying revenue recognition for new designs.
Strategic Opportunities
- Defense and Space Procurement:The Ministry of Economic Affairs recalibrates domestic content requirements for photonics in aerospace applications, opening captive demand streams for qualified suppliers.
- Quantum Dot Display Convergence:Premium backlighting applications combine nanocrystal phosphors with GaN epitaxy, creating technology licensing opportunities beyond traditional LED packaging.
- Kaohsiung Industrial Zone Channel Innovation:Texas Instruments' laser driver IC distribution networks enable direct-to-factory component supply, bypassing legacy electronics distributor markups for analog optoelectronic modules.
Industry Challenges
- III-V Processing Skill Scarcity:Photonics foundries cluster near TSMC supply partners in Hsinchu, yet molecular beam epitaxy technicians command premiums that inflate fixed manufacturing overhead.
- IEC Laboratory Capex Burden:CNS certification for LED luminaires requires Bureau of Standards, Metrology and Inspection-compliant testing facilities, forcing mid-tier suppliers to outsource validation or absorb facility depreciation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Optoelectronics Market |
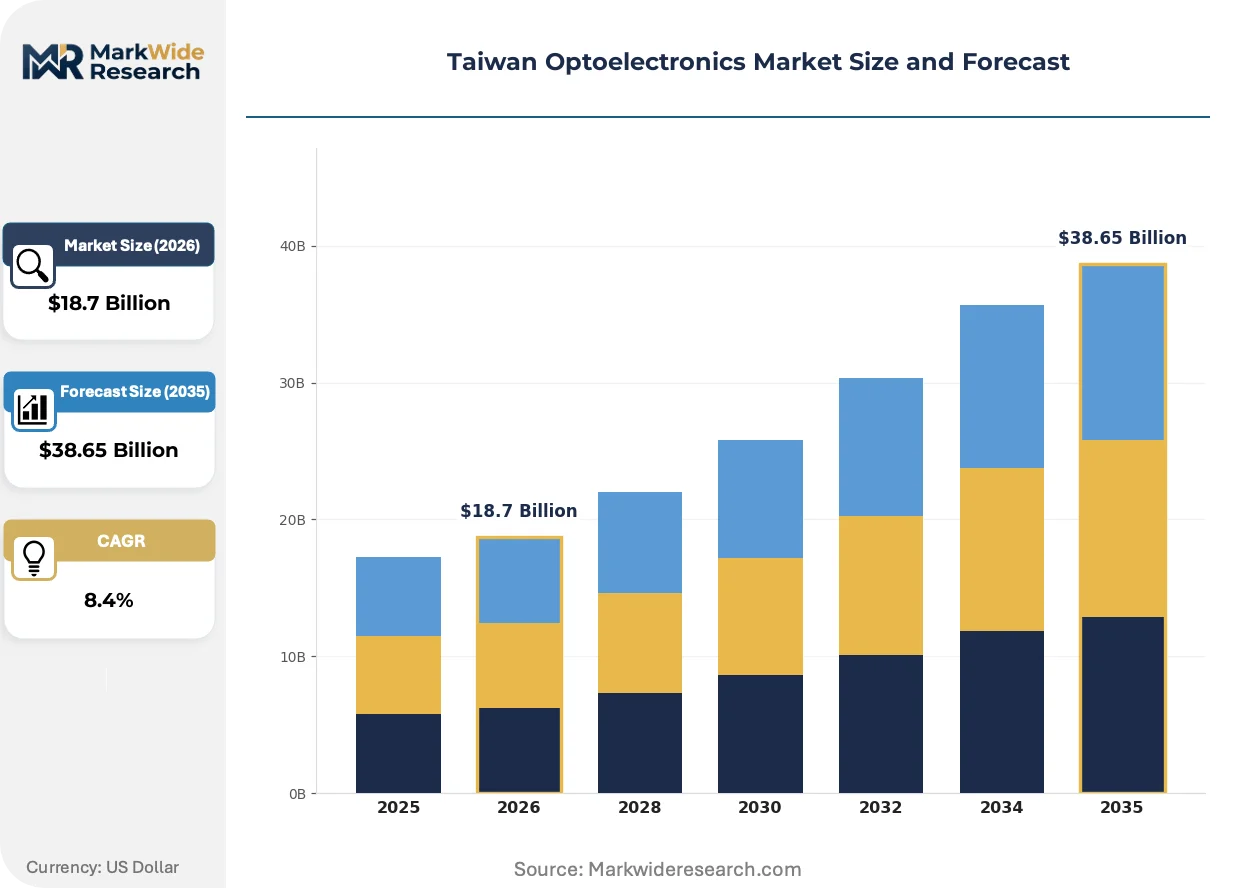
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diodes, Photodetectors, Optical Sensors Application: Display Technology, Communication Systems, Lighting Solutions, Imaging Systems End User: Consumer Electronics, Automotive Industry, Telecommunications, Medical Devices Technology: Thin-Film, Bulk, Hybrid, Quantum Dot |
| Companies Covered | ams Osram AG, Omnivision Technologies Inc, Broadcom Inc, Vishay Intertechnology Inc, Panasonic Corporation, Samsung Electronics Co Ltd, Sony Corporation, LITE-ON Technology Corporation, Texas Instruments Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Optoelectronics Market Trends and Innovations
Photonics engineering workflows are fragmenting across specialized process nodes, with equipment automation and regulatory compliance emerging as distinct competitive axes that separate integrated foundries from packaging specialists.
Miniaturized optical interconnects for co-packaged optics is bifurcating the traditional transceiver market. Data center operators in Taipei and Taoyuan demand sub-watt pluggable modules for AI training clusters. This technology is compressing margins on legacy 400G QSFP designs while enabling premium pricing for co-packaged solutions.
Taiwan's Bureau of Standards, Metrology and Inspection expanded CNS certification scope to cover laser safety in industrial automation equipment. Manufacturers must now maintain dual testing protocols for domestic and export markets. LED luminaire producers face the steepest compliance burden as they retool laboratories for IEC 60825-1 alignment.
Component sourcing patterns among Taiwanese smartphone assemblers now favor consolidated procurement of CMOS image sensor modules over discrete optical component purchasing. Module suppliers capture value previously distributed across lens, filter, and driver vendors. This consolidation is most visible in Taichung precision manufacturing corridors where camera module integrators dominate supplier qualification processes.
Taiwan Optoelectronics Market Segmentation
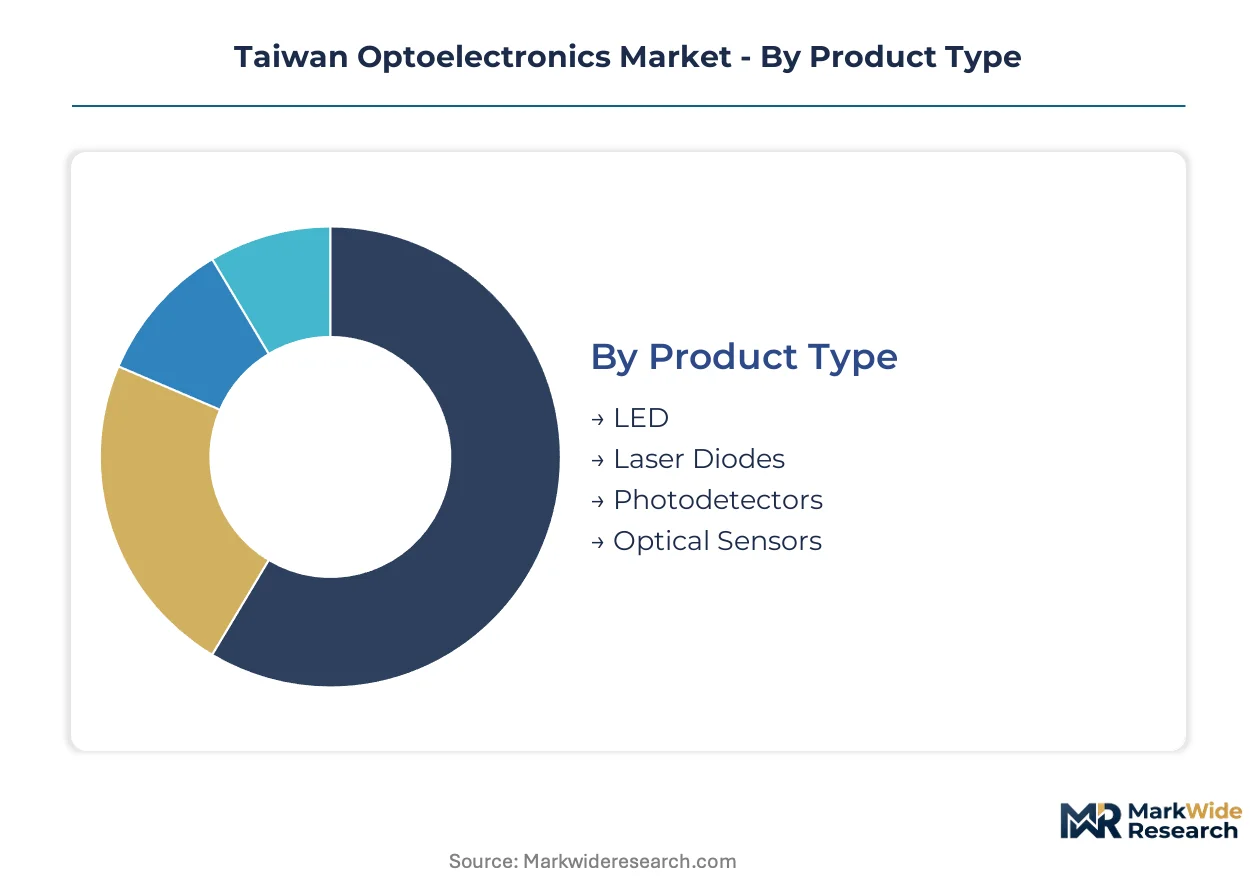
Segmentation reveals how substitution pressures and supply chain concentration reshape competitive positioning across Taiwan's optoelectronics landscape. Discrete component categories face divergent margin trajectories based on integration depth and foundry proximity.
Product Type:
Optical Sensors face the most acute substitution threat as semiconductor equipment makers embed metrology functions directly into process tools, bypassing discrete component procurement.
- LED:Solid-state illumination devices fabricated on sapphire or silicon carbide substrates with GaN epitaxy. Public infrastructure retrofit mandates in Taipei and Kaohsiung generate sustained replacement demand despite rare earth phosphor cost volatility.
- Optical Sensors:Photonic detectors enabling real-time position and intensity measurement in automated manufacturing. Hsinchu Science Park lithography equipment suppliers pull demand into captive supply chains, compressing distributor margins.
- Laser Diodes:Coherent light sources for telecommunications and industrial cutting applications.
- Photodetectors:Semiconductor devices converting optical signals to electrical current in fiber-optic receivers.
LED anchors the volume base while Optical Sensors gains share at the steepest rate.
Application:
Cost tier differentiation separates premium co-packaged optical interconnects from commoditized legacy transceiver modules in data center deployments.
- Communication Systems:Fiber-optic transmission infrastructure and 5G fronthaul networks. Taoyuan data center operators demand sub-watt pluggable modules for AI training clusters, bifurcating procurement between legacy and advanced form factors.
- Display Technology:Backlighting and direct-view emissive panels for consumer and commercial screens. Quantum dot enhancement films command premium positioning in Miaoli packaging corridors.
- Lighting Solutions:Solid-state illumination for residential, commercial, and municipal installations.
- Imaging Systems:Machine vision and photographic capture subassemblies.
Communication Systems captures the highest absolute spending while Display Technology expands most quickly through quantum dot convergence.
End User:
Customer concentration patterns concentrate procurement leverage in smartphone assemblers, who now favor consolidated CMOS module sourcing over discrete optical component purchasing.
- Consumer Electronics:Smartphones, tablets, and wearable devices requiring compact imaging and sensing subsystems. Taichung precision manufacturing corridors host camera module integrators who dominate supplier qualification processes.
- Telecommunications:Network infrastructure operators and equipment manufacturers. National Communications Commission laser emission certification timelines delay revenue recognition for new telecommunications designs.
- Automotive Industry:LiDAR, interior lighting, and driver monitoring systems.
- Medical Devices:Diagnostic imaging and surgical illumination equipment.
Consumer Electronics anchors the volume base while Automotive Industry climbs the fastest on LiDAR penetration.
Technology:
Manufacturing maturity separates volume-scaled thin-film deposition from emerging nanocrystal formulations requiring specialized epitaxy capabilities.
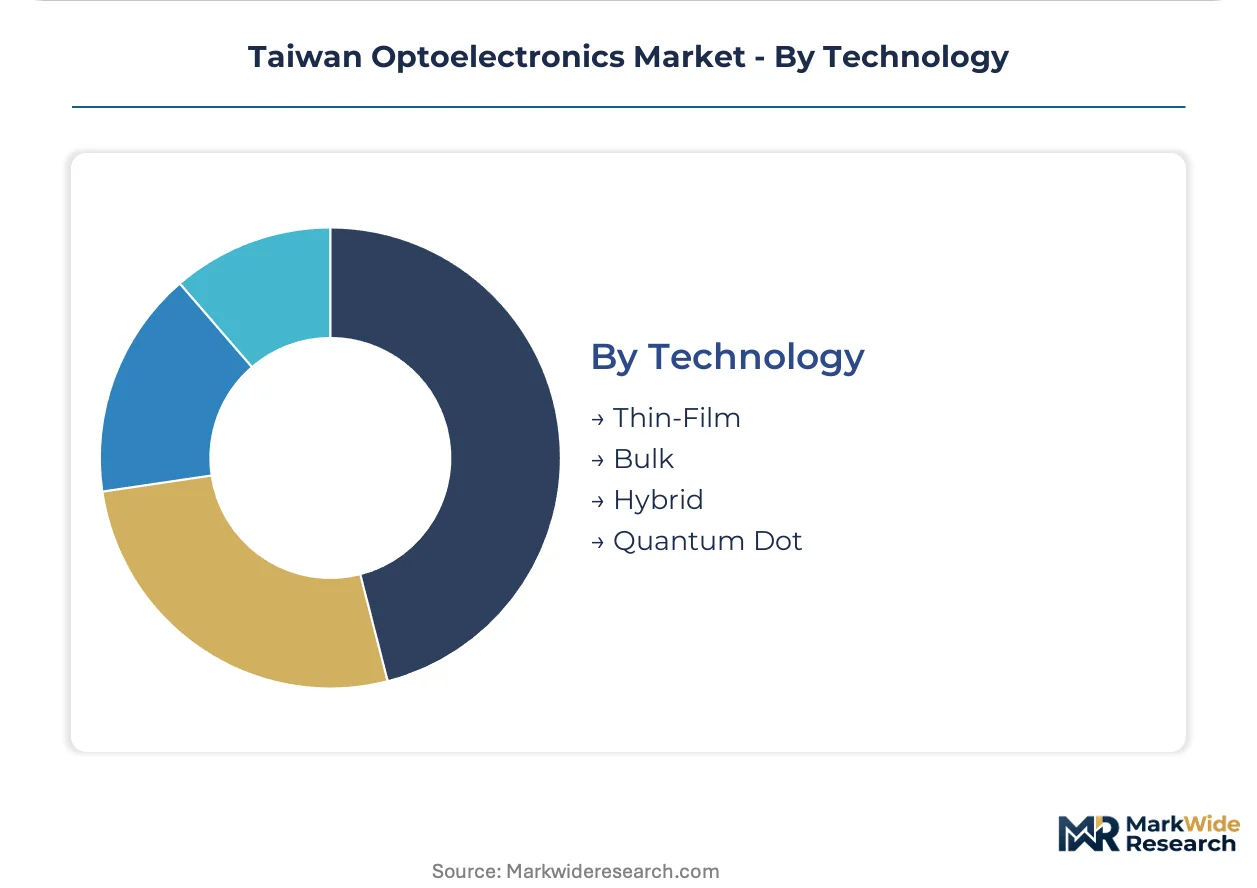
- Quantum Dot:Nanocrystal phosphors enabling tunable emission spectra with narrow full-width half-maximum. Premium backlighting applications in display technology create licensing opportunities beyond traditional LED packaging.
- Thin-Film:Epitaxial layer deposition with precise thickness control for LED and laser fabrication. Hsinchu photonics foundries cluster near TSMC supply partners, concentrating molecular beam epitaxy technician demand.
- Bulk:Conventional substrate-based fabrication for high-power applications.
- Hybrid:Multi-material integration combining organic and inorganic active layers.
Thin-Film dominates current manufacturing throughput while Quantum Dot shows the steepest expansion trajectory on display premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Bureau of Standards, Metrology and Inspection anchors the regulatory framework governing optoelectronics deployment across the island's industrial zones. The Industrial Development Bureau administers subsidies under the Statute for Industrial Innovation, directing investment toward Hsinchu and Tainan photonics corridors.
Northern Taiwan
Hsinchu Science Park concentrates molecular beam epitaxy foundries serving TSMC supply partners with real-time process control sensors. The National Communications Commission regulates laser emission standards for telecommunications equipment manufactured here. Photonics engineering talent scarcity inflates technician premiums across this cluster.
Central Taiwan
Taichung precision manufacturing corridors host camera module integrators who consolidated procurement leverage over discrete optical component vendors. The Ministry of Economic Affairs recalibrates domestic content requirements for defense applications, opening captive demand streams. Miaoli packaging corridors specialize in quantum dot enhancement films for display backlighting.
Southern Taiwan
Kaohsiung industrial zones anchor analog optoelectronic component distribution through laser driver IC channels. The Industrial Development Bureau enforces LED retrofit mandates across municipal infrastructure here. Tainan photonics training centers receive Statute for Industrial Innovation funding to replenish III-V processing specialists.
Western Taiwan Corridor
Taoyuan data center operators demand sub-watt pluggable optical interconnects for AI training clusters, bifurcating procurement between legacy and advanced form factors. The Bureau of Standards, Metrology and Inspection expanded CNS certification scope to cover laser safety in industrial automation equipment manufactured across this corridor.
Taiwan Optoelectronics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Taiwan's optoelectronics value chain. The vendor base clusters around three strategic tiers: integrated foundries with captive epitaxy capabilities, packaging specialists controlling phosphor formulation, and component distributors anchoring analog module supply. Consolidation pressures concentrate in the optical sensor segment, where semiconductor equipment makers embed metrology functions directly into process tools. Competitive moves center on backward integration into rare earth phosphor supply and technology licensing for quantum dot display convergence.
Within the integrated foundry tier, LITE-ON Technology Corporation and Texas Instruments Inc occupy positions reflecting divergent strategic orientations toward domestic packaging dominance versus analog component distribution control. Sony Corporation sits within the imaging module supplier archetype, leveraging foundry partnerships to serve Taiwanese smartphone assemblers without domestic optical component procurement. These three companies exemplify how technology specialization and channel configuration separate premium-positioned players from scale-driven competitors in this market.
| Leading Market Players |
|---|
| ams Osram AG |
| Omnivision Technologies Inc |
| Broadcom Inc |
| Vishay Intertechnology Inc |
| Panasonic Corporation |
| Samsung Electronics Co Ltd |
| Sony Corporation |
| LITE-ON Technology Corporation |
| Texas Instruments Inc |
| Others |
Pricing and Supply Chain Analysis
CNS certification for LED luminaires gates both supplier qualification and price tiering simultaneously, forcing manufacturers to absorb laboratory capex before accessing premium municipal procurement channels while compressing margins on uncertified economy-grade products.
Pricing Analysis
Kaohsiung industrial zones command higher delivered prices than Miaoli packaging corridors due to laser driver IC bundling requirements. Three-tier pricing structure across premium, standard, and economy levels separates IEC-compliant laboratory-tested products from basic CNS-certified modules and uncertified imports. Pricing pressure stems from rare earth phosphor cost volatility in LED epitaxial wafer supply. Municipal infrastructure buyers show lowest price sensitivity due to green energy mandate compliance deadlines, while consumer electronics assemblers squeeze component suppliers hardest.
Supply Chain Analysis
Taiwan and Japan anchor epitaxial wafer fabrication and phosphor formulation respectively, with South Korea supplying sapphire substrates for GaN LED production. The supply chain draws from dysprosium and terbium rare earth deposits concentrated in Chinese processing facilities. Single-source vulnerability concentrates in molecular beam epitaxy equipment where Hsinchu foundries compete for limited technician pools. Distribution runs through direct-to-factory channels for analog optoelectronic modules and legacy electronics distributors for discrete photonic components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's optoelectronics market is emerging from a cyclical trough as semiconductor capital expenditure recovery pulls demand for embedded optical sensors through Hsinchu equipment supply chains.
For Market Incumbents: Shield packaged LED margins by backward integration into captive phosphor formulation labs in Miaoli, countering rare earth cost volatility that erodes standard-tier profitability. Lock in multi-year municipal retrofit contracts before Bureau of Standards expands CNS certification scope to additional product categories, raising compliance barriers for mid-tier competitors. For New Entrants and Emerging Players: Differentiate on quantum dot display convergence by licensing nanocrystal phosphor technology to Miaoli packaging specialists seeking premium backlighting positioning. Target defense and space procurement channels where Ministry of Economic Affairs domestic content recalibration opens qualification windows for qualified suppliers without established foundry relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across optical sensor metrology as semiconductor equipment makers embed real-time process control functions, favoring asset-light technology licensors over fab-dependent component manufacturers. Target acquisition archetypes include III-V processing training centers in Tainan with Statute for Industrial Innovation funding commitments. Watch for inflection when Bureau of Standards announces laser safety certification scope expansion beyond industrial automation equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Supply | Captive rare earth formulation labs in Miaoli insulate LED packagers from dysprosium price volatility. |
| Quantum Dot Technology Licensing | Nanocrystal phosphor patents enable premium positioning in display backlighting beyond commodity LED modules. |
| Defense Procurement Qualification | Domestic content requirements for aerospace photonics open captive demand streams outside consumer electronics cycles. |
| Direct-to-Factory Channel Development | Laser driver IC distribution networks in Kaohsiung bypass legacy distributor markups for analog optoelectronic modules. |
| III-V Processing Training Center Expansion | Statute for Industrial Innovation funding for Tainan photonics corridors addresses molecular beam epitaxy technician scarcity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis, combining structured interviews with LED packaging engineers, semiconductor equipment procurement managers, Bureau of Standards compliance officers, and municipal infrastructure planners with secondary validation against Taiwan Industrial Development Bureau subsidy disclosures, National Communications Commission laser certification records, customs trade data for rare earth phosphor imports, and SEC filings from listed optoelectronics component distributors. Bottom-up segment sizing triangulated against top-down industrial output estimates from Hsinchu Science Park and Tainan photonics corridor development reports.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, application, end user, and technology dimensions with additional granularity for foundry proximity tiers and certification compliance levels. CAGRs were derived from trend extrapolation of equipment capital expenditure cycles and municipal infrastructure replacement schedules. Forecast inputs incorporated Bureau of Standards CNS certification scope expansion timelines and Ministry of Economic Affairs domestic content requirement recalibration signals.
Material uncertainties — rare earth supply disruptions, semiconductor capital expenditure cycle turns, and regulatory certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding continued Statute for Industrial Innovation funding continuity and stable Taiwan-Japan epitaxial wafer trade flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
3D Projector Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Gunn Diode Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market