
 Head-Mounted Display Market | 2026-2036
Head-Mounted Display Market Size, Share, and Industry Trends Forecast 2026-2036
Head-Mounted Display Market Analysis
MicroLED manufacturing is fragmenting across foundry partnerships and captive wafer strategies as display makers race to escape OLED supply bottlenecks. Sony Corporation leverages its CMOS image sensor expertise to anchor high-resolution near-eye panel production for both consumer and defense clients. Meta sustains aggressive R&D intensity across optical waveguide architectures despite mixed commercial traction. Varjo Technologies specializes in human-eye-resolution enterprise headsets for flight simulation and automotive design review, commanding premium pricing through patented foveated rendering.
A head-mounted display comprises an optical engine, microdisplay panel, tracking sensor array, and head-worn mechanical chassis engineered to present stereoscopic imagery within the user's field of view. These devices render computer-generated visuals for immersive simulation, heads-up data overlay, or blended environments where digital objects register against physical space. Virtual Reality headsets dominate unit shipments through gaming and entertainment volume, yet Mixed Reality Devices capture disproportionate margin pools as enterprise clients pay premiums for passthrough spatial computing. MicroLED technology leads fastest-growing technology investment as luminance and lifetime advantages over OLED attract military and outdoor industrial specifications.
FCC equipment authorization rules govern radio-frequency emissions for wireless HMDs sold in the United States, while the EU AI Act imposes conformity obligations on headsets deploying real-time biometric analysis or environmental inference. FDA 510(k) pathways shape clinical adoption timelines for surgical navigation and diagnostic visualization systems. Stakeholders must monitor how export control expansions on advanced displays affect cross-border component flows and foundry access.
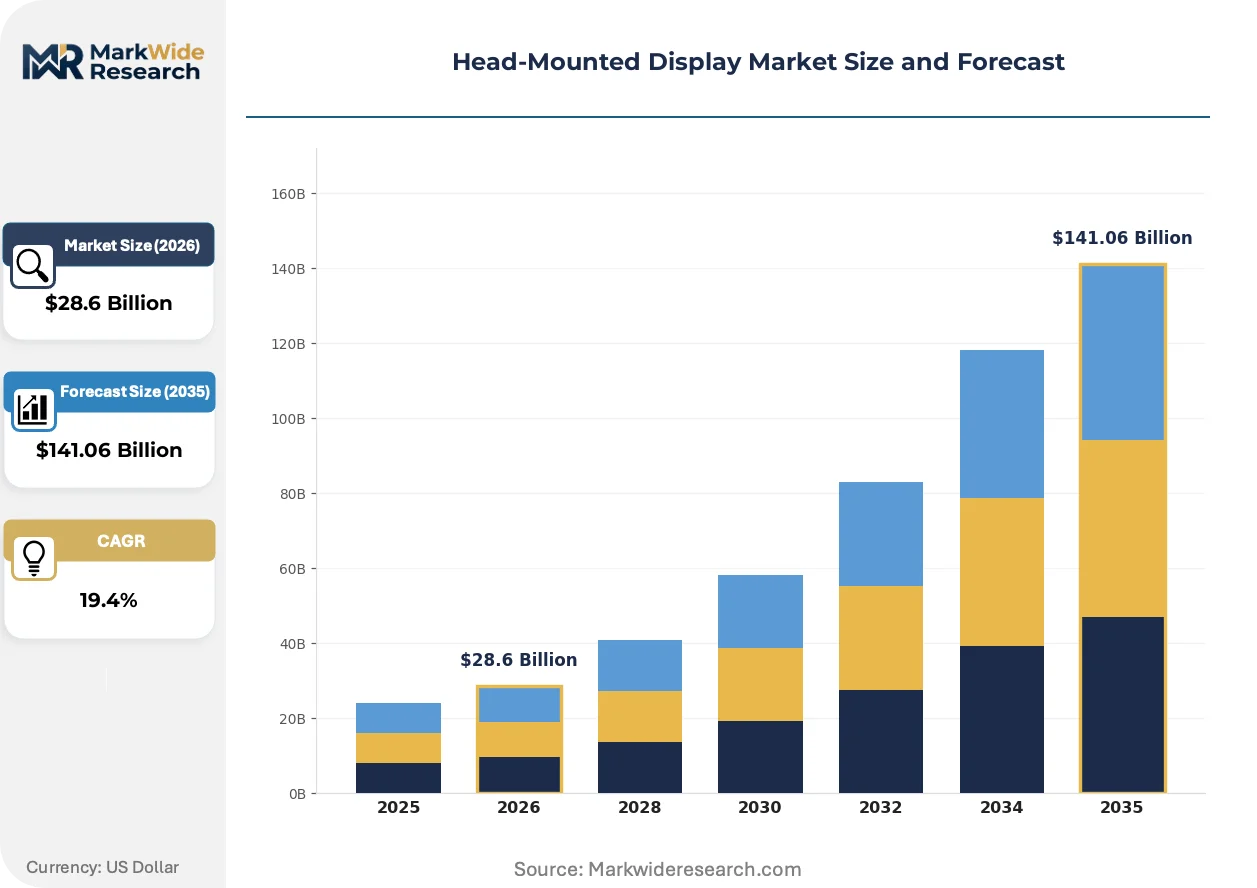
Market Dynamics
MicroLED supply chain fragmentation is forcing display manufacturers to choose between captive wafer investments and foundry partnerships, compressing time-to-market windows while raising capital intensity thresholds for new entrants.
Growth Catalysts
- Ecodesign for Sustainable Products Regulation:The European Union's rare earth reduction mandates are accelerating alternative phosphor and quantum dot research, opening procurement pathways for compliant suppliers.
- Defense pilot training modernization:NATO allies are expanding augmented reality headset procurement for flight simulation and battlefield situational awareness, creating stable multi-year demand anchors.
- Optical waveguide architectures:Advances in diffractive and holographic waveguide designs are reducing headset weight and expanding field-of-view specifications for enterprise mixed reality deployments.
Market Restraints
- Gallium and indium price volatility:MicroLED epitaxy relies on III-V compound semiconductors whose input costs fluctuate with mining output from concentrated extraction zones.
- South Korean and Taiwanese foundry concentration:Advanced microdisplay backplane manufacturing clusters in East Asia, creating single-source vulnerability for non-captive producers.
- FDA 510(k) pathway duration:Surgical navigation and diagnostic visualization systems face extended clinical validation timelines that delay revenue recognition for healthcare-focused vendors.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor assembly and testing are attracting display module investments to diversify supply origins.
- Foveated rendering plus eye tracking convergence:Combining gaze-contingent image processing with biometric sensors enables human-eye-resolution experiences at reduced computational load.
- Direct-to-enterprise channel expansion:Bypassing consumer retail distribution for industrial maintenance and automotive design review segments captures margin otherwise lost to channel intermediaries.
Industry Challenges
- Optical engineering talent scarcity:Waveguide design and near-eye optical system integration require specialized expertise concentrated in defense and aerospace labor pools.
- Multi-regulatory certification stacking:Simultaneous FCC equipment authorization, EU AI Act conformity assessment, and FDA clinical validation create parallel compliance burdens for cross-border vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head-Mounted Display Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality Headsets, Augmented Reality Glasses, Mixed Reality Devices, Smart Glasses Technology: OLED, LCD, LCoS, MicroLED End User: Gaming, Education, Healthcare, Military Application: 3D Visualization, Training Simulations, Remote Collaboration, Entertainment |
| Companies Covered | Sony Corporation, Meta, Microsoft, Samsung, Magic Leap, HTC Corporation, BAE Systems, Varjo Technologies, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head-Mounted Display Market Emerging Trajectories
Waveguide-based optical engines are displacing traditional pancake lens stacks as the dominant architecture for slim-form-factor headsets, compressing device thickness while expanding institutional adoption beyond gaming origins.
MicroLED epitaxy on silicon substrates is virtualizing the traditional OLED supply chain by enabling higher luminance outputs and extended operational lifetimes for outdoor industrial and military specifications. Defense procurement offices in the United States and Germany are accelerating qualification timelines for these panels. The technology is virtualizing established supplier relationships as captive wafer investments reshape foundry dependency patterns.
The EU AI Act's real-time biometric analysis provisions are imposing conformity obligations on headsets deploying environmental inference and gaze tracking, extending certification timelines for European market entry. Industrial safety regulators in Germany and France are interpreting these provisions strictly for workplace mixed reality deployments. Enterprise vendors are responding by segregating on-device processing from cloud inference to limit regulatory scope.
Buyer concentration among defense contractors and automotive OEMs is compressing sales cycles for premium enterprise headsets while fragmenting purchasing authority across IT, procurement, and operational safety departments. Direct vendor relationships are displacing systems integrator intermediaries for flight simulation and design review applications. This pattern is most visible in the United States, where Lockheed Martin and Boeing maintain dedicated augmented reality procurement offices with technical evaluation authority separate from traditional IT acquisition channels.
Head-Mounted Display Market Segmentation
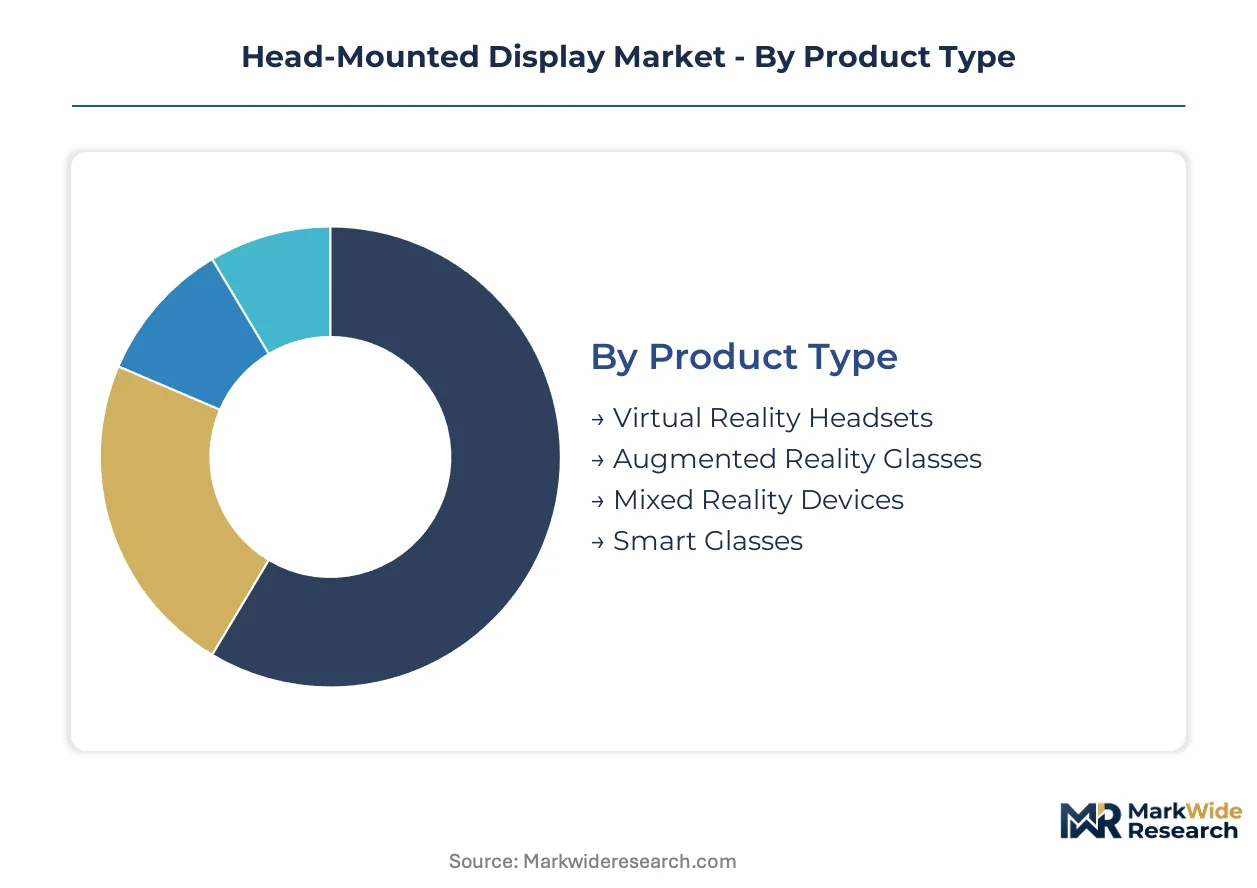
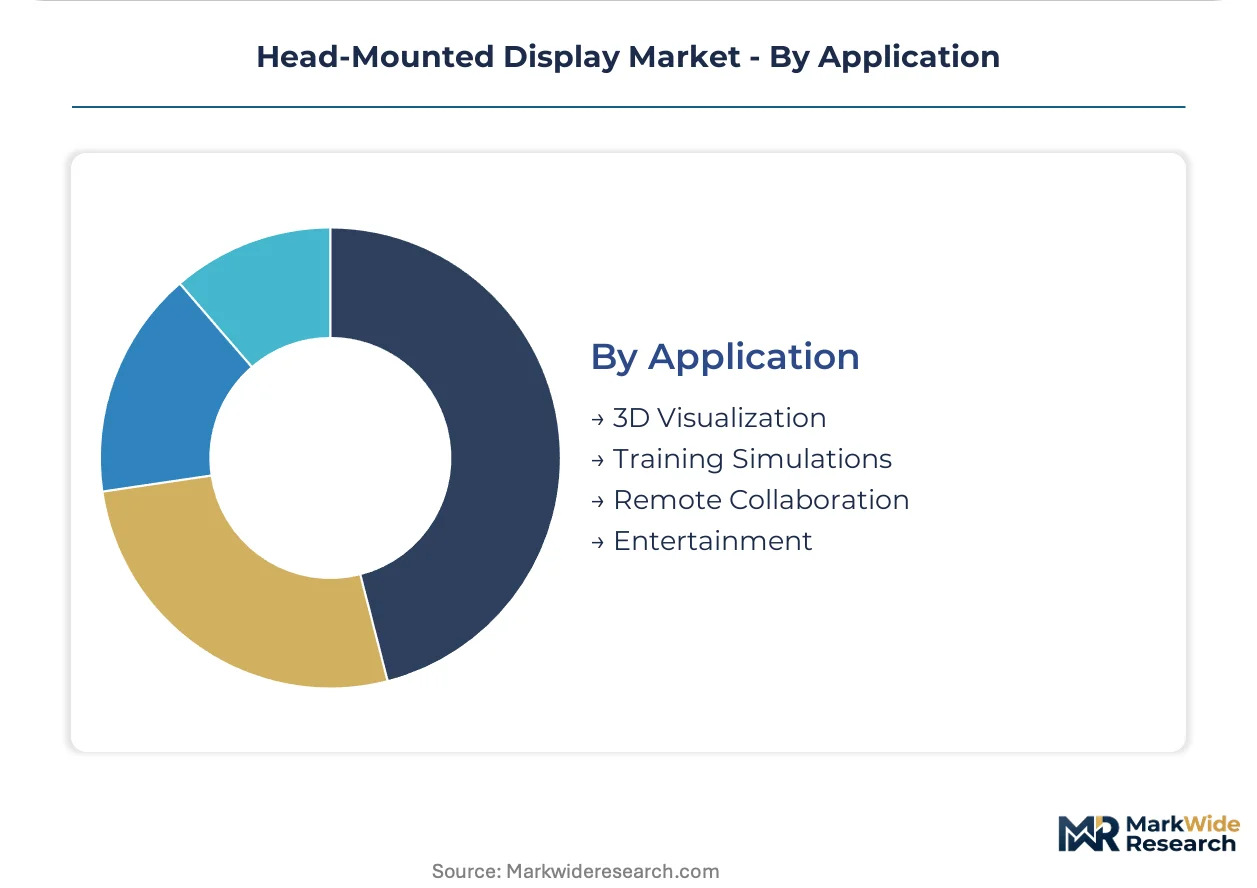
Head-mounted display segmentation reveals divergent margin structures across product architectures and end-use specifications. Technology choices determine luminance thresholds and supply chain vulnerability, while application focus shapes certification burdens and procurement channel access.
Product Type:
Mature consumer formats coexist with emerging enterprise configurations as optical architectures diverge.
- Virtual Reality Headsets:Fully immersive enclosures with pancake lens stacks or Fresnel optics dominate gaming and entertainment unit volumes. Demand concentrates in the United States through Meta's consumer retail presence and Sony's console-integrated PSVR ecosystem, constrained by content library depth and motion sickness mitigation requirements.
- Mixed Reality Devices:Passthrough camera arrays enable spatial computing with environmental meshing for industrial maintenance and design review. Procurement from automotive OEMs and defense contractors in Germany and the United States commands premium pricing through foveated rendering and eye-tracking integration.
- Augmented Reality Glasses:Optical see-through waveguides overlay data without occlusion, serving logistics and field service workflows.
- Smart Glasses:Notification-centric displays with minimal AR capability target enterprise productivity and cycling navigation niches.
Virtual Reality Headsets handles the majority of throughput; Mixed Reality Devices is the fastest mover on share.
Technology:
Cost tiers separate established deposition methods from capital-intensive next-generation epitaxy.
- MicroLED:III-V compound semiconductor epitaxy on silicon substrates delivers luminance exceeding OLED by an order of magnitude with extended operational lifetimes. Military procurement offices in the United States and Germany are accelerating qualification timelines for outdoor and avionics specifications, though gallium and indium price volatility compress foundry margins.
- OLED:Organic electroluminescent deposition on CMOS backplanes anchors consumer VR through Sony and Samsung Display supply relationships. South Korean foundry concentration creates single-source vulnerability for non-captive producers seeking high-resolution near-eye panels.
- LCD:Transmissive liquid crystal with LED backlighting serves cost-constrained enterprise training deployments.
- LCoS:Reflective liquid crystal on silicon enables high-fill-factor projection engines for waveguide-coupled AR glasses.
OLED handles the majority of throughput; MicroLED is expanding most quickly on share.
End User:
Customer type determines certification stacking intensity and sales cycle duration.
- Gaming:Consumer entertainment drives annual unit shipment peaks through holiday retail cycles and console platform releases.
- Military:NATO pilot training and battlefield situational awareness programs impose stringent environmental specifications and multi-year procurement anchors. FCC equipment authorization and ITAR compliance requirements filter vendor eligibility for defense contracts in the United States.
- Healthcare:FDA 510(k) pathways for surgical navigation and diagnostic visualization extend clinical validation timelines.
- Education:Institutional volume purchasing for STEM laboratories and vocational training programs concentrates in public procurement channels.
Gaming handles the majority of throughput; Military is climbing the fastest on share.
Application:
Volume concentration in entertainment contrasts with margin capture in specialized industrial workflows.
- Training Simulations:Flight crew certification and hazardous procedure rehearsal demand human-eye-resolution fidelity and sub-20ms motion-to-photon latency. Varjo Technologies and defense integrators in the United States command pricing premiums through foveated rendering patents and FAA training credit eligibility.
- 3D Visualization:Automotive design review and architectural walkthroughs leverage passthrough spatial computing for collaborative model manipulation. BMW and Volkswagen procurement offices in Germany maintain technical evaluation authority separate from traditional IT acquisition channels.
- Remote Collaboration:Virtual presence systems for distributed engineering teams compete with established video conferencing infrastructure.
- Entertainment:Cinematic VR and location-based attractions generate seasonal revenue concentration in United States theme park and cinema exhibition circuits.
Entertainment handles the majority of throughput; Training Simulations is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian display foundries export microdisplay backplanes to NATO defense procurement offices in the United States and Germany, creating a trade corridor that concentrates advanced panel sourcing while regional assembly investments diversify final headset production.
United States
Defense contracts from Lockheed Martin and Boeing anchor demand for pilot training headsets with FAA training credit eligibility. FCC equipment authorization and ITAR compliance requirements filter vendor eligibility for military procurement. Boston and Austin clusters host waveguide engineering talent pools serving both enterprise and defense clients.
Germany
Automotive OEM procurement from BMW and Volkswagen drives mixed reality adoption for design review workflows. KBA and industrial safety regulators interpret EU AI Act provisions strictly for workplace deployments. Bavaria's Munich-Stuttgart corridor concentrates optical engineering expertise for near-eye display systems.
South Korea
Samsung Display and LG anchor OLED backplane production for consumer VR volume, though foundry concentration creates single-source vulnerability. MFDS and MIIT-aligned standards shape regional certification requirements. Seoul-Suwon clusters dominate CMOS backplane manufacturing for high-resolution near-eye panels.
Japan
Sony leverages CMOS image sensor expertise to supply microdisplay panels for defense and consumer clients. METI funding supports MicroLED epitaxy research as an OLED alternative. Nagoya and Osaka industrial zones host precision optics manufacturing for waveguide coupling systems.
India
PLI scheme incentives for semiconductor assembly attract display module investments from Taiwanese and Korean vendors. BIS certification requirements shape import compliance for enterprise headset deployments. Karnataka and Tamil Nadu emerging as electronics manufacturing clusters for regional supply diversification.
Head-Mounted Display Market Vendor Landscape
On the supply side, the industry is bifurcated between captive-integrated display manufacturers and optical system integrators dependent on external panel sourcing. Defense contractors and consumer technology conglomerates occupy parallel demand tiers with minimal overlap in procurement channels. Strategic archetypes include CMOS-backplane-integrated display makers, waveguide-specialized optical houses, and end-to-end headset assemblers. Competitive moves concentrate on foundry partnership negotiations and foveated rendering patent licensing rather than capacity expansion.
Among defense-anchored specialists, BAE Systems and Elbit Systems exemplify the vertically integrated military tier where ITAR compliance and multi-year procurement anchors sustain pricing premiums. Sony Corporation and Meta occupy contrasting positions on the consumer-enterprise spectrum, with the former leveraging captive sensor-to-display integration and the latter sustaining optical architecture R&D despite mixed commercial traction. Varjo Technologies represents the human-eye-resolution specialist archetype commanding premium pricing through patented rendering approaches in flight simulation and automotive design review.
| Leading Market Players |
|---|
| Sony Corporation |
| Meta |
| Microsoft |
| Samsung |
| Magic Leap |
| HTC Corporation |
| BAE Systems |
| Varjo Technologies |
| Elbit Systems |
| Others |
Supply Flow & Price Mechanics
Gallium and indium price volatility in III-V compound semiconductor markets compresses foundry margins while widening spreads between OLED-based consumer tiers and MicroLED military specifications. This input cost instability simultaneously accelerates captive wafer investments among integrated display manufacturers and fragments procurement pathways for non-captive optical system integrators.
Pricing Analysis
The technology-generation pricing gap separates legacy LCD training headsets from OLED consumer VR and emerging MicroLED military panels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FAA training credit eligibility and ITAR compliance commanding substantial premiums for defense contractors. Cost compression in the standard tier intensifies because South Korean foundry concentration limits supplier switching for non-captive producers. Gaming consumers exhibit highest price sensitivity, while NATO procurement offices demonstrate lowest sensitivity due to multi-year program anchors.
Supply Chain Analysis
Contract-manufacturing concentration rests with Samsung Display and LG in South Korea, Sony in Japan, and emerging Taiwanese foundry partnerships for silicon-substrate MicroLED epitaxy. Geographic supply concentration centers on South Korea, Japan, and Taiwan for CMOS backplane fabrication, with final assembly diversifying toward India under PLI scheme incentives. Raw material dependencies draw from concentrated gallium extraction zones and indium mining outputs. Single-source vulnerability in advanced microdisplay backplane manufacturing creates structural exposure to export control expansions. Distribution runs through direct vendor relationships for defense and automotive OEMs, bypassing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Head-Mounted Display Market represents high-growth disruption as MicroLED epitaxy virtualizes established OLED supply relationships and EU AI Act conformity obligations reshape certification burdens for biometric-enabled headsets.
For Market Incumbents: Entrench through captive wafer investments in silicon-substrate MicroLED production to escape South Korean foundry dependency, while deepening optical engineering talent pools in Boston and Austin clusters. Defense procurement offices at Lockheed Martin and Boeing maintain dedicated technical evaluation authority separate from IT acquisition channels, threatening margin capture by systems integrator intermediaries. Patent licensing around foveated rendering and eye-tracking convergence offers defensive moat expansion against emerging optical specialists.
For New Entrants and Emerging Players: Industrial maintenance workflows in German automotive supply chains represent the most penetrable entry point for passthrough spatial computing headsets, as BMW and Volkswagen procurement offices seek alternatives to incumbent design review vendors. India's PLI scheme for electronics manufacturing offers geographic white-space for display module assembly investments from Taiwanese and Korean technology transfer partnerships. Direct-to-enterprise channel expansion bypassing retail distribution captures margin otherwise lost to channel intermediaries.
For Investors and Strategic Acquirers: Waveguide-specialized optical houses with defense contract eligibility and ITAR compliance infrastructure offer acquisition targets with durable pricing power. Long-term viability in this market hinges on qualification timelines for MicroLED military specifications and convergence of foveated rendering with biometric sensor integration. Watch for acceleration in NATO pilot training procurement announcements as early signal of demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive MicroLED Wafer Investment | Escapes OLED supply bottlenecks and South Korean foundry concentration for military specifications. |
| EU AI Act Conformity Certification | Enables European market entry for gaze-tracking headsets under biometric analysis provisions. |
| Direct-to-Enterprise Channel Expansion | Bypasses systems integrators to capture margin in automotive design review and flight simulation. |
| Foveated Rendering Patent Licensing | Monetizes human-eye-resolution technology through Varjo-style premium positioning. |
| India PLI Scheme Manufacturing Footprint | Diversifies final assembly origins away from East Asian concentration for export compliance. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with optical engineering directors, defense procurement officers, display foundry operations managers, and enterprise IT decision-makers; and secondary validation through SEC filings of headset manufacturers, FCC equipment authorization databases, EU AI Act conformity assessment registers, and customs records of microdisplay panel trade flows. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across product architectures and end-use specifications.
Forecast inputs considered technology adoption curves, defense procurement program timelines, and regulatory certification pathway durations across the projection horizon. Segmentation dimensions modeled include product type, display technology, end-user vertical, and application workflow, with additional weighting for military qualification status and FAA training credit eligibility. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than simple extrapolation. Industry-specific inputs encompassed gallium and indium commodity price trajectories and foundry capacity expansion announcements.
Practitioners should monitor export control expansions on advanced displays, EU AI Act enforcement interpretations by German and French regulators, and MicroLED qualification timeline acceleration by United States and German defense offices for early signals of forecast revision. Quarterly review of NATO procurement announcements, BIS certification registrations in India, and PLI scheme uptake metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
E-Paper Display Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Touch Screen Film Market
Display Technologies
Flexible Screens Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Display Mask Market
Display Technologies
Portable Video Wall Market
Display Technologies
Portable Projector Market
Display Technologies
OLED Laptops Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Monochrome Display Market
Display Technologies
IGZO Display Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Smart Display Market
Display Technologies
3D Display Market