
 Laser Photomask Market | 2026-2036
Laser Photomask Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Photomask Market Intelligence
The adoption of extreme ultraviolet (EUV) lithography is reconfiguring the entire semiconductor manufacturing process, demanding a new generation of photomasks with unprecedented precision. Toppan Printing Co. Ltd leverages its extensive R&D infrastructure to produce these advanced EUV photomasks. Photronics Inc. competes by offering a broad portfolio of photomask solutions across multiple technology nodes for diverse clients. Meanwhile, Taiwan Mask Corporation sustains its market position through deep, long-term partnerships with major foundries.
A laser photomask is an opaque plate, typically made of high-purity quartz, with a patterned layer of light-absorbing chromium. It functions as a master template in photolithography, transferring intricate circuit designs onto semiconductor wafers or flat panel display substrates. Within the product landscape, Phase Shift Photomasks are essential for achieving the fine resolutions required in advanced semiconductor fabrication. Consequently, foundries and chip designers represent the largest end-user segments, procuring masks for both leading-edge and mature process nodes.
Material and chemical usage in photomask production is governed by stringent environmental regulations such as the EU's REACH framework and rules set by the US EPA. Furthermore, export controls on advanced lithography equipment and related technologies, managed by bodies like Japan's METI, directly influence market access and supply chain strategies. Navigating the immense capital investment cycle for next-generation mask writers and inspection tools remains the critical decision point for all manufacturers.
Market Dynamics
The relentless push toward sub-10nm semiconductor nodes and the corresponding adoption of extreme ultraviolet (EUV) lithography create the central dynamic. This technological shift imposes unprecedented precision requirements and escalates capital investment for mask production and inspection equipment.
Growth Catalysts
- EUV Lithography Adoption:The industry-wide transition to EUV for manufacturing advanced logic and memory chips directly necessitates a new generation of highly complex and defect-free photomasks, pulling the market forward.
- Flat Panel Display Expansion:Demand from the display sector for higher-resolution OLED and micro-LED screens for televisions, smartphones, and automotive applications requires larger and more intricate photomasks.
- Semiconductor Sovereignty Policies:Government initiatives, including the US CHIPS Act and Europe's similar programs, incentivize domestic chip production, which in turn stimulates regional demand for photomask development and fabrication services.
Market Restraints
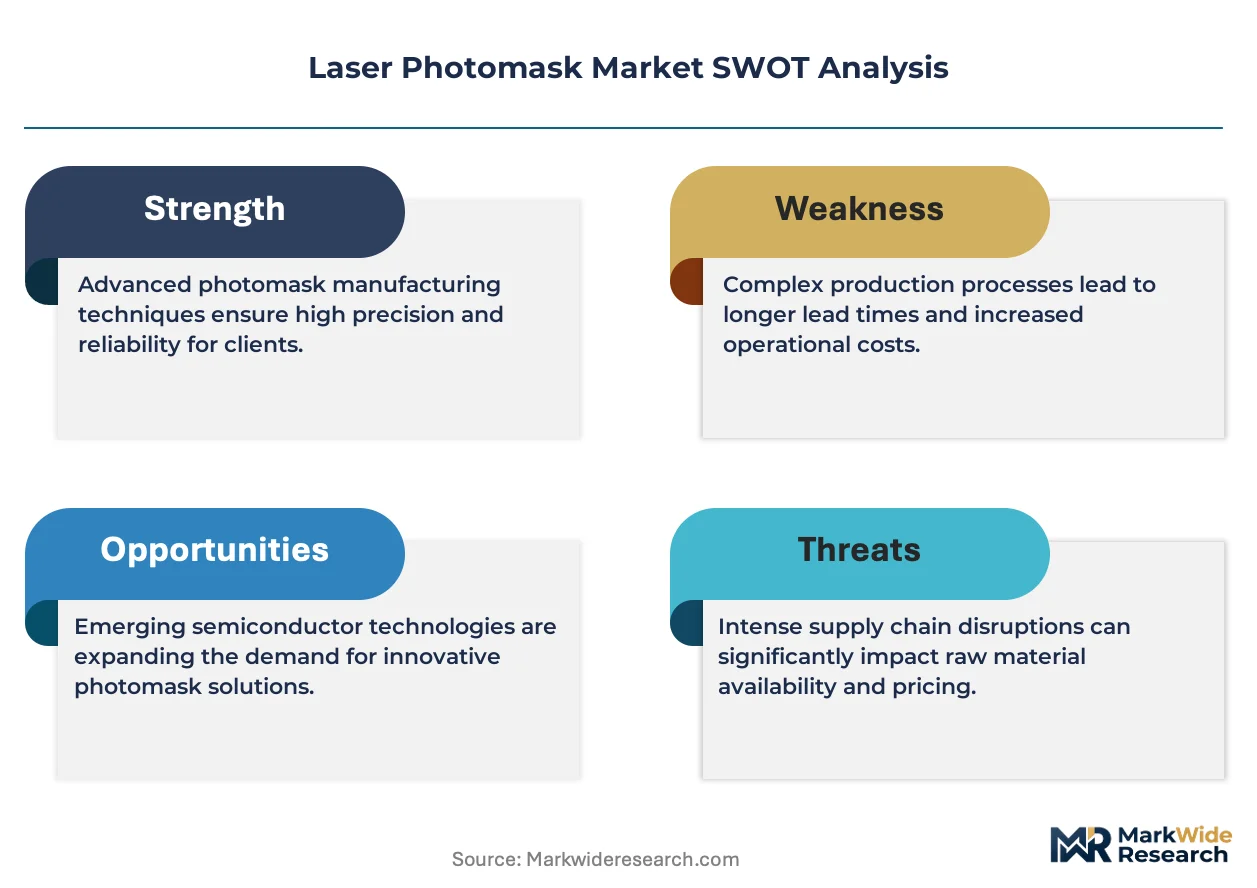
- Extreme Capital Intensity:The acquisition and maintenance of next-generation multi-beam mask writers and actinic pattern inspection systems require immense capital outlays, creating high barriers to entry and expansion for smaller players.
- Raw Material Bottlenecks:The supply of high-purity synthetic quartz glass, the primary substrate material for advanced photomasks, is concentrated among a very small number of global suppliers, posing a supply chain risk.
- Stringent Environmental Regulations:Compliance with chemical substance regulations, such as the EU's REACH framework, increases operational costs and complexity related to the handling and disposal of materials used in mask etching and cleaning.
Strategic Opportunities
- Emerging Photonic Applications:The development of silicon photonics for data centers and LiDAR systems for autonomous vehicles presents a significant opportunity for specialized photomasks designed for non-CMOS applications.
- Advanced Packaging Technologies:The move towards 2.5D and 3D IC packaging creates demand for new types of photomasks, such as those for interposers and through-silicon vias (TSVs), opening a new product segment. *Nanoimprint Lithography (NIL): As NIL matures as a potential complementary or alternative patterning technique, there is an opportunity to develop and supply master templates for this emerging manufacturing process.
Industry Challenges
- Talent Scarcity:A critical shortage of engineers and physicists with expertise in optical physics, materials science, and data analytics for mask synthesis, defect inspection, and repair hinders production scalability.
- Defect Management at Scale:Achieving and maintaining the zero-defect standard required for leading-edge EUV photomasks is an immense operational hurdle, demanding sophisticated and costly metrology and repair processes.
- Intellectual Property Complexity:Navigating the intricate web of patents and licenses associated with resolution enhancement techniques (RET) and proprietary mask data preparation flows complicates design and manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Photomask Market |
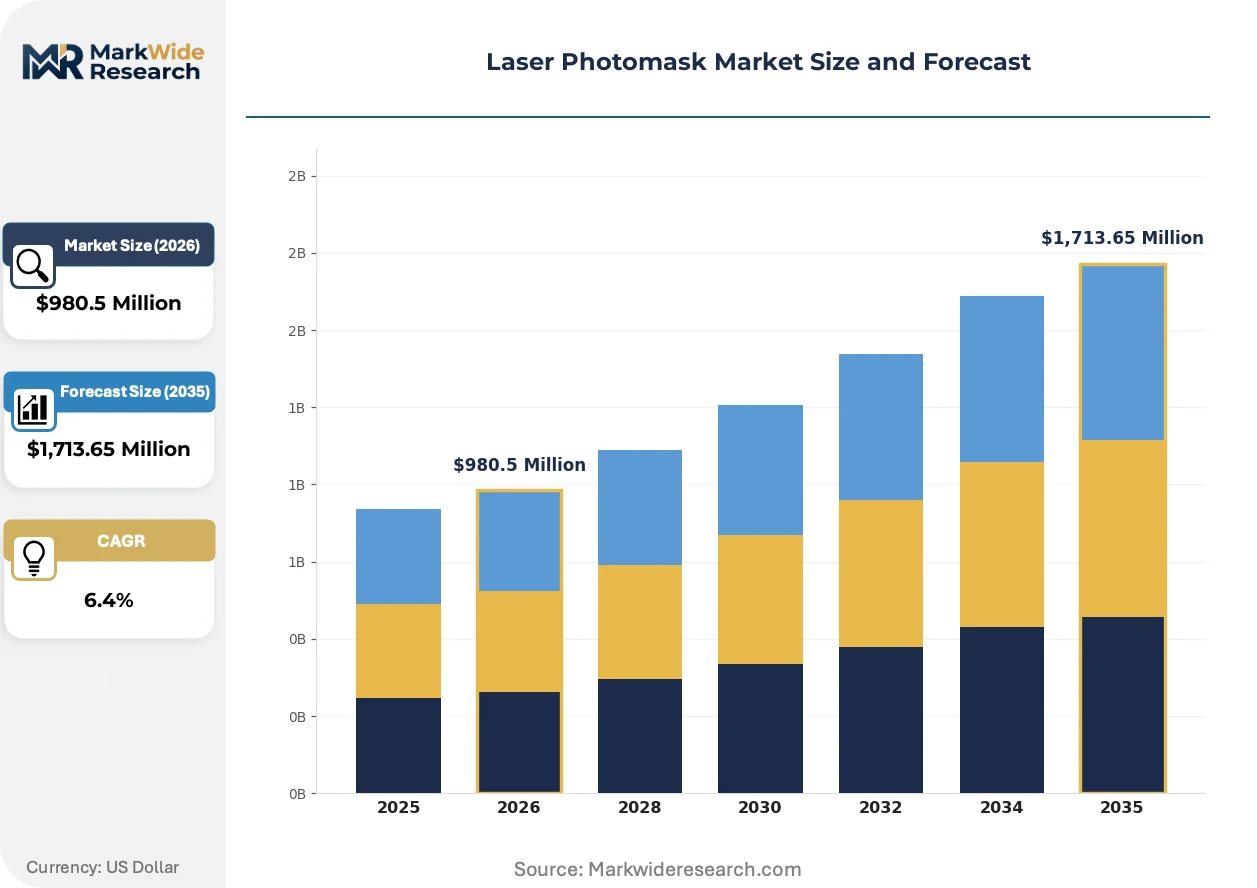
| Market Size in 2026 | $980.5 Million |
| Market Size in 2035 | $1,713.65 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binary Photomask, Phase Shift Photomask, Embedded Attenuated Phase Shifting, Chromium Photomask, Glass Photomask Technology: Laser Direct Imaging, Electron Beam Lithography, Ultra Violet Lithography, X-ray Lithography, Nanoimprint Lithography Application: Semiconductor Fabrication, Microelectromechanical Systems, Printed Circuit Boards, Flat Panel Displays, Optical Devices End User: Foundries, Chip Designers, Semiconductor Equipment Manufacturers, Contract Wafer Fabricators |
| Companies Covered | Applied Materials Inc., Nippon Filcon Co. Ltd, Photronics Inc., Taiwan Mask Corporation, SK-Electronics Co. Ltd, Toppan Printing Co. Ltd, KLA-Tencor Corporation, LG Innotek Co. Ltd, Hoya Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Photomask Market Strategic Shifts & Innovations
The market's evolution is defined by the technical race to manage pattern complexity and defectivity at shrinking scales. Innovations in writing technology, coupled with evolving procurement models, are fundamentally altering the production and consumption of photomasks.
Multi-beam mask writers (MBMW) represent a critical technological advancement in photomask fabrication. These systems utilize thousands of individually controlled electron beams to write patterns simultaneously, drastically reducing production time for complex designs. Leading-edge foundries and captive mask shops are adopting MBMW technology for sub-7nm nodes. This technology is hybridizing the mask creation process by combining unprecedented write-speed with the precision needed for EUV masks.
Export control regimes, particularly those managed by Japan's METI and the US Department of Commerce, are increasingly restricting the sale of advanced lithography and mask-making equipment. This directly impacts the supply chain strategies of manufacturers in targeted nations, limiting access to state-of-the-art tools. Consequently, photomask producers in affected geographies are either focusing on mature node technologies or accelerating internal R&D programs to develop domestic equipment alternatives.
A significant behavioral shift is the rising utilization of multi-project wafer (MPW) shuttle services by fabless semiconductor companies and research institutions. This model aggregates designs from multiple customers onto a single photomask set, effectively amortizing the high cost of mask fabrication. The practice disrupts the traditional one-customer-per-mask-set model and is most visible within the design ecosystems of Taiwan and California, lowering entry barriers for silicon prototyping.
Laser Photomask Market Segmentation
Understanding the diverse segments within the laser photomask market clarifies the varying technical demands and strategic priorities across its value chain. This granular view reveals how specific product types, technologies, applications, and end-users shape market dynamics. Analysis of these distinct categories informs targeted innovation and investment decisions for manufacturers.
Product Type:
The product type segmentation reveals a spectrum from mature, foundational mask types to advanced solutions critical for leading-edge manufacturing.
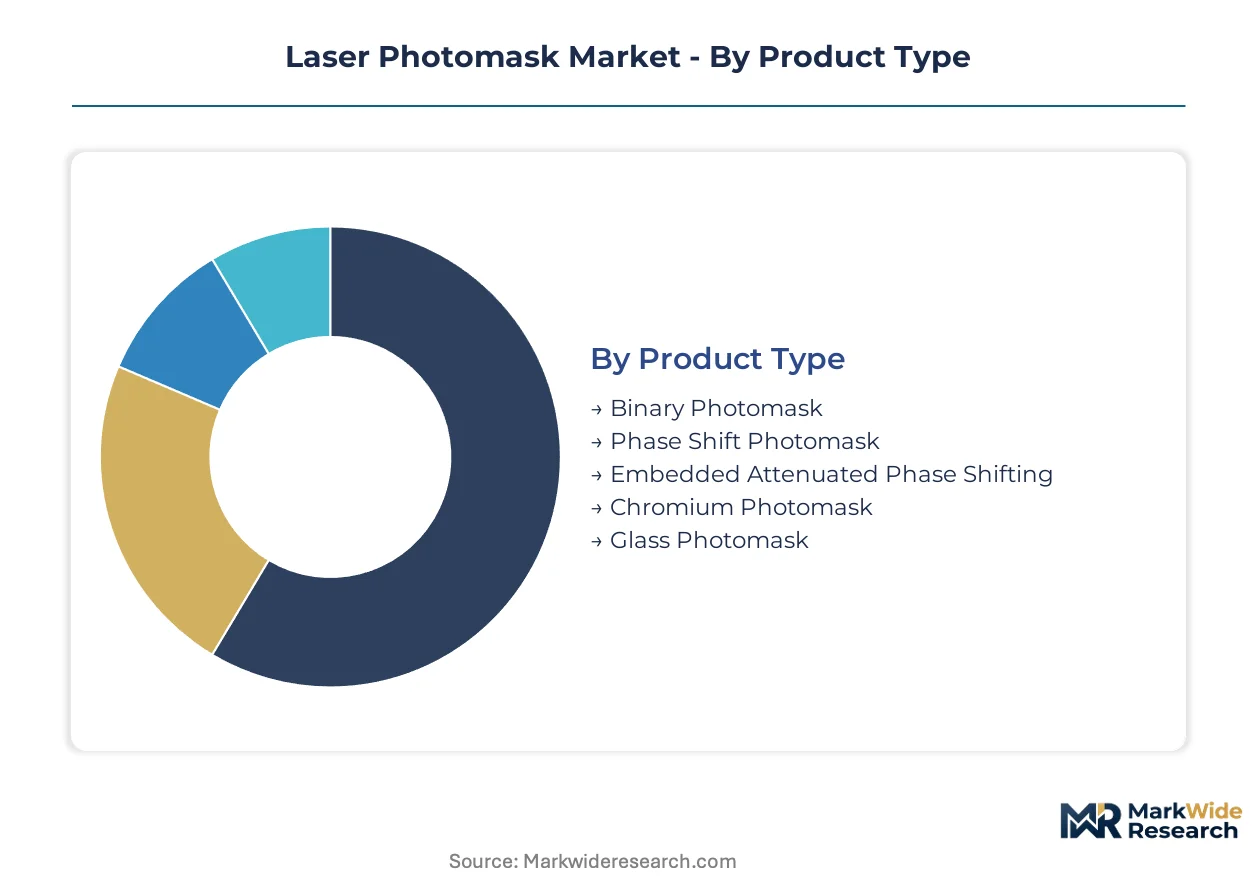
- Phase Shift Photomask:Phase Shift Photomasks manipulate light interference to enhance resolution and pattern fidelity, crucial for sub-10nm semiconductor nodes. Demand is concentrating in Taiwan's advanced foundries, driven by the imperative for defect-free patterning in EUV lithography.
- Embedded Attenuated Phase Shifting:Embedded Attenuated Phase Shifting photomasks use partially transmissive layers to improve image contrast and critical dimension control. This technology sees strong demand from leading chip designers in California, who require precise feature definition for high-performance logic devices.
- Binary Photomask:Binary photomasks, featuring opaque chromium patterns on transparent substrates, serve as fundamental templates for mature process nodes and flat panel display production.
- Chromium Photomask:Chromium photomasks utilize a thin layer of chromium as the light-absorbing material, providing robust pattern definition for various lithography applications.
- Glass Photomask:Glass photomasks, typically made of high-purity quartz, form the transparent substrate onto which circuit patterns are etched, ensuring optical clarity.
Binary Photomasks retain volume leadership; Phase Shift Photomasks hold the steepest expansion curve.
Technology:
Different mask writing technologies address specific resolution requirements and throughput demands across diverse manufacturing applications.
- Electron Beam Lithography:Electron Beam Lithography employs focused electron beams to create intricate patterns with sub-nanometer precision on photomasks, essential for EUV mask fabrication. Foundries in South Korea heavily invest in this technology for producing memory chips, where extreme resolution is paramount.
- Laser Direct Imaging:Laser Direct Imaging systems use modulated laser beams to directly pattern photomasks, offering high throughput for less critical layers and flat panel display applications. This technology sees significant adoption in China's display manufacturing sector due to its efficiency and cost-effectiveness.
- Ultra Violet Lithography:Ultra Violet Lithography, while foundational for chip manufacturing, also describes the use of UV light for less demanding photomask patterning processes.
- X-ray Lithography:X-ray Lithography, though less common in commercial photomask production, offers potential for ultra-fine feature generation due to its short wavelength.
- Nanoimprint Lithography:Nanoimprint Lithography involves mechanically pressing a master template onto a substrate, offering a high-throughput, low-cost patterning alternative for future masks.
Electron Beam Lithography remains central to advanced mask creation; Nanoimprint Lithography represents a future innovation frontier.
Application:
The diverse applications of laser photomasks underscore their foundational impact across multiple high-tech manufacturing sectors.
- Semiconductor Fabrication:Semiconductor Fabrication represents the largest application segment, where photomasks are indispensable for patterning integrated circuits on silicon wafers. Demand is particularly intense from foundries in Taiwan and the United States, driven by the relentless pursuit of smaller feature sizes.
- Flat Panel Displays:Flat Panel Displays utilize large-area photomasks to create intricate pixel arrays for OLED, micro-LED, and LCD screens. This application sees significant demand from manufacturers in South Korea and China, who are expanding production of high-resolution televisions and mobile devices.
- Microelectromechanical Systems:Microelectromechanical Systems (MEMS) production relies on photomasks for patterning tiny mechanical and electrical components used in sensors and actuators.
- Printed Circuit Boards:Printed Circuit Boards (PCBs) use photomasks for transferring circuit patterns onto copper-clad laminates, forming the basis of electronic assemblies.
- Optical Devices:Optical Devices like waveguides and diffractive optics employ specialized photomasks for precise patterning, enabling advanced photonics applications.
Semiconductor Fabrication drives the largest mask demand; Flat Panel Displays exhibit substantial growth in mask complexity.
End User:
The end-user segmentation highlights distinct consumption patterns and procurement strategies within the laser photomask ecosystem.
- Foundries:Foundries, as dedicated semiconductor manufacturers, are the largest purchasers of photomasks for mass production across various technology nodes. Their demand is concentrated in Taiwan and South Korea, driven by high-volume manufacturing of logic and memory chips for global markets.
- Chip Designers:Chip Designers, particularly fabless companies, procure photomasks for prototyping and initial production runs of their innovative integrated circuits. This segment's demand is strong in California and Europe, where new architectures for AI and automotive electronics are developed.
- Semiconductor Equipment Manufacturers:Semiconductor Equipment Manufacturers utilize photomasks for internal R&D and for testing their lithography and inspection tools.
- Contract Wafer Fabricators:Contract Wafer Fabricators, often serving niche markets or mature nodes, acquire photomasks tailored to their specific process requirements and client designs.
Foundries represent the primary consumption channel; Chip Designers hold strategic importance for early mask development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photomask exports from Japan and the United States primarily serve the advanced semiconductor manufacturing hubs in Taiwan and South Korea. These regions drive substantial demand for leading-edge masks, reflecting their critical roles in global chip production. Diverse regional policies and technological concentrations define market dynamics across key geographies.
Taiwan
Taiwan's world-leading foundry ecosystem creates immense demand for advanced photomasks, particularly for sub-10nm semiconductor nodes. The national government actively supports its semiconductor industry through strategic investment policies and infrastructure development. Hsinchu Science Park and Tainan Science Park serve as epicenters for high-volume manufacturing of logic and memory chips.
South Korea
South Korea's robust memory chip sector and growing high-resolution display production drive significant photomask procurement. National industrial policies prioritize semiconductor self-sufficiency and technological leadership. Companies in Gyeonggi Province, home to major memory chip manufacturers, heavily invest in Electron Beam Lithography for extreme resolution requirements.
United States
The United States generates strong demand for leading-edge photomasks from its vibrant chip design community and expanding fabrication capacity. The US CHIPS Act incentivizes domestic semiconductor manufacturing and advanced R&D. Silicon Valley and emerging hubs in Arizona and Texas focus on developing new architectures for AI and automotive electronics.
Japan
Japan maintains a critical position in the photomask market through its advanced R&D infrastructure and production of high-purity quartz substrates. The Ministry of Economy, Trade and Industry (METI) manages export controls on advanced lithography equipment, influencing global supply chains. Companies in Tokyo and Osaka leverage extensive R&D to produce advanced EUV photomasks.
China
China's expanding flat panel display manufacturing sector and government-backed initiatives for domestic chip production fuel substantial photomask demand. National policies, including those from the Ministry of Industry and Information Technology (MIIT), aim to reduce reliance on foreign technology. Display manufacturers in the Yangtze River Delta and Pearl River Delta widely adopt Laser Direct Imaging for efficiency.
Laser Photomask Market Key Industry Players
Channel-controlling players compete with product-specialist players across the laser photomask market. The market structure exhibits consolidation among a few global leaders, alongside specialized firms serving niche technology nodes or specific end-user segments. Strategic archetypes include integrated technology providers, broad-portfolio solution suppliers, and foundry-aligned specialists. Dominant competitive moves involve significant R&D investment and the formation of strategic partnerships to manage extreme capital intensity.
Within the advanced photomask manufacturing tier, Toppan Printing Co. Ltd and Photronics Inc. represent distinct strategic approaches. Toppan Printing Co. Ltd, a Japan-based Co. Ltd, exemplifies an integrated player leveraging extensive R&D infrastructure for advanced EUV photomasks. Photronics Inc., an Inc. company, occupies a position as a broad-portfolio provider of photomask solutions across multiple technology nodes. Taiwan Mask Corporation, a Corporation, anchors the market through its deep, long-term partnerships with major foundries, particularly within the crucial Taiwan ecosystem.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| Nippon Filcon Co. Ltd |
| Photronics Inc. |
| Taiwan Mask Corporation |
| SK-Electronics Co. Ltd |
| Toppan Printing Co. Ltd |
| KLA-Tencor Corporation |
| LG Innotek Co. Ltd |
| Hoya Corporation |
| Others |
Cost & Logistics Intelligence
Shipping lanes from East Asia, critical for photomask components, influence pricing power due to concentrated supply and the high value of specialized materials. This dynamic ties logistics costs directly to the final price differentiation across various photomask types.
Pricing Analysis
The pricing gap between leading-edge EUV photomasks and mature node binary masks is substantial, reflecting immense R&D and manufacturing complexity. Contract-based long-term offtake agreements dominate for advanced masks, securing supply for major foundries. Price differentiation stems from customization level for specific process nodes and the stringent zero-defect certification required for EUV. Pricing pressure stems from the extreme capital intensity of next-generation mask writers, yet is offset by the indispensable nature of advanced masks. Chip designers procuring masks for prototyping innovative integrated circuits exhibit less price sensitivity than foundries negotiating high-volume contracts for mature nodes.
Supply Chain Analysis
The upstream supply of high-purity synthetic quartz glass, a critical substrate, centers on a very small number of suppliers primarily in Japan. Raw material dependencies include both this specialized quartz and high-grade chromium for light-absorbing patterns. Single-source vulnerability for key materials and export controls on advanced lithography equipment pose significant supply chain risks. Distribution runs through direct sales channels from photomask manufacturers to major foundries and fabless chip design companies globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser photomask market represents an early-cycle expansion story, driven by the pervasive adoption of extreme ultraviolet lithography across advanced semiconductor manufacturing.
For Market Incumbents: Build robust IP portfolios and R&D infrastructure to maintain technological leadership in EUV photomasks. Secure long-term supply agreements for high-purity quartz to mitigate raw material bottlenecks. Invest in next-generation multi-beam mask writers to counter emerging alternative patterning techniques like Nanoimprint Lithography. Deepen strategic partnerships with leading foundries in Taiwan to ensure market access and co-development opportunities.
For New Entrants and Emerging Players: Geographic underpenetration in domestic chip production initiatives, particularly in China, offers strategic entry points. Target specialized photomasks for advanced packaging technologies, such as interposers, or non-CMOS applications like silicon photonics. Focus on cost-effective solutions for mature process nodes or flat panel display applications using Laser Direct Imaging. A viable go-to-market strategy involves offering niche mask solutions that address specific regional demand or specialized fabrication requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates seeking to divest non-core mask-related metrology or material science divisions. The market offers long-term viability as a foundational technology for the semiconductor roadmap over the next decade. Acquisition targets should include specialized metrology tool manufacturers or high-purity material suppliers with strong intellectual property. Commercialization of Nanoimprint Lithography for volume production serves as a critical signal to watch for potential market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Mask Writers | Enhances precision and throughput for next-generation EUV photomasks. |
| Secure Long-Term Material Contracts | Mitigates supply chain risks for critical high-purity quartz substrates. |
| Form Foundry Partnerships | Ensures early access to leading-edge process nodes for co-development. |
| Target Advanced Packaging Masks | Diversifies product portfolio into high-growth 2.5D and 3D IC segments. |
| Expand Regional Manufacturing | Supports government-backed semiconductor sovereignty initiatives in key geographies. |
Research Approach
A spread of perspectives from foundry executives, chip design engineers, material scientists, and equipment manufacturers converged on the working assumptions for this analysis. Primary interviews with industry stakeholders were combined with secondary validation from industry association reports, patent databases, and SEC filings of public companies. Both bottom-up and top-down triangulation approaches were employed to ensure robust data integrity.
The demand-supply-balance framing guided the analytical framework, integrating demand forecasts with supply-side capacity assessments across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional manufacturing capability. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included semiconductor capital expenditure cycles and flat panel display panel expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or material suppliers would shift outcomes. Unforeseen geopolitical shifts impacting export controls or rapid breakthroughs in maskless lithography represent specific risk factors. Cross-checking against international semiconductor consortium roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Photonic Sensors Market
Optical Components
Co-Packaged Optics Market
Optical Components
Machine Vision Light Source Market
Optical Components
Pancake Optical Module Market
Optical Components
CMP Polishing Machine Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Optical Encoder Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Europe Optical Film Market
Optical Components
Night Vision Tubes Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
3-7mm Galvo Scanner Market