
 Printed Image Sensors Market | 2026-2036
Printed Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Image Sensors Market Outlook
East Asian substrate producers are pivoting toward roll-to-roll compatible semiconductor coatings for printed image sensor fabrication. ISORG leverages its organic photodetector portfolio to anchor European supply chains for large-area imaging. FlexEnable Limited sustains technology leadership through proprietary organic thin-film transistor backplanes. PolyIC GmbH & Co. KG specializes in printed electronics platforms that extend into capacitive and photonic sensing layers.
Printed image sensors are optoelectronic devices manufactured through additive printing processes on flexible polymer substrates, typically employing organic semiconductors or quantum dot active layers with spectral sensitivity ranging from visible to near-infrared wavelengths. These sensors convert incident photons into electrical signals for applications requiring conformal surfaces, large active areas, or ultra-low weight profiles. CMOS-based printed variants currently dominate unit shipments due to compatibility with existing readout integrated circuit architectures. Quantum dot sensors represent the fastest-expanding technology segment as tunable absorption edges enable multispectral imaging without external filter arrays. Medical device applications concentrate margin pools where biocompatible substrates and disposable form factors justify premium positioning against conventional silicon imagers.
REACH and RoHS frameworks in Europe restrict cadmium and lead content in printed sensor active layers, redirecting R&D investment toward indium phosphide and perovskite quantum dot alternatives. FDA 510(k) pathways in the United States govern the integration of printed image sensors into disposable endoscopic and dermatological diagnostic tools, creating differentiated approval timelines by clinical risk class. Stakeholders must monitor regulatory convergence between biocompatibility standards for wearable medical devices and emerging electromagnetic compatibility requirements for automotive printed electronics.
Market Dynamics
The EU Green Deal and RoHS directives are compressing heavy-metal chemistries out of printed image sensor active layers, forcing rapid migration toward organic photodetector and quantum dot alternatives across European supply chains. This regulatory compression is reshaping R&D allocation, pilot line investments, and substrate material selection decisions for manufacturers targeting automotive and medical imaging end-uses.
Growth Catalysts
- REACH and RoHS frameworks:European chemical restrictions on cadmium and lead content are redirecting capital toward indium phosphide and perovskite quantum dot development, accelerating commercialization timelines for compliant photodetector platforms.
- Automotive cabin monitoring:OEM integration of printed sensors into advanced driver assistance systems and occupant detection systems is pulling flexible imager volumes into vehicle qualification pipelines.
- Roll-to-roll fabrication:East Asian substrate producers are scaling compatible semiconductor coatings, reducing unit costs for large-area imaging applications previously uneconomical with silicon wafer approaches.
Market Restraints
- Indium supply concentration:Thin-film transistor backplane production depends on indium tin oxide sourced primarily from Chinese refining operations, exposing European and North American sensor fabricators to input cost volatility and export control risks.
- Silicon CMOS substitution:Conventional silicon image sensors maintain cost-performance dominance in resolution-critical applications, limiting printed sensor penetration in smartphone and security camera end-uses.
- FDA 510(k) pathway friction:Disposable medical device applications face elongated approval timelines for printed imagers without predicate device equivalence, compressing margin recovery periods for biocompatible substrate investments.
Strategic Opportunities
- Biocompatible disposables:Dermatological diagnostic and endoscopic tool manufacturers in Germany and France are qualifying polymer-based printed sensors for single-use applications where silicon wafer economics fail.
- Near-infrared spectroscopy:Tunable quantum dot absorption edges enable multispectral imaging without external filter arrays, opening food quality inspection and agricultural monitoring applications.
- EU AI Act compliance:Automotive printed electronics integration for cabin monitoring systems aligns with emerging algorithmic transparency mandates for in-vehicle biometric processing.
Industry Challenges
- Organic semiconductor process engineering:Printed electronics specialists with roll-to-roll coating expertise remain scarce relative to silicon foundry talent pools, constraining pilot line scale-up velocity.
- Readout circuit integration:Hybrid bonding of printed photodetector layers to silicon CMOS readout integrated circuits requires precision alignment equipment with capital intensity comparable to display panel manufacturing.
- Electromagnetic compatibility certification:Automotive printed sensor modules must satisfy evolving EMC requirements for in-vehicle electronics while maintaining flexible form factors incompatible with conventional shielding approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Image Sensors Market |
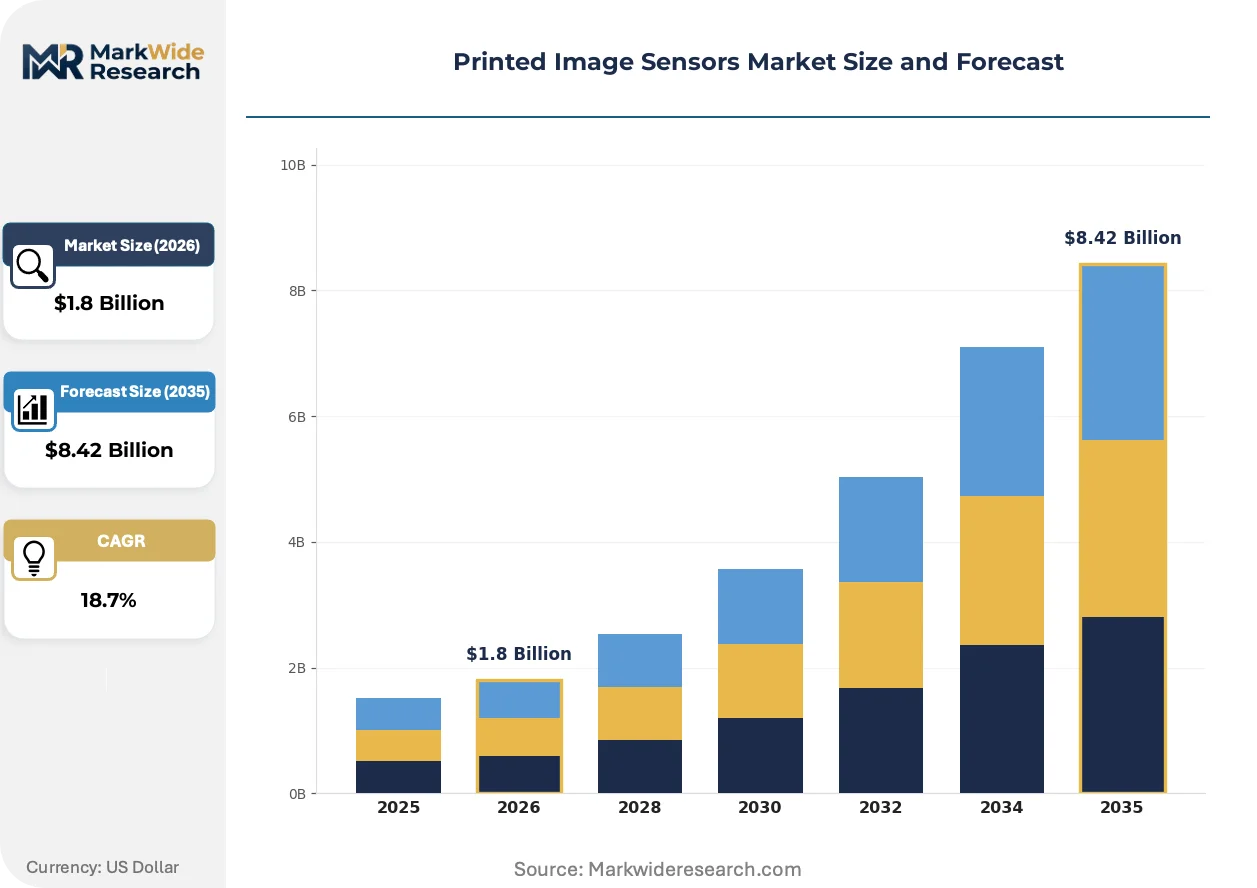
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS Sensors, CCD Sensors, Photodiodes, TDI Sensors Technology: Organic Photodetectors, Quantum Dot Sensors, Thin-Film Sensors, Micro-Lens Arrays Application: Consumer Electronics, Automotive Imaging, Medical Devices, Industrial Automation End User: OEMs, Research Institutions, Healthcare Providers, Manufacturing Companies |
| Companies Covered | ISORG, FlexEnable Limited, PolyIC GmbH & Co. KG, Interlink Electronics, GSI Technologies, Canatu Oy, MC10, Inc., Plastic Logic, T+Ink, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Image Sensors Market Strategic Shifts
Printed image sensor technology trajectories center on material chemistry substitution, regulatory compliance engineering, and manufacturing process migration from sheet-fed to continuous roll-to-roll platforms.
Perovskite quantum dot active layers are consolidating spectral tunability advantages across medical and industrial imaging segments. Diagnostic device manufacturers in Germany are adopting these materials for disposable dermatological sensors requiring near-infrared sensitivity. The technology is consolidating multispectral capability into single-layer architectures previously requiring external filter arrays or multiple sensor stacks.
REACH authorization procedures and RoHS substance restrictions are compressing cadmium-based quantum dot commercialization timelines. European chemical agency evaluations are forcing reformulation investments toward indium phosphide alternatives before 2027 sunset dates. Medical device substrates face the most acute substitution pressure, as biocompatibility certification cycles cannot accommodate late-stage material changes.
Automotive OEMs are compressing supplier qualification cycles for cabin monitoring printed sensors. Tier-1 integrators are displacing traditional camera module procurement with direct substrate sourcing from printed electronics specialists. This pattern is most visible in German vehicle manufacturing clusters, where KBA type-approval timelines for advanced driver assistance systems are accelerating printed sensor validation protocols.
Printed Image Sensors Market Segmentation
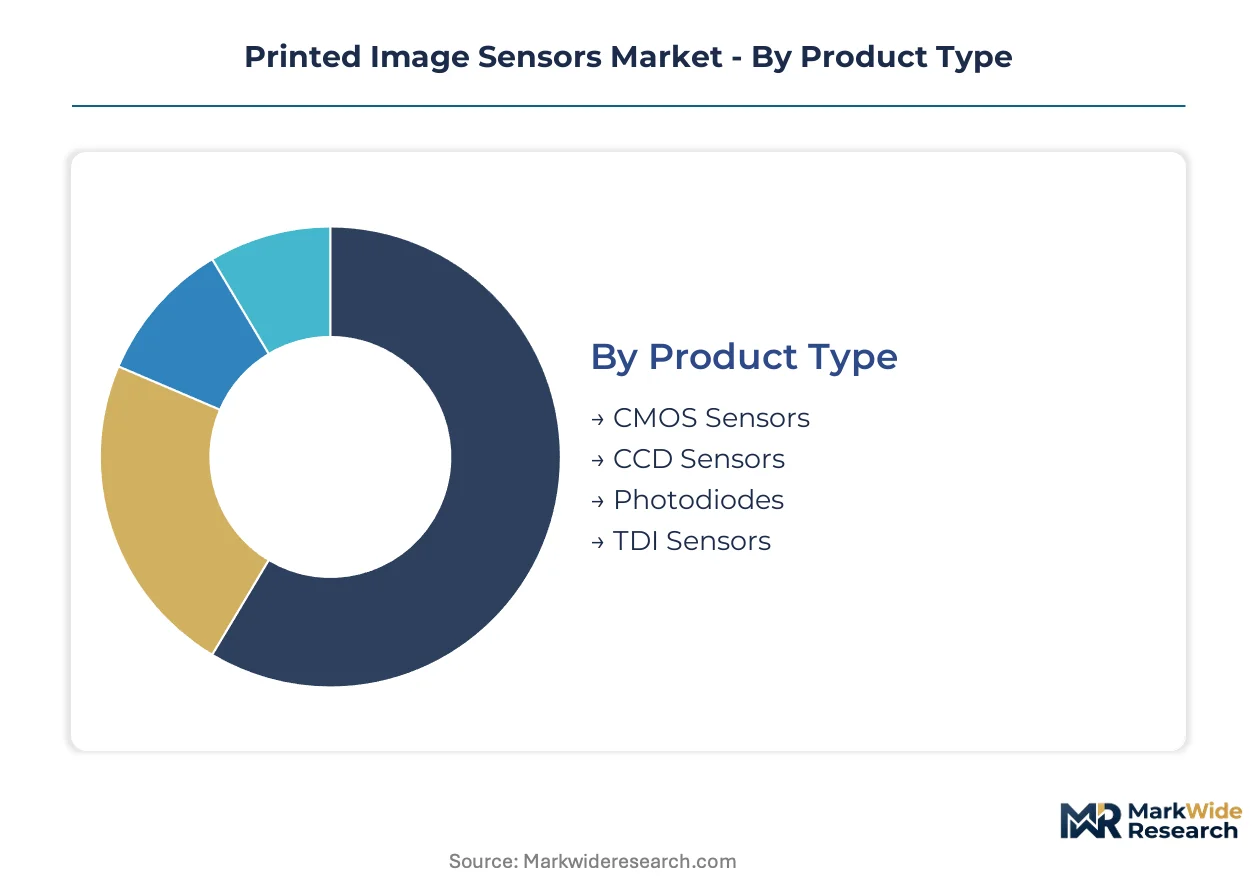
Printed image sensor segmentation reveals distinct integration architectures across product types and end-use environments. Standalone sensor modules serve industrial and research applications, while embedded configurations dominate automotive and consumer electronics deployments where space and weight constraints drive substrate-level integration decisions.
Product Type:
CMOS sensors and TDI sensors anchor high-volume production pipelines, while photodiodes and CCD variants concentrate in specialized imaging workflows requiring distinct readout characteristics.
- CMOS Sensors:Printed CMOS variants employ organic thin-film transistor backplanes compatible with existing readout integrated circuit architectures. Automotive OEMs in Germany are pulling these into cabin monitoring systems where flexible form factors enable curved surface mounting. The EU Green Deal is compressing heavy-metal content specifications, forcing rapid qualification of compliant organic photodetector chemistries.
- TDI Sensors:Time-delay integration architectures accumulate charge across multiple pixel rows, delivering enhanced signal-to-noise ratios for low-light industrial inspection. Manufacturing companies in Japan are deploying these for high-speed production line monitoring where conventional area sensors generate motion blur artifacts. Roll-to-roll fabrication compatibility is reducing unit costs for large-format TDI substrates.
- CCD Sensors:Charge-coupled device printed variants retain niche positioning in scientific imaging requiring precise charge transfer efficiency.
- Photodiodes:Discrete printed photodiodes serve spectroscopic applications where single-point detection suffices.
CMOS sensors lead volumes today; TDI sensors are gaining share fastest in industrial automation end-uses.
Technology:
Material chemistry differentiation determines spectral performance boundaries and regulatory compliance pathways across European, North American, and East Asian supply chains.
- Quantum Dot Sensors:Tunable absorption edges enable multispectral imaging without external filter arrays. Perovskite and indium phosphide formulations are displacing cadmium-based alternatives ahead of REACH sunset dates. Medical device manufacturers in France are qualifying these for disposable dermatological sensors requiring near-infrared sensitivity.
- Organic Photodetectors:Solution-processable semiconductor layers achieve biocompatibility certifications impossible with conventional silicon. Healthcare providers in Germany are sourcing these for single-use endoscopic tools where substrate disposability overrides silicon wafer economics. FlexEnable and PolyIC maintain active pilot production lines for thin-film organic substrates.
- Thin-Film Sensors:Amorphous silicon and metal oxide semiconductors on polymer substrates serve cost-sensitive large-area applications.
- Micro-Lens Arrays:Printed microlens structures concentrate incident light onto active photodetector regions, improving fill factors in compact imager designs.
Organic photodetectors dominate current European medical device procurement; quantum dot sensors show the steepest expansion trajectory across food inspection and agricultural monitoring segments.
Application:
End-use concentration patterns reflect divergent performance requirements, from consumer electronics resolution demands to automotive electromagnetic compatibility mandates.
- Automotive Imaging:Cabin monitoring and advanced driver assistance systems require printed sensors satisfying KBA type-approval protocols for in-vehicle electronics. OEMs are compressing supplier qualification cycles, displacing traditional camera module procurement with direct substrate sourcing from printed electronics specialists. EMC certification for flexible form factors remains unresolved for conventional shielding approaches.
- Medical Devices:Disposable endoscopic and dermatological diagnostic tools command premium positioning against silicon imagers through biocompatible polymer substrates. FDA 510(k) pathways govern integration timelines, with elongated approval cycles for printed imagers lacking predicate device equivalence.
- Consumer Electronics:Smartphone and wearable device integration faces cost-performance barriers from silicon CMOS substitution.
- Industrial Automation:Large-area inspection systems leverage roll-to-roll fabrication economics unavailable with wafer-based approaches.
Medical devices concentrate margin pools; automotive imaging is climbing the fastest as OEM integration accelerates.
End User:
Procurement authority patterns separate volume purchasers with internal integration capabilities from research-driven adopters requiring technical support.
- OEMs:Tier-1 automotive and electronics manufacturers are establishing direct substrate sourcing relationships, bypassing traditional camera module suppliers. German vehicle manufacturing clusters are driving this pattern through accelerated validation protocols for advanced driver assistance systems.
- Healthcare Providers:Hospital systems and diagnostic laboratories are qualifying printed sensors for single-use clinical workflows, prioritizing biocompatibility certification over pixel density metrics.
- Research Institutions:Academic and government laboratories pilot novel organic photodetector chemistries, generating performance datasets for commercial scale-up decisions.
- Manufacturing Companies:Production line operators deploy printed imagers for quality inspection where conformal mounting surfaces enable sensor placement impossible with rigid silicon modules.
OEMs lead procurement volumes; healthcare providers are expanding fastest as disposable medical applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands automotive printed sensor qualification pipelines, while the United States governs medical device integration through FDA pathways. China concentrates indium refining for thin-film transistor backplanes. Japan scales roll-to-roll fabrication for industrial TDI sensors. France qualifies quantum dot formulations for disposable dermatological tools.
Germany
KBA type-approval protocols accelerate printed sensor validation for cabin monitoring systems in Stuttgart and Munich manufacturing clusters. The EU Green Deal compresses heavy-metal content specifications, forcing rapid migration to compliant organic photodetector chemistries. FlexEnable and PolyIC maintain active pilot production lines for thin-film image sensor substrates in the Baden-Württemberg and Bavaria regions.
United States
FDA 510(k) pathways govern integration of printed imagers into disposable endoscopic and dermatological diagnostic tools. The EPA and OSHA frameworks influence biocompatibility certification requirements for wearable medical device substrates. Research institutions in the Greater Boston and San Francisco Bay Area generate performance datasets for organic photodetector commercial scale-up decisions.
China
Indium tin oxide refining operations concentrated in Chinese supply chains expose European and North American fabricators to input cost volatility. MIIT standards and dual carbon goals shape semiconductor coating investments for roll-to-roll compatible fabrication. Yangtze River Delta substrate producers pivot toward large-area imaging applications previously uneconomical with silicon wafer approaches.
Japan
Manufacturing companies deploy TDI sensors for high-speed production line monitoring where conventional area sensors generate motion blur artifacts. METI industrial policy supports roll-to-roll fabrication scaling for large-format substrates. Osaka and Nagoya industrial clusters concentrate expertise in time-delay integration architectures for low-light industrial inspection.
France
Medical device manufacturers qualify perovskite and indium phosphide quantum dot alternatives for disposable dermatological sensors requiring near-infrared sensitivity. ECHA REACH authorization procedures force reformulation investments ahead of cadmium sunset dates. Paris and Lyon healthcare providers source biocompatible polymer substrates for single-use clinical workflows where silicon wafer economics fail.
Printed Image Sensors Market Competitive Environment
European producers anchor the organic photodetector tier; East Asian specialists hold roll-to-roll fabrication capabilities. The vendor base concentrates around printed electronics platforms with proprietary backplane technologies and quantum dot active layer formulations. Three archetypes dominate: organic semiconductor specialists, quantum dot material suppliers, and flexible substrate integrators. Strategic moves center on direct OEM substrate sourcing relationships and pilot line scale-up investments.
Among European fabricators, ISORG, FlexEnable Limited, and PolyIC GmbH & Co. KG exemplify distinct positioning archetypes. ISORG occupies a position anchoring European supply chains for large-area imaging through organic photodetector portfolios. FlexEnable Limited sits within the proprietary technology tier through organic thin-film transistor backplane capabilities. PolyIC GmbH & Co. KG represents the printed electronics platform archetype extending into capacitive and photonic sensing layers.
| Leading Market Players |
|---|
| ISORG |
| FlexEnable Limited |
| PolyIC GmbH & Co. KG |
| Interlink Electronics |
| GSI Technologies |
| Canatu Oy |
| MC10, Inc. |
| Plastic Logic |
| T+Ink, Inc. |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive OEMs in Stuttgart and Munich manufacturing clusters anchor procurement volumes, forcing contract-based long-term offtake structures with volume-tiered discounts that compress margin recovery for substrate specialists lacking scale.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for organic photodetector substrates as FlexEnable and PolyIC expand pilot line throughput. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared medical grades from automotive EMC-qualified tiers and uncertified industrial variants. Cost compression in standard-tier automotive substrates is intensifying because OEMs are consolidating supplier panels. Healthcare providers in France show least price sensitivity due to biocompatibility certification premiums, while industrial automation buyers in Japan drive hardest bargain negotiation.
Supply Chain Analysis
Freight cost volatility for indium tin oxide shipments from Chinese refining operations to European backplane fabricators is amplifying input cost uncertainty. Supply concentrates in China for indium refining, Germany for organic semiconductor formulation, and Japan for TDI sensor roll-to-roll coating. Raw material dependencies span indium metal, organic photodetector precursors, and polymer substrate films. Single-source vulnerability in Chinese indium supply exposes European sensor fabricators to export control disruption. Distribution runs through direct OEM substrate sourcing relationships that displace traditional camera module intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH-compliant organic photodetector production in Germany commands premium positioning against Chinese quantum dot alternatives facing cadmium sunset restrictions.
For Market Incumbents: Lock in indium supply through backward integration into recycling partnerships or long-term offtake agreements with Chinese refiners before export control tightening. Defend margin position by accelerating FDA 510(k) pathway investments for disposable medical substrates where silicon substitution is weakest. For New Entrants and Emerging Players: Enter via near-infrared spectroscopy applications in food quality inspection where tunable quantum dot absorption edges create technical differentiation without competing against established CMOS cost structures. Target agricultural monitoring segments in France and Germany where multispectral imaging demand outpaces incumbent capacity. For Investors and Strategic Acquirers: Tier-1 automotive electronics integrators are the most active acquirer in this space, seeking captive substrate supply for cabin monitoring systems. Over the medium-term horizon, acquisition targets cluster around roll-to-roll coating specialists with active pharmaceutical ingredient-grade cleanroom capabilities. Watch for ECHA REACH authorization decisions on indium phosphide quantum dots as inflection signal for chemistry substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Reformulation | Reformulation investments ahead of ECHA sunset dates secure European medical device procurement pipelines. |
| Roll-to-Roll Fabrication Scale-Up | Capacity expansion in Osaka and Nagoya industrial clusters reduces unit costs for large-format TDI substrates. |
| Direct OEM Substrate Sourcing | Bypassing camera module suppliers accelerates KBA type-approval timelines for automotive printed sensors. |
| FDA 510(k) Pathway Investment | Biocompatibility certification for disposable endoscopic tools commands premium positioning against silicon imagers. |
| Indium Supply Backward Integration | Captive recycling partnerships mitigate Chinese export control exposure for thin-film transistor backplane production. |
Study Parameters
Coverage spans Europe, East Asia, and North America, with primary inputs from each region combining structured interviews with printed electronics R&D directors, automotive Tier-1 procurement managers, hospital biomedical engineers, and regulatory affairs specialists at medical device manufacturers. Secondary validation drew from ECHA REACH authorization databases, FDA 510(k) premarket notification filings, KBA type-approval registries, and MIIT semiconductor industry disclosures. Bottom-up unit shipment estimates triangulated against top-down value projections.
Rate-of-change decomposition across the analysis window separated volume growth from price trajectory and mix shift effects. Segmentation dimensions modeled include product architecture, material chemistry class, end-use application, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns in automotive and medical verticals. Forecast inputs incorporated pilot line capacity announcements, ECHA sunset date schedules, and OEM platform integration timelines.
Inputs from ECHA authorization procedures and FDA predicate device databases were available through the study window; gaps in confidential OEM qualification timelines introduce uncertainty bands around automotive adoption velocity. Forecasts reflect documented assumptions on chemistry substitution rates and regulatory enforcement intensity. A model refresh is warranted upon material change in REACH authorization decisions for quantum dot active layers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Borescope Market
Imaging
Silent Scan Technology Market
Imaging
Underwater Camera Market
Imaging
Photoconductor Drums Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Electron Microscopy Market
Imaging
Low-Light Imaging Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Thermal Imaging Camera Market
Imaging
Mobile Imaging Market
Imaging
Global High-Speed Digital Camera Market
Imaging
AI Camera Market
Imaging
Chemical Imaging Systems Market
Imaging
Camera Lens Market
Imaging
Latin America IP Camera Market