
 Optical Encoder Market | 2026-2036
Optical Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Encoder Market Analysis
Buyer concentration in the optical encoder space is broadening as mid-sized robotics OEMs and medical device manufacturers fragment what was once a concentrated automotive-supplier customer base. Heidenhain anchors premium positioning through in-house glass-scale manufacturing and sub-micron resolution capabilities. Baumer Group competes across industrial automation with modular encoder platforms that simplify integration into servo motor systems.
An optical encoder converts mechanical motion into digital signals through photoelectric scanning of a patterned disc or scale, typically achieving resolutions from hundreds to millions of counts per revolution depending on line density and interpolation electronics. Its primary purpose is closed-loop position and velocity feedback in precision motion control systems. Absolute encoders dominate applications requiring position retention through power cycles, such as surgical robotics and satellite positioning mechanisms, while incremental variants sustain cost-sensitive volume in standard factory automation. Rotary configurations occupy the largest installed base, though linear encoders capture higher per-unit margins in semiconductor lithography and coordinate measuring machines.
FDA device regulations in the United States shape encoder specifications for surgical and diagnostic equipment through electromagnetic compatibility and biocompatibility requirements. EMA and EU MDR standards in Europe impose traceability and risk-management documentation on encoders integrated into patient-contacting systems. ISO 13849 machinery safety standards further dictate reliability grades for encoders in collaborative robot joints. Stakeholders must monitor how functional safety certifications fragment across regional frameworks as automation OEMs pursue single-SKU global product strategies.
Market Dynamics
Collaborative robot OEMs are fragmenting encoder demand patterns as mid-sized manufacturers scale precision motion systems beyond traditional automotive supply chains.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Europe now require absolute encoders with full lifecycle documentation, expanding premium encoder procurement.
- Semiconductor lithography equipment:Sub-nanometer positioning requirements in EUV scanner stages are accelerating demand for linear glass-scale encoders.
- China precision manufacturing clusters:Domestic automation OEMs in Suzhou and Shenzhen are localizing encoder sourcing for servo motor production.
Market Restraints
- Specialized glass substrate concentration:High-purity glass-ceramic disc production concentrates among a handful of Japanese and German suppliers, creating input bottlenecks.
- REACH substance restrictions:RoHS and REACH compliance in Europe is eliminating certain optical adhesives and coatings, forcing reformulation cycles.
- Magnetic encoder substitution:Sealed magnetic encoders are capturing cost-sensitive rotary applications in food processing and washdown environments.
Strategic Opportunities
- India PLI scheme for robotics:Production-linked incentives for industrial automation are attracting encoder suppliers to establish local assembly.
- Surgical robotics FDA 510(k) pathway:Streamlined biocompatibility review for encoder-integrated instruments is opening patient-contacting applications.
- AI-driven predictive maintenance:Encoder health monitoring algorithms are converging with edge computing platforms to create service revenue streams.
Industry Challenges
- Interpolation algorithm expertise:Shortage of firmware engineers capable of implementing sub-divisional error compensation in real-time signal processing.
- ISO 13849 functional safety certification:Extended validation timelines for SIL-rated encoders are delaying collaborative robot joint deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Encoder Market |
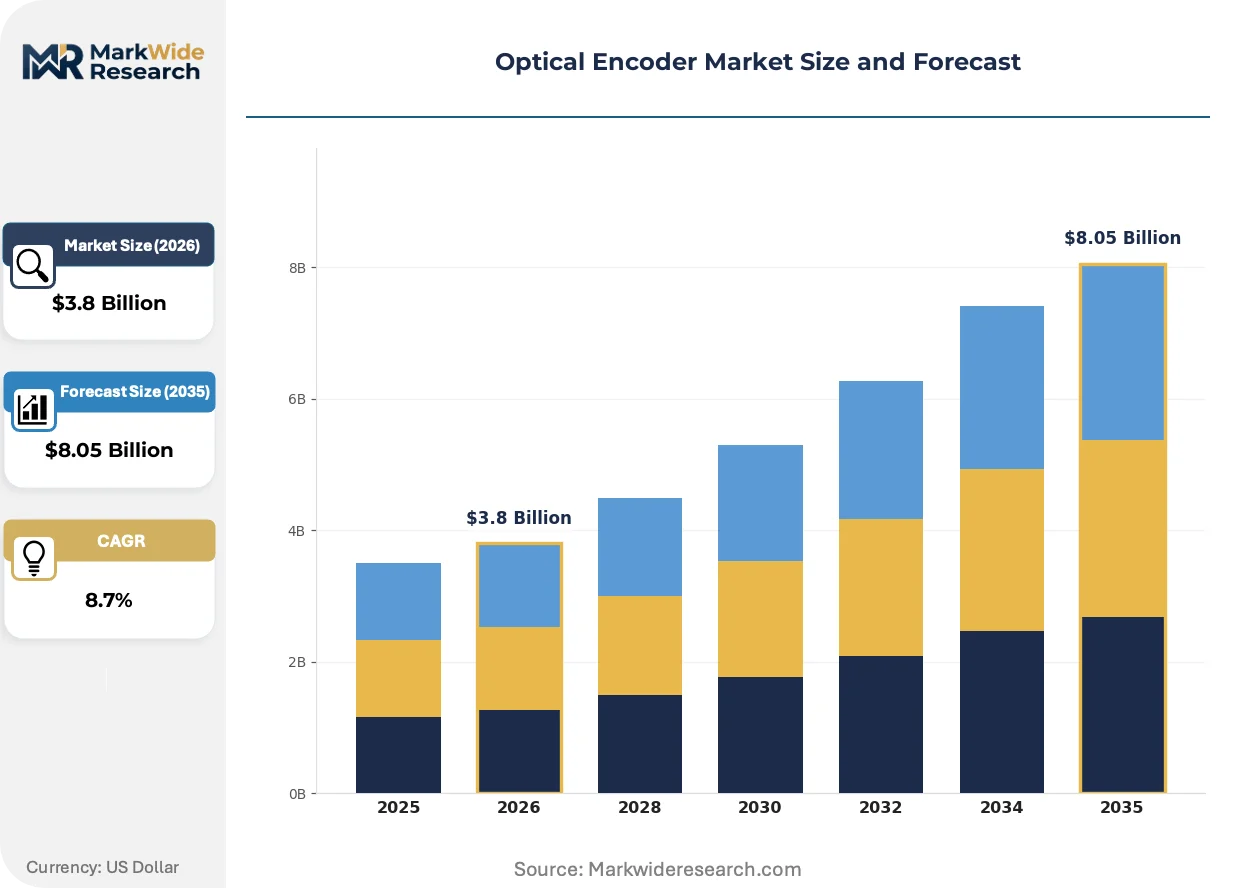
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incremental, Absolute, Rotary, Linear Technology: Optical, Magnetic, Capacitive, Inductive Application: Industrial Automation, Robotics, Automotive, Aerospace End User: Manufacturing, Transportation, Healthcare, Consumer Electronics |
| Companies Covered | Omron Corporation, Baumer Group, Renishaw, Nidec Corporation, Sensata Technologies, Heidenhain, Dynapar, Panasonic Industry, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Encoder Market Emerging Trajectories
Photonic integration and signal processing advances are compressing encoder form factors while expanding resolution capabilities beyond traditional mechanical limits.
Capacitive sensing architectures are overtaking optical scanning in compact servo motor feedback applications. These solid-state designs eliminate glass discs and LED assemblies. Collaborative robot joint manufacturers are adopting them for shock resistance and reduced axial length. The technology is overtaking incremental optical encoders in sub-50mm diameter motor integrations.
REACH Annex XVII restrictions on perfluorinated compounds are forcing optical coating reformulations across European supply chains. ECHA substance evaluations have flagged several anti-reflective treatments used in encoder windows. Manufacturers are qualifying plasma-deposited alternatives. Medical and semiconductor equipment suppliers face the steepest qualification burdens.
Direct OEM contracting is displacing traditional motion control distributor networks for high-volume robotics programs. Encoder suppliers are establishing technical sales offices near Shenzhen, Stuttgart, and Detroit automation clusters. System integrators retain influence in retrofit markets. This channel compression is most pronounced in battery manufacturing and EV powertrain assembly lines.
Optical Encoder Market Segmentation
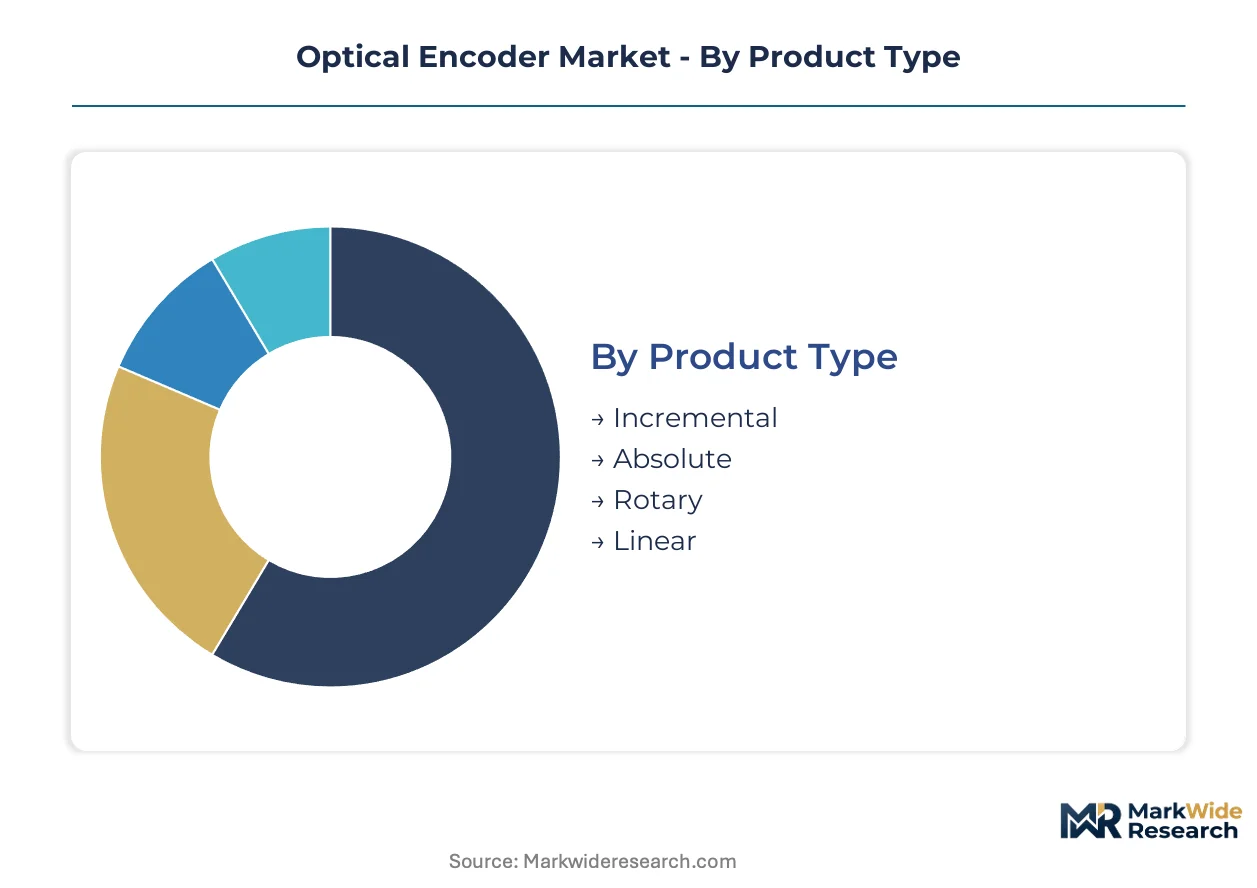
Optical encoder procurement decisions hinge on resolution requirements, environmental sealing, and power-loss position retention. Buyers across robotics and medical equipment prioritize absolute encoding for safety-critical axes while cost-driven factory automation sustains incremental volume.
Product Type:
Resolution specifications and power-cycle behavior drive buyer selection between incremental and absolute architectures.
- Incremental:Generates position data through pulse counting from a patterned disc, requiring homing routines after power loss. Sustains volume in standard factory automation across China and Germany where cost sensitivity dominates multi-axis machine designs.
- Absolute:Encodes unique position values across the entire rotation or stroke, retaining location through power cycles without homing. Concentrates demand in surgical robotics and satellite positioning mechanisms where FDA and EMA safety documentation mandates position certainty.
- Rotary:Dominates installed base across servo motor integrations and collaborative robot joints.
- Linear:Commands premium positioning in semiconductor lithography and coordinate measuring machines.
Rotary encoders lead on scale; absolute encoders lead on momentum.
Technology:
Environmental exposure and shock tolerance reshape technology selection beyond pure resolution metrics.
- Optical:Achieves sub-micron resolution through photoelectric scanning of glass or metal scales with interpolation electronics. Retains dominance in semiconductor lithography equipment across Japan and Germany where sub-nanometer positioning is non-negotiable.
- Magnetic:Employs Hall-effect or magnetoresistive sensing of encoded magnetic poles, eliminating optical contamination risks. Expanding most quickly in food processing and washdown environments across the United States where IP69K sealing requirements exclude glass-disc designs.
- Capacitive:Solid-state architecture eliminates mechanical wear components for compact servo integrations.
- Inductive:Resists extreme temperatures and magnetic interference in heavy industrial settings.
Optical technology commands margin; magnetic technology gains share fastest.
Application:
Precision requirements and safety certification burdens fragment demand across end-use sectors.
- Industrial Automation:Encompasses CNC machinery, packaging equipment, and material handling systems requiring repeatable positioning. Sustains volume across German and Japanese machine tool OEMs where ISO 13849 functional safety grades dictate encoder reliability specifications.
- Robotics:Spans collaborative robot joints, autonomous mobile robots, and surgical manipulators demanding compact form factors. Concentrates growth in Shenzhen and Stuttgart automation clusters where mid-sized OEMs localize encoder sourcing.
- Automotive:Integrates into electric powertrain manufacturing and battery assembly lines.
- Aerospace:Demands radiation-hardened absolute encoders for satellite positioning systems.
Industrial automation leads on scale; robotics leads on momentum.
End User:
Regulatory exposure and production volume determine encoder specification stringency across buyer categories.
- Manufacturing:Spans discrete automation, process industries, and precision machining operations. Sustains the broadest encoder demand across China precision manufacturing clusters in Suzhou and Shenzhen where domestic servo motor production is localizing component sourcing.
- Healthcare:Encompasses surgical robotics, diagnostic imaging, and prosthetic systems requiring biocompatibility documentation. Faces the steepest qualification burdens from FDA 510(k) pathways and EU MDR traceability mandates.
- Transportation:Includes railway signaling and electric vehicle powertrain testing.
- Consumer Electronics:Demands ultra-compact encoders for camera stabilization and haptic feedback systems.
Manufacturing leads on scale; healthcare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics engineers and mechatronics specialists cluster around Stuttgart, Shenzhen, and Nagoya, anchoring regional design capabilities. Their concentration shapes where encoder suppliers establish technical sales offices and application engineering centers.
China
Domestic automation OEMs in Suzhou and Shenzhen are accelerating servo motor production with localized encoder sourcing. MIIT industrial robot deployment targets and dual carbon goals are tightening precision requirements for manufacturing equipment. Yangtze River Delta precision manufacturing clusters now account for the densest concentration of encoder procurement outside Germany and Japan.
Germany
Machine tool OEMs in Baden-Württemberg and Bavaria sustain ISO 13849 functional safety grade demand for collaborative robot joints. REACH and RoHS compliance through ECHA is eliminating legacy optical adhesives, forcing coating reformulations. Stuttgart's automation corridor anchors encoder technical sales density for European industrial automation.
Japan
Sub-nanometer semiconductor lithography equipment from Tokyo and Nagoya drives linear glass-scale encoder specifications. METI semiconductor equipment subsidies are expanding EUV scanner production capacity. Chubu region precision component suppliers concentrate the highest-purity glass-ceramic disc production globally.
United States
FDA 510(k) pathway streamlining for surgical robotics is opening patient-contacting encoder applications in Massachusetts and California clusters. EPA and OSHA workplace safety frameworks shape factory automation encoder specifications. Detroit EV powertrain assembly lines and Boston surgical robotics corridors fragment demand between automotive and medical-grade encoders.
India
PLI scheme production-linked incentives for industrial automation are attracting encoder suppliers to establish local assembly near Pune and Chennai. BIS standard harmonization with ISO machinery safety grades is accelerating collaborative robot joint deployments. Tamil Nadu and Maharashtra precision manufacturing zones are localizing servo motor component sourcing.
Optical Encoder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across encoder technology tiers. The vendor base stratifies between premium resolution specialists and modular platform suppliers serving volume automation. Three archetypes dominate: in-house glass-scale manufacturers, modular encoder platform providers, and sealed magnetic encoder diversifiers. M&A activity concentrates on signal processing firmware capabilities, while capacity expansion targets technical sales proximity to Shenzhen and Stuttgart automation clusters.
Among precision measurement specialists, Heidenhain and Renishaw exemplify the premium-tier archetype through captive glass-scale manufacturing. Baumer Group occupies a position within modular industrial automation platforms. Sensata Technologies and Nidec Corporation represent diversified conglomerate encoders integrated into broader motor and sensor portfolios. Omron Corporation, SICK AG, and Dynapar sit within the factory automation volume tier. Panasonic Industry rounds out the Asia-Pacific headquartered supplier set.
| Leading Market Players |
|---|
| Omron Corporation |
| Baumer Group |
| Renishaw |
| Nidec Corporation |
| Sensata Technologies |
| Heidenhain |
| Dynapar |
| Panasonic Industry |
| SICK AG |
| Others |
Supply Flow & Price Mechanics
Mid-sized robotics OEMs in Shenzhen and Stuttgart are consolidating procurement power through multi-year encoder supply agreements, shifting pricing models from transactional spot purchases toward bundled service contracts that incorporate calibration and predictive maintenance.
Pricing Analysis
Bundled after-sales service packages are separating premium encoder suppliers from unbundled commodity competitors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13849 functional safety certification tiers and glass-scale resolution specifications. Cost compression in economy-tier incremental encoders is intensifying because magnetic encoder substitution is eroding volume in washdown factory automation. Medical device manufacturers in Massachusetts and Baden-Württemberg show the lowest price sensitivity due to FDA 510(k) and EU MDR compliance burdens.
Supply Chain Analysis
Freight cost volatility from Japan and Germany to China precision manufacturing clusters is amplifying landed cost differentials for high-purity glass-ceramic substrates. Production concentrates in Japan, Germany, and China for finished encoders, while raw material supply draws from specialized glass-ceramic foundries in Aichi Prefecture and Bavaria. Single-source vulnerability in sub-nanometer glass-scale production creates chokepoint risk for semiconductor lithography equipment. Distribution runs through direct OEM technical sales offices near automation corridors, bypassing traditional motion control distributors in high-volume robotics programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical encoder market functions as a stable compounder anchored by irreversible automation adoption in precision manufacturing and surgical robotics, where position feedback hardware remains non-displaceable regardless of software advances.
For Market Incumbents: Extend firmware development capabilities in interpolation algorithms and sub-divisional error compensation to defend against capacitive sensing substitution in compact servo motor integrations. Deepen captive glass-scale manufacturing capacity near Nagoya and Stuttgart to tighten supply security for semiconductor lithography customers. Prioritize ISO 13849 SIL-rated certification pipelines to capture collaborative robot joint deployments delayed by validation bottlenecks. For New Entrants and Emerging Players: Solid-state capacitive encoder architectures offer a technology-first wedge into collaborative robot joint manufacturers seeking shock resistance and reduced axial length below 50mm motor diameters. Target India's PLI scheme production zones near Pune and Chennai for local assembly partnerships with domestic servo motor OEMs. Pursue technical sales co-location in Shenzhen automation clusters rather than distributor channel reliance. For Investors and Strategic Acquirers: Diversified sensor conglomerates are the most active acquirers in this space, consolidating signal processing firmware capabilities to complement existing motor and motion control portfolios. The 5-10 year viability window favors targets with in-house glass-scale manufacturing and established FDA/EMA medical device documentation. Watch for inflection when EUV lithography equipment subsidies in Japan accelerate linear encoder demand beyond current glass-ceramic substrate capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass-Scale Manufacturing | Captive substrate production secures supply for sub-nanometer semiconductor lithography positioning systems. |
| Firmware Acquisition for Interpolation Algorithms | Signal processing expertise closes capability gaps in real-time sub-divisional error compensation. |
| Technical Sales Office Expansion | Proximity to Shenzhen and Stuttgart automation clusters compresses OEM contracting cycles. |
| ISO 13849 SIL-Rated Certification Investment | Functional safety validation unlocks collaborative robot joint deployments stalled by compliance timelines. |
| India PLI Scheme Local Assembly | Production-linked incentives attract encoder suppliers to Pune and Chennai servo motor corridors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with encoder product managers at industrial automation OEMs, procurement leads at surgical robotics manufacturers, precision motion system engineers, and aftermarket service heads with secondary validation against METI semiconductor equipment subsidies, ECHA REACH substance restriction filings, FDA 510(k) device databases, and customs trade data for glass-ceramic substrate flows. Bottom-up encoder shipment estimates and top-down precision manufacturing equipment demand projections were triangulated for convergence.
Segment-weighting approaches distributed value and volume across incremental versus absolute architectures, rotary versus linear configurations, optical versus magnetic versus capacitive technologies, and industrial automation versus robotics versus healthcare applications. CAGRs were derived from fitted growth curves against equipment deployment trajectories, with specific inputs including EUV lithography scanner production schedules and collaborative robot joint density per unit.
The model holds under stable regulatory compliance timelines and continued semiconductor capital expenditure; deviation in REACH substance restriction acceleration or magnetic encoder performance breakthroughs would shift substitution dynamics and forecast outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
CVD Sic Ring Market
Optical Components
Optical Transmitter Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Erbium Oxide Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Fluorophore Market
Optical Components
Optical Interconnect Market
Optical Components
Electro Optical System Market
Optical Components
Diode Laser Module Market
Optical Components
Ring Panel Filters Market
Optical Components
North America Optical Film Market
Optical Components
Machine Vision Light Source Market