
 Co-Packaged Optics Market | 2026-2036
Co-Packaged Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Packaged Optics Market Insights
Terabit-scale throughput requirements is reorganizing competitive dynamics in co-packaged optics. Broadcom leverages its switch silicon leadership to define optical-electrical integration roadmaps for hyperscale customers. Intel anchors its position through advanced packaging capabilities that bridge photonic and electronic dies. NVIDIA specializes in co-designing optics with GPU clusters to minimize latency in AI fabric architectures.
Co-packaged optics integrates photonic components directly adjacent to switch ASICs through advanced 2.5D or 3D packaging, eliminating retimer stages and reducing electrical trace lengths to millimeter scales. This architecture primarily serves data centers demanding sub-picojoule-per-bit energy efficiency at terabit aggregate bandwidths. Silicon photonics dominates current design activity due to its CMOS-compatible manufacturing path and waveguide density advantages. Optical transceivers retain substantial revenue share during the transition period as legacy pluggable form factors persist in enterprise and telecom deployments. Cloud service providers represent the fastest-growing end user category, driven by AI cluster buildouts requiring optical bandwidth scaling beyond what copper or traditional pluggable optics can sustain.
FCC equipment authorization rules shape electromagnetic compatibility requirements for co-packaged switch platforms deployed in US data centers. EPA energy efficiency guidelines increasingly influence procurement criteria for optical interconnects in federal and enterprise facilities. OSHA workplace safety standards affect laser power classifications and handling protocols during module installation and maintenance. Stakeholders must monitor how IEEE 802.3 standards evolution and OIF implementation agreements resolve interoperability specifications before committing to single-vendor ecosystem bets.
Market Dynamics
The transition from 25.6 Tbps to 51.2 Tbps switch ASICs is compressing electrical reach budgets to millimeter scales, forcing optical-electrical integration at the package level rather than the board level. This bandwidth inflection point is restructuring supplier relationships and capital allocation across the interconnect stack.
Growth Catalysts
- AI Cluster Power Constraints:Hyperscale operators face strict thermal envelopes in GPU training fabrics, driving demand for sub-picojoule-per-bit optical links that eliminate retimer stages.
- IEEE 802.3dj Standardization:The 200 Gbps per lane electrical specification is creating implementation clarity for co-packaged optical modules, reducing interoperability risk for early adopters.
- Silicon Photonics Yield Maturation:CMOS-compatible foundry processes at 300mm wafer scale are collapsing cost curves for photonic integrated circuits.
Market Restraints
- Advanced Packaging Cost Concentration:2.5D interposer and 3D hybrid bonding capacity concentrates in Taiwan and South Korea, creating supply bottleneck risk for multi-die optical engines.
- Laser Reliability Requirements:Telecom-grade 25-year lifetime specifications for external cavity lasers clash with data center refresh cycles, forcing over-engineering of components.
- Copper Interconnect Substitution:Active electrical cables retain cost advantage below 3 meters, limiting co-packaged optics penetration to rack-scale and cluster-scale deployments.
Strategic Opportunities
- Edge AI Inference Satellites:Distributed inference clusters in secondary metro markets lack the power density of hyperscale campuses, creating demand for lower-power optical integration.
- EU Green Deal Procurement Mandates:European cloud operators face Scope 3 emissions disclosure requirements that favor energy-efficient interconnect technologies in facility buildouts.
- Photonics-Electronics Convergence:Co-design workflows linking electronic design automation with photonic simulation tools are collapsing development cycles for custom optical engines.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:The intersection of thermal, electrical, and optical modeling requires specialized expertise that remains concentrated in academic and national laboratory pipelines.
- OSHA Laser Safety Certification:Class 1M and Class 3B optical power levels in co-packaged modules trigger specialized handling protocols that complicate field deployment and maintenance workflows.
- Legacy Pluggable Inventory Stranding:Enterprise data centers with depreciated QSFP-DD and OSFP infrastructure face write-down risks if migration timelines compress unexpectedly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Packaged Optics Market |
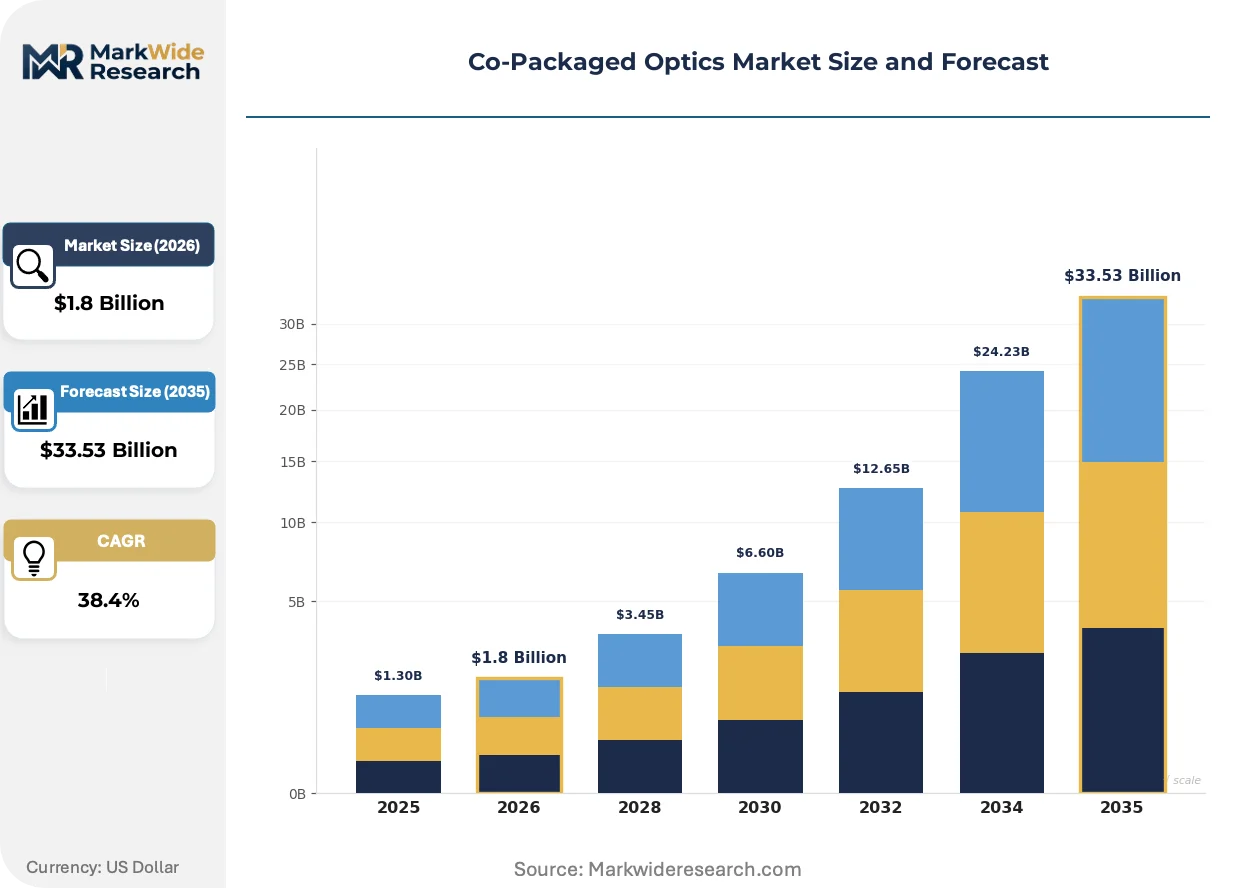
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Optical Cables, Silicon Photonics, Integrated Modules, Optical Transceivers Technology: Coherent Optics, Passive Optics, Electromechanical Interfaces, Optical Interface End User: Data Centers, Telecommunication Providers, Networking Companies, Cloud Service Providers Application: High-Speed Data Transmission, Data Center Interconnects, Network Infrastructure, Broadband Connectivity |
| Companies Covered | Broadcom, Intel, NVIDIA, Marvell, Molex, RANOVUS, Ciena, Ayar Labs, Coherent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Packaged Optics Market Trends and Innovations
Photonic integration roadmaps are diverging across packaging architectures as bandwidth targets outpace legacy interconnect scaling laws. Three distinct vectors are reshaping how optical and electronic functions merge.
Silicon photonics with germanium-on-silicon photodetectors is fragmenting the transceiver supply chain by enabling foundry-based manufacturing separate from traditional optical component specialists. Hyperscale operators are qualifying these devices for 51.2 Tbps switch generations ahead of enterprise adoption curves. The shift is compressing margins for discrete laser and modulator suppliers while elevating semiconductor packaging houses.
EPA energy efficiency guidelines for federal data center procurements are tightening power-per-bit thresholds for interconnect equipment. The rules are accelerating retirement of pluggable optics in government cloud facilities and favoring integrated optical-electrical designs. US federal integrators are rewriting technical specifications to embed these requirements into request-for-proposal documents.
Direct procurement of optical engines by cloud service providers is displacing traditional distributor and value-added reseller channels. Large buyers are establishing technical account relationships directly with silicon photonics foundries and advanced packaging providers. This pattern is most visible in the United States, where hyperscale capital expenditure concentration supports dedicated supply agreements.
Co-Packaged Optics Market Segmentation
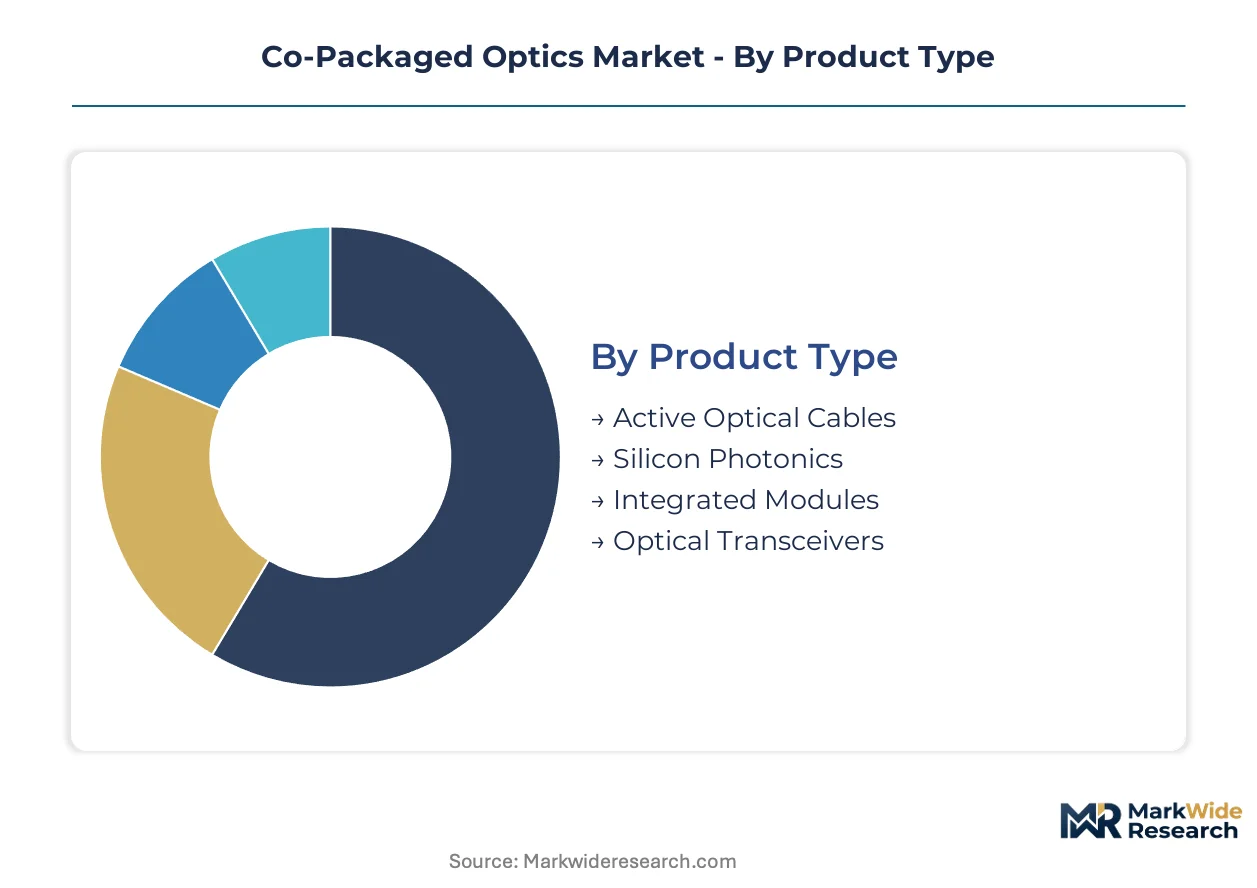
Segmentation in co-packaged optics reveals how technical requirements fragment across deployment scales and customer sophistication. Product architecture, interface standards, and thermal constraints create distinct purchasing patterns that reshape supplier relationships and margin structures.
Product Type:
Domestic demand in the United States concentrates on integrated modules for hyperscale switch platforms, while export flows from Asian foundries supply silicon photonics wafers to global equipment vendors.
- Silicon Photonics:Germanium-on-silicon photodetectors integrated with CMOS waveguides enable 200 Gbps per lane signaling. Hyperscale data centers in Virginia and Oregon drive qualification programs for 51.2 Tbps switch generations, constrained by 300mm wafer capacity concentration in Taiwan.
- Integrated Modules:Multi-die optical engines combine lasers, modulators, and drivers in 2.5D interposer packages. Cloud service providers in California and Washington State specify these for AI training clusters where retimer elimination cuts picojoules-per-bit below legacy alternatives.
- Active Optical Cables:Pluggable assemblies with embedded optical engines serve enterprise data centers with depreciated copper infrastructure.
- Optical Transceivers:QSFP-DD and OSFP form factors retain substantial deployment in telecom central offices with 10-15 year refresh cycles.
Optical transceivers hold the largest share; momentum sits with silicon photonics.
Technology:
Cost tiering separates coherent solutions for metro transport from passive architectures dominating intra-rack connections.
- Coherent Optics:Digital signal processing enables 800 Gbps and 1.6 Tbps transmission over 80km spans. Telecommunication providers in Texas and Illinois deploy these for data center interconnects between primary and secondary metro markets, facing laser power consumption tradeoffs against reach requirements.
- Optical Interface:Direct attach and near-package optics eliminate retimer stages through millimeter-scale electrical traces. Networking companies in North Carolina and Massachusetts qualify these for 51.2 Tbps switch ASICs where IEEE 802.3dj electrical specifications compress reach budgets.
- Passive Optics:Waveguide-based interconnects without active amplification serve sub-2-meter reach inside server racks.
- Electromechanical Interfaces:Precision alignment structures bridge photonic and electronic dies in hybrid packaging.
Optical interface adoption is climbing the fastest as switch bandwidth doubles; coherent optics maintains revenue concentration in telecom applications.
End User:
Customer type determines procurement sophistication, with cloud operators rewriting specifications while enterprises defer to system integrators.
- Cloud Service Providers:Direct technical account relationships with silicon photonics foundries bypass traditional distribution. Operators in the United States negotiate dedicated supply agreements for 51.2 Tbps switch platforms, constrained by OSHA Class 1M laser handling protocols during field deployment.
- Data Centers:Colocation and enterprise facilities balance performance against depreciation schedules. Facilities in Arizona and Nevada prioritize EPA energy efficiency guidelines in procurement criteria, favoring integrated optical-electrical designs for federal compliance.
- Telecommunication Providers:Central office and metro transport networks maintain 25-year reliability specifications that clash with data center refresh cycles.
- Networking Companies:Switch and router OEMs integrate optical engines at board level pending package-level maturation.
Data centers represent the largest installed base; cloud service providers are gaining share fastest through AI cluster buildouts.
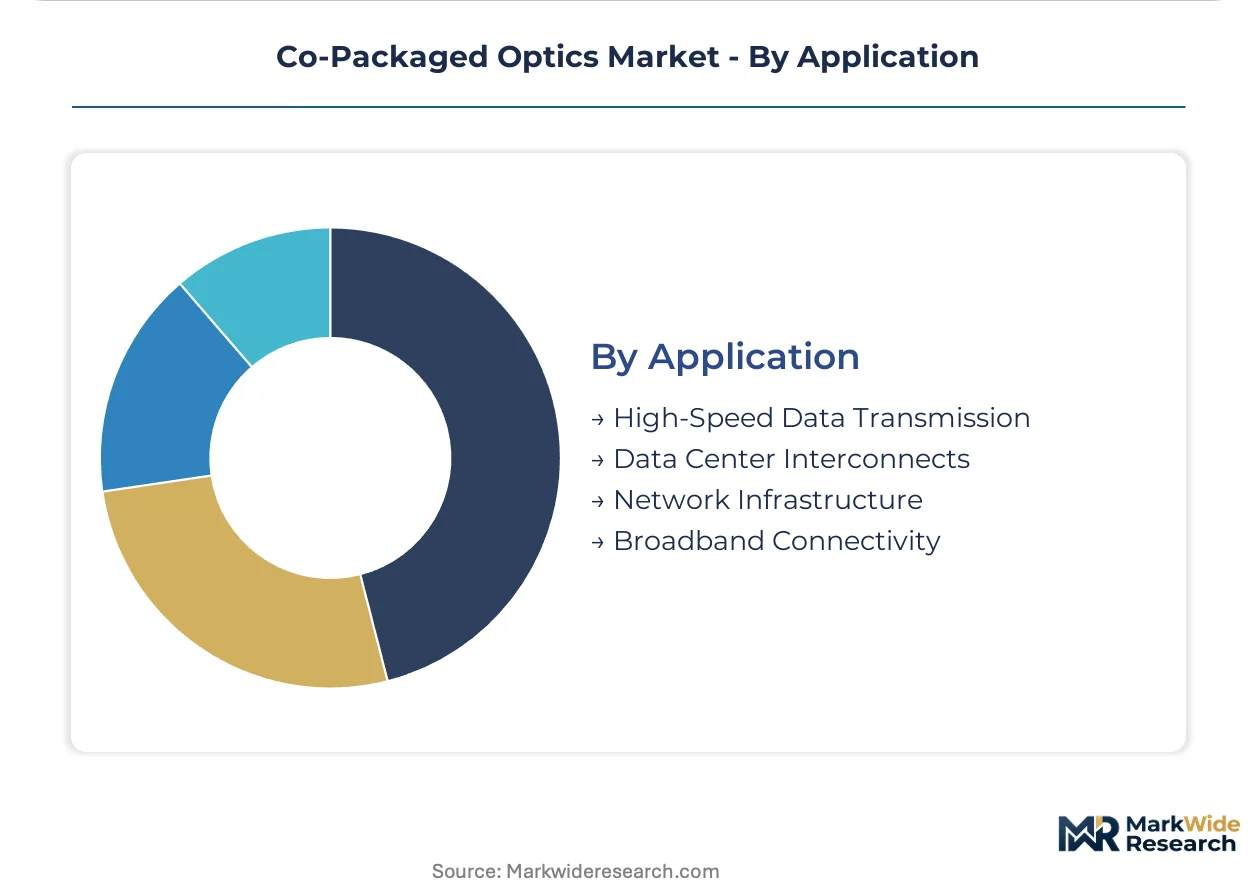
Application:
Volume concentrates in high-speed data transmission as training cluster bandwidth requirements outpace legacy scaling laws.
- High-Speed Data Transmission:GPU-to-GPU and GPU-to-switch links in AI fabrics demand sub-picojoule-per-bit efficiency. Training clusters in New Mexico and Georgia deploy co-packaged optics to stay within strict thermal envelopes, with copper substitution failing beyond 3-meter reaches.
- Data Center Interconnects:Campus and metro links between compute pools require coherent modulation for distance. Operators in Colorado and Utah bridge facilities with 10-80km spans where passive optics attenuate beyond utility.
- Network Infrastructure:Core router backplanes and aggregation switches transition from pluggable to integrated optics.
- Broadband Connectivity:Access network upgrades retain pluggable transceiver dominance due to cost sensitivity and lower bandwidth density.
Data center interconnects command premium pricing; high-speed data transmission shows the steepest expansion trajectory as AI training scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of silicon photonics wafers concentrate in Taiwan and South Korea, while the United States imports advanced packaging capacity for switch ASIC integration. This trade pattern shapes regional investment priorities as data center buildouts accelerate.
United States
Hyperscale operators in Virginia and Oregon deploy first commercial volumes of co-packaged switch platforms for AI training clusters. FCC equipment authorization rules govern electromagnetic compatibility for these deployments. Cloud service providers in California negotiate direct supply agreements with foundries, bypassing traditional distribution channels.
Taiwan
300mm wafer-scale silicon photonics manufacturing serves global demand for photonic integrated circuits. The island's foundries face capacity constraints as 51.2 Tbps switch generations ramp. Advanced packaging houses in Hsinchu Science Park hybrid bond photonic and electronic dies for multi-die optical engines.
South Korea
Memory and logic semiconductor infrastructure extends into photonics packaging through existing 2.5D interposer capabilities. The country's national industrial regulator supports advanced packaging investments under semiconductor competitiveness programs. Samsung and SK Hynix supplier ecosystems in Suwon and Icheon adapt DRAM packaging expertise to optical-electrical integration.
China
Domestic switch ASIC development drives parallel qualification of local silicon photonics supply chains. MIIT standards for data center equipment shape procurement specifications for state-owned cloud operators. Yangtze River Delta packaging houses in Suzhou and Wuxi develop captive optical engine capacity for indigenous switch platforms.
Japan
Telecommunication equipment vendors in Tokyo and Osaka maintain 25-year reliability specifications for metro transport applications. METI energy efficiency guidelines influence procurement criteria for domestic data center operators. Photonics specialists in Kanagawa Prefecture supply external cavity lasers for coherent optics in long-haul interconnects.
Co-Packaged Optics Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration depth. The market structures around semiconductor giants with captive optical programs, independent photonics specialists, and advanced packaging houses. Three archetypes dominate: switch silicon vendors extending into optics, pure-play photonics integrators, and packaging service providers. M&A activity concentrates on photonics startups with proven foundry relationships, while capacity expansion targets 2.5D interposer throughput for multi-die engines.
Within the switch silicon tier, Broadcom and Marvell exemplify vendors leveraging ASIC leadership to define optical-electrical integration roadmaps. NVIDIA occupies a position as a GPU cluster architect co-designing optics for AI fabric minimization. Among independent photonics specialists, Ayar Labs and RANOVUS represent pure-play approaches to package-level optical integration without captive silicon.
| Leading Market Players |
|---|
| Broadcom |
| Intel |
| NVIDIA |
| Marvell |
| Molex |
| RANOVUS |
| Ciena |
| Ayar Labs |
| Coherent |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for 300mm silicon photonics wafers concentrate pricing power with Taiwan foundries while compressing margins for downstream optical engine integrators. This inventory-to-delivery gap forces cloud service providers into long-term offtake agreements that lock in volume commitments ahead of IEEE 802.3dj qualification cycles.
Pricing Analysis
Cloud service providers anchor three-tier pricing structure across premium, standard, and economy levels in co-packaged optics procurement. Premium tiers command position through 2.5D interposer integration and sub-picojoule-per-bit performance guarantees, while standard tiers trade thermal envelope specifications for cost reduction. Price differentiation hinges on laser source reliability grades and foundry process node certification. Cost compression in economy-tier active optical cables is intensifying because copper interconnects retain advantage below three-meter reaches. Enterprise data centers exhibit highest price sensitivity due to depreciated QSFP-DD inventory exposure, whereas hyperscale operators prioritize energy efficiency over unit cost.
Supply Chain Analysis
Strategic stockpiling of germanium-on-silicon photodetectors dominates procurement behavior as yield maturation lags 51.2 Tbps switch ASIC ramps. Supply concentrates in Taiwan wafer fabrication, South Korean 2.5D interposer packaging, and US-based switch silicon integration. Raw material dependencies span III-V compound semiconductors for lasers, high-purity silicon substrates, and advanced organic substrates for hybrid bonding. Single-source vulnerability in Taiwan advanced packaging capacity creates bottleneck risk for multi-die optical engines. Distribution runs through direct technical account relationships that displace traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-packaged optics represents a high-growth disruption as 51.2 Tbps switch bandwidth inflection forces optical-electrical integration at package level. The EPA's tightening federal data center efficiency guidelines accelerate retirement of legacy pluggable form factors.
For Market Incumbents: Compound switch silicon leadership into captive optical engine roadmaps through backward integration into silicon photonics foundry relationships. Defend margin position by securing dedicated 2.5D interposer capacity in Taiwan and South Korea before multi-die packaging bottlenecks intensify. Accelerate IEEE 802.3dj interoperability certification to reduce customer single-vendor lock-in risk. For New Entrants and Emerging Players: Anchor in edge AI inference satellites across secondary US metro markets where power density constraints favor lower-power optical integration. Target enterprise data centers in Arizona and Nevada facing EPA compliance deadlines with retrofit-focused active optical cable solutions. Pursue photonics-electronics co-design software partnerships to collapse development cycles against established semiconductor packaging houses. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-semiconductor convergence play because data center energy efficiency mandates hardwire optical bandwidth scaling into AI cluster economics. Acquisition candidates with proven foundry relationships and OSHA Class 1M laser safety certification protocols command scarcity premiums. Watch for hyperscale direct procurement announcements as signal of distributor channel permanent displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures 300mm wafer capacity for 200 Gbps per lane photonic integrated circuits. |
| 2.5D Interposer Capacity Expansion | Addresses Taiwan packaging bottleneck for multi-die optical engine hybrid bonding. |
| EPA Energy Efficiency Certification | Unlocks federal data center procurement criteria for integrated optical-electrical designs. |
| Direct Hyperscale Technical Account | Bypasses stranded distributor inventory through cloud provider supply agreement. |
| Photonics-Electronics Co-Design Platform | Collapses thermal-electrical-optical multiphysics simulation cycles for custom engines. |
Research Methodology
The analysis maps silicon photonics integration tiers, switch ASIC bandwidth generations, and packaging architecture roadmaps, each validated through hyperscale procurement executives, advanced packaging engineering directors, and semiconductor foundry account managers. Primary fieldwork combined structured interviews with secondary validation against SEC hyperscaler capex disclosures, IEEE standards committee documentation, and EPA federal procurement guideline revisions. Bottom-up demand modeling from switch platform deployment schedules triangulates against top-down market sizing from foundry capacity announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product architecture, interface standard, thermal envelope, and end-user procurement sophistication. CAGRs derive from bandwidth demand elasticity against switch ASIC release cadence, with specific inputs including AI training cluster power density constraints and OSHA laser safety certification adoption curves.
Material uncertainties — IEEE 802.3dj implementation timeline slippage, Taiwan packaging capacity allocation shifts, copper interconnect active cable substitution thresholds — sit outside the modeled envelope. Forecasts reflect assumptions on hyperscale capital expenditure concentration and foundry yield maturation trajectories. Revision becomes warranted when cloud service provider direct procurement penetration crosses critical mass thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Film Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Liquid Lenses Market
Optical Components
Electro Optical System Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Passive Optical Component Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Diode Laser Module Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Spectroradiometers Market
Optical Components
Optical Component Tester Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Digital Cinema Lens Market