
 Picosecond and Femtosecond Fiber Lasers Market | 2026-2036
Picosecond and Femtosecond Fiber Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Picosecond and Femtosecond Fiber Lasers Market Insights
A shortage of ultrafast laser physicists and fiber-optic engineers is redrawing competitive boundaries across the supply base. IPG Photonics Corporation leverages in-house diode and fiber fabrication to sustain cost advantages at high average powers. Coherent Corp. anchors its position through vertical control of crystal growth and coating capabilities. NKT Photonics specializes in nonlinear fiber architectures that dominate supercontinuum generation niches.
Picosecond and femtosecond fiber lasers generate optical pulses with durations between 10⁻¹² and 10⁻¹⁵ seconds, typically employing ytterbium-doped or erbium-doped gain fibers mode-locked via saturable absorbers or nonlinear polarization evolution. These systems deliver peak powers exceeding megawatts while maintaining near-diffraction-limited beam quality for cold ablation of metals, polymers, and biological tissue without thermal diffusion zones. Femtosecond lasers command premium positioning in corneal refractive surgery and transparent material micromachining where pulse duration directly determines feature resolution. Material processing applications absorb the dominant volume share, though biomedical segments generate disproportionate margin pools due to regulatory barriers and clinical validation requirements. Optical fiber technology leads unit shipments, yet solid-state architectures retain footholds in scientific instrumentation demanding sub-50-fs pulse widths.
FDA 510(k) clearance requirements govern surgical laser deployments in the United States, while EU MDR and CE marking impose clinical evidence standards for ophthalmic and dermatological systems sold across Europe. ISO 13485 quality management certification functions as a de facto market-access threshold for healthcare-oriented suppliers. China's NMPA registration pathway and GB laser safety standards shape domestic procurement criteria for industrial and medical units alike. Stakeholders must weigh regulatory capital intensity against the margin premiums available in clinically validated segments versus commodity material-processing contracts.
Market Dynamics
East Asian precision electronics manufacturers are compressing feature tolerances below 10 micrometers, forcing laser suppliers to deliver sub-picosecond pulse stability at industrial throughput rates. This miniaturization imperative is redrawing equipment specifications across semiconductor packaging, flexible circuit fabrication, and microLED repair workflows.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined surgical laser clearances in the United States are compressing clinical validation timelines for femtosecond ophthalmic platforms. Corneal refractive procedures now access commercial deployment within 12-18 months of submission.
- EU MDR CE Marking Harmonization:Consolidated clinical evidence standards across European dermatological and surgical laser categories are reducing redundant testing burdens. Single certification runs now unlock 27 national markets simultaneously.
- Yangtze River Delta Cluster Expansion:China's electronics manufacturing corridor is absorbing record volumes of picosecond systems for flexible PCB drilling and glass cutting. Local NMPA registration pathways align procurement with domestic safety standards.
Market Restraints
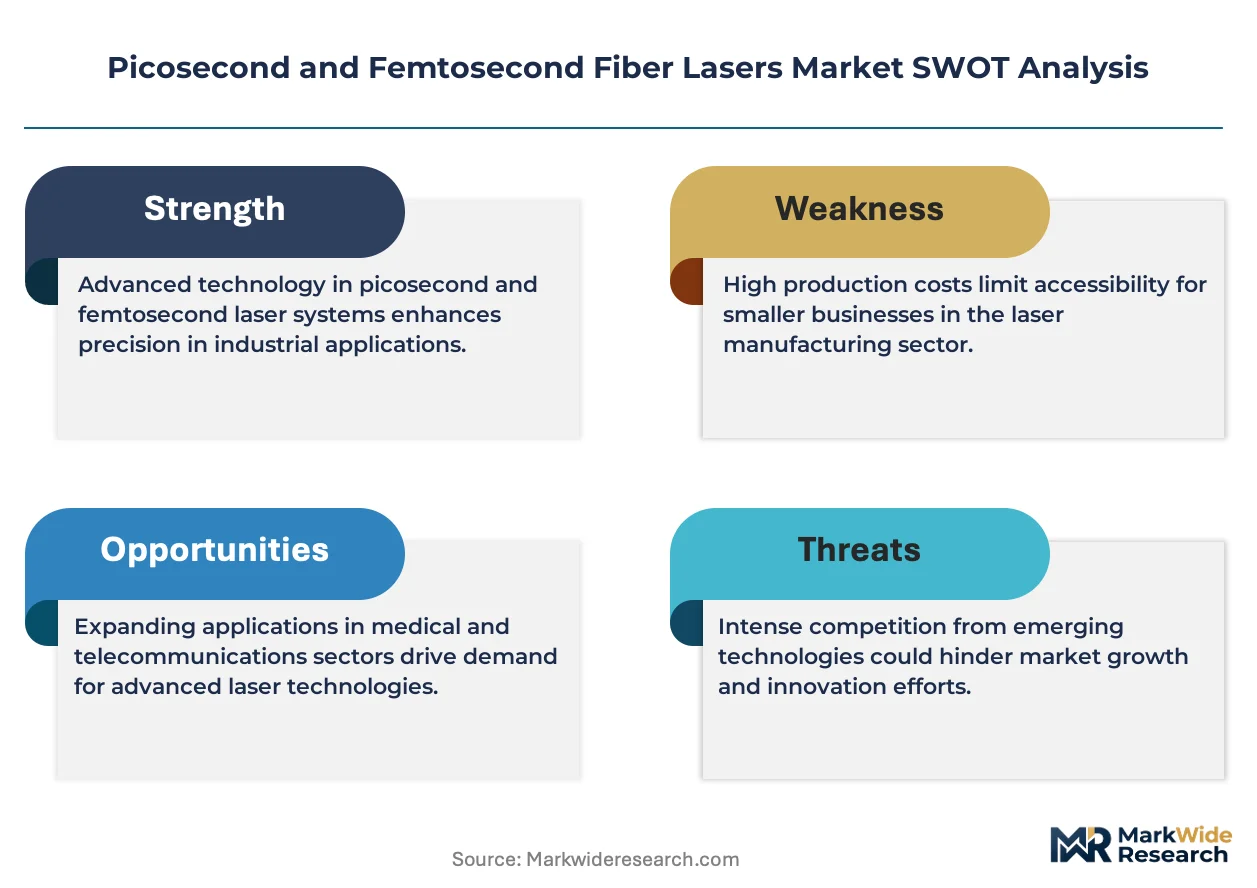
- Rare-Earth Fiber Cost Volatility:Ytterbium-doped and erbium-doped gain fiber prices fluctuate with Chinese export quotas on raw rare-earth oxides. IPG Photonics and NKT Photonics mitigate exposure through captive preform manufacturing.
- German Precision-Tooling Supply Concentration:Beam delivery optics and scanning galvanometer production clusters heavily in Baden-Württemberg and Bavaria. Disruptions to this corridor propagate through global system assembly schedules.
- Thermal Diffusion Limitations:Picosecond architectures cannot achieve the sub-50-femtosecond pulse widths demanded by attosecond spectroscopy and certain multiphoton microscopy protocols. Solid-state alternatives retain lock-in for these scientific instrumentation niches.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for semiconductor and display manufacturing are attracting greenfield fab investments. Local laser system procurement will scale with domestic packaging and testing capacity buildouts.
- Neurostimulation Device Micromachining:Femtosecond cold ablation enables polymer microchannel fabrication for implantable neural interfaces without thermal damage to biocompatible coatings. This application remains commercially underdeveloped.
- ISO 13485 Certification Arbitrage:Quality management certification for medical devices functions as a de facto market-access threshold. Suppliers achieving this standard unlock margin premiums in clinically validated segments versus commodity industrial contracts.
Industry Challenges
- Ultrafast Laser Physicist Scarcity:Mode-locked fiber design and nonlinear pulse propagation modeling require specialized expertise concentrated in university photonics departments. Industrial employers compete with academic and national laboratory recruitment.
- Multi-Jurisdiction Certification Parallelism:Simultaneous FDA, EU MDR, NMPA, and PMDA submissions demand redundant clinical trials and documentation. Small and mid-cap suppliers face capital constraints navigating this matrix.
- Legacy Solid-State System Integration:Industrial customers with installed titanium-sapphire amplifier bases resist full fiber platform transitions due to retraining costs and process revalidation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Picosecond and Femtosecond Fiber Lasers Market |
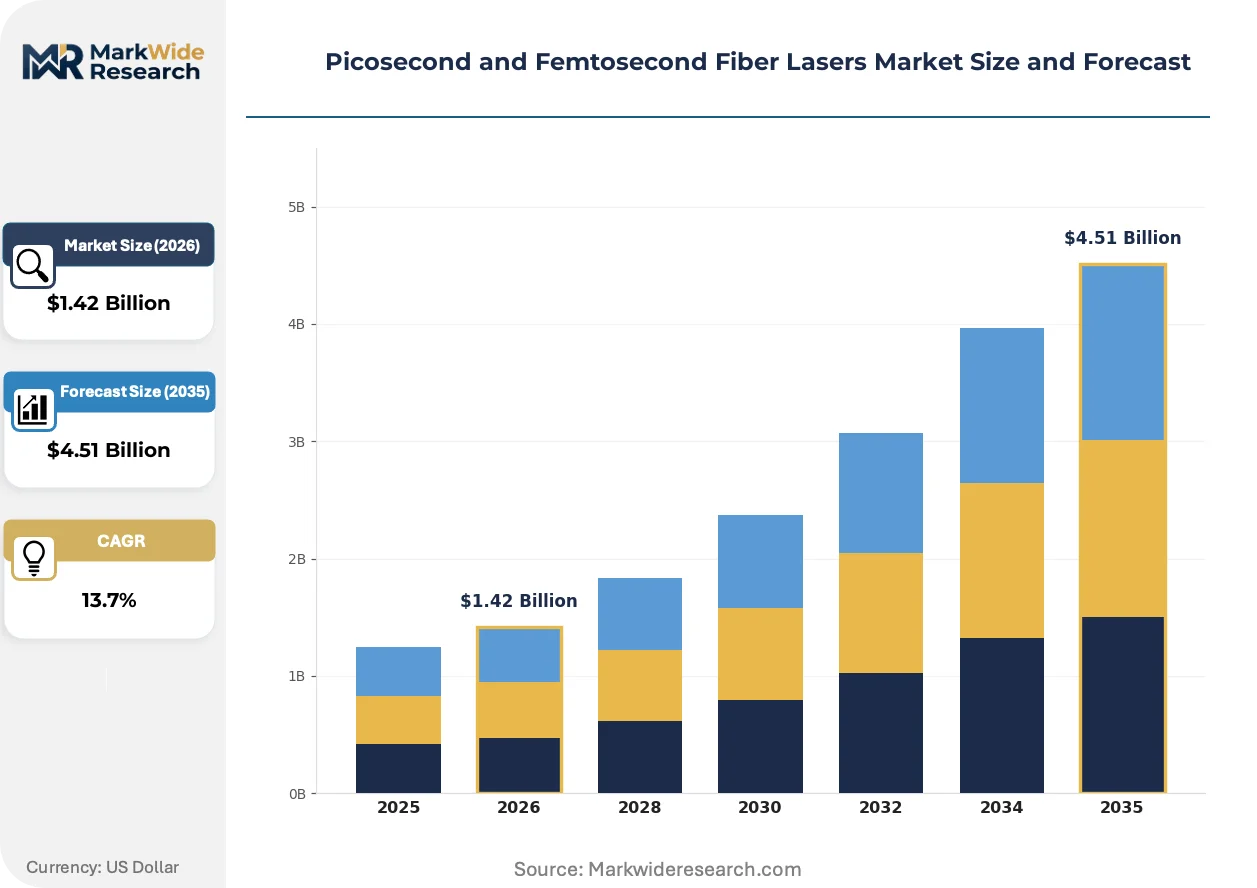
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Picosecond Lasers, Femtosecond Lasers, Ultrafast Lasers, Continuous Wave Lasers Application: Material Processing, Biomedical, Aerospace, Communications End User: Manufacturing, Research Institutions, Healthcare, Electronics Technology: Optical Fiber, Solid State, Semiconductor, Others |
| Companies Covered | IPG Photonics Corporation, Coherent Corp., Lumentum Holdings Inc., TRUMPF SE + Co. KG, MKS Instruments Inc., NKT Photonics, Spark Lasers, Toptica Photonics, EKSPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Picosecond and Femtosecond Fiber Lasers Market Trends and Innovations
Ytterbium-doped fiber master-oscillator power-amplifier architectures are displacing bulk solid-state platforms across industrial micromachining workflows. This transition compresses footprint, improves wall-plug efficiency, and enables turnkey operation without active cavity alignment.
All-fiber nonlinear polarization evolution mode-locking is miniaturizing seed oscillator designs to palm-scale packages. Medical device OEMs in Germany and Japan are integrating these subsystems into portable dermatological and ophthalmic platforms. The structural consequence is collapsing the traditional separation between laboratory-grade and clinical-deployable laser sources.
EU MDR clinical evidence requirements for surgical laser systems are elevating post-market surveillance obligations. Manufacturers must now maintain active implant registries and periodic safety update reports across CE-marked device portfolios. Ophthalmic femtosecond platforms face the steepest compliance burden, with notified body audit frequencies doubling relative to pre-2021 Medical Device Directive baselines.
Japanese automotive suppliers are unbundling laser system procurement from traditional integrator channels. Tier-1 component manufacturers now source ytterbium fiber modules directly from NKT Photonics and IPG Photonics for in-house welding station development. This disintermediation concentrates in Toyota and Honda supply chains, where vertical integration into production engineering reduces cycle-time dependencies on external system houses.
Picosecond and Femtosecond Fiber Lasers Market Segmentation
Ultrafast fiber laser procurement channels diverge sharply between industrial system integrators and medical device OEMs, with certification requirements and service infrastructure dictating segment-specific distribution strategies. Understanding these channel dynamics illuminates where margin pools concentrate versus where volume flows.
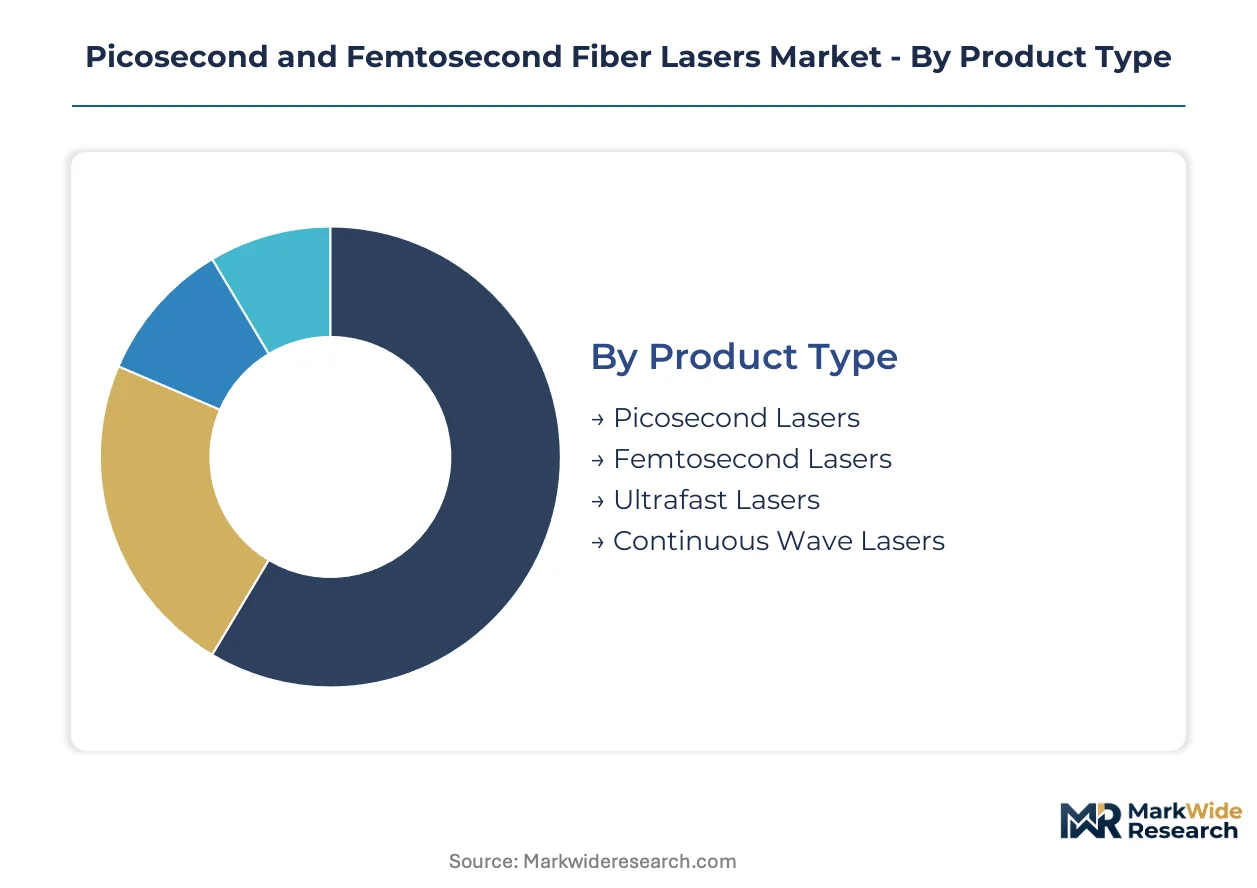
Product Type:
Channel concentration varies by pulse architecture, with femtosecond platforms flowing predominantly through medical device distributors while picosecond systems move via industrial automation integrators.
- Picosecond Lasers:Pulse durations between 1-10 picoseconds deliver peak powers sufficient for cold ablation of metals and ceramics without thermal diffusion zones. Electronics manufacturers in China's Yangtze River Delta absorb the dominant volume for flexible PCB drilling and glass cutting applications where throughput trumps ultimate precision.
- Femtosecond Lasers:Sub-picosecond pulse widths enable multiphoton absorption in transparent materials and intrastromal tissue dissection with micron-level accuracy. Corneal refractive surgery platforms in Germany and Japan command premium positioning through FDA 510(k) and PMDA clearance pathways that filter distribution through specialized ophthalmic equipment channels.
- Ultrafast Lasers:Broader category encompassing both pulse regimes serves scientific instrumentation markets through university procurement offices and national laboratory supply contracts.
- Continuous Wave Lasers:Non-pulsed architectures retain footholds in pump laser and seed oscillator applications where cost sensitivity outweighs peak power requirements.
By volume, picosecond systems lead. By growth pace, femtosecond platforms are climbing the fastest.
Application:
Application-driven cost tiers separate commodity material processing contracts from clinically validated medical deployments, with regulatory capital intensity creating distinct margin structures.
- Material Processing:Semiconductor packaging, microLED repair, and flexible circuit fabrication absorb industrial system volumes. East Asian precision electronics manufacturers compress feature tolerances below 10 micrometers, forcing suppliers to deliver sub-picosecond stability at production throughput rates.
- Biomedical:Ophthalmic refractive surgery and dermatological resurfacing generate disproportionate margin pools due to FDA, EU MDR, and PMDA clinical evidence requirements. Post-market surveillance obligations for CE-marked surgical systems have doubled audit frequencies relative to pre-2021 baselines.
- Aerospace:Turbine blade cooling hole drilling and composite material trimming demand beam delivery systems certified to AS9100 quality standards, restricting supplier pools to established aerospace tier-1 integrators.
- Communications:Telecom test equipment and optical component manufacturing utilize lower-power picosecond sources where cost-per-watt efficiency dominates procurement criteria.
Material processing commands unit volume leadership. Biomedical applications capture the steepest expansion trajectory.
End User:
Customer type determines specification complexity, with research institutions demanding configurable platforms while manufacturing buyers prioritize turnkey reliability.
- Manufacturing:Automotive suppliers in Japan are unbundling laser procurement from traditional integrator channels, sourcing ytterbium fiber modules directly for in-house welding station development. This disintermediation concentrates in Toyota and Honda supply chains.
- Research Institutions:Attosecond spectroscopy and multiphoton microscopy protocols require sub-50-femtosecond pulse widths that fiber architectures cannot achieve, locking scientific demand into solid-state titanium-sapphire alternatives.
- Healthcare:Hospital systems and ambulatory surgery centers acquire femtosecond ophthalmic platforms through group purchasing organizations that negotiate service-inclusive contracts spanning 5-7 year depreciation cycles.
- Electronics:Contract manufacturers in India's emerging semiconductor packaging sector will scale procurement alongside PLI scheme-induced domestic fab capacity buildouts.
Manufacturing end users dominate current volume. Healthcare procurement is gaining share fastest.
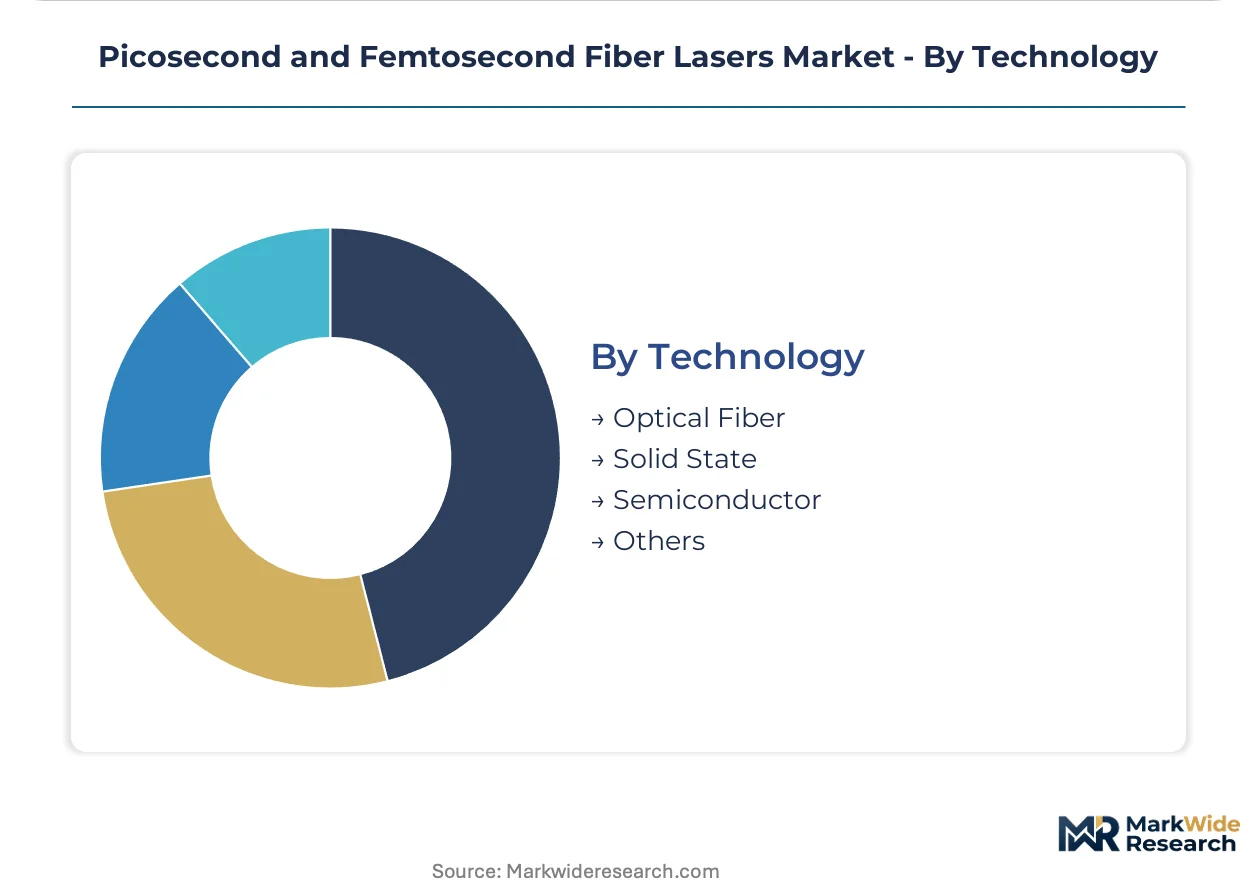
Technology:
Technology maturity curves separate volume-shipping fiber architectures from performance-leading solid-state alternatives, with supply concentration in rare-earth fiber preform manufacturing creating cost tier differentiation.
- Optical Fiber:Ytterbium-doped master-oscillator power-amplifier designs displace bulk solid-state platforms across industrial micromachining. All-fiber nonlinear polarization evolution mode-locking miniaturizes seed oscillators to palm-scale packages for portable medical platforms.
- Solid State:Titanium-sapphire and Yb:KGW crystals retain lock-in for scientific instrumentation demanding sub-50-fs pulse widths and broadband tunability. IPG Photonics and Coherent Corp. maintain captive crystal growth capabilities to mitigate supply risk.
- Semiconductor:Vertical-cavity surface-emitting laser and quantum dot saturable absorber technologies enable compact seed oscillator designs for OEM integration.
- Others:Emerging architectures including thin-disk and Innoslab geometries serve niche high-average-power applications where thermal management limits fiber scalability.
Optical fiber leads by shipment volume. Solid-state platforms command the highest average selling prices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearances anchor the United States as the dominant geography for surgical laser commercialization, while China's NMPA pathways and Germany's precision-tooling corridors concentrate industrial procurement. Regulatory divergence across these three markets is fragmenting certification strategies for multinational suppliers.
United States
Ophthalmic refractive surgery platforms drive femtosecond laser procurement through FDA 510(k) pathways that compress validation timelines to 12-18 months. Hospital systems and ambulatory surgery centers acquire systems through group purchasing organizations negotiating service-inclusive contracts. The Boston-Cambridge corridor hosts concentrated medical device OEM development activity.
Germany
Precision-tooling manufacturers in Baden-Württemberg and Bavaria absorb picosecond systems for automotive component micromachining. EU MDR CE marking harmonization reduces redundant testing burdens across 27 national markets. Beam delivery optics and scanning galvanometer production clusters heavily in Stuttgart and Munich metropolitan areas.
China
Electronics contract manufacturers in the Yangtze River Delta deploy record volumes for flexible PCB drilling and microLED repair workflows. NMPA registration pathways align procurement with GB laser safety standards for domestic industrial and medical units. Shanghai and Suzhou anchor the electronics manufacturing corridor driving sub-picosecond pulse stability requirements.
Japan
Toyota and Honda supply chains are disintermediating traditional integrators to source ytterbium fiber modules directly for in-house welding station development. PMDA clearance pathways govern ophthalmic femtosecond platform commercialization. The Nagoya-Toyota industrial belt concentrates automotive laser welding application engineering.
India
Production-linked incentive schemes for semiconductor and display manufacturing are attracting greenfield fab investments. CDSCO medical device regulations shape procurement criteria for clinical laser systems. Gujarat and Karnataka will scale domestic packaging and testing capacity alongside laser system procurement buildouts.
Picosecond and Femtosecond Fiber Lasers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive rare-earth fiber preform manufacturing separating cost tiers. The vendor base organizes around three archetypes: vertically integrated diode-to-system suppliers, crystal growth specialists, and nonlinear fiber architects. Competitive moves concentrate on M&A for regulatory certification portfolios and capacity expansion in ytterbium-doped fiber amplification.
Within the integrated tier, IPG Photonics Corporation and Coherent Corp. exemplify archetypes defined by in-house control over upstream components. NKT Photonics occupies a position among specialists leveraging nonlinear fiber architectures. These three anchors represent distinct competitive vectors: captive diode fabrication, vertical crystal growth control, and supercontinuum generation niche dominance.
| Leading Market Players |
|---|
| IPG Photonics Corporation |
| Coherent Corp. |
| Lumentum Holdings Inc. |
| TRUMPF SE + Co. KG |
| MKS Instruments Inc. |
| NKT Photonics |
| Spark Lasers |
| Toptica Photonics |
| EKSPLA |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for ytterbium-doped gain fiber lock in supply access and price visibility for laser system manufacturers serving China's Yangtze River Delta electronics cluster. These arrangements insulate against Chinese export quota volatility on rare-earth oxides while committing buyers to minimum volume thresholds.
Pricing Analysis
Price spreads between German precision-tooling suppliers and East Asian electronics manufacturers exceed three-to-one for equivalent picosecond systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and after-sales service bundling. Cost compression in standard-tier industrial units is intensifying because Japanese automotive suppliers are disintermediating traditional integrator channels. Contract manufacturers in India's emerging semiconductor sector exhibit the highest price sensitivity, while FDA-cleared ophthalmic platforms in Germany and Japan command the lowest.
Supply Chain Analysis
China and Germany anchor rare-earth fiber preform manufacturing and beam delivery optics production respectively. Ytterbium-doped gain fibers, erbium-doped amplifiers, and saturable absorber crystals draw from concentrated upstream sources. Single-source vulnerability runs through Baden-Württemberg's scanning galvanometer clusters. Distribution runs through medical device OEMs for femtosecond platforms and industrial automation integrators for picosecond systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where all-fiber nonlinear polarization evolution architectures are collapsing the separation between laboratory-grade and clinical-deployable laser sources. Interoperability between palm-scale seed oscillators and OEM-integrated medical devices is redrawing competitive boundaries.
For Market Incumbents: Secure captive preform manufacturing capabilities to mitigate rare-earth fiber cost volatility from Chinese export quotas. Deepen backward integration into diode fabrication and crystal growth to defend against emerging solid-state specialists. Prioritize ISO 13485 certification investment to capture margin premiums in clinically validated segments versus commodity material-processing contracts. For New Entrants and Emerging Players: Anchor in India's PLI-scheme semiconductor packaging corridor where domestic fab capacity buildouts will scale laser system procurement. Target neurostimulation device micromachining as a commercially underdeveloped application for femtosecond cold ablation. Pursue direct module supply relationships with Japanese automotive Tier-1s disintermediating traditional integrator channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated diode-to-system suppliers with regulatory certification portfolios. Long-term viability over the next decade hinges on controlling upstream rare-earth fiber preform manufacturing and downstream medical device OEM channels. Watch FDA 510(k) clearance velocity for femtosecond ophthalmic platforms as the inflection signal indicating clinical adoption timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Fiber Preforms | Mitigates Chinese export quota exposure for ytterbium-doped gain fiber supply. |
| ISO 13485 Quality Management Certification | Unlocks margin premiums in FDA and EU MDR surgical laser segments. |
| All-Fiber Nonlinear Polarization Evolution Miniaturization | Enables palm-scale seed oscillators for portable dermatological platforms. |
| Direct Module Supply to Automotive Tier-1s | Bypasses traditional integrator channels in Toyota and Honda supply chains. |
| Multi-Jurisdiction Regulatory Certification Parallelism | Accelerates FDA, EU MDR, NMPA, and PMDA clearance timelines for global deployment. |
Research Methodology
A standing panel of laser system procurement managers at precision electronics manufacturers, biomedical engineers at ophthalmic device OEMs, and aftermarket service heads at industrial automation integrators provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, NMPA registration databases, EU MDR notified body audit records, and SEC 10-K disclosures from listed photonics suppliers. Bottom-up shipment data from fiber laser module manufacturers triangulated against top-down demand estimates from end-use sector analysts.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled pulse architecture, application sector, end-user type, and technology platform as segmentation dimensions. CAGRs derived from fitted growth curves incorporating rare-earth fiber price indices, regulatory clearance velocity metrics, and electronics manufacturing capital expenditure patterns.
Underlying assumptions cover stable Chinese rare-earth export policy, continued EU MDR harmonization, and FDA 510(k) pathway efficiency, with deviation risk concentrated in geopolitical supply disruptions and multi-jurisdiction certification delays. Recalibration cycles align with material shifts in NMPA registration timelines and PLI scheme-induced capacity buildouts in India's semiconductor sector.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Portable Lenses Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
100G Optical Transceivers Market
Optical Components
Optical Amplifier Market
Optical Components
Optical Position Sensors Market
Optical Components
Spectroradiometers Market
Optical Components
Global Tunable Filter Market
Optical Components
Optical Cross Connect Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Optical Dome Market
Optical Components
Digital Cinema Lens Market