
 Global Fiber Optic Gyroscope Market | 2026-2036
Global Fiber Optic Gyroscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Optic Gyroscope Market Intelligence
The direct sales channel to large aerospace and defense contractors is tilting toward partnerships with systems integrators, altering traditional supply lines. Safran S.A. leverages its extensive aerospace portfolio to secure large-scale contracts for navigation systems. Honeywell International Inc. competes on the basis of reliability and its established presence in commercial aviation platforms. Northrop Grumman Corporation dominates the high-performance segment, particularly for strategic defense applications in the United States.
A fiber optic gyroscope is an inertial sensor that measures angular velocity by detecting phase shifts of light, a phenomenon known as the Sagnac effect, within a closed loop of optical fiber. These devices are characterized by their bias stability and low angular random walk, making them essential for high-precision applications. Navigation Systems for Defense Forces remain the largest application segment by value. The Robotics and Autonomous Vehicle Developers end-user segments are expanding rapidly, driven by the need for reliable, solid-state inertial measurement.
Product qualification is governed by stringent standards from bodies like the U.S. Federal Aviation Administration (FAA) for civil aviation and military specifications (MIL-SPEC) for defense. These regulations mandate extensive testing for reliability and performance, creating high barriers to entry for new component suppliers. Component manufacturers now face a strategic choice between scaling production for high-volume commercial applications and focusing R&D on ultra-high-performance defense and space-grade systems.
Market Dynamics
The fundamental dynamic shaping the fiber optic gyroscope market is the strategic divergence between high-volume, cost-sensitive commercial applications and low-volume, ultra-high-performance defense and space programs. This split is forcing component manufacturers to make difficult choices on R&D and production scaling.
Growth Catalysts
- Autonomous Systems Expansion:Demand from developers of autonomous vehicles, drones, and robotics for precise, GPS-denied navigation capabilities provides a significant commercial pull, especially in North America and Europe.
- Integrated Photonics:The maturation of photonic integrated circuit (PIC) technology enables the production of smaller, lighter, and more cost-effective FOGs, opening new applications where size and weight are critical constraints.
- Defense Modernization:National defense programs in the United States, South Korea, and France prioritize upgrading legacy navigation systems on aircraft, missiles, and naval vessels with solid-state inertial technology for improved reliability.
Market Restraints
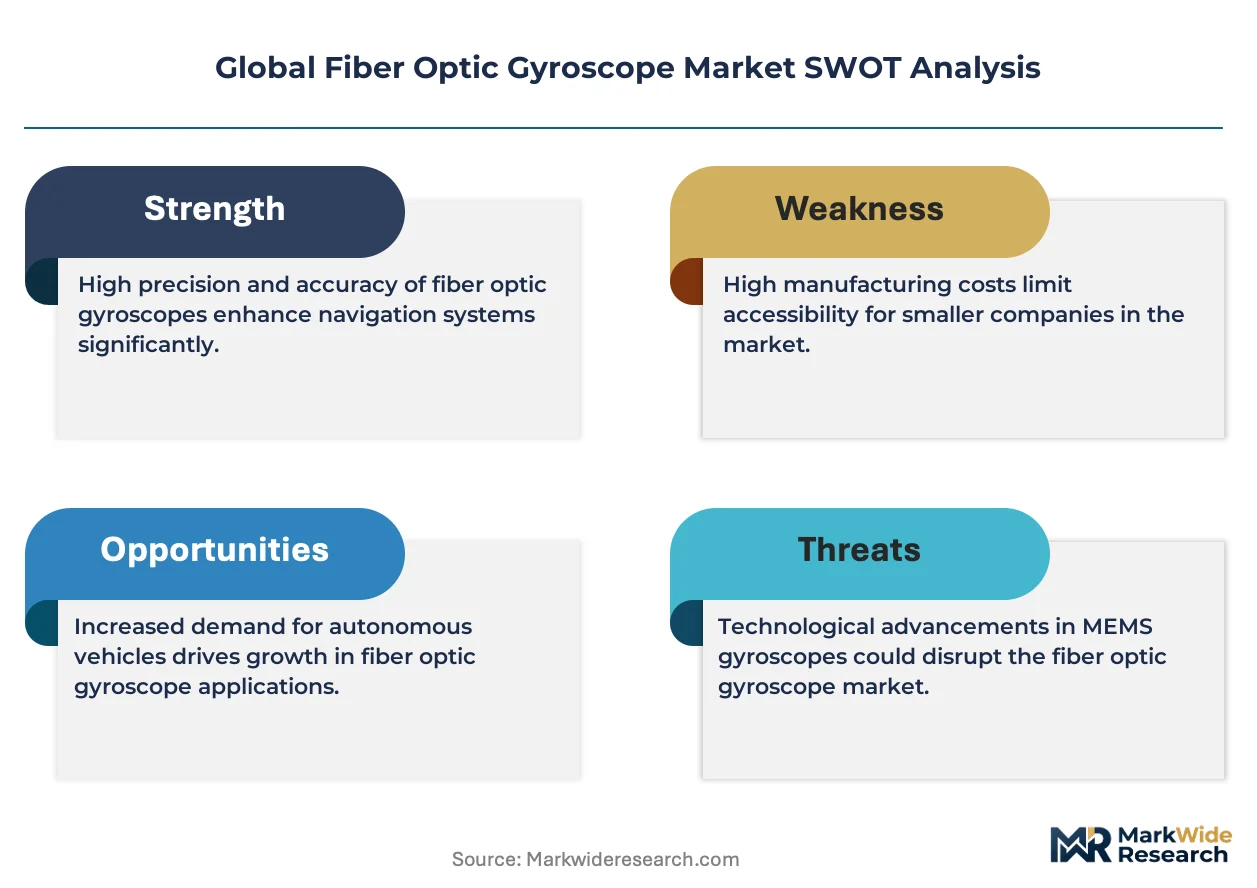
- High Component Cost:The specialized polarization-maintaining optical fiber and high-coherence laser diodes required for high-performance FOGs remain expensive, limiting adoption in cost-sensitive commercial markets outside of niche applications.
- Technical Sensitivity:Performance, particularly bias stability, is highly sensitive to temperature fluctuations and mechanical stress, necessitating complex and costly compensation electronics and packaging which increases system complexity.
- Stringent Qualification Standards:The extensive testing and documentation required to meet U.S. military specifications (MIL-SPEC) or FAA certification create high barriers to entry and lengthen product development cycles significantly.
Strategic Opportunities
- Industrial Automation:The need for precise positioning in automated guided vehicles (AGVs) and robotic arms within large-scale logistics and manufacturing facilities represents a major, underpenetrated industrial application.
- New Space Economy:A growing number of private space ventures in countries like Japan and India require reliable, radiation-tolerant inertial sensors for satellite attitude control and launch vehicle guidance, creating a new customer segment.
- Hybrid Sensor Fusion:Combining FOGs with lower-cost MEMS accelerometers and gyroscopes in a single inertial measurement unit (IMU) offers a path to provide cost-effective, high-performance navigation solutions for a broader market.
Industry Challenges
- Specialized Talent Scarcity:A limited pool of engineers and technicians with expertise in photonics, optical engineering, and high-reliability assembly constrains the ability of manufacturers to scale production and R&D efforts.
- Supply Chain Bottlenecks:Securing a consistent and qualified supply of critical components, such as high-purity optical fiber and specialized laser sources, presents a significant operational hurdle for new and existing manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Optic Gyroscope Market |
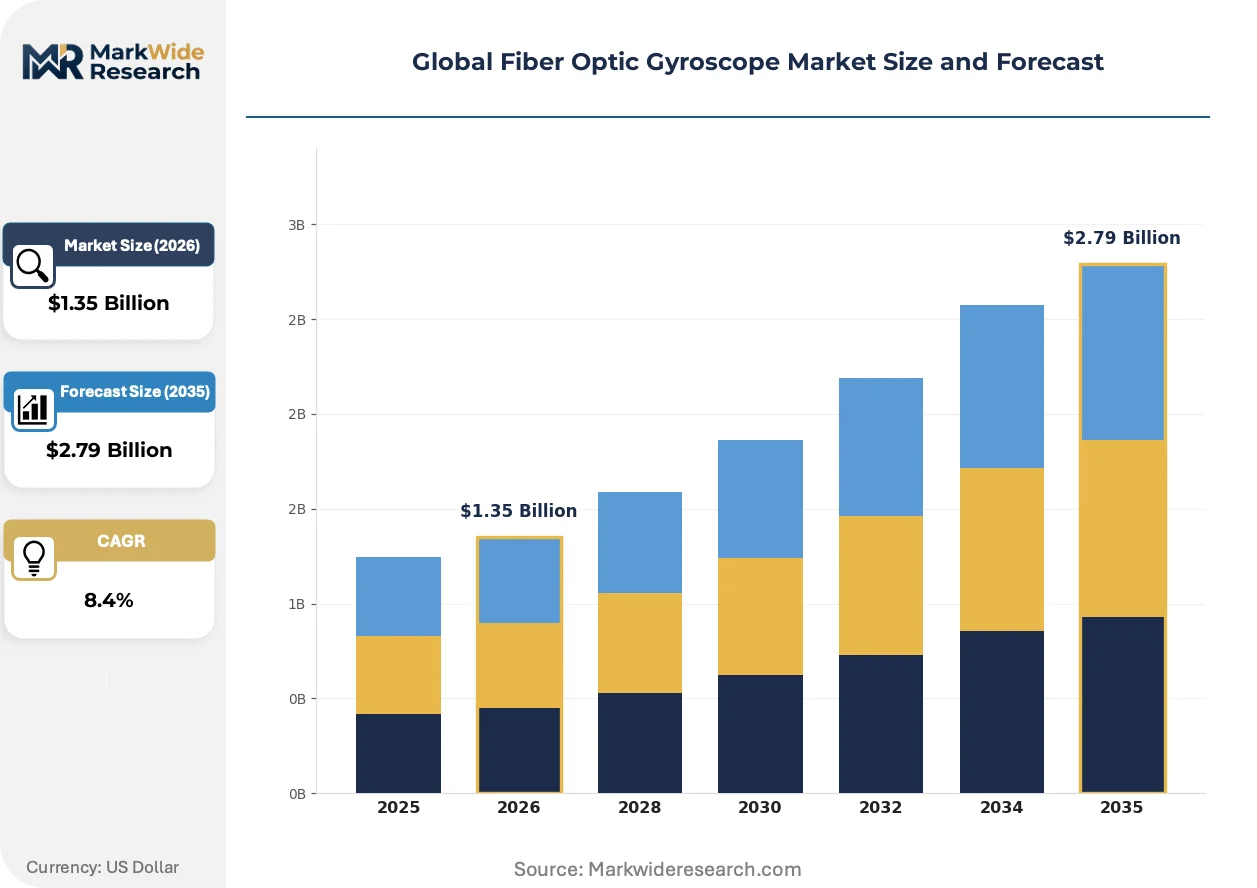
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FOG, RLG, IFOG, HRG, Interferometric Gyroscope Technology: Coherent Light, Polarization Maintaining Fiber, Integrated Photonics, Planar Lightwave Circuit, Digital Signal Processing Application: Navigation Systems, Guidance Control, Attitude & Heading Reference, Stabilization Platforms, Robotics End User: Defense Forces, Aerospace Manufacturing, Marine Navigation, Surveying Equipment Makers, Autonomous Vehicle Developers |
| Companies Covered | KVH Industries, Inc., Safran S.A, Honeywell International Inc., FIBERPRO Inc., Northrop Grumman LITEF GmbH, Northrop Grumman Corporation, iXBlue SAS, Advanced Navigation, EMCORE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Optic Gyroscope Market Strategic Shifts & Innovations
The market's evolution is defined by a persistent drive toward miniaturization and integration, which is unlocking applications far beyond the technology's original aerospace and defense stronghold. This shift is enabled by advancements in both materials and manufacturing processes.
Photonic Integrated Circuits (PICs) are a key enabling technology, consolidating multiple optical functions onto a single chip. Autonomous vehicle and advanced drone developers are rapidly adopting PIC-based FOGs for their navigation systems. This technology is digitizing the sensor's core architecture, moving from discrete fiber-wound components to a compact, solid-state solution that radically lowers unit cost and power consumption.
Evolving certification standards from bodies like the U.S. Federal Aviation Administration for new aircraft categories, including Urban Air Mobility (UAM) platforms, are a major influence. These regulations mandate high-reliability, low-SWaP (Size, Weight, and Power) navigation systems, effectively disqualifying older mechanical gyroscopes. The commercial aviation segment is responding by specifying solid-state FOG or ring laser gyro systems for all new platform designs.
Customers in sophisticated end-markets are increasingly shifting from purchasing individual components to acquiring pre-integrated and certified inertial measurement units (IMUs). This trend disrupts the role of traditional component distributors, favoring systems integrators who can provide a complete, qualified navigation solution with supporting software. This demand-side shift is most visible within the defense and commercial aerospace sectors in North America.
Global Fiber Optic Gyroscope Market Segmentation
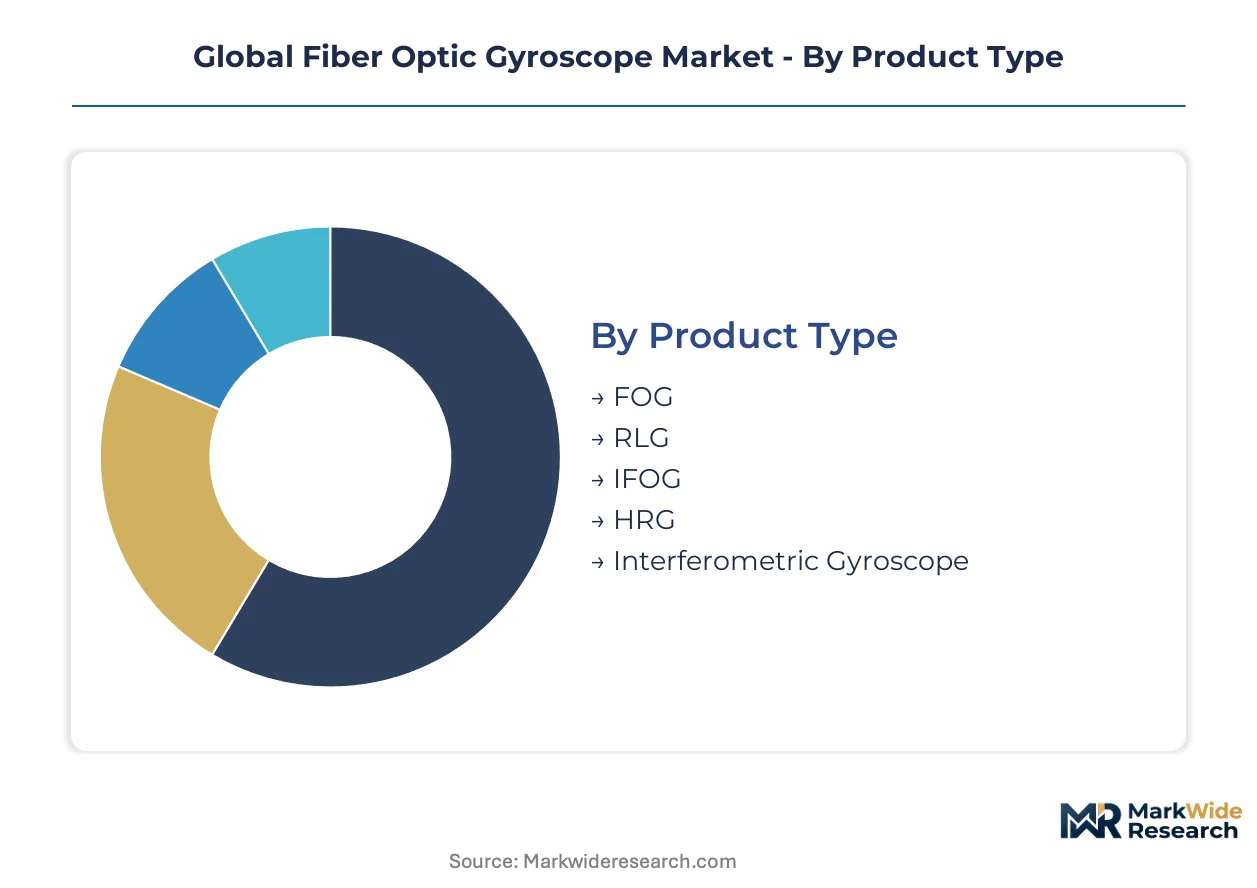
The segmentation analysis for the global fiber optic gyroscope market illuminates the diverse landscape of product offerings, underlying technologies, primary applications, and distinct end-user requirements. Understanding these segments helps manufacturers tailor product development and market strategies to specific demand pockets and performance criteria.
Product Type:
The product type segmentation highlights the maturity spectrum from established inertial sensors to advanced solid-state solutions that define the market. Each variant offers specific performance characteristics catering to different operational demands.
- FOG:Fiber Optic Gyroscopes measure angular velocity using the Sagnac effect in a coiled optical fiber. Demand for FOGs is concentrating in autonomous vehicles and robotics due to their solid-state reliability and improved cost-effectiveness.
- IFOG:Interferometric Fiber Optic Gyroscopes utilize interferometry to detect phase shifts in light within the fiber coil, offering enhanced precision and bias stability. This product type sees significant demand from strategic defense applications requiring ultra-high performance navigation.
- RLG:Ring Laser Gyroscopes operate on similar principles but use laser beams in a closed optical path within a cavity. RLG systems are primarily used in high-end commercial aviation and precision military platforms.
- HRG:Hemispherical Resonator Gyroscopes are solid-state devices measuring angular rate through the vibration of a resonant hemisphere. HRGs find niche applications in space-grade systems and high-shock environments.
- Interferometric Gyroscope:This broad category includes devices that measure angular velocity by detecting interference patterns of light. Interferometric gyroscopes are foundational to various high-accuracy inertial sensing technologies.
FOG handles the majority of throughput; IFOG is the fastest mover on share.
Technology:
Technology differentiation often correlates with the cost tier, where specialized components enable superior performance at a higher price point. The underlying technological advancements dictate the size, weight, power, and cost profile of fiber optic gyroscopes.
- Integrated Photonics:This technology consolidates multiple optical functions onto a single chip, enabling smaller, lighter, and more cost-effective FOG units. Autonomous vehicle developers are rapidly adopting PIC-based FOGs for navigation systems.
- Polarization Maintaining Fiber:This specialized optical fiber preserves the polarization state of light, critical for maintaining signal integrity and high bias stability in FOGs. High-performance defense applications depend heavily on these advanced fibers.
- Coherent Light:The use of coherent light sources, typically laser diodes, is fundamental to the operation of fiber optic gyroscopes. Coherent light ensures the precise phase shift detection necessary for accurate angular velocity measurement.
- Planar Lightwave Circuit:Planar lightwave circuits are integrated optical devices fabricated on a chip, offering a compact alternative to bulk optical components. These circuits contribute to the miniaturization of FOG systems.
- Digital Signal Processing:Digital signal processing techniques are essential for extracting precise angular rate information from raw optical signals and compensating for environmental effects. DSP enhances the overall accuracy and stability of FOGs.
Integrated Photonics is rapidly gaining traction due to its cost-effectiveness, while Polarization Maintaining Fiber remains critical for high-performance systems.
Application:
Application segmentation reveals where demand volume concentrates, from traditional high-value defense uses to emerging commercial sectors. Each application requires specific performance characteristics from the gyroscope system.
- Navigation Systems:Fiber optic gyroscopes provide precise orientation and position data for aircraft, ships, and ground vehicles, especially in GPS-denied environments. Defense forces remain the largest end-user segment for these high-accuracy systems.
- Robotics:Robotics applications utilize FOGs for accurate orientation, path planning, and stabilization in autonomous robots and industrial manipulators. Developers of advanced robotics systems prioritize reliable, solid-state inertial measurement.
- Guidance Control:FOGs are integral to the guidance systems of missiles, torpedoes, and unmanned aerial vehicles, ensuring accurate trajectory and target acquisition. National defense programs consistently upgrade guidance systems with solid-state inertial technology.
- Attitude & Heading Reference:These systems provide continuous real-time orientation (pitch, roll, yaw) and heading information for various platforms. Commercial aviation platforms specify FOGs for their reliability in attitude and heading reference units.
- Stabilization Platforms:FOGs are used to stabilize cameras, antennas, and sensor platforms on moving vehicles, ensuring steady operation despite motion. Marine navigation systems widely deploy FOGs for platform stabilization.
Navigation Systems command the largest market share; Robotics applications demonstrate the steepest expansion trajectory.
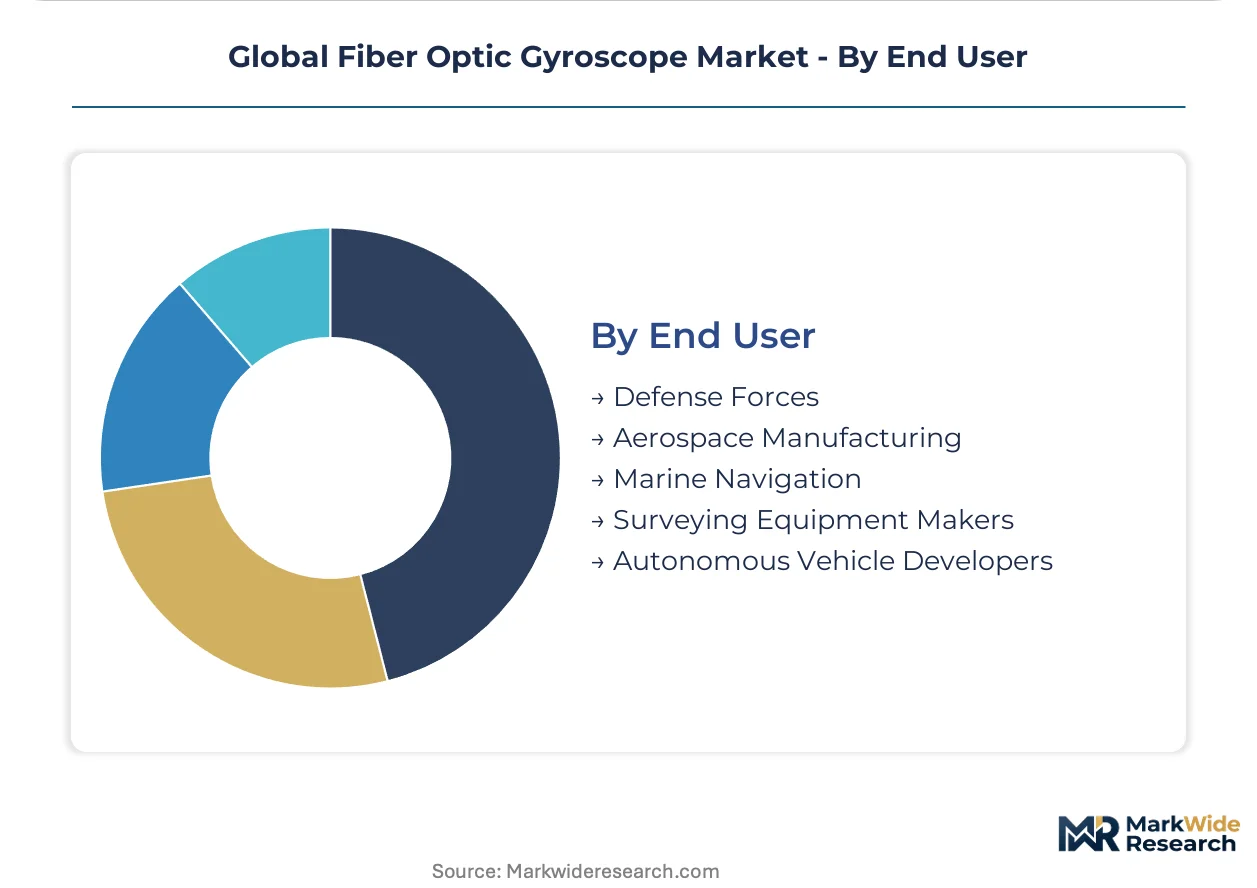
End User:
The end-user segmentation distinguishes customer types based on their primary purchasing criteria, ranging from extreme reliability to cost-efficiency. Each end-user group presents unique market dynamics and regulatory considerations.
- Defense Forces:Military organizations require FOGs for high-precision navigation, guidance, and control in aircraft, naval vessels, and strategic weapons systems. Stringent MIL-SPEC standards govern product qualification for defense applications.
- Autonomous Vehicle Developers:This segment includes companies developing self-driving cars, drones, and unmanned ground vehicles that rely on FOGs for precise, GPS-independent navigation. The need for reliable, solid-state inertial measurement drives demand from these developers.
- Aerospace Manufacturing:Manufacturers of commercial and civil aircraft integrate FOGs into navigation and attitude reference systems. The FAA's stringent certification standards influence FOG selection in civil aviation.
- Marine Navigation:Commercial and military marine vessels use FOGs for accurate heading, roll, and pitch measurements, crucial for safe navigation and offshore operations. Marine navigation systems demand robust and reliable inertial sensors.
- Surveying Equipment Makers:Companies producing high-precision surveying and mapping equipment incorporate FOGs for accurate orientation and positioning in challenging terrains. These makers seek FOGs for their bias stability and low angular random walk.
Defense Forces represent the dominant end-user segment; Autonomous Vehicle Developers are driving significant new demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National defense modernization programs across several key economies prioritize upgrading legacy navigation systems with solid-state inertial technology. This strategic focus on improved reliability and performance drives significant investment in fiber optic gyroscopes. Regulatory bodies also influence market dynamics by mandating stringent qualification standards for high-precision navigation solutions.
United States
Demand for fiber optic gyroscopes stems from extensive defense and aerospace programs requiring precise navigation. U.S. Federal Aviation Administration (FAA) and military specifications (MIL-SPEC) mandate rigorous testing for reliability. Silicon Valley and aerospace hubs like Seattle are centers for FOG R&D and integration.
France
Defense modernization initiatives and a strong aerospace industry drive demand for high-performance FOGs. France's national defense programs and EU regulations shape product development. Toulouse, a major aerospace hub, concentrates R&D and manufacturing for advanced inertial sensors.
South Korea
Upgrading legacy navigation systems on aircraft and naval vessels, plus autonomous vehicle development, fuels FOG market expansion. The Ministry of National Defense prioritizes solid-state inertial technology. Seoul and Daejeon host research institutions and companies focused on advanced sensor technologies.
Japan
The burgeoning new space economy and industrial automation sectors are increasing demand for reliable, radiation-tolerant inertial sensors. Japan's METI supports advanced manufacturing and space technology initiatives. Tokyo and Nagoya are key industrial centers for private space ventures and robotics.
India
Growing private space ventures and defense sector upgrades require high-precision navigation and guidance systems. ISRO and the Ministry of Defence drive demand for advanced inertial measurement units. Bengaluru, India's "Silicon Valley," is a hub for aerospace, defense, and space technology.
Global Fiber Optic Gyroscope Market Key Industry Players
On the supply side, the industry is bifurcated, with established players dominating high-performance defense and aerospace segments while new entrants target commercial applications. This dynamic creates distinct strategic archetypes: integrated systems providers, specialized component manufacturers, and emerging photonic integrated circuit developers. Dominant competitive moves include strategic partnerships with systems integrators, focused R&D on miniaturization and cost reduction, and geographic expansion into new commercial markets.
Within the integrated systems provider archetype, Safran S.A. leverages its extensive aerospace portfolio to secure large-scale navigation system contracts, particularly in European defense and civil aviation. Northrop Grumman Corporation, a major U.S.-based defense contractor, exemplifies leadership in the ultra-high-performance segment for strategic defense applications. Honeywell International Inc. also occupies a strong position, competing on the basis of reliability and its established presence in commercial aviation platforms globally.
| Leading Market Players |
|---|
| KVH Industries, Inc. |
| Safran S.A |
| Honeywell International Inc. |
| FIBERPRO Inc. |
| Northrop Grumman LITEF GmbH |
| Northrop Grumman Corporation |
| iXBlue SAS |
| Advanced Navigation |
| EMCORE Corporation |
Cost & Logistics Intelligence
Specialized component scarcity in high-purity optical fiber and laser diodes significantly determines both the premium pricing tiers and the geographically concentrated supply chain shape for fiber optic gyroscopes. This scarcity impacts production costs and market accessibility.
Pricing Analysis
Certification level, particularly U.S. military specifications and FAA standards, creates the primary price differentiation across fiber optic gyroscope products. The dominant pricing model remains per-unit transactional, often integrated into project-based contracts for large systems. Performance metrics like bias stability and radiation tolerance also drive significant price premiums. Pricing softness in commercial-grade FOGs stems from the push for miniaturization and integrated photonics, making Autonomous Vehicle Developers highly price sensitive compared to Defense Forces.
Supply Chain Analysis
The upstream supply of specialized components, including high-purity optical fiber and high-coherence laser diodes, sources predominantly from advanced manufacturing hubs in the United States, Japan, and parts of Europe. Fiber optic gyroscope manufacturers rely on these highly technical inputs for performance. Single-source vulnerability for these critical components presents a significant structural risk across the industry. Distribution often runs through direct sales channels to large aerospace and defense contractors, increasingly involving partnerships with systems integrators for complete navigation solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the expanding demand from Autonomous Systems Expansion for precise, GPS-denied navigation. This shift creates distinct niches for specialized fiber optic gyroscope solutions across various performance and cost tiers.
For Market Incumbents: Harden existing relationships with defense and aerospace contractors by investing in R&D for ultra-high-performance, space-grade systems. Incumbents must also deepen vertical integration into specialized component manufacturing to mitigate supply chain bottlenecks. This defends against margin pressure from new entrants leveraging integrated photonics for commercial applications. Prioritize certification investment for new platforms, especially in civil aviation and defense modernization programs.
For New Entrants and Emerging Players: Establish a beachhead in the rapidly expanding Robotics and Autonomous Vehicle Developers segment, particularly in North America and Europe. Focus on developing cost-effective, PIC-based FOGs that meet commercial reliability standards. Leverage hybrid sensor fusion strategies, combining FOGs with MEMS, to offer high-performance solutions at a broader market price point. Industrial automation presents a major underpenetrated application for these new solid-state inertial measurement units.
For Investors and Strategic Acquirers: Specialized component manufacturers and photonic integrated circuit developers represent attractive acquisition targets over the next 5-10 years. These entities control critical upstream supply and enable miniaturization, essential for long-term market growth. Focus on firms with strong IP in polarization-maintaining fiber or high-coherence laser diodes. The rapid commercial adoption of PIC-based FOGs by autonomous vehicle developers serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Integrated Photonics | This initiative enables smaller, lighter, and more cost-effective FOGs for autonomous vehicle developers. |
| Partnerships with Systems Integrators | This secures large-scale navigation system contracts with aerospace and defense contractors. |
| Investment in High-Purity Optical Fiber Production | This ensures a consistent and qualified supply of critical components, mitigating supply chain bottlenecks. |
| Certification for Urban Air Mobility (UAM) | This opens new commercial aviation segments requiring high-reliability, low-SWaP navigation systems. |
| Hybrid Sensor Fusion Product Development | This offers cost-effective, high-performance navigation solutions for a broader commercial market. |
Research Approach
Initial hypotheses were tested against primary input from aerospace manufacturing executives, defense procurement officers, and photonics R&D scientists, then refined through iterative processes. This approach combined in-depth interviews with extensive secondary validation from FAA certification documents, MIL-SPEC standards, and academic research. A robust triangulation of bottom-up market sizing and top-down industry analysis ensured data accuracy.
Demand-supply balance formed the core analytical framework across the analysis window, integrating historical trends with future projections. Segmentation dimensions modeled included product type, underlying technology, key application areas, and end-user segments, alongside regional defense spending patterns. Compound Annual Growth Rates were derived from a multi-factor regression analysis. Key forecast inputs included defense budget allocations and autonomous vehicle development timelines.
Stress conditions across geopolitical stability, technological breakthroughs, and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning supply chain stability and the pace of integrated photonics adoption. Cross-checking against industry consortia reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Co-Packaged Optics Market
Optical Components
Laser Photomask Market
Optical Components
Optical Modulators Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Duplication Disc Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Optical Position Sensors Market
Optical Components
Diode Laser Module Market
Optical Components
Passive Optical Component Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market