
 Low-E Glass Magnetron Sputtering Coating Line Market | 2026-2036
Low-E Glass Magnetron Sputtering Coating Line Market Size, Share, and Industry Trends Forecast 2026-2036
Low-E Glass Magnetron Sputtering Coating Line Market Insights
Specialized vacuum engineering talent is bifurcating the competitive landscape, separating equipment makers with captive technical depth from assemblers dependent on outsourced know-how. Von Ardenne leverages its German engineering heritage to sustain premium positioning in high-complexity inline systems. Luoyang North Glass anchors domestic supply chains for China's architectural glass sector through localized service networks. Bühler Group differentiates via integrated process control software that extends equipment value beyond hardware installation.
Low-E glass magnetron sputtering coating lines deposit nanometer-scale metal and metal-oxide layers onto float glass in controlled vacuum environments, typically achieving emissivity below 0.15 to suppress radiative heat transfer. The process requires precise gas flow management, cathode power stability, and substrate temperature control to ensure optical clarity alongside thermal performance. Inline systems dominate capital deployment among large-scale float glass producers seeking continuous throughput, while batch systems retain relevance for specialty automotive glazing runs with frequent changeovers. DC magnetron technology leads installed capacity due to mature power supply economics, though pulsed magnetron configurations are gaining traction where coating uniformity demands exceed conventional arc-suppression limits.
China's MIIT enforces GB standards for building energy efficiency that directly mandate low-E glass in commercial envelopes above specified floor areas. The EU Green Deal and F-Gas Regulation jointly pressure glazing suppliers toward higher-performance coatings that reduce HVAC loads and limit fluorinated gas leakage from insulated glass units. EPA and DOE efficiency programs in the United States create parallel demand pull through ENERGY STAR certification requirements for fenestration products. Stakeholders must monitor how evolving carbon border adjustment mechanisms reshape equipment sourcing decisions across integrated glass manufacturers.
Market Dynamics
Equipment makers face intensifying pressure from China's dual carbon goals and the EU Green Deal, which mandate rapid upgrades to energy-efficient glazing capacity while compressing payback timelines for capital-intensive sputtering installations.
Growth Catalysts
- MIIT GB Standards:China's building energy efficiency mandates require low-E glass in commercial envelopes above specified floor areas, forcing glass processors to expand coating capacity.
- Yangtze River Delta Cluster:Concentrated float glass output in this manufacturing hub generates localized demand pull for inline sputtering systems with continuous throughput.
- Pulsed Magnetron Technology:Advanced power supply configurations address arc-suppression limits in high-uniformity coatings, opening specification windows for automotive glazing applications.
Market Restraints
- Specialized Vacuum Engineering Talent:Scarce technical depth in cathode design and gas flow management concentrates capability among a handful of equipment makers with captive expertise.
- High-Purity Target Materials:Silver and indium-tin-oxide supply volatility directly impacts coating line operating economics and margin stability.
- F-Gas Regulation Compliance:EU restrictions on fluorinated gases in insulated glass units add certification overhead that extends project timelines for glazing suppliers.
Strategic Opportunities
- India Green Building Codes:Emerging commercial construction standards create first-mover positioning for equipment vendors establishing local service infrastructure.
- Automotive Smart Glazing:Electrochromic and heated windshield applications demand batch sputtering systems with rapid changeover capability.
- Integrated Process Control Software:Value-added digital layers extend equipment monetization beyond hardware installation through predictive maintenance and yield optimization.
Industry Challenges
- Cathode Power Stability Expertise:Operational excellence in DC and pulsed magnetron configurations requires specialized technicians that equipment buyers struggle to recruit and retain.
- Substrate Temperature Calibration:Precision thermal management across large glass formats demands extensive commissioning periods that delay production ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-E Glass Magnetron Sputtering Coating Line Market |
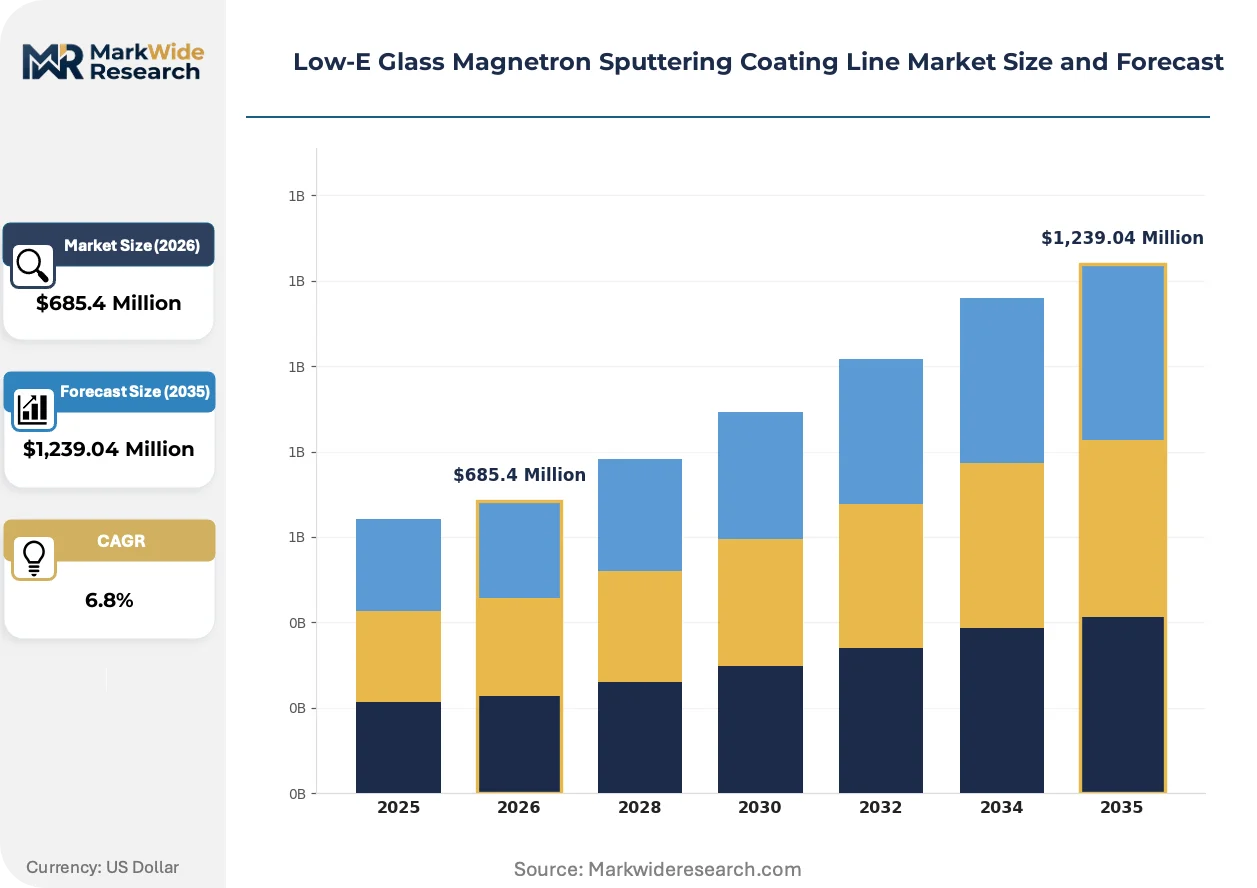
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Systems, Batch Systems, Vacuum Systems, Hybrid Systems End User: Residential Buildings, Commercial Buildings, Automotive Industry, Solar Panels Technology: DC Magnetron, RF Magnetron, Pulsed Magnetron, Hybrid Technology Application: Energy-Efficient Windows, Solar Thermal, Automotive Glazing, Architectural Glazing |
| Companies Covered | Bühler Group, Von Ardenne, Luoyang North Glass, Hongda Vacuum, Guangdong Huicheng Vacuum, Sichuan Goldstone, Shanghai Zichuang Coating, Zhaoqing Dexin Vacuum, Guangdong Xianzheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-E Glass Magnetron Sputtering Coating Line Market Trends and Innovations
Coating line architecture is fragmenting as end-users diverge on throughput priorities versus flexibility requirements, with technology choices hardening into distinct competitive postures rather than converging on a single optimal configuration.
Pulsed magnetron sputtering is bifurcating the installed base between high-volume architectural producers and specialty automotive runs. Large-scale float glass manufacturers favor continuous inline systems with DC power economics, while premium glazing suppliers adopt pulsed configurations for coating uniformity that exceeds conventional arc-suppression limits. This technical split is compressing the addressable market for mid-tier equipment makers lacking depth in either configuration.
The EU F-Gas Regulation and Green Deal jointly pressure glazing suppliers toward higher-performance thermal barriers that reduce HVAC loads. Equipment specifications now prioritize emissivity below 0.15 alongside optical clarity metrics that earlier generations struggled to balance. German and Dutch glass processors are responding fastest, embedding coating capacity upgrades into facility expansion timelines.
Glass processors are unbundling after-sales service contracts from initial equipment purchases, treating spare parts logistics and cathode refurbishment as separate procurement categories. This purchasing pattern shift disrupts traditional bundled pricing models and favors vendors with regional parts depots. The Yangtze River Delta and Rhine-Ruhr corridor exhibit the most advanced service unbundling, with buyers negotiating power supply and vacuum pump maintenance through independent channels.
Low-E Glass Magnetron Sputtering Coating Line Market Segmentation
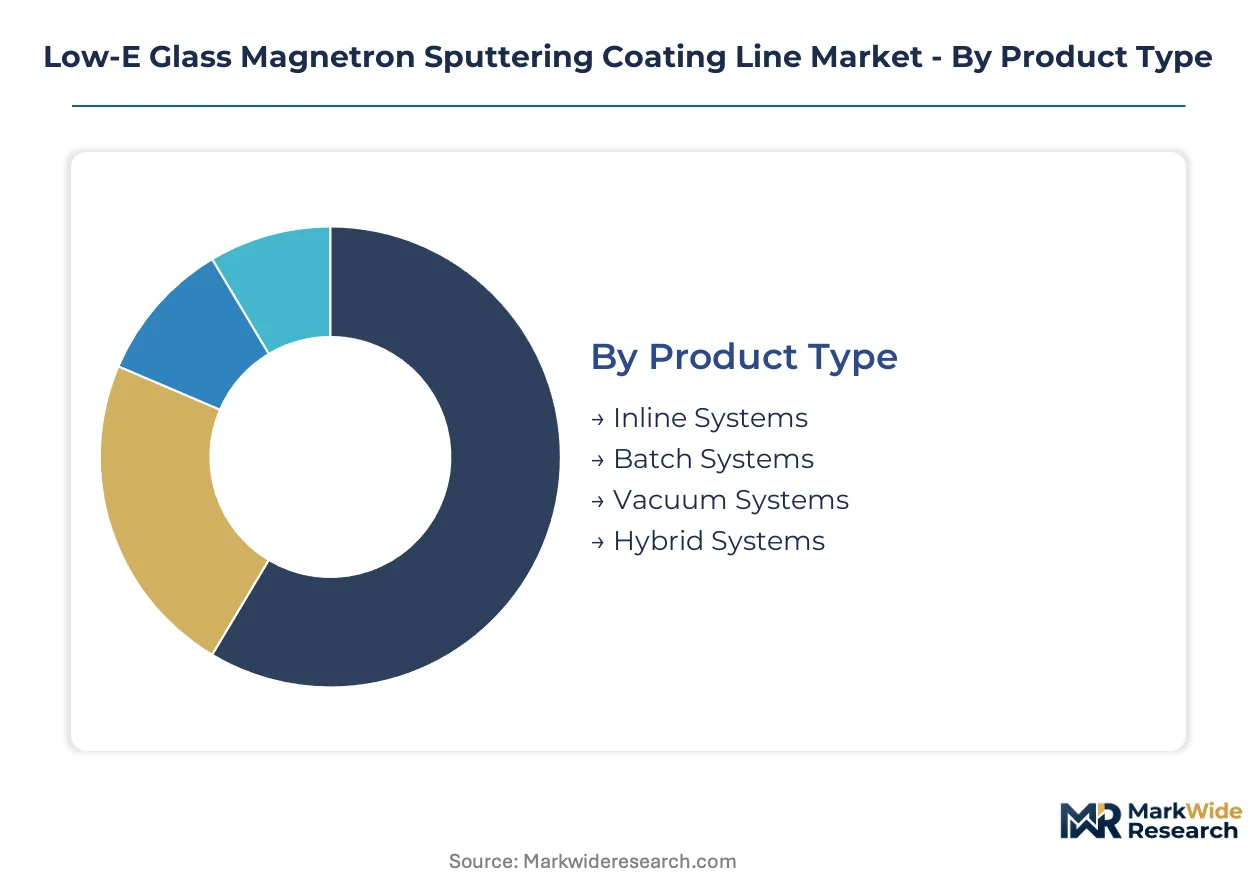
Equipment configuration choices in magnetron sputtering directly determine throughput economics, coating uniformity, and operational flexibility. Segmentation reveals where capital deployment concentrates among float glass producers versus specialty glazing suppliers, and which technology platforms face displacement pressure from emerging power supply architectures.
Product Type:
Substitute pressure from alternative deposition methods—chemical vapor deposition, spray pyrolysis, and sol-gel coating—varies sharply across system architectures, with continuous inline formats most shielded by scale economics and batch formats most exposed to flexible manufacturing competition.
- Inline Systems:Continuous throughput configurations process float glass ribbons up to 6 meters width without interruption, integrating multiple cathode stations for multi-layer stack deposition. Demand concentrates among China's Yangtze River Delta float glass cluster, where Xinyi Glass and CSG Holding prioritize capacity utilization rates above 85% to amortize capital-intensive installations. MIIT GB standards enforcement accelerates replacement cycles for aging architectural coating lines.
- Batch Systems:Chamber-based configurations accommodate frequent substrate changeovers for automotive windshield runs with varying curvature specifications. German and Czech automotive glazing specialists favor pulsed power integration here to suppress arcing during silver-based low-E stack deposition. Substrate temperature calibration complexity extends commissioning timelines versus inline alternatives.
- Vacuum Systems:Pump-down architecture and chamber sealing technology determine base pressure achievement speed, directly impacting cycle economics. Dry screw pumps are displacing oil-sealed roughing stages in European installations due to F-Gas Regulation maintenance restrictions.
- Hybrid Systems:Modular designs combine inline substrate transport with batch-style cathode accessibility for target material swaps. Japanese architectural glass processors deploy these for seasonal product mix shifts between solar control and thermal insulation coatings.
Inline systems retain volume leadership; hybrid systems hold the steepest expansion curve as mid-scale processors seek flexibility without full batch economics sacrifice.
End User:
Cost tier stratification separates price-sensitive residential fenestration from performance-driven commercial envelopes, with automotive and solar applications occupying distinct margin bands above and below architectural glazing.
- Commercial Buildings:LEED and BREEAM certification requirements drive specification of double and triple low-E glazing in curtain wall assemblies. China's tier-one cities enforce energy efficiency audits that disqualify conventional clear glass in new construction above 20,000 square meters. Procurement concentrates through facade contractors with long-term service agreements covering coating degradation monitoring.
- Automotive Industry:Heated windshields and electrochromic roof panels demand precise emissivity control across curved substrates. European OEMs source through Saint-Gobain Sekurit and AGC Automotive, which operate captive batch coating capacity with rapid changeover protocols for model-year transitions.
- Residential Buildings:Volume replacement window markets prioritize cost per square meter over coating performance differentiation. North American vinyl window manufacturers source standard low-E glass through regional float processors with limited sputtering sophistication.
- Solar Panels:Transparent conductive oxide deposition for photovoltaic front contacts requires indium-tin-oxide target purity above 99.99%. Module assemblers in India and Southeast Asia represent emerging equipment demand as domestic content rules tighten.
Commercial buildings command the dominant revenue share; solar panel manufacturing is gaining share fastest as photovoltaic capacity expansion accelerates coating line procurement for transparent electrode production.
Technology:
Application maturity splits the installed base between proven DC architectures and emerging pulsed configurations, with RF magnetron retaining niche relevance for dielectric target deposition where reactive sputtering dominates.
- DC Magnetron:Direct current power supplies dominate architectural glass installations due to mature arc suppression and target utilization economics above 30%. Chinese equipment makers source IGBT-based power modules from domestic semiconductor suppliers, reducing import dependency versus European line builders. Operating stability requires technician expertise in cathode dark space management and gas flow ratio optimization.
- Pulsed Magnetron:Mid-frequency bipolar pulse configurations enable reactive oxide deposition with reduced target poisoning and eliminated arcing in precision automotive runs. Von Ardenne and Bühler Group specify these for electrochromic glazing stacks where layer thickness uniformity must hold within 2% across 3-meter substrates.
- RF Magnetron:Radio frequency excitation sustains plasma in dielectric target sputtering for anti-reflective and protective topcoats. Frequency matching network complexity limits adoption to specialty optical coating operations with dedicated electrical engineering support.
- Hybrid Technology:Combined DC and pulsed power architectures enable multi-cathode sequences with alternating metallic and dielectric layer deposition. Architectural processors in the Netherlands and Germany deploy these for solar control coatings combining silver infrared reflectors with titanium nitride absorption tuning.
DC magnetron retains volume leadership; pulsed magnetron holds the steepest expansion curve as automotive glazing uniformity requirements harden.
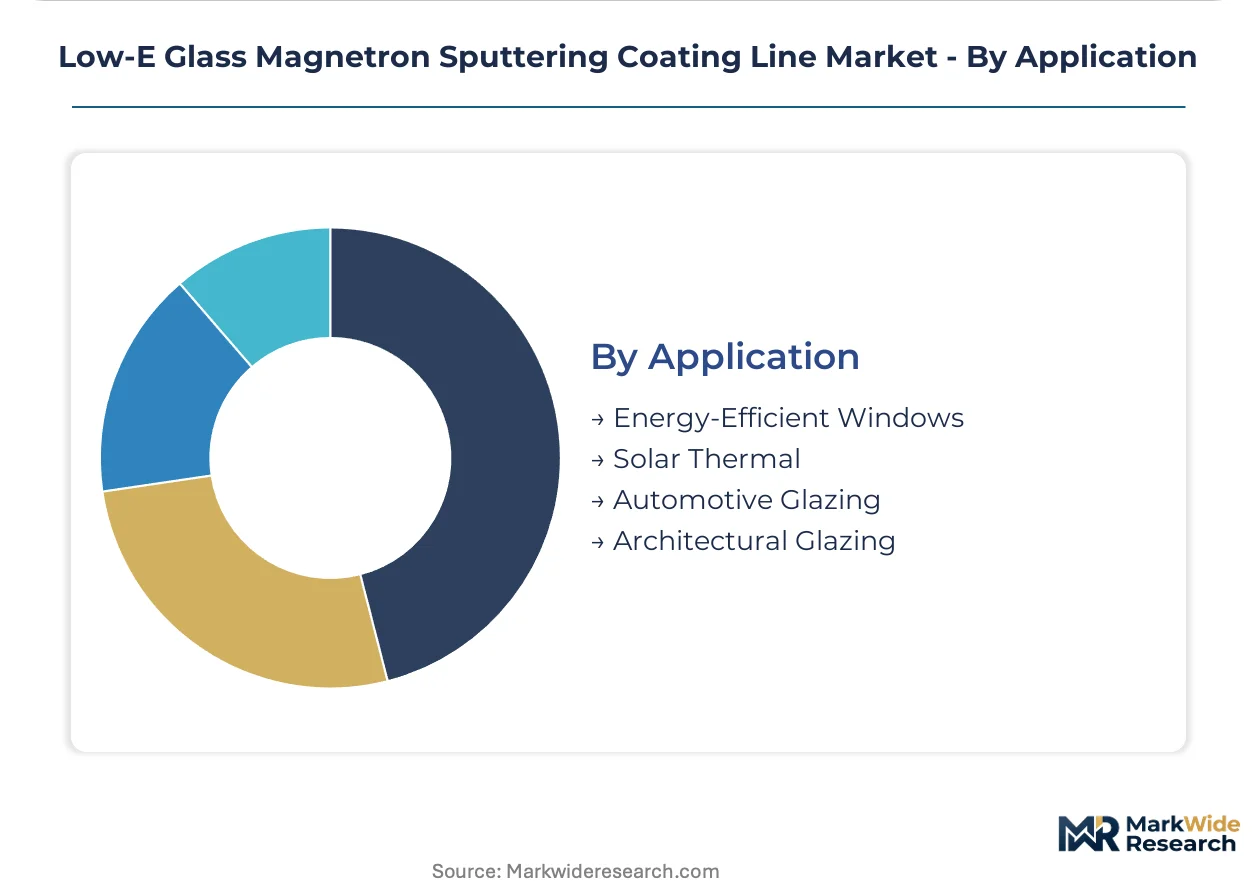
Application:
Geography concentration shapes procurement patterns, with energy-efficient window demand anchored in temperate climate zones where heating and cooling loads justify premium glazing investment, and solar thermal applications concentrated in high-insolation regions with active incentive structures.
- Energy-Efficient Windows:Insulated glass units with low-E coatings reduce U-values below 1.0 W/m²K in triple-pane configurations. EU Green Deal renovation wave targets 35 million building retrofits, embedding coating capacity expansion into flat glass processor capital plans. ENERGY STAR certification in the United States creates parallel specification pull through utility rebate programs.
- Architectural Glazing:Curtain wall and skylight applications prioritize optical clarity alongside thermal performance, with visible light transmission above 70% typically required for commercial daylighting standards. Specifiers balance solar heat gain coefficient against emissivity in climate-zone-specific product selections.
- Automotive Glazing:Windshield and side lite coatings must withstand thermal cycling from -40°C to 80°C without delamination or haze formation. Heated windshield applications deposit transparent conductive oxides with sheet resistance below 10 ohms per square for rapid defrosting.
- Solar Thermal:Selective absorber coatings for flat-plate and evacuated tube collectors require high solar absorptance above 0.95 paired with low thermal emittance below 0.10. Chinese collector manufacturers source equipment through domestic vendors with cost structures below European competitors.
Energy-efficient windows retain volume leadership; solar thermal holds the steepest expansion curve as renewable heating targets harden across European and East Asian climate policy frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. China's Yangtze River Delta processors prioritize continuous inline throughput for architectural glass, while European fabricators emphasize pulsed magnetron precision for automotive glazing. India's emerging green building codes drive first-mover procurement of batch systems with rapid changeover capability.
China
MIIT GB standards mandate low-E glass in commercial envelopes above specified floor areas, forcing glass processors to expand coating capacity. Dual carbon goals compress payback timelines for capital-intensive sputtering installations. The Yangtze River Delta manufacturing cluster concentrates float glass output, generating localized demand pull for inline systems with continuous throughput.
Germany
EU F-Gas Regulation and Green Deal jointly pressure glazing suppliers toward higher-performance thermal barriers. German processors embed coating capacity upgrades into facility expansion timelines. The Rhine-Ruhr corridor exhibits advanced service unbundling, with buyers negotiating power supply maintenance through independent channels.
United States
EPA and DOE efficiency programs create demand pull through ENERGY STAR certification requirements for fenestration products. ENERGY STAR-certified low-E glazing dominates commercial retrofit specifications. Regional float processors in the Southeast and Midwest source standard coating capacity through equipment leasing arrangements.
India
Emerging commercial construction standards under the Bureau of Energy Efficiency create first-mover positioning for equipment vendors. Green building codes tighten across tier-one cities, embedding low-E glazing into facade specifications. Domestic module assemblers represent emerging equipment demand as solar photovoltaic capacity expansion accelerates.
Japan
METI efficiency standards drive specification of high-performance glazing in commercial envelopes. Japanese architectural glass processors deploy hybrid systems for seasonal product mix shifts between solar control and thermal insulation coatings. Automotive glazing specialists favor batch configurations with rapid changeover protocols for model-year transitions.
Low-E Glass Magnetron Sputtering Coating Line Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage concentrating around captive vacuum engineering depth and regional service infrastructure. The market structure separates equipment makers with in-house cathode design capability from assemblers dependent on outsourced technical know-how. Three archetypes dominate: German-engineered premium system builders, Chinese domestic supply chain anchors, and integrated process control software vendors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as equipment buyers prioritize localized commissioning support and spare parts logistics.
Within the premium engineering tier, Von Ardenne exemplifies German heritage positioning in high-complexity inline systems. Luoyang North Glass Technology Co., Ltd. anchors domestic supply chains for China's architectural glass sector through localized service networks. Bühler Group occupies a position defined by integrated process control software that extends equipment value beyond hardware installation. These three companies represent distinct competitive postures rather than converging on a single optimal configuration.
| Leading Market Players |
|---|
| Bühler Group |
| Von Ardenne |
| Luoyang North Glass |
| Hongda Vacuum |
| Guangdong Huicheng Vacuum |
| Sichuan Goldstone |
| Shanghai Zichuang Coating |
| Zhaoqing Dexin Vacuum |
| Guangdong Xianzheng |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between float glass producers and coating line vendors lock in both cathode supply access and five-year price visibility, insulating capital-intensive installations from silver and indium-tin-oxide spot volatility while compressing margin flexibility for equipment makers serving China's Yangtze River Delta cluster.
Pricing Analysis
Project-based pricing dominates equipment procurement, with architectural glass processors in China and Germany negotiating turn-key installations that bundle commissioning, training, and two-year spare parts coverage. Price differentiation hinges on cathode power supply architecture—DC configurations command standard rates while pulsed magnetron systems extract 15-25% premiums for automotive uniformity specifications. Cost compression in mid-tier batch systems is intensifying because Chinese domestic vendors are undercutting European incumbents on vacuum chamber fabrication. Residential fenestration buyers exhibit highest price sensitivity, deferring coating upgrades until regulatory mandates force compliance, whereas automotive OEMs prioritize performance over unit economics.
Supply Chain Analysis
Inventory buffers for high-purity silver targets and ITO ceramics stretch 8-12 months due to mining concentration in Peru, Mexico, and China, creating working capital intensity that favors large processors with balance sheet capacity. Cathode assembly draws from German vacuum engineering expertise, Chinese machined components, and Japanese ceramic substrates, exposing the ecosystem to single-source vulnerability in bipolar pulse power supply modules. Distribution runs through direct vendor-field-service teams for inline architectural systems, while batch configurations for automotive glazing move through specialized integrators with captive commissioning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling is expanding faster than hardware revenue, with cathode refurbishment contracts and predictive maintenance software subscriptions creating recurring-revenue streams that outpace new equipment sales growth across European and East Asian markets.
For Market Incumbents: Compound regional service density by establishing captive cathode refurbishment facilities in the Yangtze River Delta and Rhine-Ruhr corridor, defending against Chinese domestic vendors eroding hardware margins through localized response-time advantages. Deepen backward integration into pulsed power supply design to differentiate from assemblers dependent on outsourced IGBT modules. For New Entrants and Emerging Players: Spare parts logistics gaps in India's emerging green building corridor represent immediate white-space opportunity, where Bureau of Energy Efficiency code enforcement is accelerating procurement ahead of established vendor service infrastructure deployment. Target batch system configurations with rapid changeover protocols for automotive glazing specialists in the Czech Republic and Mexico seeking alternatives to European lead times. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment makers with integrated process control software platforms that embed predictive maintenance and yield optimization modules. Long-term viability favors vendors with captive vacuum engineering depth rather than assembly-dependent business models. Monitor MIIT enforcement intensity in tier-two Chinese cities as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Infrastructure Expansion | Captive cathode refurbishment in the Yangtze River Delta compresses customer response times below 48 hours. |
| Backward Integration into Power Electronics | In-house IGBT-based pulsed supply design insulates margin from semiconductor import dependency. |
| Software-Layer Monetization | Predictive maintenance modules extend contract value beyond hardware installation through yield optimization. |
| Batch System Flexibility Engineering | Rapid changeover protocols open specification windows for automotive model-year transition cycles. |
| Green Certification Alignment | EU F-Gas Regulation compliance embedding positions vendors for Green Deal renovation wave procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with coating line operators, vacuum engineering specialists, and procurement directors at float glass processors; and secondary validation through MIIT GB standard filings, EU F-Gas Regulation implementation timelines, and customs trade records for silver and ITO target materials. Bottom-up equipment shipment tallies from Chinese and German manufacturing clusters were triangulated against top-down capital expenditure disclosures from publicly traded glass processors.
Across the projection horizon, the analytical framework modeled volume and value outputs by system configuration (inline, batch, hybrid, vacuum), end-use sector (commercial buildings, automotive, residential, solar), power supply technology (DC, pulsed, RF, hybrid), and application type (energy-efficient windows, architectural glazing, automotive glazing, solar thermal). CAGRs were derived from regression against regulatory mandate enforcement schedules and float glass capacity expansion pipelines, with specific weighting applied to MIIT dual carbon goal timelines and EU Green Deal renovation targets.
Forecasts assume regulatory continuity in Chinese MIIT enforcement, EU F-Gas Regulation stringency, and EPA ENERGY STAR program funding; material policy shifts in any regime would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Encoder Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Europe Optical Imaging Market
Optical Components
Europe Optical Film Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Objective Lens Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Polarizer Film Market