
 Quartz Glass Substrate Market | 2026-2036
Quartz Glass Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Glass Substrate Market Insights
Semiconductor end-use demand is shifting toward advanced lithography and etching processes that require ultra-high-purity quartz substrates. Heraeus Holding leverages its vertical integration from raw material refining to finished wafer carriers, sustaining quality consistency across semiconductor supply chains. Momentive Performance Materials Inc. anchors North American supply through specialized fused silica production for photomask blanks. Corning Inc. competes on scale, operating large-format melting furnaces that reduce unit costs for display-grade substrates.
Quartz glass substrate denotes a high-silica content panel manufactured through electric fusion or flame hydrolysis of silicon tetrachloride, achieving thermal expansion coefficients below 0.6 x 10⁻⁶/K for dimensional stability at temperatures exceeding 1000°C. These substrates serve as critical carriers in photolithography stages, reaction chambers, and optical windows where thermal shock resistance and UV transparency are mandatory. Fused silica dominates volume due to its established supply base for semiconductor wafer processing, while high purity quartz captures margin concentration in EUV lithography components where contamination thresholds sit below 10 parts per billion. Ultra high purity grades represent the fastest-expanding quality tier as foundries migrate to sub-3nm nodes.
REACH in Europe and RoHS directives enforce traceability of heavy metal content in quartz substrates destined for electronics applications, elevating testing costs for non-compliant suppliers. China's GB standards and MIIT guidelines on electronic-grade materials impose parallel certification requirements for import market access. Japan's METI promotes domestic quartz purification capabilities through JIS-standardized quality benchmarks that protect local semiconductor equipment manufacturers. Stakeholders must monitor evolving purity specifications tied to next-generation lithography nodes while calibrating regional certification investments against customer concentration in East Asian fabs.
Market Dynamics
Semiconductor foundries are migrating toward sub-3nm EUV lithography nodes, forcing quartz substrate suppliers to certify ultra-high-purity grades below 10 parts per billion contamination thresholds. This technical escalation is compressing qualification timelines while fragmenting the supplier base between integrated refiners and specialized fabricators.
Growth Catalysts
- EUV Lithography Node Migration:Foundries in Taiwan and South Korea are procuring synthetic fused silica for photomask blanks and wafer carriers. Each process shrink tightens thermal expansion coefficient tolerances.
- REACH Purity Mandates:European electronics manufacturers now require documented traceability of heavy metal content in substrate supply chains. This elevates demand for certified electric-fusion production methods.
- East Asian Manufacturing Clustering:Pyeongtaek and Taichung Science Parks concentrate capital equipment procurement. Local content requirements in these zones accelerate regional quartz purification capacity buildouts.
Market Restraints
- High-Purity Silica Feedstock Concentration:Ultra-low-alkali sand deposits suitable for semiconductor-grade refining concentrate in limited geographies. Single-source dependency creates supply vulnerability during extraction disruptions.
- Energy-Intensive Electric Fusion:Arc melting furnaces consume substantial electricity per kilogram of finished substrate. Volatility in industrial power tariffs directly compresses margin structures for non-integrated producers.
- Aluminosilicate Glass Substitution:Display panel manufacturers in selected applications are evaluating codoped glass alternatives with comparable thermal properties at reduced material cost.
Strategic Opportunities
- Domestic Purification in India:The country's PLI scheme for semiconductor manufacturing creates demand for localized quartz component supply. Early entrants can establish qualification relationships with greenfield fab projects.
- Photovoltaic Silicon Pulling Crucibles:Monocrystalline ingot growth for solar applications requires high-purity quartz crucibles with different purity profiles than semiconductor grades. This adjacent market offers volume absorption for mid-tier producers.
- Dual Carbon Goals in China:Beijing's emissions reduction mandates are accelerating electric furnace upgrades in legacy flame-hydrolysis facilities. Cleaner production credentials unlock preferential procurement from multinational equipment OEMs.
Industry Challenges
- EUV Contamination Control Expertise:Foundry customers now audit particle detection protocols down to 0.1-micron sensitivity. The talent pool for cleanroom manufacturing engineering remains shallow outside established Japanese and German supplier bases.
- Multi-Jurisdiction Certification Overlap:Simultaneous pursuit of REACH, RoHS, and China's GB standards creates redundant testing cycles. Documentation harmonization across regulatory frameworks lacks industry-wide coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Glass Substrate Market |
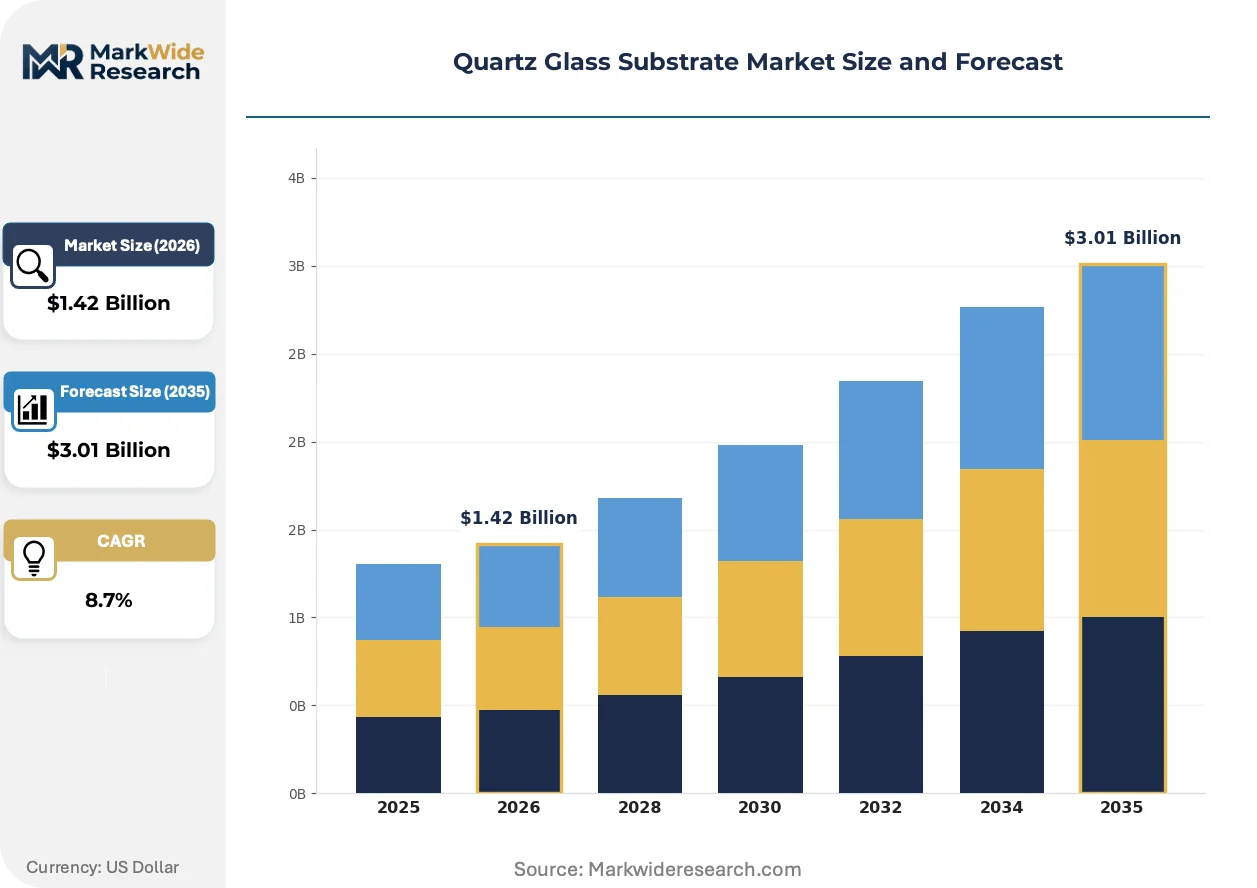
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Silica, Borosilicate Glass, High Purity Quartz, Recrystallized Quartz Application: Semiconductors, Optical Devices, Photovoltaics, Laboratory Equipment End User: Electronics Manufacturers, Research Institutions, Aerospace, Automotive Components Quality Grade: Standard Grade, High Grade, Ultra High Purity, Specialty Grade |
| Companies Covered | Heraeus Holding, Momentive Performance Materials Inc., Corning Inc., Shin-Etsu Chemical, Tosoh Quartz Co., Ltd., QSIL, MARUWA, Raesch Quarz GmbH, Saint-Gobain Quartz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Glass Substrate Market Trends and Innovations
Process automation and regulatory digitization are compressing traditional substrate qualification cycles while enabling real-time purity verification across distributed supply chains. These shifts favor capital-rich incumbents capable of integrating sensing technology with production infrastructure.
Laser-induced breakdown spectroscopy is automating inline contamination monitoring during fused silica synthesis. ASML-qualified suppliers in the Netherlands and Japan are deploying these systems to eliminate batch-release bottlenecks. The technology is automating what previously required offline laboratory analysis, shrinking qualification timelines from months to weeks for high-volume contracts.
Europe's CSRD disclosure requirements now mandate scope-three emissions reporting for electronics substrate supply chains. German automotive semiconductor buyers are transmitting these obligations upstream to quartz component vendors. Mid-tier suppliers without embedded carbon accounting systems face exclusion from qualified vendor lists serving Stuttgart and Munich-based equipment manufacturers.
Direct long-term contracting is displacing spot procurement for EUV-grade substrates. Taiwanese foundry operators are negotiating three-to-five-year offtake agreements with specified purity improvement trajectories. This pattern is most pronounced in Hsinchu Science Park, where concentrated buyer power enables volume commitments in exchange for dedicated production lines and joint development roadmaps.
Quartz Glass Substrate Market Segmentation
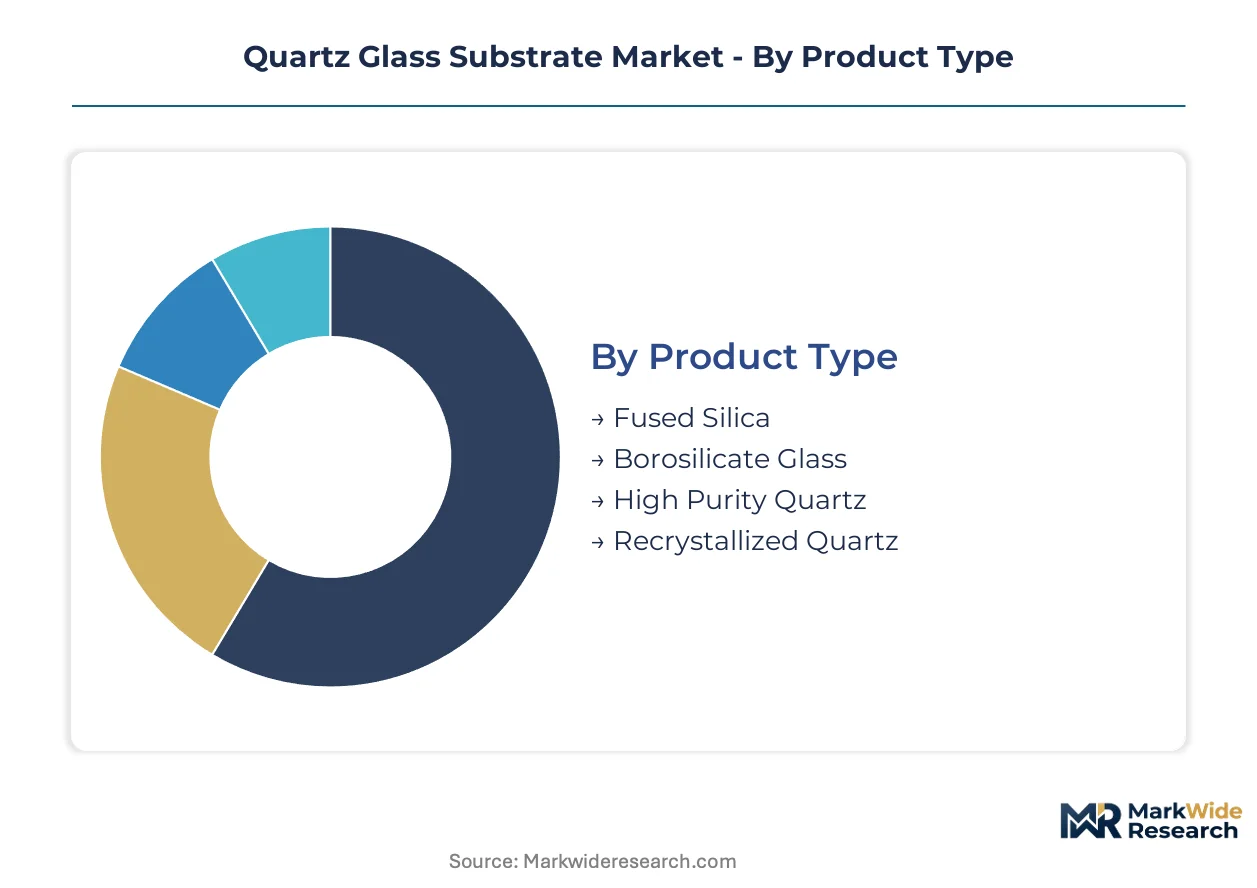
Quartz glass substrate segmentation reveals a market bifurcated between high-volume display applications and precision semiconductor grades. Technical specifications diverge sharply across purity thresholds, thermal expansion coefficients, and contamination limits. Understanding these tiered demands exposes where margin concentration aligns with capability barriers.
Product Type:
Fused silica commands volume leadership through established electric fusion supply chains, while ultra-high-purity synthetic grades capture premium pricing in advanced lithography.
- Fused Silica:Manufactured through electric arc melting of high-purity quartz sand, achieving thermal expansion coefficients below 0.55 x 10⁻⁶/K. Semiconductor wafer processing in South Korea and Taiwan absorbs the majority of output, with each node shrink tightening dimensional stability requirements for photomask blanks.
- High Purity Quartz:Natural quartz refined to sub-10 parts per billion contamination thresholds through acid leaching and thermal shock purification. EUV lithography component demand from Dutch and Japanese equipment OEMs is compressing qualification timelines for certified suppliers.
- Borosilicate Glass:Lower thermal shock resistance than fused silica but cost-advantaged for laboratory equipment and non-critical optical applications.
- Recrystallized Quartz:Reprocessed material serving cost-sensitive photovoltaic crucible manufacturing with relaxed purity specifications.
Today's leader: Fused Silica. Tomorrow's challenger: High Purity Quartz.
Application:
End-use fragmentation spans precision manufacturing and scientific instrumentation, with contamination sensitivity determining grade requirements.
- Semiconductors:Photolithography stages, reaction chambers, and wafer carriers demand synthetic fused silica with UV transparency above 90% at 193nm wavelengths. Sub-3nm node migration in Taiwanese foundries is accelerating substitution toward ultra-high-purity grades.
- Optical Devices:Laser optics and telescope mirrors require homogeneity specifications below 5nm peak-to-valley surface flatness. Defense procurement from US and German contractors maintains steady demand for specialty grade substrates.
- Photovoltaics:Monocrystalline silicon pulling crucibles consume high-purity quartz with different alkali metal tolerances than semiconductor grades.
- Laboratory Equipment:Standard grade substrates serve analytical instrumentation where thermal stability exceeds chemical purity in priority.
Semiconductor applications concentrate margin; photovoltaics absorb volume.
End User:
Customer archetypes separate by certification burden, with electronics manufacturers imposing the most stringent audit protocols.
- Electronics Manufacturers:Integrated device foundries and memory producers in Hsinchu and Pyeongtaek Science Parks specify three-to-five-year purity improvement trajectories in direct contracts.
- Research Institutions:National laboratories and university facilities prioritize optical homogeneity over batch-to-batch consistency.
- Aerospace:Satellite optical systems and re-entry vehicle windows demand thermal shock resistance across extreme temperature differentials.
- Automotive Components:LED headlamp substrates and sensor housings drive mid-tier fused silica consumption with moderate purity requirements.
Electronics manufacturers dictate specification evolution; research institutions sustain specialty demand.
Quality Grade:
Four-tier stratification separates commodity supply from capability-protected premium positions.
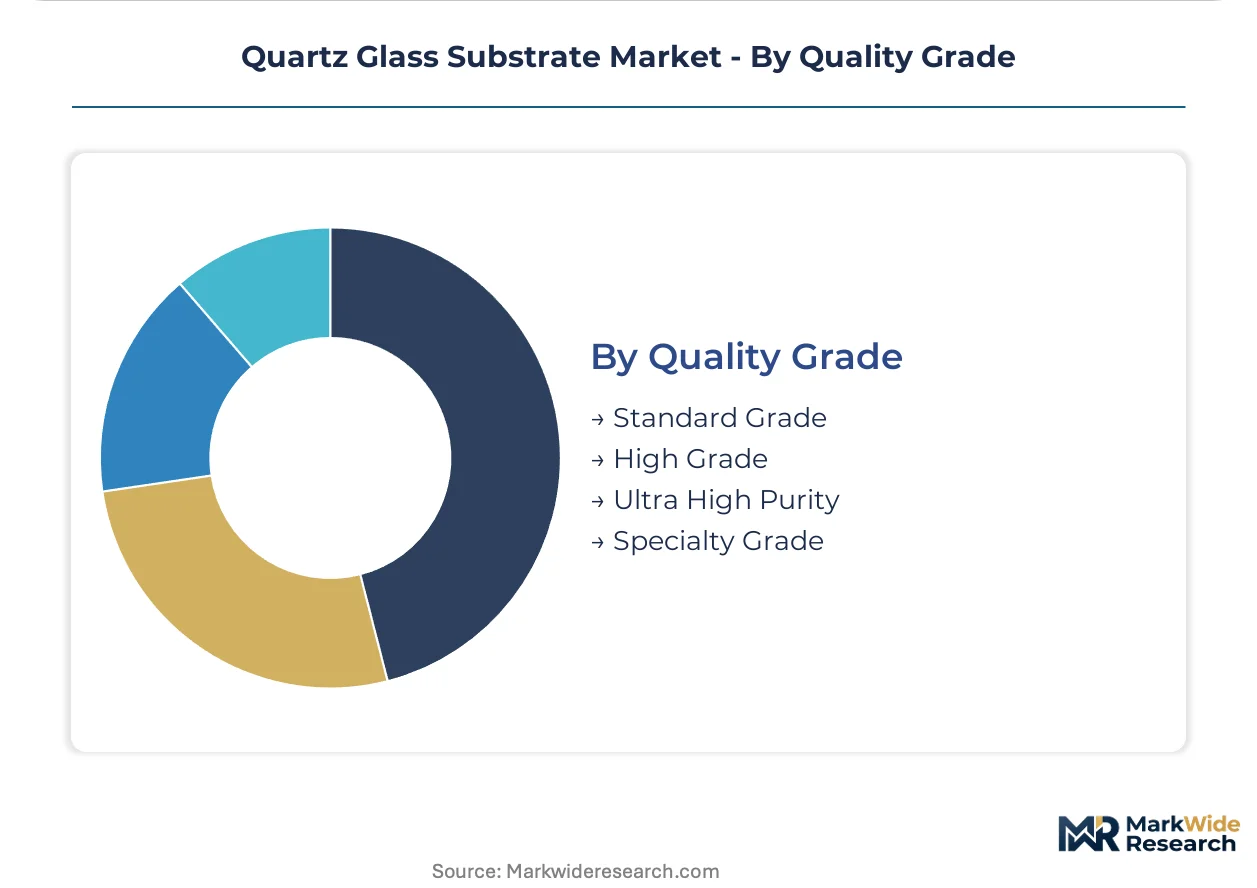
- Ultra High Purity:Sub-10 ppb total contamination with documented traceability for alkali metals, transition metals, and rare earth elements. EUV lithography qualification from ASML-certified suppliers in the Netherlands and Japan creates a narrow qualified vendor base.
- High Grade:10-100 ppb contamination thresholds serving DUV lithography and advanced etching equipment. Flame hydrolysis production in German and Japanese facilities dominates supply.
- Standard Grade:100-1000 ppb tolerance for display panel manufacturing and general industrial optics.
- Specialty Grade:Customized thermal expansion profiles for specific optical or mechanical property requirements.
Ultra High Purity commands pricing power; Standard Grade faces substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing quartz substrate production toward jurisdictions with lower compliance costs for ultra-high-purity certification. Foundries in South Korea and Taiwan absorb premium volumes, while European REACH mandates elevate testing burdens for import-dependent suppliers.
South Korea
Samsung Foundry and SK Hynix drive synthetic fused silica procurement for sub-3nm EUV lithography nodes. The Ministry of Trade, Industry and Energy (MOTIE) subsidizes domestic material purification capabilities under the K-Semiconductor Belt initiative. Pyeongtaek's semiconductor cluster concentrates photomask blank demand from Dutch equipment OEMs.
Taiwan
TSMC's advanced node expansion at Hsinchu and Taichung Science Parks consumes the majority of regional ultra-high-purity substrate output. The National Development Council enforces local content requirements for critical semiconductor materials procurement. Kaohsiung's emerging fab complex is negotiating three-to-five-year offtake agreements with certified quartz suppliers.
Japan
Domestic equipment manufacturers Tokyo Electron and Shin-Etsu Chemical anchor demand for JIS-standardized quartz components. METI promotes captive purification capabilities through the Semiconductor and Digital Industry Strategy. Kyushu's silicon island hosts specialized fused silica refiners serving photolithography stages.
Germany
Automotive semiconductor buyers in Stuttgart and Munich transmit CSRD scope-three emissions obligations upstream to substrate vendors. ECHA's REACH enforcement tightens heavy metal traceability requirements for electronics-grade materials. Heraeus Holding operates integrated refining-to-fabrication facilities in Hanau.
China
Domestic foundry buildouts by SMIC and Hua Hong Semiconductor absorb standard-grade fused silica for mature node processing. MIIT's GB standards and dual carbon goals accelerate electric furnace upgrades in legacy flame-hydrolysis facilities. Yangtze River Delta manufacturing clusters concentrate import substitution efforts for photomask substrates.
Quartz Glass Substrate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated refiners commanding premium positions in EUV-qualified supply while regional fabricators serve display-grade volume. The vendor base concentrates around three capability tiers: electric-fusion specialists with captive sand deposits, synthetic silica producers leveraging flame hydrolysis scale, and niche fabricators serving research instrumentation. Strategic moves center on backward integration into ultra-low-alkali feedstock sourcing and multi-jurisdiction certification harmonization to compress qualification timelines.
Among German-integrated material groups, Heraeus Holding exemplifies the captive-refining archetype spanning raw material to finished wafer carriers. Japanese specialists Shin-Etsu Chemical and Tosoh Quartz Co., Ltd. occupy positions within the premium synthetic silica tier, with geographic naming signaling domestic production anchoring. These three entities represent distinct competitive vectors: European vertical integration, Asian synthetic purity scale, and equipment-aligned component supply.
| Leading Market Players |
|---|
| Heraeus Holding |
| Momentive Performance Materials Inc. |
| Corning Inc. |
| Shin-Etsu Chemical |
| Tosoh Quartz Co., Ltd. |
| QSIL |
| MARUWA |
| Raesch Quarz GmbH |
| Saint-Gobain Quartz |
| Others |
Pricing and Supply Chain Analysis
Cleanroom manufacturing engineering talent concentrates in Japan and Germany, creating labor-cost differentials that widen spreads between EUV-qualified premium tiers and standard-grade alternatives. These geographic skill premiums compound with energy intensity in electric fusion to stratify pricing across quality grades.
Pricing Analysis
Distributor margins compress at the standard-grade tier while direct-to-OEM contracts capture premium pricing for EUV-qualified supply. Three-tier pricing structure across premium, standard, and economy levels separates ASML-certified ultra-high-purity grades from flame-hydrolysis high-grade and display-standard alternatives. Cost compression in standard-grade fused silica is intensifying because aluminosilicate glass substitution threats from display panel manufacturers force volume discounting. Electronics manufacturers in Hsinchu and Pyeongtaek show least price sensitivity for contamination thresholds below 10 ppb, while photovoltaic crucible buyers absorb volume at economy-tier positioning.
Supply Chain Analysis
Freight costs for ultra-low-alkali sand feedstock from Spruce Pine, North Carolina and similar deposits amplify landed costs for non-integrated refiners in Europe and Asia. Supply concentrates in Germany, Japan, and the United States for high-purity electric fusion capacity, while China dominates flame-hydrolysis synthetic silica scale. Raw material dependencies center on ultra-low-alkali quartz sand, high-purity silicon tetrachloride, and specialized refractory crucibles for arc melting. Single-source vulnerability for semiconductor-grade sand deposits creates supply risk during extraction disruptions. Distribution runs through direct long-term offtake agreements with foundry operators, displacing spot procurement for advanced lithography grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The quartz glass substrate market represents a late-cycle quality story as foundry migration toward sub-3nm EUV nodes concentrates procurement power with certified ultra-high-purity suppliers capable of documented traceability below 10 ppb contamination thresholds.
For Market Incumbents: Extend qualification relationships through joint development roadmaps that lock in three-to-five-year purity improvement trajectories with Taiwanese and South Korean foundry operators. Deepen backward integration into captive ultra-low-alkali sand deposits to insulate margin structures from feedstock concentration risk. Prioritize multi-jurisdiction certification harmonization across REACH, RoHS, and China's GB standards to compress redundant testing cycles that delay volume contracts. For New Entrants and Emerging Players: Enter via India's PLI scheme for semiconductor manufacturing, where greenfield fab projects lack established local quartz component supply relationships and qualification timelines remain open. Target photovoltaic silicon pulling crucibles as an adjacent volume absorption channel, where purity specifications differ from semiconductor grades and certification barriers remain lower. Pursue equipment OEM partnerships rather than direct foundry qualification to bypass ASML-certified vendor list constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier flame-hydrolysis producers facing margin compression from energy cost volatility and standard-grade substitution pressure. Long-term viability over a 5-10 year window favors integrated electric-fusion specialists with captive sand deposits and existing EUV qualification relationships. Watch for inflection signals in direct long-term contracting velocity at Hsinchu Science Park, where concentrated buyer power indicates foundry confidence in dedicated supply commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultra-Low-Alkali Feedstock | Heraeus Holding's captive Spruce Pine sand sourcing insulates margin structures from extraction disruption risk. |
| Multi-Jurisdiction Certification Harmonization | Unified REACH-RoHS-GB testing protocols reduce qualification timelines from months to weeks for high-volume contracts. |
| Direct Long-Term Offtake Agreements | TSMC's three-to-five-year purity improvement trajectories lock in dedicated production lines and joint development roadmaps. |
| Laser-Induced Breakdown Spectroscopy Deployment | ASML-qualified suppliers in the Netherlands automate inline contamination monitoring to eliminate batch-release bottlenecks. |
| Carbon Accounting System Implementation | German automotive semiconductor buyers transmit CSRD scope-three obligations upstream, excluding non-compliant vendors from qualified lists. |
Research Methodology
Direct dialogue with semiconductor equipment procurement managers, cleanroom manufacturing engineers, quartz refinery operations directors, and regulatory compliance officers grounded qualitative findings across the primary research phase. Secondary validation drew from ECHA REACH filings, SEC 10-K disclosures by listed material suppliers, Japanese METI industrial statistics, and Taiwan's National Development Council fab investment reports. Bottom-up and top-down triangulation cross-checked volume estimates against import-export customs data and foundry capex announcements.
Bottom-up modeling aggregated segment-level demand across purity grades, applications, and end-user archetypes, while top-down validation referenced aggregate semiconductor materials spend patterns across the projection horizon. Segmentation dimensions included product type, quality grade, application, and regional manufacturing cluster concentration. CAGRs were derived from fitted growth curves calibrated to historical qualification timeline compression and node migration schedules. Industry-specific forecast inputs incorporated EUV lithography adoption curves and electric furnace capacity expansion announcements.
Inputs from primary stakeholder interviews and disclosed regulatory filings were available through the study window; gaps in real-time foundry inventory levels and confidential contract pricing introduce uncertainty bands around volume and value estimates. Forecasts reflect assumptions regarding continued sub-3nm node migration, stable energy tariff regimes for electric fusion, and sustained REACH-RoHS enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
VCSEL for Data Communication Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Liquid Lenses Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Raman Amplifier Market
Optical Components
Optical Transceiver Market
Optical Components
Optical Component Tester Market
Optical Components
Faraday Rotator Market
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
Display Optical Film Market
Optical Components
Optical Interconnect Market
Optical Components
Optical Lens Edger Market
Optical Components
Europe Scintillator Market
Optical Components
LGP (Light Guide Plate) for TV Market