
 Europe Optical Film Market | 2026-2036
Europe Optical Film Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Optical Film Market Analytics
Software-defined optical tuning is decoupling film performance from fixed hardware specifications across European supply chains. 3M leverages its polymer science portfolio to sustain premium positioning in display-grade polarizer films. Toray Industries anchors its European operations through specialized PET substrate production for quantum dot enhancement films.
Optical film comprises multilayer polymer substrates engineered with nanoscale precision, typically 50-250 micrometers thick, designed to manipulate light transmission, polarization, or diffusion for electronic displays and solid-state lighting systems. Polarizer films currently command the largest value share within the product type dimension due to their irreplaceable function in LCD and emerging microLED stacks. Quantum dot technology represents the fastest-expanding technology segment as European display manufacturers pursue wider color gamut specifications for premium consumer electronics applications.
REACH compliance and the EU Green Deal framework constrain fluorinated compound usage in optical film manufacturing, while RoHS directives govern heavy metal content in display-integrated film assemblies. ECHA substance evaluations are reshaping raw material sourcing requirements for diffusers and prism films sold across the single market. Stakeholders must monitor evolving MEE-equivalent standards from Asian suppliers that increasingly dictate upstream material availability for European converters.
Market Dynamics
Software-defined optical tuning is decoupling film performance from fixed hardware specifications across European supply chains. This structural shift enables display manufacturers to source standardized substrates while calibrating optical properties through firmware, compressing traditional film specification tiers and pressuring incumbent suppliers to demonstrate algorithmic compatibility.
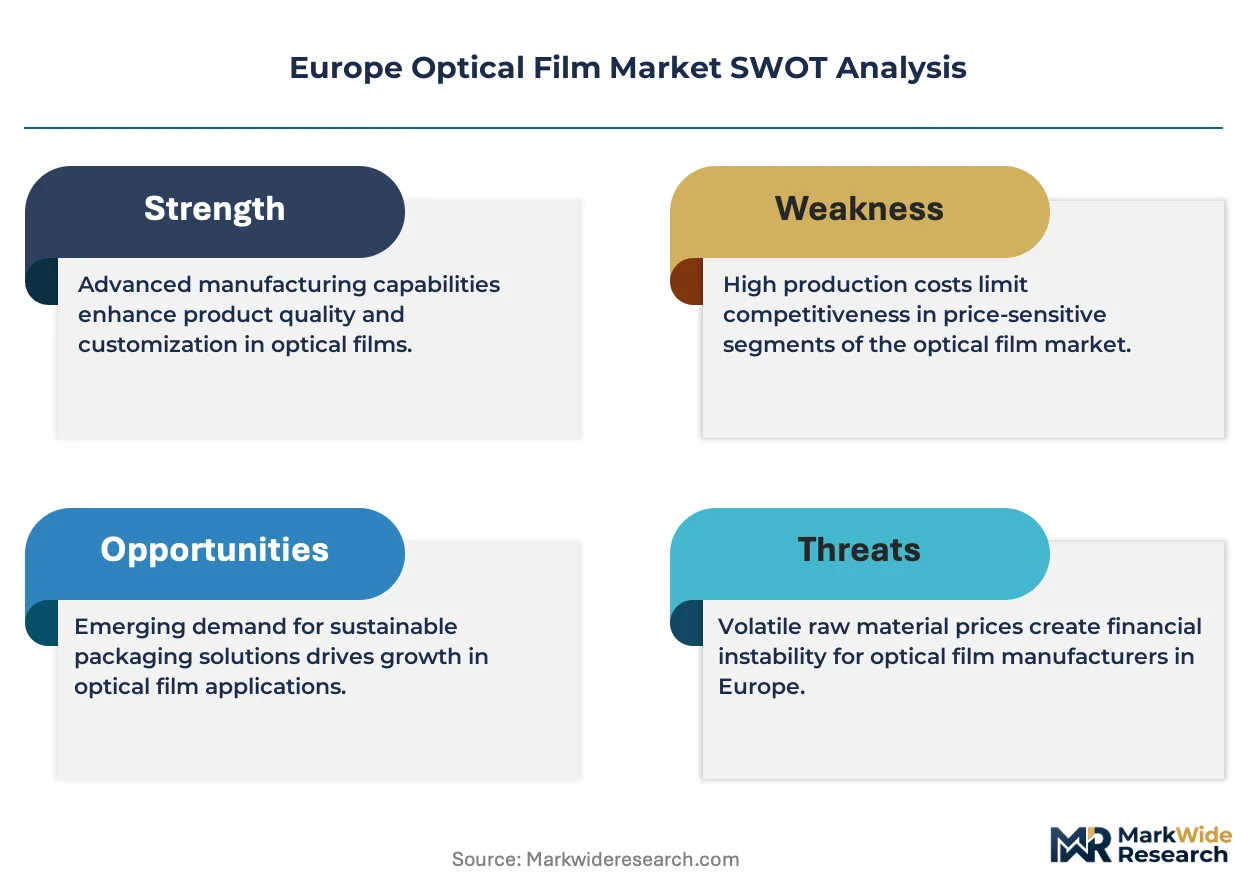
Growth Catalysts
- EU Green Deal compliance mandates:The framework tightens material requirements for fluorinated compounds in optical film manufacturing. Producers investing in alternative chemistries secure preferential supplier status with German automotive display manufacturers.
- Quantum dot enhancement film demand:Premium consumer electronics manufacturers in France and the Netherlands pursue wider color gamut specifications. This technology segment commands accelerating procurement volumes from tier-one display integrators.
- Baden-Württemberg electronics corridor concentration:Germany's southwestern manufacturing belt hosts dense clusters of display assembly operations. Proximity to these facilities reduces logistics costs and enables just-in-time substrate delivery.
Market Restraints
- Fluorinated precursor supply concentration:ECHA substance evaluations restrict qualified raw material sources for high-performance diffuser films. European converters face extended qualification timelines for alternative chemistries.
- PET substrate price volatility:Energy-intensive polymer production exposes optical film margins to natural gas cost fluctuations. German chemical parks transmit these input shocks directly to film laminators.
- MicroLED direct-emission substitution:Emerging display architectures eliminate polarizer film layers entirely. Long-term demand compression threatens the largest product category within optical film portfolios.
Strategic Opportunities
- Polish and Czech manufacturing expansion:Lower operating costs and EU structural fund access attract film conversion facilities. These locations serve as distribution hubs for Central European display assembly plants.
- Automotive interior display proliferation:Dashboard, mirror-replacement, and passenger entertainment screens multiply film area per vehicle. French and Italian premium automotive brands specify anti-reflective and anti-fingerprint coated films.
- RoHS directive alignment services:Heavy metal content verification and documentation creates value-added service revenue. Film suppliers offering integrated compliance certification capture procurement preference from display integrators.
Industry Challenges
- Nanoscale coating process engineering talent:Specialized expertise in atomic layer deposition and precision slot-die coating remains scarce. German technical universities and Fraunhofer institutes compete with industry for qualified researchers.
- MEE-equivalent standard reconciliation:Asian substrate suppliers operate under divergent environmental monitoring protocols. European converters must maintain dual documentation systems to satisfy ECHA and customer audit requirements.
- Cleanroom infrastructure capex cycles:Class 1000 and better manufacturing environments require substantial capital deployment. Mid-scale converters face financing constraints for capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Optical Film Market |
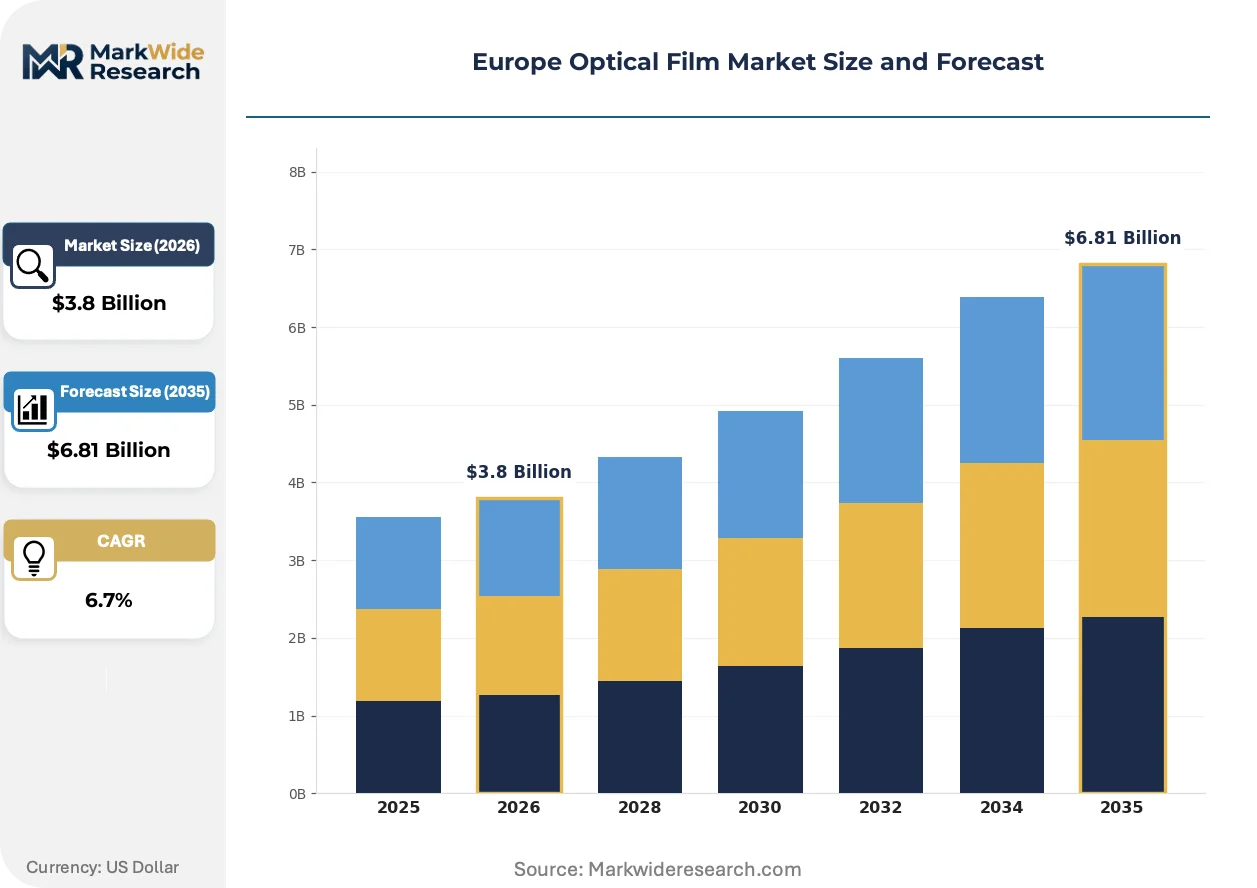
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polarizers, Diffusers, Prism Films, Reflective Films Application: Display, Lighting, Packaging, Automotive End User: Consumer Electronics, Industrial, Healthcare, Telecommunications Technology: LCD, OLED, Quantum Dot, MicroLED |
| Companies Covered | 3M, LG Chem, Toray Industries, Nitto Denko, Mitsubishi Chemical, Sumitomo Chemical, Samsung SDI, Hyosung Chemical, Kolon Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Optical Film Market Evolving Landscape
Computational optical design is displacing empirical film development cycles across European supply chains. This methodological shift compresses product qualification timelines while demanding new competencies in simulation software and machine learning from traditional polymer science organizations.
Metasurface optical films are rewriting the relationship between physical substrate thickness and optical function. These engineered nanostructures manipulate light through subwavelength surface patterns rather than bulk material properties. Automotive HUD manufacturers in Stuttgart and Munich are qualifying metasurface combiners for augmented reality windshields. The technology is compressing supply chain tiers by enabling foundry-style fabrication models that bypass conventional film lamination and conversion steps.
REACH authorization procedures are restricting per- and polyfluoroalkyl substance usage in optical film manufacturing. The regulation forces reformulation of anti-smudge and anti-reflective coatings that previously relied on fluorinated surface treatments. Diffuser and prism film categories face the most acute raw material sourcing disruptions. Suppliers are responding with silicone-based and hydrocarbon alternatives that require extended customer requalification.
Automotive procurement teams are consolidating optical film specifications across multiple display programs. Tier-one suppliers such as Continental and Bosch demand substrate platforms compatible with software-defined optical tuning across instrument cluster, center stack, and passenger screen applications. This pattern is most visible in German OEM supply chains where platform engineering mandates override individual program customization. Film suppliers must demonstrate firmware-configurable performance ranges rather than fixed optical specifications.
Europe Optical Film Market Segmentation
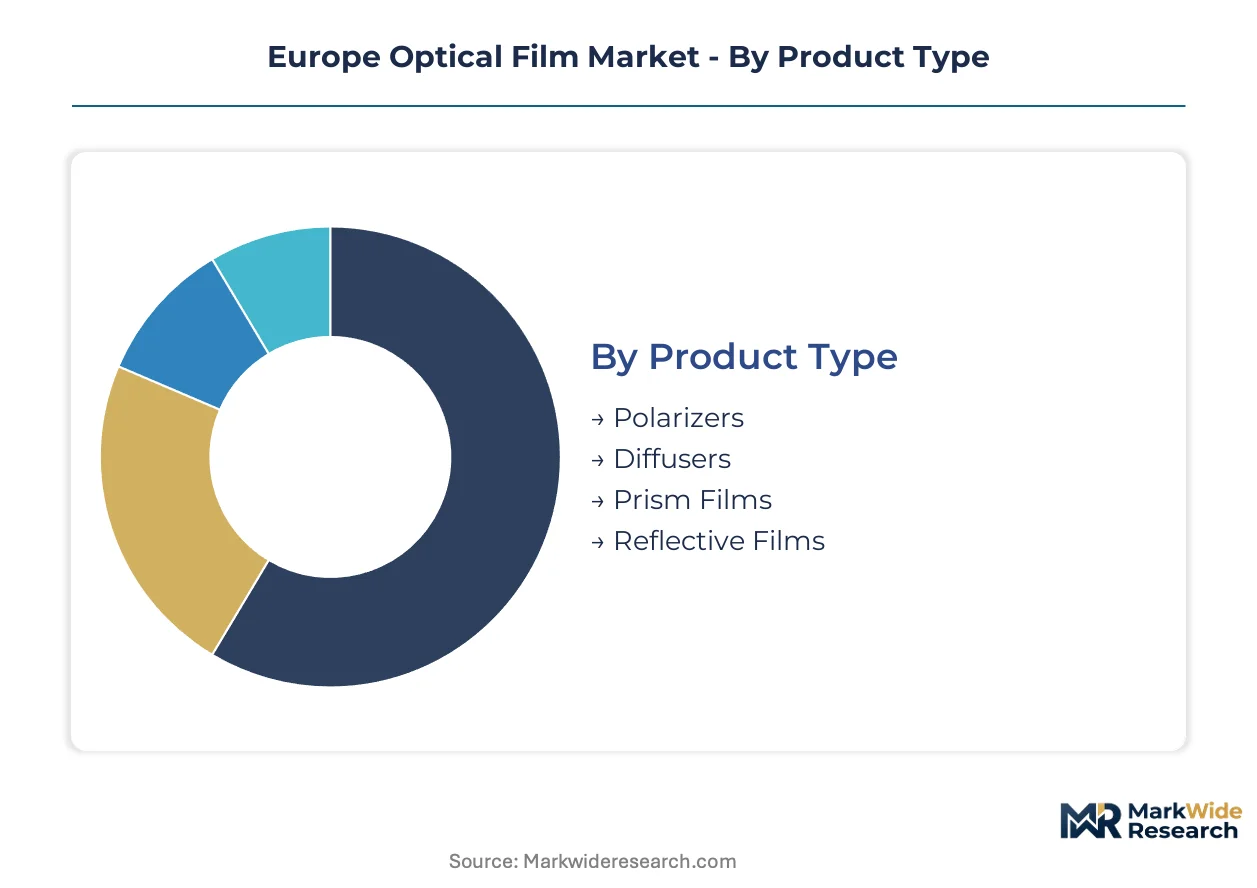
Optical film specifications vary sharply across end-use applications, with display manufacturers demanding nanoscale precision while automotive buyers prioritize durability under thermal cycling. Upgrade cycles in consumer electronics and the shift toward software-defined optical tuning are fragmenting procurement patterns across substrate categories.
Product Type:
Replacement cycles in display manufacturing are compressing as OEMs consolidate supplier bases around multi-functional substrates capable of firmware-configurable performance.
- Polarizers:These multilayer polymer films selectively transmit light waves of specific orientation, typically incorporating iodine-dyed polyvinyl alcohol sandwiched between TAC substrates. LCD and emerging microLED stacks in Germany's Baden-Württemberg corridor absorb the majority of European procurement volumes, though direct-emission display architectures threaten long-term demand compression.
- Diffusers:Engineered surface or bulk structures scatter incident light to eliminate hot spots and improve luminance uniformity across display panels. REACH authorization restrictions on fluorinated compounds force European converters toward silicone-based alternatives, extending requalification timelines with French and Dutch consumer electronics manufacturers.
- Prism Films:Microstructured acrylic or polycarbonate substrates redirect off-axis light toward the viewer, enhancing brightness without additional power consumption. Automotive HUD applications in Stuttgart and Munich are qualifying these for augmented reality windshields.
- Reflective Films:Metallized or dielectric multilayer constructions return light toward the source for backlight recycling or ambient light rejection. Solid-state lighting retrofits across industrial facilities in Poland and the Czech Republic drive procurement volumes.
Volume placements concentrate in Polarizers; the faster expansion belongs to Diffusers as reformulation investments mature.
Application:
Cost tier differentiation separates commodity lighting films from display-grade substrates commanding certification premiums.
- Display:Smartphone, tablet, monitor, and television panels require polarizers, prism films, and quantum dot enhancement films with sub-micron thickness tolerances. German automotive display manufacturers are strengthening procurement across instrument cluster and center stack programs.
- Lighting:Edge-lit and direct-lit LED fixtures employ diffuser and reflective films to optimize extraction efficiency and beam shaping. Commercial retrofits in France and Italy specify anti-glare surface treatments.
- Packaging:Security features and premium aesthetic applications utilize holographic and color-shifting optical films. Anti-counterfeiting mandates from EU customs authorities expand authentication film requirements.
- Automotive:Dashboard, mirror-replacement, and passenger entertainment screens multiply film area per vehicle while demanding anti-reflective and anti-fingerprint coatings. French and Italian premium brands specify hardened surface treatments for interior durability.
Display applications dominate procurement spend; Automotive is climbing the fastest as electrification multiplies screen counts per vehicle platform.
End User:
Customer type fragmentation separates high-volume electronics OEMs from specialized industrial buyers with divergent qualification protocols.
- Consumer Electronics:Television, smartphone, and personal computer manufacturers drive standardization around quantum dot and OLED-compatible substrates. Premium color gamut specifications from Dutch and French brands accelerate quantum dot enhancement film adoption.
- Industrial:Machine vision, process control, and human-machine interface applications demand wide-temperature-range optical films with chemical resistance. German manufacturing automation clusters specify extended operational lifetimes.
- Healthcare:Diagnostic imaging displays and surgical visualization systems require color-calibrated films with anti-microbial surface treatments. CE marking under the EU MDR tightens biocompatibility documentation requirements.
- Telecommunications:Data center optical interconnects and fiber-to-the-home terminals employ waveguide and collimating films. 5G infrastructure deployment across Spain and Italy expands demand for precision optical components.
Consumer Electronics anchors volume commitments; Healthcare is gaining share fastest as diagnostic display specifications tighten.
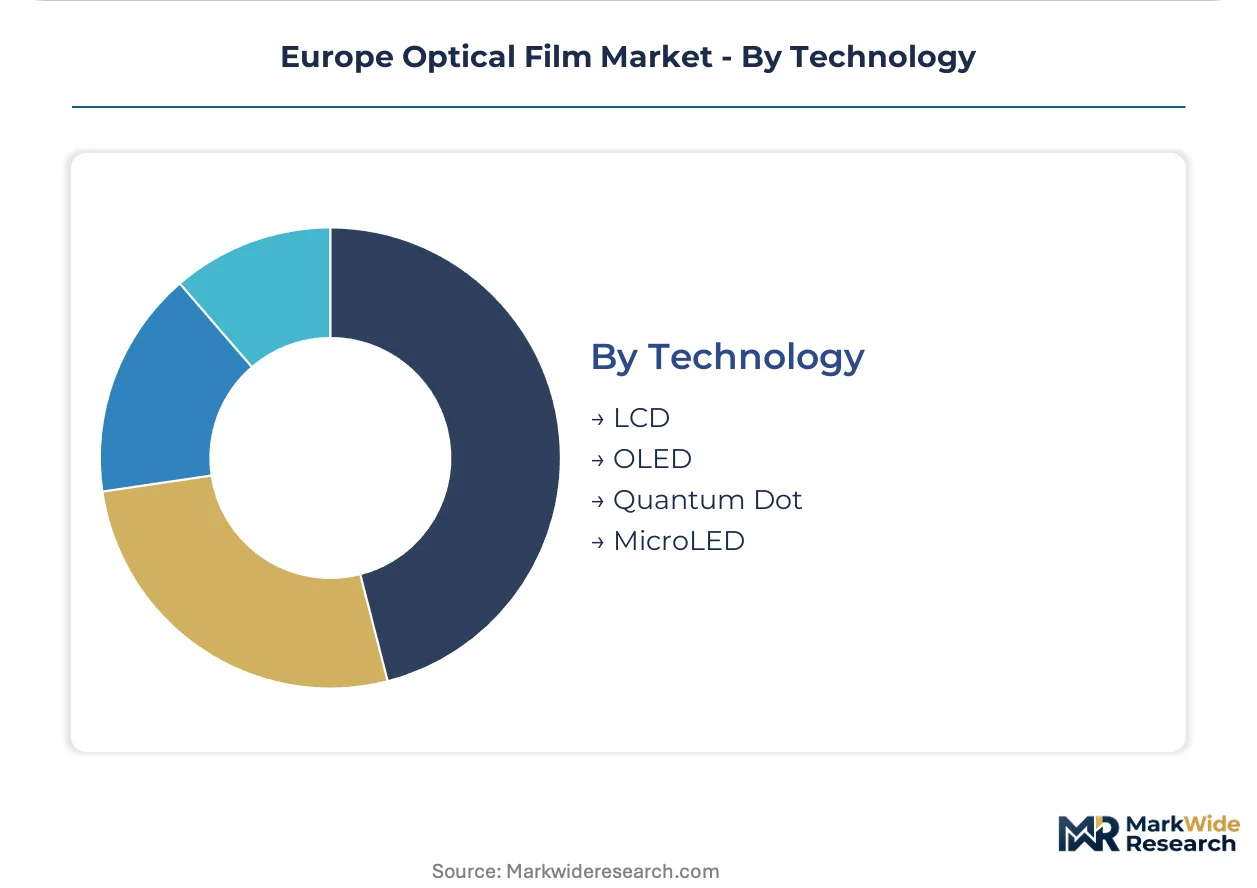
Technology:
Supply concentration in substrate manufacturing follows the technology maturity curve, with established LCD supply chains facing disruption from emerging microLED qualification.
- LCD:Mature liquid crystal display architectures consume polarizer, diffuser, and prism film stacks in standardized configurations. Polish and Czech conversion facilities serve as distribution hubs for Central European LCD assembly plants.
- OLED:Organic light-emitting diode panels eliminate backlight units but retain circular polarizers for ambient light suppression and touch electrode shielding. Italian and French premium smartphone brands specify ultra-thin circular polarizer constructions.
- Quantum Dot:Color conversion films incorporating cadmium-free or cadmium-containing quantum dots expand color gamut beyond traditional phosphor limitations. EU RoHS directives govern heavy metal content, forcing cadmium-free formulations for European market access.
- MicroLED:Direct-emission microLED architectures eliminate polarizer layers entirely, threatening the largest optical film product category over the long term. Stuttgart and Munich automotive HUD manufacturers are qualifying metasurface combiners that bypass conventional film lamination.
LCD technology maintains the steepest volume base; Quantum Dot is expanding most quickly as premium consumer electronics manufacturers pursue wider color gamut specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's electronics manufacturing corridor anchors European optical film demand, with Stuttgart and Karlsruhe hosting dense clusters of display assembly operations serving automotive and industrial customers.
Germany
Automotive display manufacturers in Stuttgart and Munich are multiplying film area per vehicle across instrument cluster and center stack programs. The EU Green Deal and F-Gas Regulation tighten fluorinated compound compliance requirements for local converters. Fraunhofer institutes in Baden-Württemberg collaborate with film suppliers on metasurface qualification for augmented reality windshields.
France
Premium consumer electronics brands in Paris and the Île-de-France region specify quantum dot enhancement films for wider color gamut televisions and monitors. REACH authorization procedures restrict per- and polyfluoroalkyl substance usage in anti-reflective coatings. Toulouse and Grenoble host specialized cleanroom facilities for aerospace-qualified optical film conversion.
Netherlands
Eindhoven's high-tech systems and materials cluster drives procurement of polarizer films for OLED-compatible smartphone displays. RoHS directives govern heavy metal content in display-integrated assemblies exported across the single market. ASML's lithography supply chain creates spillover demand for precision optical components in nearby Venlo and Helmond.
Poland
Lower operating costs and EU structural fund access attract film conversion facilities serving Central European LCD assembly plants. ECHA substance evaluations reshape raw material sourcing requirements for diffusers distributed from Wrocław and Kraków logistics hubs. The country's manufacturing automation clusters specify extended-lifetime optical films for machine vision applications.
Italy
Premium automotive brands in Turin and Milan specify anti-fingerprint and hardened surface treatments for interior display durability. CE marking under the EU MDR tightens biocompatibility documentation for healthcare diagnostic imaging films produced near Milan's medical device corridor. Bologna's packaging machinery sector expands authentication film requirements under EU customs anti-counterfeiting mandates.
Europe Optical Film Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across European optical film supply chains. The market structure concentrates around integrated polymer science conglomerates and specialized substrate converters. Three archetypes dominate: diversified chemical majors with captive film operations, dedicated optical film specialists, and Asian substrate suppliers establishing European distribution. Capacity expansion and software-defined optical tuning compatibility represent the dominant competitive moves as procurement teams consolidate specifications across display programs.
Within the diversified chemical major tier, 3M and Toray Industries exemplify integrated polymer science capabilities that sustain premium positioning in display-grade substrates. Among Asian-origin suppliers, LG Chem and Samsung SDI occupy positions as volume anchors for quantum dot and polarizer film categories. These named entities represent archetypes rather than exhaustive market coverage, with each sitting within distinct strategic postures around technology licensing versus captive manufacturing scale.
| Leading Market Players |
|---|
| 3M |
| LG Chem |
| Toray Industries |
| Nitto Denko |
| Mitsubishi Chemical |
| Sumitomo Chemical |
| Samsung SDI |
| Hyosung Chemical |
| Kolon Industries |
| Others |
Value Network & Pricing Analysis
Display-grade certification tiers separate polarizer films commanding firmware-configurable premiums from commodity diffuser substrates facing cost compression, with German automotive OEMs consolidating procurement around multi-program platforms while Polish conversion facilities absorb price-sensitive LCD volumes. This bifurcation concentrates margin capture in REACH-compliant substrate suppliers serving Stuttgart and Munich, while energy-intensive PET production exposes laminators to natural gas cost transmission from German chemical parks.
Pricing Analysis
Margin tightening in commodity diffuser tiers reflects silicone-based reformulation costs as REACH authorization restricts fluorinated compounds. Three-tier pricing structure across premium, standard, and economy levels separates firmware-configurable automotive substrates from fixed-specification consumer electronics films. Price differentiation hinges on EU Green Deal compliance certification and volume scale commitments from Baden-Württemberg display assemblers. Consumer electronics procurement teams in France and the Netherlands exhibit highest price sensitivity; German automotive tier-one suppliers prioritize algorithmic compatibility over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Japanese polarizer substrate suppliers dominating quantum dot enhancement film precursor availability. Raw material dependencies center on PET resin from German chemical parks, iodine-dyed PVA from Asian polymer producers, and cadmium-free quantum dot phosphors. Tariff exposure threatens European converters importing TAC substrates under divergent MEE-equivalent documentation protocols. Distribution runs through Wrocław and Kraków logistics hubs serving Central European LCD assembly plants, with just-in-time delivery contracts to Baden-Württemberg automotive clusters commanding premium freight terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom infrastructure scarcity props pricing for Class 1000 manufacturing capacity, constraining mid-scale converter expansion and sustaining incumbent margin structures across European optical film supply chains.
For Market Incumbents: Anticipate microLED direct-emission substitution compressing polarizer demand by qualifying metasurface combiner technologies for augmented reality windshields. Defend position through backward integration into silicone-based diffuser formulation to bypass REACH-authorized fluorinated compound restrictions. Prioritize capacity addition in Polish manufacturing corridors to capture Central European LCD assembly procurement migrating from German conversion facilities. For New Entrants and Emerging Players: Begin with automotive interior display proliferation in French and Italian premium brands, where anti-fingerprint and hardened surface treatment specifications remain undersupplied by incumbent coating specialists. Target healthcare diagnostic imaging films near Milan's medical device corridor, where EU MDR biocompatibility documentation requirements create qualification barriers for commodity converters. Pursue foundry-style metasurface fabrication partnerships with Fraunhofer institutes as a go-to-market angle bypassing conventional lamination equipment investments. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cleanroom operators given EU structural fund access accelerating Polish and Czech manufacturing expansion. Long-term viability favors substrate converters demonstrating software-defined optical tuning compatibility across automotive multi-program platforms. Watch for ECHA substance evaluation acceleration as an inflection indicator forcing extended requalification timelines and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | Silicone-based diffuser chemistry secures preferential supplier status with German automotive OEMs. |
| Cleanroom Capacity Expansion | Class 1000 manufacturing in Poland captures Central European LCD assembly procurement volumes. |
| Metasurface Technology Partnership | Fraunhofer collaboration enables augmented reality windshield qualification with Stuttgart automotive HUD manufacturers. |
| Software-Defined Optical Tuning Integration | Firmware-configurable performance ranges satisfy Continental and Bosch platform consolidation mandates. |
| RoHS Alignment Service Development | Integrated heavy metal certification captures procurement preference from Dutch consumer electronics brands. |
Research Methodology
Multi-period observation of ECHA substance evaluation timelines, EU Green Deal implementation trajectories, and automotive display program consolidation anchored the trend analysis, supplemented by interviews with optical film plant managers, procurement leads at German Tier 1 suppliers, distribution channel partners in Polish logistics hubs, and technical R&D directors at polymer science conglomerates. Secondary validation drew from REACH authorization databases, F-Gas Regulation compliance filings, SEC 10-K disclosures from listed materials companies, and customs trade data tracking PET substrate import flows. Bottom-up volume modeling across substrate categories triangulated against top-down display industry production forecasts.
Segment-weighting approaches distributed value estimates across polarizer, diffuser, prism, and reflective film product types, with further disaggregation by LCD, OLED, quantum dot, and microLED technology maturity curves. End-use application splits incorporated display, lighting, packaging, and automotive procurement patterns, while geographic allocation reflected Baden-Württemberg electronics corridor concentration against Polish and Czech distribution hub expansion. CAGRs derived from polynomial trend fitting across the projection horizon, with inputs from natural gas price volatility indices affecting PET production economics and automotive electrification screen-count multipliers.
Regulatory acceleration beyond ECHA substance evaluation timelines, faster-than-anticipated microLED commercialization, and automotive OEM platform standardization reversals are the dominant revision risks to modeled outcomes. Forecasts embed assumptions around REACH authorization procedural timelines and EU structural fund disbursement rates for Central European manufacturing expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Quartz Glass Substrate Market
Optical Components
Optical Lens Edger Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
CMP Polishing Machine Market
Optical Components
Machine Vision Light Source Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
North America Tunable Laser Market
Optical Components
Portable Lenses Market
Optical Components
Optical Amplifier Market
Optical Components
Optical Waveguide Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Photomask Pellicle Market