
 Single Wafer Wet Cleaning Equipment Market | 2026-2036
Single Wafer Wet Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Single Wafer Wet Cleaning Equipment Market Insights
Advanced node semiconductor manufacturing is hardening as the dominant demand vertical, displacing legacy research and solar applications. Applied Materials leverages its installed base dominance in front-end wafer processing to sustain pricing power across sub-7nm foundry contracts. Tokyo Electron anchors its position through proprietary chemical delivery architectures that reduce particle counts below 0.1 particles per wafer. Lam Research competes by extending its dry etch expertise into hybrid wet-dry cleaning sequences for 3D NAND stack processing.
Single wafer wet cleaning equipment refers to precision systems that process individual semiconductor wafers using controlled chemical dispensation, megasonic or brush-assisted agitation, and deionized water rinsing at temperatures typically ranging from ambient to 80°C, designed to remove particulate, metallic, and organic contaminants without cross-contamination between wafers. These systems serve the critical function of maintaining yield rates in advanced fabrication by ensuring surface cleanliness prior to deposition, lithography, or etch steps. Chemical cleaning technology dominates current revenue pools due to its entrenched role in photoresist stripping and post-etch residue removal, while spin clean technology represents the fastest-growing segment as throughput demands intensify for high-volume logic foundries. Batch cleaners retain relevance in trailing-edge and memory applications where cost-per-wafer economics outweigh particle performance requirements.
ISO 14644 cleanroom classification standards, SEMI S2 safety guidelines, and regional semiconductor subsidies collectively shape equipment qualification timelines and factory acceptance protocols for new system deployments. The EPA regulates effluent chemistry discharge from US-based fabrication facilities, constraining wet bench chemical formulations and driving closed-loop recycling adoption. Stakeholders must monitor evolving export control frameworks governing advanced equipment shipments to specific manufacturing regions while calibrating R&D allocation between incremental throughput improvements and next-generation cleaning chemistries for gate-all-around transistor architectures.
Market Dynamics
Transition to gate-all-around transistor architectures at 3nm and below is forcing equipment suppliers to recalibrate chemical delivery precision and thermal uniformity specifications across single wafer platforms.
Growth Catalysts
- ISO 14644-1 cleanroom classification tightening:Semiconductor fabs in Taiwan and South Korea are mandating sub-0.1 particle-per-wafer performance thresholds, accelerating replacement cycles for legacy batch systems.
- 3D NAND layer stacking beyond 200 layers:Memory manufacturers require hybrid wet-dry cleaning sequences to manage residue accumulation in high-aspect-ratio channel holes.
- China's domestic fab buildout:Regional capacity expansion under the 14th Five-Year Plan is generating concentrated demand for import-substitute wet processing equipment.
Market Restraints
- High-purity chemical supply concentration:Fluorinated solvent production concentrates in Japanese and German chemical conglomerates, exposing equipment OEMs to input cost volatility and allocation constraints.
- Sub-7nm technical barriers:Atomic-level defect control requires closed-loop metrology integration that exceeds current platform architectures without substantial retrofit investment.
- Export control friction:US Department of Commerce Entity List restrictions complicate equipment shipments to specific Chinese foundry projects, elongating qualification timelines.
Strategic Opportunities
- India's semiconductor manufacturing incentives:The country's PLI scheme and Design-Linked Incentive program are attracting foundry investments that will require localized wet cleaning equipment supply chains.
- Photonics and silicon carbide expansion:Compound semiconductor fabs processing 150mm and 200mm wafers for electric vehicle power electronics represent an underserved equipment segment.
- Closed-loop chemical recycling mandates:EPA effluent regulations and EU Green Deal circular economy targets are creating pull for integrated reclamation modules that reduce chemistry consumption.
Industry Challenges
- Process engineer scarcity:Specialized expertise in megasonic frequency optimization and Marangoni drying physics remains concentrated among veteran technicians at established equipment suppliers.
- Fab-to-fab qualification timelines:Each new installation requires 12-18 months of particle baseline establishment and process matching before volume production authorization.
- Legacy system integration:Brownfield fab retrofits must accommodate 300mm platforms alongside existing 200mm wet benches without disrupting production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Wafer Wet Cleaning Equipment Market |
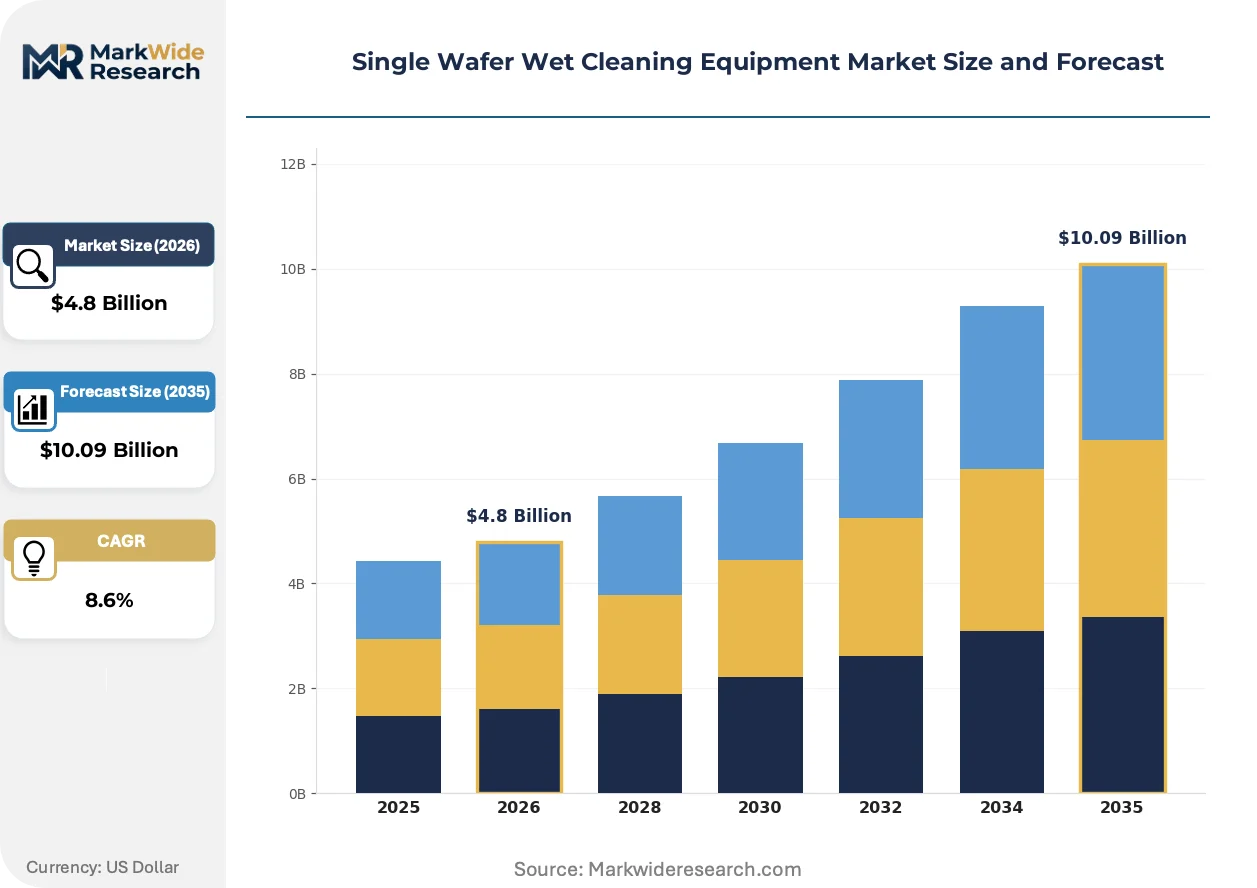
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wafer Cleaners, Batch Cleaners, Plating Systems, Dry Etchers Technology: Chemical Cleaning, Ultrasonic Cleaning, DI Water Rinse, Spin Clean Technology End User: Semiconductor Manufacturers, Research Laboratories, MEMS Fabricators, Solar Cell Producers Application: Wafer Processing, Surface Preparation, Equipment Maintenance, Contamination Removal |
| Companies Covered | Applied Materials, Tokyo Electron, Lam Research, SCREEN Holdings, Hitachi High-Tech, SEMES, Shibaura Mechatronics, Veeco Instruments, ACM Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Wafer Wet Cleaning Equipment Market Trends and Innovations
Equipment architecture is pivoting from discrete chemical processing modules toward integrated platforms that combine precision dispense, in-situ metrology, and adaptive thermal control within unified footprints.
Supercritical CO2 cleaning is expanding into photoresist stripping applications for advanced packaging interconnects. Memory and logic foundries in South Korea are piloting systems that eliminate aqueous chemistries entirely for sensitive low-k dielectric structures. This technology is expanding into broader adoption as environmental compliance costs for aqueous effluent treatment escalate.
REACH restrictions on per- and polyfluoroalkyl substances are compelling European semiconductor chemical suppliers to reformulate cleaning chemistries before 2025 sunset dates. Equipment manufacturers must validate alternative surfactant packages without compromising particle removal efficiency. Front-end EUV lithography fabs are most affected, accelerating collaborative R&D programs between equipment OEMs and German specialty chemical producers.
Consolidated procurement through semiconductor equipment buying consortiums is compressing vendor negotiation cycles and unbundling after-sales service contracts from initial system purchases. Large foundry operators in Taiwan are negotiating multi-year framework agreements that lock in spare parts pricing and field service response times. This pattern is most visible where capital expenditure cycles synchronize with node migration timelines.
Single Wafer Wet Cleaning Equipment Market Segmentation
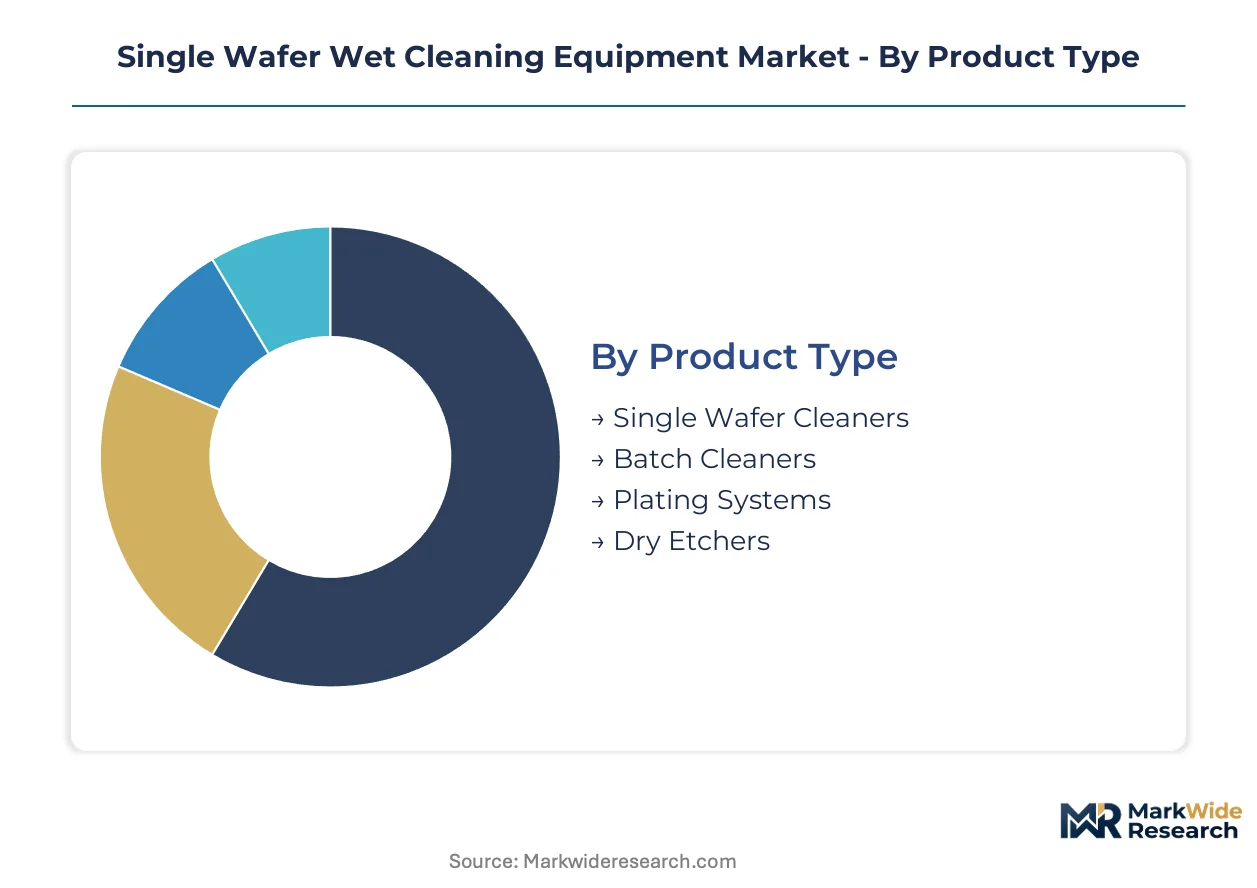
Equipment segmentation in this market directly maps to contamination control stringency, with certification requirements escalating from research-grade installations to sub-7nm foundry deployments. Process node migration and substrate material diversification are fragmenting demand across technology tiers that carry distinct qualification burdens.
Product Type:
SEMI S2 safety certification and ISO 14644-1 cleanroom compliance requirements vary sharply across product architectures, with single wafer platforms facing the most exhaustive factory acceptance protocols.
- Single Wafer Cleaners:These systems process individual wafers through isolated chambers with dedicated chemical delivery, eliminating cross-contamination risks critical for advanced logic production. Taiwan's leading foundries and South Korea's memory manufacturers anchor demand as 3nm gate-all-around transistor architectures harden particle performance thresholds below 0.1 particles per wafer.
- Batch Cleaners:Multiple wafers process simultaneously in shared chemical baths, sacrificing particle control for throughput economics. Trailing-edge fabs in mainland China and legacy memory lines retain these systems where cost-per-wafer metrics outweigh atomic-level defect sensitivity.
- Plating Systems:Electroplating modules for copper interconnect deposition require specialized contamination control distinct from cleaning platforms.
- Dry Etchers:Plasma-based material removal systems complement wet cleaning in hybrid process sequences for 3D NAND fabrication.
Single wafer cleaners sit at the top of the volume ranking, with plating systems climbing the fastest as through-silicon via and advanced packaging applications expand.
Technology:
Cost structures stratify across technology tiers, with premium chemical cleaning commanding the highest equipment margins while spin clean platforms compete on throughput-per-square-meter metrics.
- Chemical Cleaning:Proprietary chemistries including sulfuric peroxide mixtures and dilute hydrofluoric acid solutions remove metallic and organic contaminants through controlled redox reactions. Photoresist stripping and post-etch residue removal in EUV lithography fabs drive concentrated demand from Taiwan and South Korea.
- Spin Clean Technology:Centrifugal force combined with precision dispense nozzles enables rapid drying and reduced chemical consumption. High-volume logic foundries prioritize these systems as wafer-per-hour throughput targets intensify for sub-5nm production ramps.
- Ultrasonic Cleaning:Megasonic frequency agitation dislodges sub-micron particles without surface damage.
- DI Water Rinse:Deionized water cascades remove residual chemistries prior to drying steps.
Chemical cleaning maintains the largest installed base, though spin clean technology is expanding most quickly as foundry capital expenditure cycles synchronize with node migration timelines.
End User:
Customer type determines procurement scale and qualification complexity, with semiconductor manufacturers negotiating multi-year framework agreements while research laboratories purchase through fragmented tender processes.
- Semiconductor Manufacturers:Integrated device manufacturers and pure-play foundries operate the most demanding specifications, requiring closed-loop metrology integration and predictive maintenance architectures. Taiwan Semiconductor Manufacturing Company and Samsung Electronics anchor regional demand clusters.
- MEMS Fabricators:Microelectromechanical systems producers process specialized substrates with relaxed particle requirements compared to CMOS logic.
- Research Laboratories:Academic and government facilities prioritize flexibility over throughput for process development applications.
- Solar Cell Producers:Photovoltaic manufacturers employ wet cleaning for silicon wafer texturing and emitter formation.
Semiconductor manufacturers dominate capital deployment, with MEMS fabricators gaining share fastest as automotive sensor and RF filter applications multiply.
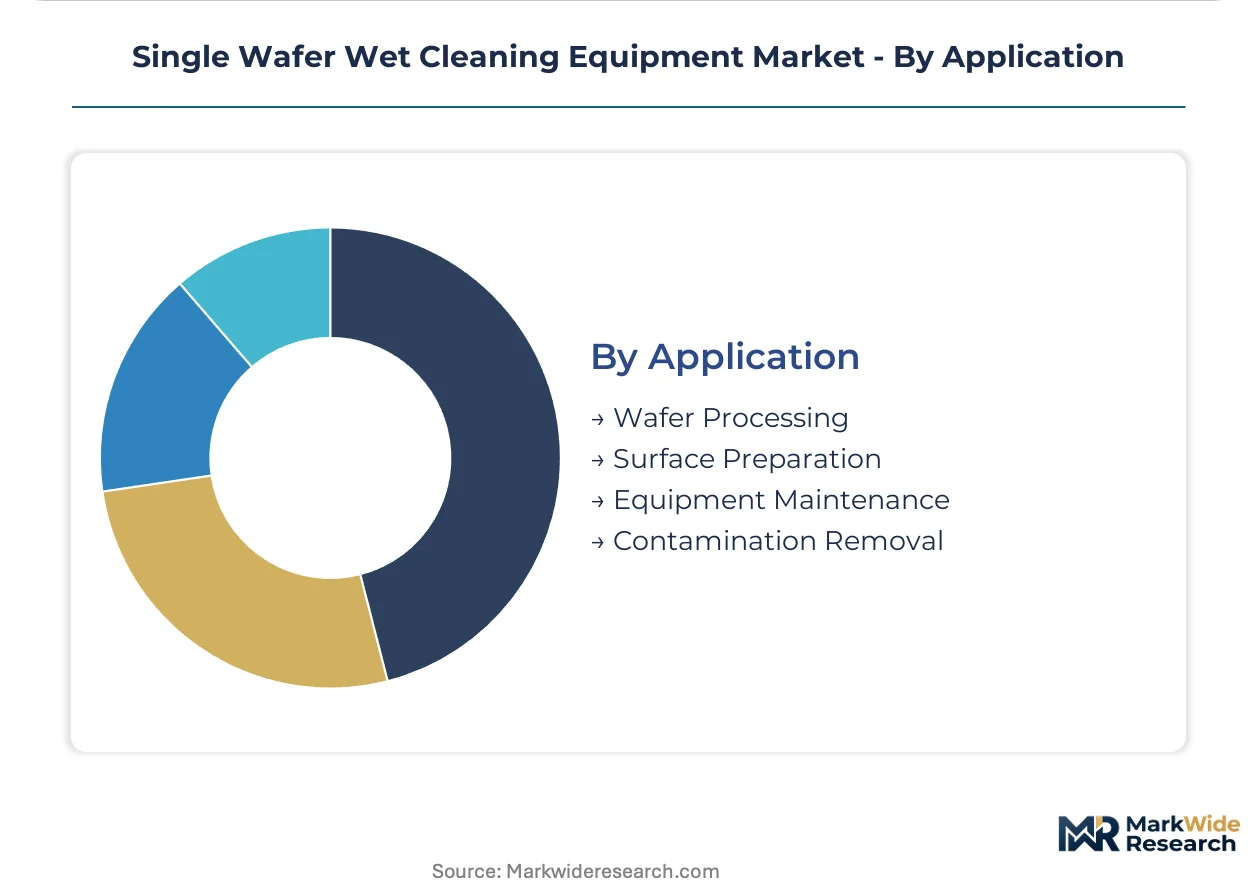
Application:
Application maturity varies across the fabrication sequence, with front-end wafer processing representing entrenched demand and equipment maintenance emerging as a services revenue expansion vector.
- Wafer Processing:Critical surface preparation steps preceding deposition, lithography, and etch operations require sequential cleaning modules integrated into cluster tools. Advanced packaging fabs processing 300mm wafers for chiplets and heterogeneous integration are extending equipment utilization into back-end processes.
- Contamination Removal:Targeted elimination of particulate, metallic, and organic defects drives replacement cycles as ISO 14644-1 classifications tighten.
- Surface Preparation:Native oxide removal and hydrophobicity tuning precede high-k dielectric deposition.
- Equipment Maintenance:Chamber cleaning and preventive maintenance applications extend system lifetime and reduce unplanned downtime.
Wafer processing commands the deepest equipment penetration, with contamination removal applications expanding most steeply as yield sensitivity intensifies at each node transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting wet cleaning equipment procurement toward jurisdictions with streamlined environmental permitting and concentrated subsidy programs. Taiwan, South Korea, and mainland China maintain cost-of-compliance advantages through integrated chemical supply chains and expedited fab construction timelines.
Taiwan
Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation are expanding 3nm and 2nm production capacity in Tainan and Hsinchu Science Parks. The island's EPA enforces effluent discharge standards that align with ISO 14644-1 Class 1 requirements, accelerating equipment replacement cycles. Tainan's Southern Taiwan Science Park hosts the most advanced single wafer cleaning installations serving gate-all-around transistor ramp-ups.
South Korea
Samsung Electronics and SK Hynix are stacking 3D NAND beyond 300 layers and advancing 2nm logic process development. METI-equivalent Korean industrial policy channels tax credits toward domestic equipment localization under the K-Semiconductor Belt initiative. Pyeongtaek and Yongin semiconductor clusters concentrate demand for hybrid wet-dry cleaning sequences in high-aspect-ratio memory fabrication.
China
Domestic foundry buildouts under the 14th Five-Year Plan are generating procurement volume for import-substitute wet processing platforms. MIIT oversees equipment qualification protocols that favor local assembly and service capabilities. Shanghai's Lingang New Area and Beijing's Zhongguancun Science Park are emerging as concentrated demand nodes for 28nm and 14nm production lines.
United States
Intel's Ohio and Arizona fab investments are reshoring advanced logic manufacturing with CHIPS Act funding support. EPA effluent regulations constrain wet bench chemical formulations, driving closed-loop recycling module adoption. Phoenix's semiconductor corridor and Columbus's New Albany mega-site represent emerging equipment deployment centers for sub-7nm production.
Japan
Tokyo Electron and SCREEN Holdings anchor domestic supply chains serving global memory and logic customers. METI's semiconductor equipment subsidy programs under the Economic Security Promotion Act strengthen local manufacturing ecosystems. Kyushu's Kumamoto Prefecture and Hiroshima Prefecture concentrate specialized chemical delivery system production for export markets.
Single Wafer Wet Cleaning Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as foundry capital expenditure cycles synchronize with node migration timelines. The vendor base concentrates among integrated front-end equipment conglomerates and specialized wet processing specialists, creating a tiered structure with distinct qualification barriers. Two strategic archetypes prevail: diversified platform suppliers leveraging installed base relationships, and focused wet cleaning specialists competing on chemical delivery precision. M&A activity and geographic expansion represent the dominant competitive moves, with players acquiring regional service capabilities and local chemical formulation expertise.
Among diversified equipment conglomerates, Applied Materials, Tokyo Electron, and Lam Research exemplify archetypes spanning the competitive spectrum. Applied Materials occupies a position reflecting front-end processing breadth and foundry contract scale. Tokyo Electron represents precision chemical architecture specialization with proprietary contamination control systems. Lam Research sits within the hybrid process integration tier, extending dry etch expertise into wet-dry cleaning sequences. These three anchors demonstrate how competitive positioning stratifies across platform breadth, chemical delivery precision, and process sequence integration capabilities.
| Leading Market Players |
|---|
| Applied Materials |
| Tokyo Electron |
| Lam Research |
| SCREEN Holdings |
| Hitachi High-Tech |
| SEMES |
| Shibaura Mechatronics |
| Veeco Instruments |
| ACM Research |
| Others |
Pricing and Supply Chain Analysis
EPA effluent discharge mandates and EU Green Deal circular economy targets gate qualified supply access and premium-tier pricing power, restricting system deployments to vendors with closed-loop chemical recycling architectures and ISO 14644-1 Class 1 certification pathways.
Pricing Analysis
Direct-to-foundry contracts compress distributor margins to single-digit percentages while spare parts and field service contracts unbundle as separate revenue streams. Three-tier pricing structure across sub-7nm certified, trailing-edge qualified, and research-grade equipment levels separates particle performance thresholds. Cost compression in trailing-edge segments intensifies because Chinese domestic fab buildouts prioritize import-substitute platforms. Research laboratories exhibit highest price sensitivity; Taiwan's leading foundries demonstrate least sensitivity due to yield-loss economics at advanced nodes.
Supply Chain Analysis
China's domestic-content mandates under MIIT equipment qualification protocols are reshaping sourcing patterns for regional foundry projects. High-purity fluorinated solvent production concentrates in Japan and Germany, while precision dispense nozzle manufacturing anchors in South Korea and Taiwan. Supply chain risk centers on single-source vulnerability for sub-0.1 particle-per-wafer metrology integration components. Distribution runs through semiconductor equipment buying consortiums that negotiate multi-year framework agreements locking spare parts pricing and response time guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with node migration timelines at 3nm and below driving replacement cycle regularity that insulates revenue streams from cyclical downturns.
For Market Incumbents: Deepen proprietary chemical delivery architecture investments to defend against emerging Chinese equipment suppliers capturing domestic fab share. Prioritize backward integration into high-purity solvent formulation capabilities to offset Japanese and German chemical conglomerate allocation constraints. Expand field service density in India's emerging semiconductor corridors under PLI scheme incentives. For New Entrants and Emerging Players: Compound semiconductor fabricators processing silicon carbide for electric vehicle power electronics represent an underserved buyer archetype with relaxed qualification timelines versus advanced logic foundries. Photonics manufacturing clusters in North America and Europe offer white-space entry points with lower capital barriers. Pursue collaborative R&D partnerships with German specialty chemical producers navigating REACH reformulation deadlines. For Investors and Strategic Acquirers: Valuations sit cheapest among wet processing specialists with captive chemical delivery IP and established foundry qualification records. Five-to-ten year viability hinges on gate-all-around transistor architecture adoption rates displacing legacy finFET cleaning protocols. Monitor EPA effluent regulation tightening as inflection indicator for closed-loop recycling module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Chemical Recycling Module Integration | EPA discharge constraints and EU Green Deal targets compel reclamation architecture adoption across Taiwan and South Korea fabs. |
| Domestic Equipment Localization Partnership | China's MIIT qualification protocols favor local assembly capabilities for 14th Five-Year Plan foundry buildouts. |
| Compound Semiconductor Platform Development | Silicon carbide power electronics expansion creates equipment demand outside saturated advanced logic markets. |
| Multi-Year Service Contract Unbundling | Taiwanese foundry consortiums negotiate spare parts pricing and response time guarantees separately from system purchases. |
| Alternative Surfactant Chemistry Validation | REACH per- and polyfluoroalkyl substance restrictions force collaborative R&D with German specialty chemical producers. |
Research Methodology
Multiple input streams — equipment supplier technical directors, foundry process integration engineers, specialty chemical procurement leads, and cleanroom certification auditors — were reconciled against customs trade data, SEMI industry association reports, SEC equipment manufacturer filings, and regional environmental regulator discharge records. Bottom-up unit deployment estimates across Taiwan, South Korea, China, and North American fab projects were cross-validated with top-down capital expenditure triangulation from foundry operator disclosures.
Historical capacity expansion patterns were cross-referenced against panel input from equipment OEM sales executives and foundry procurement directors. Segmentation dimensions modeled include product architecture, cleaning technology type, process node tier, end-user category, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating node migration timelines, equipment replacement cycles, and subsidy program phasing across the projection horizon. Forecast inputs incorporated ISO 14644-1 classification tightening trajectories and export control framework evolution.
Underlying measurement precision varies by segment; sub-7nm foundry deployments carry tighter precision than research laboratory installations due to disclosed capital expenditure visibility. Forecasts embed assumptions regarding gate-all-around transistor ramp schedules and REACH chemistry reformulation compliance timelines. Unplanned export control expansion or sudden fluorinated solvent supply disruptions could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
I-Line Lithography Market