
 CMP Polishing Machine Market | 2026-2036
CMP Polishing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
CMP Polishing Machine Market Insights
Buyer concentration among foundries is restructuring supply relationships across the CMP polishing machine landscape. Applied Materials Inc. leverages its installed base in 300mm wafer processing to sustain recurring revenue from consumables and retrofits. Ebara Corporation anchors its position through proprietary slurry delivery architectures that reduce defect density in sub-7nm nodes. Disco Corporation competes aggressively in back-grinding and dicing adjacent workflows, extending its relevance into compound semiconductor polishing.
CMP polishing machines execute precision material removal using chemically reactive slurries and polyurethane pads to achieve atomic-level planarization on silicon wafers and hard substrates. Multi-head configurations dominate high-volume logic foundries where throughput per square meter of cleanroom space determines capital efficiency. Electrochemical-mechanical hybrid technology captures the fastest expansion trajectory as chipmakers pursue damage-free polishing of fragile III-V materials for power electronics. Research institutes represent a concentrated margin pool due to low price sensitivity and demand for configurable platforms that accommodate experimental chemistries.
EPA hazardous waste rules and REACH chemical authorization in Europe constrain slurry formulation choices, directly shaping equipment design requirements for closed-loop processing. Japan's METI semiconductor revitalization framework and South Korea's K-Semiconductor Belt subsidies redirect regional demand toward domestically sourced CMP platforms. Stakeholders must monitor how export control alignments between the US Bureau of Industry and Security and allied regulators reshape equipment eligibility for advanced node fabs in China.
Market Dynamics
Advanced node migration at sub-5nm geometries is compressing planarization tolerance windows below 0.5nm, forcing simultaneous retooling of slurry chemistry, pad porosity, and endpoint detection systems across foundry fleets.
Growth Catalysts
- Sub-7nm Logic Ramp:TSMC and Samsung Foundry are expanding 300mm capacity for 3nm gate-all-around transistors, each new fab requiring 40-60 CMP heads per line.
- Japan's METI Semiconductor Revitalization:Subsidies under this framework are redirecting capital expenditure toward domestically sourced CMP platforms for silicon carbide power device manufacturing.
- III-V Material Integration:Gallium nitride and indium phosphide wafers for RF and photonics applications demand electrochemical-mechanical hybrid polishers that prevent crystalline damage.
Market Restraints
- Slurry Input Concentration:Four chemical suppliers control 70% of ceria and silica abrasive formulations, creating vulnerability to rare earth export restrictions from China.
- Cleanroom Space Economics:Multi-head CMP tools occupy 40% more floor area per wafer-start than single-head legacy systems, constraining retrofit options at mature 200mm facilities.
- EPA Hazardous Waste Rules:Stricter effluent limits on copper and tungsten particulates are extending permitting timelines for new installations by 8-14 months.
Strategic Opportunities
- Compound Semiconductor Adjacencies:Silicon carbide substrate polishing for electric vehicle inverters remains underserved by incumbent silicon-optimized equipment architectures.
- Research Institute Configurability:National laboratories and university cleanrooms seek modular platforms accommodating experimental chemistries at price premiums 35-50% above production tools.
- South Korea K-Semiconductor Belt:Government incentives for domestic equipment sourcing are creating localized demand clusters around Pyeongtaek and Yongin.
Industry Challenges
- Process Control Talent Scarcity:Endpoint detection algorithm development requires rare combinations of materials science and machine learning expertise concentrated at a handful of institutions.
- Legacy System Integration:Retrofitting 200mm fabs with advanced slurry recirculation conflicts with original equipment architectures from the late 1990s.
- Cross-Border Certification Divergence:CE marking under EU machinery directives and SEMI S2 safety standards are diverging on electrical grounding specifications, forcing dual-validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMP Polishing Machine Market |
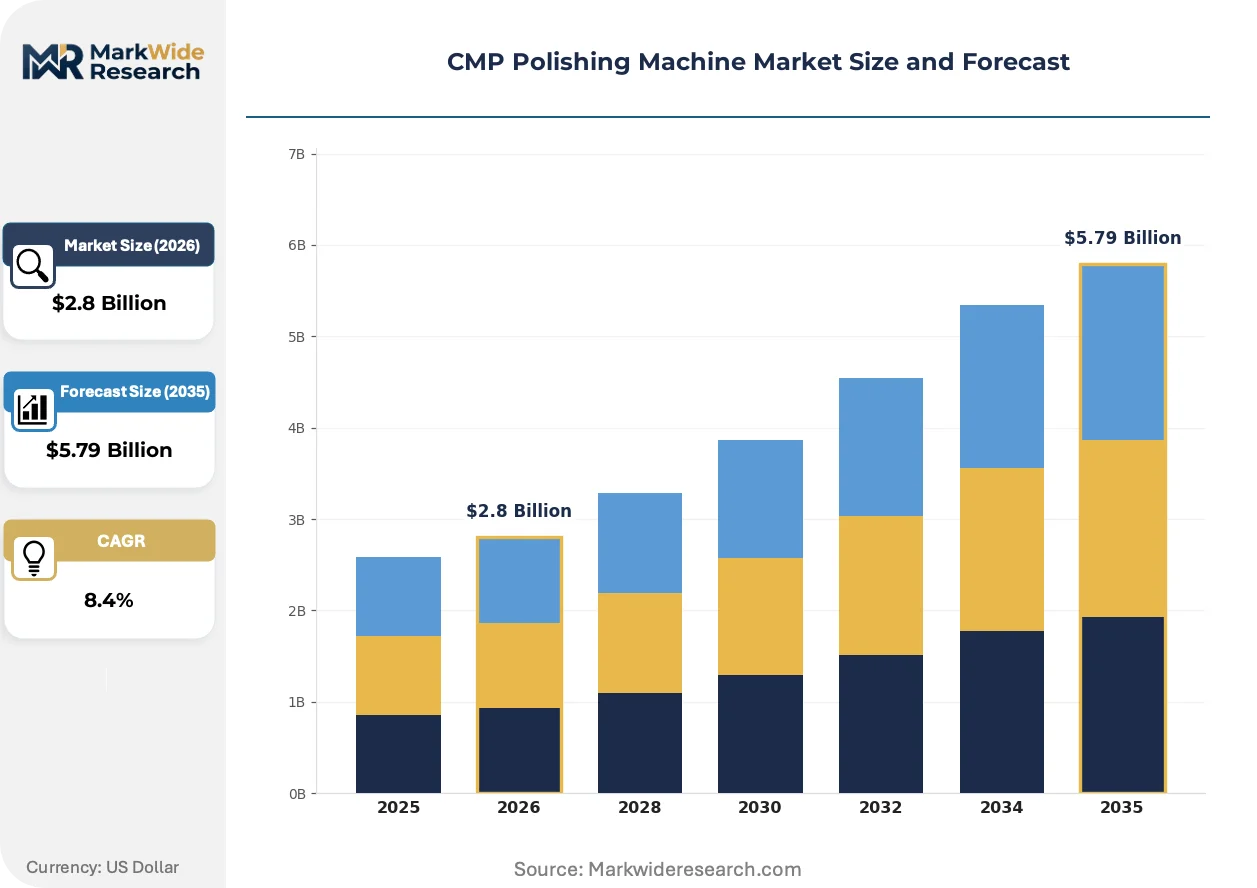
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Head, Multi-Head, Rotary, Linear, Hybrid Technology: Electrochemical, Mechanical, Chemical, Plasma, Laser Application: Semiconductor Wafers, LED Substrates, Solar Cells, Hard Disk Drives, MEMS Devices End User: Integrated Device Manufacturers, Foundries, Research Institutes, Electronics Manufacturers |
| Companies Covered | Applied Materials Inc., Ebara Corporation, Entegris Inc., DuPont de Nemours Inc., Lapmaster Wolters GmbH, CMC Materials Inc., Revasum Inc., Okamoto Corporation, Disco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMP Polishing Machine Market Trends and Innovations
Real-time process control architectures are displacing fixed-parameter recipes as the primary source of yield differentiation in high-mix manufacturing environments.
Machine vision-based endpoint detection is automating the transition from time-based to feature-complete polish termination. Logic foundries with 20,000+ wafer-starts per month are deploying these systems across 90% of new tool purchases. This shift is automating the elimination of over-polish margin that previously consumed 8-12% of usable die area.
REACH chemical authorization in Europe is restricting perfluorinated surfactants in tungsten slurry formulations. Equipment vendors are redesigning delivery systems to accommodate water-based alternatives with higher viscosity and particle settling rates. Front-end-of-line processes at Dresden and Leuven fabs are experiencing 15-20% longer polish times as formulation stability is revalidated.
Consolidated procurement through equipment-lessor intermediaries is displacing direct manufacturer relationships at mid-scale memory producers. These lessors bundle refurbishment, consumables, and uptime guarantees into per-wafer charges. This model is most visible among Chinese NAND flash manufacturers seeking to preserve balance sheet flexibility during capacity cycle troughs.
CMP Polishing Machine Market Segmentation
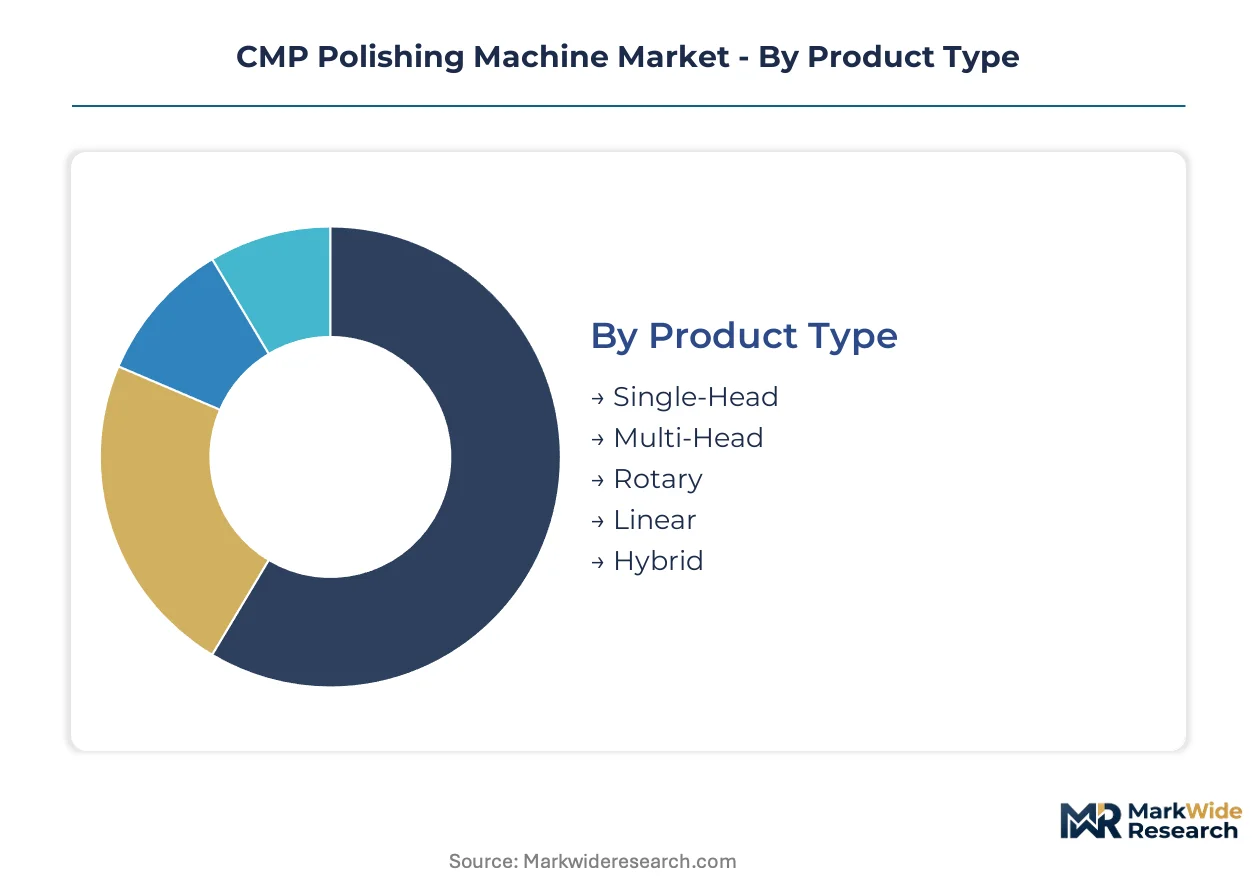
Segmentation in CMP polishing machines reveals how planarization requirements diverge across substrate materials, manufacturing scales, and regulatory environments. Equipment specifications vary dramatically between high-volume logic foundries and experimental research platforms.
Product Type:
Volume throughput and capital efficiency per square meter of cleanroom space define the product type hierarchy.
- Multi-Head:Simultaneous processing of multiple wafers through independent polishing heads maximizes throughput in 300mm logic foundries. TSMC and Samsung Foundry deploy these configurations exclusively for sub-7nm node ramp, where floor space constraints limit single-tool expansion.
- Hybrid:Electrochemical-mechanical architectures combine chemical dissolution with mechanical abrasion for damage-free polishing of fragile III-V compounds. Demand concentrates in silicon carbide substrate manufacturing for electric vehicle power electronics, where crystalline integrity determines device performance.
- Single-Head:Legacy 200mm installations at mature analog fabs continue operating these systems for mixed-signal and power management chips.
- Rotary:Conventional turntable designs persist in LED substrate polishing where cost sensitivity outweighs throughput optimization.
- Linear:Belt-driven linear polishers serve specialized MEMS applications requiring uniform pressure distribution across non-circular die.
Mature deployment sits with Single-Head systems. Newer deployment is concentrated in Hybrid configurations.
Technology:
Process-material compatibility determines technology selection, with chemical stability and substrate fragility as decisive constraints.
- Mechanical:Pure abrasive polishing dominates legacy silicon wafer planarization where established pad and slurry combinations deliver predictable removal rates. Mature 200mm fabs in Japan's Kumamoto region continue relying on these systems for analog and discrete device production.
- Electrochemical:Anodic dissolution combined with minimal mechanical contact prevents subsurface damage in gallium nitride and indium phosphide wafers. RF component manufacturers in the US and Germany are expanding capacity for these systems to serve 5G base station and radar module demand.
- Chemical:Slurry-dominated removal mechanisms serve standard silicon dioxide and tungsten polishing in memory fabs.
- Plasma:Dry etch-based planarization addresses extreme topography in 3D NAND stack processing.
- Laser:Thermal ablation techniques handle exotic substrates including diamond and sapphire for thermal management applications.
Mechanical technology anchors established silicon processing. Electrochemical methods are climbing the fastest in compound semiconductor integration.
Application:
Substrate material properties and device architecture complexity create distinct equipment requirements across application segments.
- Semiconductor Wafers:Silicon planarization for logic and memory devices demands the tightest tolerance control, with surface roughness specifications below 0.5nm at sub-5nm nodes. Taiwan's Hsinchu Science Park corridor concentrates the densest deployment of advanced CMP capacity worldwide.
- LED Substrates:Sapphire and silicon carbide wafer polishing for solid-state lighting operates at relaxed tolerances but requires specialized pad conditioning for hard, brittle materials. Chinese manufacturers in Xiamen and Nanchang dominate procurement for these systems.
- Solar Cells:Silicon wafer texturing and edge isolation use simplified CMP variants with lower consumables intensity.
- Hard Disk Drives:Aluminum and glass substrate polishing for magnetic storage media requires exceptional flatness for flying height control.
- MEMS Devices:Non-planar structures and released mechanical features demand selective polishing with protected active areas.
Semiconductor wafers represent the premium tier by equipment value. LED substrates are gaining share fastest as automotive lighting and display backplane demand expands.
End User:
Procurement scale and technical sophistication create divergent purchasing patterns across end user categories.
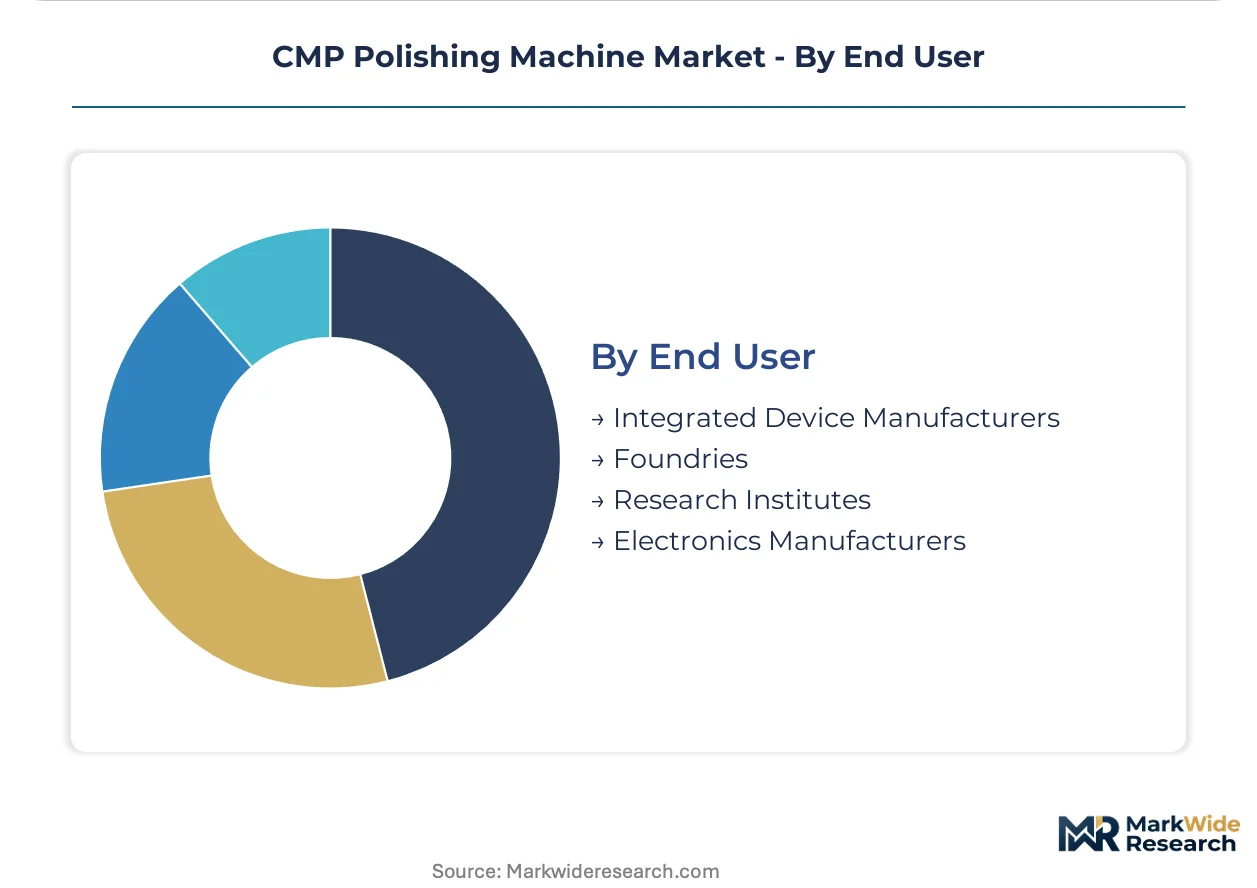
- Foundries:Merchant logic and memory manufacturers operate the largest installed bases, with fleet standardization reducing spare parts complexity. TSMC, Samsung Foundry, and Intel Foundry Services negotiate multi-year framework agreements bundling equipment, consumables, and service.
- Research Institutes:National laboratories and university cleanrooms prioritize configurability over throughput, accepting 35-50% price premiums for modular platforms accommodating experimental chemistries. The US Department of Energy's five Nanoscale Science Research Centers represent concentrated demand for these systems.
- Integrated Device Manufacturers:Captive fabs at analog and power semiconductor specialists maintain smaller, longer-lived equipment fleets.
- Electronics Manufacturers:Substrate and component suppliers outside traditional semiconductor verticals represent fragmented, price-sensitive demand.
Integrated Device Manufacturers represent the most mature procurement relationships. Research Institutes are expanding fastest as government semiconductor initiatives fund new cleanroom construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park corridor concentrates the densest deployment of advanced CMP capacity worldwide, with procurement patterns at TSMC and UMC restructuring supplier relationships across the equipment landscape.
Taiwan
TSMC's 3nm gate-all-around ramp and UMC's specialty node expansion drive multi-head CMP procurement at 40-60 heads per new fab line. The National Development Council's semiconductor initiative subsidizes domestic equipment sourcing. Hsinchu Science Park hosts the world's most concentrated advanced planarization capacity, with suppliers co-locating service centers to minimize downtime.
South Korea
Samsung Foundry's Pyeongtaek complex and SK Hynix's Yongin memory fabs anchor demand for high-throughput configurations. The K-Semiconductor Belt subsidies redirect capital expenditure toward domestically sourced CMP platforms. Seoul Capital Area cleanrooms are expanding electrochemical-mechanical hybrid capacity for silicon carbide power device manufacturing.
Japan
Kumamoto's mature analog fabs and Nagoya's automotive semiconductor clusters sustain legacy 200mm system demand. METI's semiconductor revitalization framework subsidizes silicon carbide polishing equipment for power electronics. Kyoto-Osaka corridor manufacturers are integrating domestic slurry delivery architectures into next-generation tool designs.
United States
Intel's Arizona and Oregon fabs plus emerging foundry capacity in Ohio drive advanced node equipment procurement. EPA hazardous waste rules on copper and tungsten particulates extend new installation permitting timelines by 8-14 months. Department of Energy Nanoscale Science Research Centers represent concentrated demand for configurable research-grade platforms.
China
SMIC and Hua Hong Semiconductor expand 28nm and above capacity despite export control constraints on advanced node tools. The country's national semiconductor regulator enforces domestic equipment procurement quotas under the integrated circuit industry promotion law. Shanghai's Zhangjiang Hi-Tech Park clusters the most intensive CMP tool deployment for mature node logic and memory production.
CMP Polishing Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue compound semiconductor adjacencies and research institute configurability. The vendor base stratifies across three maturity tiers: integrated process equipment conglomerates with installed base leverage, specialized planarization technology developers, and regional fabrication equipment suppliers. Dominant competitive moves include backward integration into consumables and slurry formulation partnerships, plus geographic co-location of service infrastructure near high-volume fab clusters.
Among Japanese precision equipment specialists, Ebara Corporation and Disco Corporation exemplify archetype differentiation through proprietary architectures and adjacent workflow extension. Applied Materials Inc. anchors the integrated tier with recurring revenue streams from 300mm wafer processing installed bases. Revasum Inc. occupies a position within the specialized tier, representing equipment developers focused on hard substrate and compound semiconductor applications.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| Ebara Corporation |
| Entegris Inc. |
| DuPont de Nemours Inc. |
| Lapmaster Wolters GmbH |
| CMC Materials Inc. |
| Revasum Inc. |
| Okamoto Corporation |
| Disco Corporation |
| Others |
Pricing and Supply Chain Analysis
Foundry procurement concentration at TSMC, Samsung, and Intel Foundry Services anchors contract-based long-term offtake agreements that bundle equipment, consumables, and service into per-wafer charges. This buyer archetype's consolidated purchasing power compresses margins for standard-tier multi-head systems while preserving premium pricing for hybrid electrochemical-mechanical platforms serving compound semiconductor applications.
Pricing Analysis
High-volume logic foundries negotiate volume scale discounts that strip 15-25% from list prices for multi-head configurations, while research institutes absorb 35-50% premiums for modular configurability. Three-tier pricing structure across premium hybrid systems, standard multi-head tools, and economy single-head legacy equipment reflects certification grade differentiation under SEMI S2 and CE marking requirements. Cost compression in standard silicon-optimized equipment intensifies as Chinese NAND flash manufacturers shift toward equipment-lessor intermediaries. Memory producers exhibit highest price sensitivity due to cyclical capacity investments, while national laboratories demonstrate lowest sensitivity for experimental chemistry platforms.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale buyer demand for 300mm advanced node tools, while regional fabrication equipment suppliers serve research institute and IDM segments through distributor networks. Component manufacturing concentrates in Japan for precision polishing heads, South Korea for endpoint detection electronics, and the USA for process control software. Critical dependencies include ceria and silica abrasive formulations from concentrated chemical suppliers, polyurethane pad substrates, and rare earth elements for slurry stabilization. Single-source vulnerability in abrasive chemical supply creates exposure to export restriction shocks from Chinese rare earth processing. Distribution runs through equipment-lessor intermediaries at mid-scale memory producers seeking balance sheet flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EPA hazardous waste rules on copper and tungsten particulates create barrier-to-entry moats for vendors with validated closed-loop processing architectures.
For Market Incumbents: Extend service infrastructure co-location around Hsinchu Science Park and Pyeongtaek fab clusters to minimize downtime and lock in consumables recurring revenue. Deepen backward integration into proprietary slurry delivery architectures that reduce defect density, defending against emerging entrants targeting compound semiconductor adjacencies with electrochemical-mechanical hybrid designs. For New Entrants and Emerging Players: Launch via research institute direct sales channels where configurability premiums and low price sensitivity offset R&D amortization burdens. Target silicon carbide substrate polishing for electric vehicle power electronics as the most penetrable white space underserved by silicon-optimized incumbent architectures. Position around modular platforms accommodating experimental chemistries at national laboratories. For Investors and Strategic Acquirers: The window for entry favors specialized planarization technology developers with validated III-V material processing capabilities over integrated process equipment conglomerates facing installed base saturation. Long-term viability hinges on exposure to silicon carbide and gallium nitride ramp timelines rather than mature silicon node replacement cycles. Monitor K-Semiconductor Belt and METI subsidy disbursement velocity as inflection indicators for regional demand reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slurry Formulation | Captive supply of ceria-based abrasives insulates against Chinese export restriction exposure. |
| Service Center Co-location | Proximity to TSMC Hsinchu and Samsung Pyeongtaek clusters reduces mean-time-to-repair metrics. |
| Hybrid Platform Development | Electrochemical-mechanical architectures address silicon carbide power electronics demand from Tesla and BYD. |
| Research Institute Direct Channel | Department of Energy Nanoscale Science Research Centers represent concentrated margin pool with 35-50% pricing premiums. |
| CE Marking and SEMI S2 Dual Validation | Compliance with diverging EU machinery directives and safety standards enables cross-border equipment eligibility. |
Research Methodology
Document review covered SEC 10-K filings from Applied Materials and Ebara, equipment procurement disclosures from TSMC and Samsung, EPA hazardous waste rule dockets, and METI subsidy program announcements, complemented by interviews with fab operations directors, slurry formulation chemists, and semiconductor equipment procurement managers. Primary fieldwork with cleanroom engineering heads at Hsinchu Science Park and Yongin memory complexes validated secondary data on throughput specifications and downtime costs. Trade customs data from Japan's METI and South Korea's KITA anchored import-export flow analysis. Bottom-up wafer-start projections and top-down equipment capex triangulation reconciled market sizing.
Segmentation outputs across product type, technology, application, and end user dimensions were modeled across the projection horizon with regional regulatory clusters as cross-cutting variables. CAGRs were derived from equipment shipment volumes, fab capacity expansion announcements, and consumables intensity per wafer-start. Forecast inputs incorporated III-V material integration timelines, REACH chemical authorization impacts on slurry reformulation, and export control alignment effects on equipment eligibility for Chinese fabs.
Export control escalation, REACH chemical restriction expansion, and rare earth supply disruption are the dominant revision risks that could compress or accelerate equipment procurement timelines. Forecasts reflect assumptions around subsidy program continuity and node migration schedules that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Co-Packaged Optics Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Photointerrupter Market
Optical Components
North America Optical Film Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Objective Lens Market
Optical Components
Optical Isolator Market
Optical Components
Laser Module Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Optical Lens Edger Market
Optical Components
Photomask Pellicle Market
Optical Components
Coherent Optical Equipment Market