
 Machine Vision Light Source Market | 2026-2036
Machine Vision Light Source Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Vision Light Source Market Foresight
LED phosphor formulations are consolidating around ceramic-substrate architectures that cut thermal drift by half versus legacy epoxy packages. CCS Inc leverages in-house LED die bonding to control beam uniformity for medical device inspection. Advanced Illumination anchors its competitive position through modular bar-light platforms that scale from 50 mm to 2 meters without optical recalibration. Smart Vision Lights differentiates via IP69K-rated washdown enclosures that penetrate food processing installations.
Machine vision light sources are engineered photonic subsystems that deliver controlled spectral output, typically spanning 365 nm ultraviolet through 940 nm near-infrared, with luminous intensity stability below one percent deviation across operating temperature ranges. Their primary purpose is to eliminate ambient interference and amplify feature contrast so that area-scan and line-scan cameras can resolve dimensional tolerances to the micron level. LED illumination now leads the product type landscape due to instant on-off switching and programmable intensity, while structured light technology captures the fastest expansion as three-dimensional bin-picking and depth-mapping applications multiply in logistics and robotic assembly. Strobe backlighting retains entrenched positions in high-speed bottle and vial inspection where motion blur must be frozen at production line velocities.
The FDA enforces 21 CFR Part 820 quality system regulations on vision systems deployed in pharmaceutical packaging verification, compelling light source vendors to document wavelength stability and irradiance repeatability. The EU RoHS directive and REACH framework restrict cadmium-based quantum dot phosphors and certain halogenated flame retardants in luminaire housings, redirecting material selection toward aluminum-nitride substrates and bio-based polycarbonates. Basler AG and Omron Corporation navigate these compliance layers by pre-certifying modular light controllers for CE marking and FDA-recognized consensus standards. Stakeholders must now decide whether to absorb rising rare-earth phosphor costs or accelerate alternative dopant research before supply bottlenecks harden.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea now specify ceramic-substrate LED architectures that halve thermal drift, tightening procurement standards and compressing qualification timelines for legacy epoxy-package suppliers.
Growth Catalysts
- EU RoHS mercury restrictions:The directive bans mercury-content lighting in industrial equipment, forcing OEMs toward solid-state LED alternatives and expanding addressable market for compliant vendors.
- Wafer inspection intensity:Taiwan and South Korean semiconductor fabs demand sub-pixel illumination consistency for defect detection at 7nm nodes and below.
- Structured light adoption:Three-dimensional bin-picking and depth-mapping applications multiply in logistics corridors, driving fastest-expansion technology segment.
Market Restraints
- Rare-earth phosphor cost volatility:Neodymium and cerium supply concentrates in Chinese processing facilities, creating input price instability for high-CRI LED formulations.
- REACH substance restrictions:Cadmium-based quantum dot phosphors and certain halogenated flame retardants face phase-out timelines, forcing material requalification.
- Thermal management limits:Epoxy-substrate packages exhibit luminous intensity drift exceeding one percent across operating temperature ranges, disqualifying them from medical device applications.
Strategic Opportunities
- Food processing washdown specifications:IP69K-rated enclosures penetrate meat, dairy, and beverage inspection lines where high-pressure sanitation cycles degrade standard luminaires.
- Modular platform scaling:Bar-light architectures spanning 50 mm to 2 meters without optical recalibration address automotive and electronics assembly line variability.
- Pharmaceutical packaging verification:FDA 21 CFR Part 820 quality system regulations compel documented wavelength stability, creating certified-supplier preference windows.
Industry Challenges
- Optical engineer scarcity:Beam uniformity optimization and thermal-mechanical co-design require specialized expertise concentrated in Japanese and German research clusters.
- Multi-certification timelines:CE marking, FDA-recognized consensus standards, and emerging GB standards for China market entry extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Vision Light Source Market |
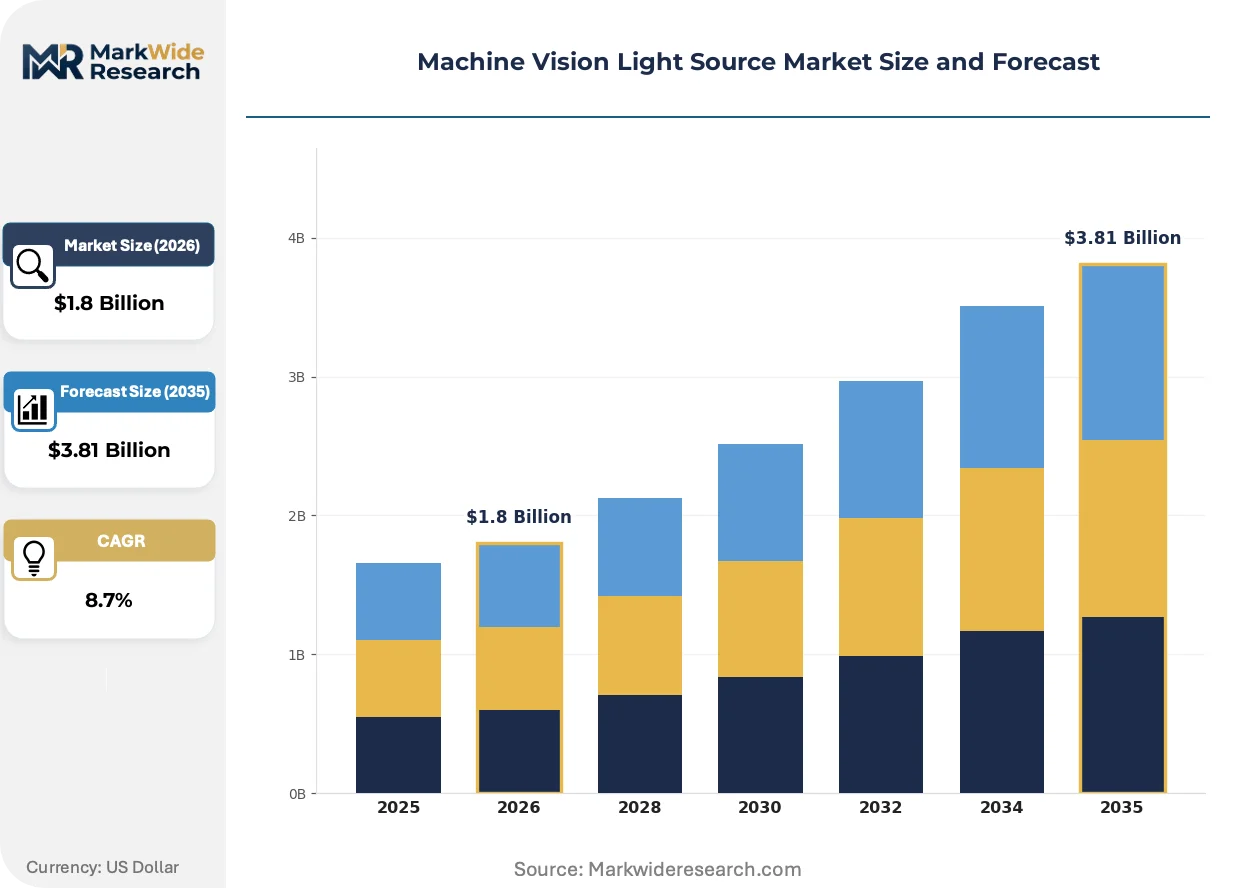
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser, Xenon, Fluorescent Technology: Illumination, Structured Light, Backlighting, Strobe Application: Quality Control, Object Detection, Barcode Reading, Surface Inspection End User: Manufacturing, Automotive, Electronics, Food Processing |
| Companies Covered | Cognex Corporation, Keyence Corporation, Omron Corporation, CCS Inc, Smart Vision Lights, Advanced Illumination, Spectrum Illumination, Basler AG, Banner Engineering Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Vision Light Source Market Shifts & Advancements
Photonic subsystem engineering is consolidating around programmable intensity control and spectral tunability, compressing hardware refresh cycles while expanding application reach into precision agriculture and autonomous inspection drones.
Structured light projection modules are integrating time-of-flight sensors and MEMS mirror arrays to enable real-time depth mapping at production line velocities. Automotive battery pack assembly lines in Germany and Michigan adopt these configurations for gap-and-flush verification. The technology is integrating previously separate illumination and sensing subsystems, reducing cell footprint by 40 percent.
REACH framework amendments tighten cadmium and lead thresholds in luminaire housings and driver electronics. European machine vision integrators now specify aluminum-nitride substrates and bio-based polycarbonates to preempt compliance deadlines. Medical device OEMs face the steepest requalification burden, as FDA-recognized consensus standards reference REACH substance lists for biocompatibility assessments.
Buyer preference is compressing toward pre-certified modular controllers that ship with documented wavelength stability and irradiance repeatability. Japanese electronics manufacturers now demand controller-light source bundles with unified warranty terms, displacing discrete component sourcing. South Korean semiconductor fabs lead this consolidation, specifying single-vendor accountability for sub-pixel performance guarantees.
Machine Vision Light Source Market Segmentation
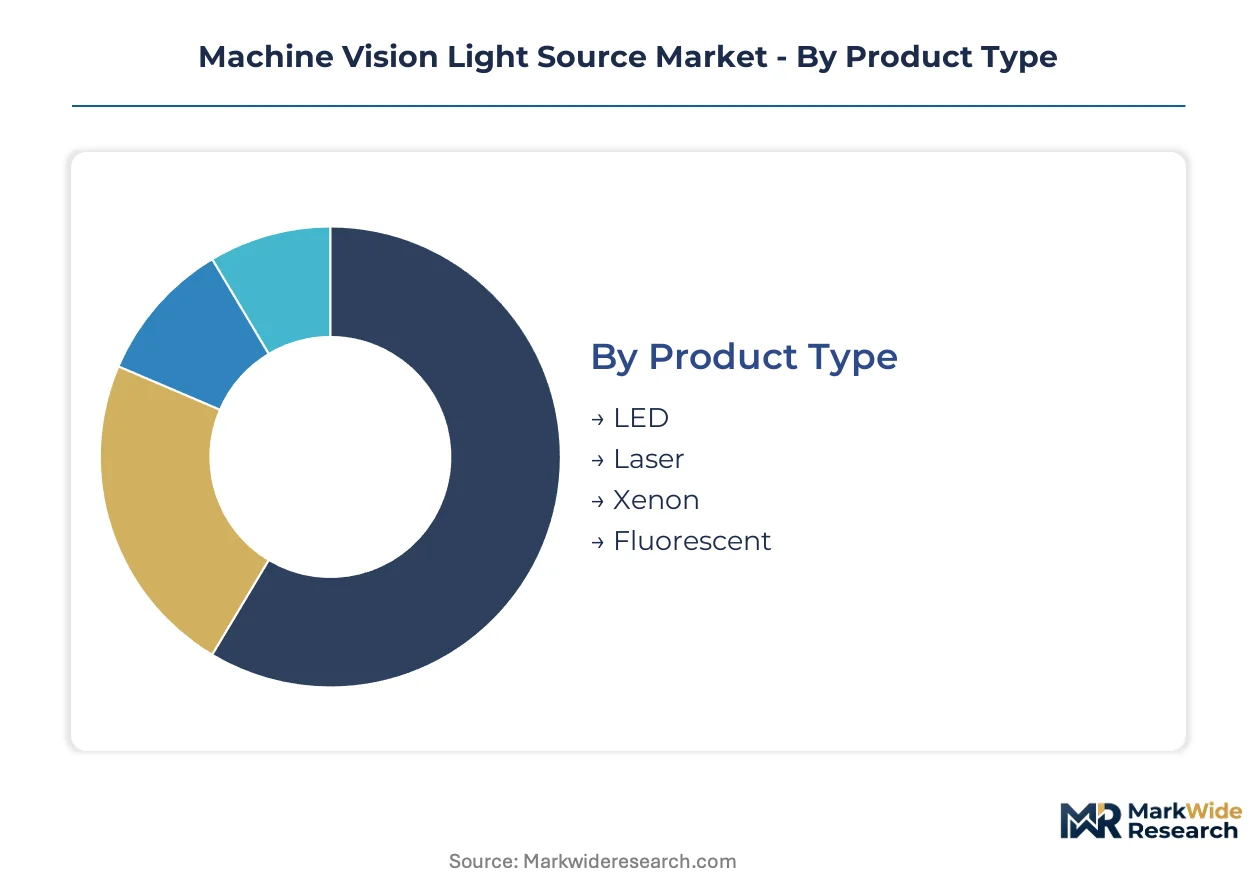
Machine vision light source segmentation reveals how illumination requirements fragment across integration depths, from standalone retrofit units to embedded photonic subsystems. Procurement patterns diverge sharply between fabs demanding sub-pixel uniformity and logistics operators prioritizing rapid deployment.
Product Type:
Integration depth separates retrofit-ready standalone units from embedded die-level solutions bound to camera modules.
- LED:Solid-state architectures with ceramic substrates cut thermal drift by half versus epoxy packages. Taiwan and South Korean semiconductor fabs now specify these for wafer inspection, tightening procurement standards for legacy suppliers.
- Laser:Coherent sources deliver precise wavelength selectivity for confocal microscopy and holographic inspection. Medical device OEMs in Germany and Japan drive qualification timelines for fiber-coupled diode arrays.
- Xenon:Broadband arc lamps retain niche positions in spectral imaging where continuous UV-Vis-NIR coverage matters. REACH mercury restrictions compress addressable market for industrial equipment.
- Fluorescent:Linear tube formats persist in legacy food processing lines where cost sensitivity outweighs efficiency gains. EU RoHS enforcement accelerates replacement cycles.
LED leads volumes today; laser is gaining share fastest.
Technology:
Cost tier stratification separates commodity illumination from premium structured light systems commanding three-to-five-fold price multiples.
- Illumination:Diffuse and directional LED arrays provide baseline contrast enhancement for area-scan cameras. Electronics assembly corridors in East Asia concentrate procurement for precision component placement verification.
- Structured Light:Pattern projection modules integrate MEMS mirror arrays and time-of-flight sensors for real-time depth mapping. Automotive battery pack lines in Germany and Michigan adopt these for gap-and-flush verification.
- Backlighting:High-uniformity panels sit behind transparent objects for dimensional measurement. High-speed bottle inspection lines rely on strobe-synchronized configurations to freeze motion blur.
- Strobe:Pulsed operation delivers microsecond-duration flashes that eliminate motion artifacts at production velocities. Pharmaceutical vial inspection demands irradiance repeatability documentation under FDA 21 CFR Part 820.
Illumination commands the largest installed base; structured light shows the steepest expansion trajectory.
Application:
Application maturity separates established quality protocols from emerging use cases where performance specifications remain fluid.
- Quality Control:Dimensional tolerance verification to micron precision requires luminous intensity stability below one percent deviation. Automotive stamping plants in Michigan and Bavaria specify modular bar-light platforms scaling from 50 mm to 2 meters.
- Object Detection:Feature recognition for robotic bin-picking drives demand for programmable spectral output. Logistics operators in Dutch and Belgian distribution hubs prioritize rapid deployment over optical recalibration.
- Barcode Reading:High-contrast illumination ensures readability of degraded or reflective labels. Retail distribution centers specify IP54-rated enclosures for warehouse environments.
- Surface Inspection:Defect detection on polished or textured substrates demands angled dark-field configurations. Semiconductor wafer fabs require sub-pixel consistency for 7nm node detection.
Quality control retains the largest revenue pool; object detection is expanding most quickly.
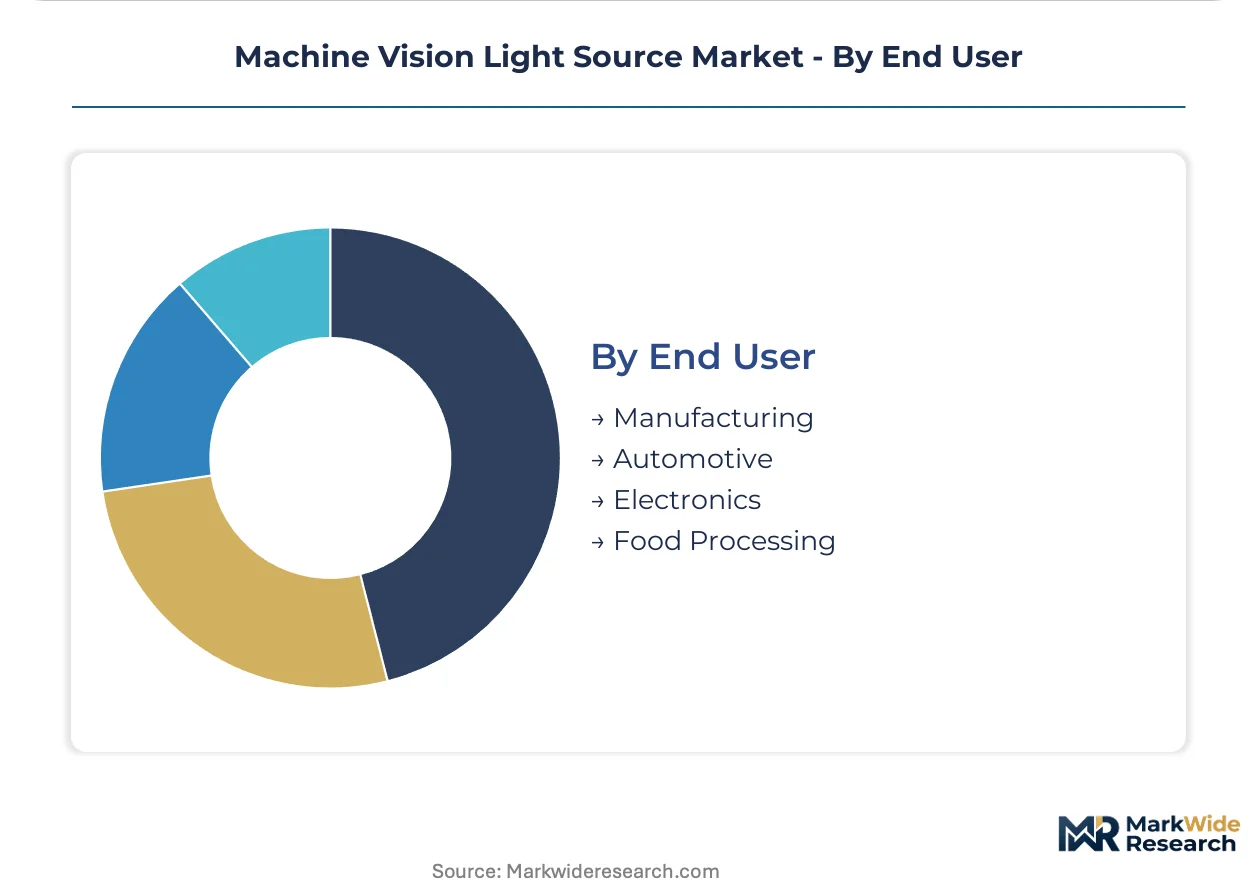
End User:
Customer type determines specification stringency, from FDA-regulated pharmaceutical packaging to cost-optimized commodity manufacturing.
- Manufacturing:General industrial automation spans discrete component assembly through final packaging verification. Mexican maquiladora electronics plants prioritize rapid commissioning over thermal performance optimization.
- Automotive:Battery pack assembly and paint surface inspection demand washdown-rated IP69K enclosures. German OEMs specify unified controller-light source bundles with single-vendor warranty terms.
- Electronics:Semiconductor and PCB inspection commands the tightest beam uniformity specifications. South Korean fabs lead consolidation toward single-vendor accountability for sub-pixel performance guarantees.
- Food Processing:High-pressure sanitation cycles degrade standard luminaires, driving IP69K penetration in meat and dairy inspection lines. USDA facility standards reference FDA-recognized consensus standards for equipment qualification.
Electronics manufacturing leads absolute demand; food processing shows the fastest certification-driven upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics manufacturing corridors generate the densest concentration of machine vision light source procurement, with Taiwan and South Korean semiconductor fabs setting the tightest beam uniformity specifications worldwide.
United States
FDA 21 CFR Part 820 regulations govern pharmaceutical packaging verification systems deployed across Michigan and New Jersey manufacturing clusters. The FDA enforces documented wavelength stability and irradiance repeatability for vision systems in drug labeling applications. Automotive battery pack assembly lines in Michigan adopt structured light configurations for gap-and-flush verification at production velocities.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify IP69K-rated washdown enclosures for paint surface inspection and battery assembly operations. REACH framework amendments tighten cadmium and lead thresholds in luminaire housings, redirecting material selection toward aluminum-nitride substrates. German integrators now demand pre-certified modular controllers with unified warranty terms from single vendors.
China
GB standards for machine vision equipment create compliance entry requirements for domestic and foreign suppliers serving Yangtze River Delta electronics corridors. The country's national standards body references REACH substance lists for biocompatibility assessments in medical device applications. Shenzhen and Suzhou manufacturing hubs concentrate procurement for precision component placement verification in PCB assembly.
South Korea
Semiconductor fabs in the Seoul Capital Area and Busan-Ulsan corridor specify ceramic-substrate LED architectures that halve thermal drift for wafer inspection at 7nm nodes. The Ministry of Food and Drug Safety enforces quality system regulations on vision systems deployed in pharmaceutical packaging. Samsung and SK Hynix facilities drive consolidation toward single-vendor accountability for sub-pixel performance guarantees.
Japan
METI industrial technology roadmaps prioritize photonic subsystem development for precision agriculture and autonomous inspection applications. Japanese electronics manufacturers in the Kanto and Kansai regions demand controller-light source bundles with unified warranty terms, displacing discrete component sourcing. Nagoya-area automotive suppliers specify modular bar-light platforms scaling from 50 mm to 2 meters without optical recalibration.
Machine Vision Light Source Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to compress multi-certification timelines and secure single-vendor accountability contracts. The vendor base organizes around three tiers: diversified industrial automation conglomerates with integrated vision portfolios, specialized photonic subsystem engineers with ceramic-substrate competencies, and regional fabricators serving cost-optimized retrofit markets. M&A activity and technology licensing agreements represent the primary competitive vectors as players race to anchor East Asian electronics corridors.
Within the specialized photonic subsystem tier, CCS Inc and Advanced Illumination exemplify engineering-intensive positioning, while Smart Vision Lights occupies a distinct position around washdown-rated enclosure specifications. Cognex Corporation and Keyence Corporation represent the diversified conglomerate archetype with integrated controller-light source bundles. Omron Corporation and Basler AG anchor the pre-certified modular controller segment with documented compliance for FDA and CE marking requirements.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Omron Corporation |
| CCS Inc |
| Smart Vision Lights |
| Advanced Illumination |
| Spectrum Illumination |
| Basler AG |
| Banner Engineering Corp. |
| Others |
Supply & Pricing Matrix
Captive LED die bonding at CCS Inc and in-house ceramic substrate production anchor supply positions while insulating premium tiers from rare-earth phosphor cost pass-through. This backward integration into critical photonic components concentrates pricing power among Japanese and German subsystem specialists serving medical device and semiconductor inspection verticals.
Pricing Analysis
Rare-earth phosphor cost pass-through runs through high-CRI LED formulations, compressing margins for epoxy-package suppliers serving commodity electronics assembly. Pricing stratifies across FDA-certified, CE-marked, and uncertified tiers, with pharmaceutical packaging verification commanding three-fold premiums over food processing retrofits. Cost compression in standard illumination intensifies as Chinese fabricators scale ceramic-substrate output. Mexican maquiladora electronics plants exhibit the highest price sensitivity, while South Korean semiconductor fabs prioritize sub-pixel performance guarantees over unit economics.
Supply Chain Analysis
China's GB standards for domestic machine vision equipment content reshape sourcing patterns for Yangtze River Delta electronics corridors. LED die and ceramic substrate supply concentrates in China, Japan, and Taiwan, with phosphor formulation expertise anchored in German and Japanese research clusters. Neodymium and cerium processing dependence creates single-source vulnerability for high-uniformity formulations. Distribution runs through Japanese electronics manufacturers demanding controller-light source bundles and German automotive OEMs specifying unified warranty terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The machine vision light source market functions as a regulatory compounder where EU RoHS mercury restrictions and FDA 21 CFR Part 820 quality system regulations continuously upgrade demand specifications and compress qualification timelines for non-compliant suppliers.
For Market Incumbents: Deepen ceramic-substrate LED architectures and in-house phosphor formulation to defend against rare-earth cost volatility and emerging Chinese fabricators scaling premium output. Anchor single-vendor accountability contracts with South Korean semiconductor fabs and German automotive OEMs to lock out modular competitors. For New Entrants and Emerging Players: Capture IP69K-rated washdown enclosure white space in North American meat and dairy processing facilities where USDA facility standards drive certified-supplier preference windows. Target pharmaceutical packaging verification as the most penetrable premium segment given FDA documentation burdens that incumbent generalists underserve. For Investors and Strategic Acquirers: Roll-up economics work for specialized photonic subsystem engineers because optical engineer scarcity and multi-certification timelines create durable moats against commoditization. Watch for REACH framework amendments tightening cadmium and lead thresholds as the inflection signal accelerating material requalification investments and consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Substrate Capacity Expansion | Halves thermal drift for Taiwan and South Korean wafer inspection fabs. |
| FDA Pre-Certification Investment | Documents wavelength stability for pharmaceutical packaging verification systems. |
| IP69K Enclosure Platform Launch | Penetrates USDA-regulated meat and dairy high-pressure sanitation cycles. |
| Controller-Light Source Bundle Integration | Meets Japanese electronics manufacturer unified warranty demands. |
| Phosphor Formulation Backward Integration | Insulates margins from Chinese rare-earth processing concentration. |
Research Methodology
Direct dialogue with optical subsystem engineers, semiconductor fab procurement leads, medical device OEM quality managers, and machine vision integrators grounded qualitative findings in operational constraints. Secondary validation drew from FDA 510(k) filings, EU RoHS enforcement notices, REACH substance restriction amendments, and SEC disclosures by diversified industrial automation conglomerates. Bottom-up demand modeling across LED, laser, xenon, and fluorescent product types triangulated against top-down market sizing.
Segment-level projections across illumination, structured light, backlighting, and strobe technologies fed into aggregate value estimates across the analysis window. Modeled dimensions included integration depth, spectral output range, end-use certification tier, and regional regulatory cluster. CAGRs derived from regression against semiconductor capital expenditure cycles and automotive battery pack assembly line deployment rates.
Phosphor supply disruption, REACH substance list expansion, and GB standards enforcement acceleration are the dominant revision risks to installed base and replacement cycle assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Lithium Niobate Modulator Market
Optical Components
Global Tunable Filter Market
Optical Components
Photointerrupter Market
Optical Components
Electro Optical System Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Quartz Glass Substrate Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Optical Dome Market
Optical Components
Objective Lens Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Optical Interconnect Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Optical Modulators Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Fluorophore Market
Optical Components
Europe Lithium Niobate Modulator Market