
 Europe Multi Camera Vision Inspection Systems Market | 2026-2036
Europe Multi Camera Vision Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Multi Camera Vision Inspection Systems Market Insights
Buyer concentration in Europe's automotive supply base is shifting as tier-one suppliers consolidate their vendor lists for multi-camera inspection platforms. Cognex Corporation leverages its software-defined vision architecture to sustain long-term contracts with German OEMs. Basler AG anchors the component supply layer through its camera manufacturing scale in Ahrensburg. Keyence Corporation competes aggressively with its direct sales force across France and Italy.
Multi Camera Vision Inspection Systems deploy arrays of synchronized image sensors, typically operating at frame rates exceeding 100 fps with sub-pixel calibration, to capture dimensional and surface data from multiple angles for real-time quality decisions. Fixed Systems dominate installed base value across European factory floors due to their integration into permanent production lines, while 3D Vision capabilities are expanding fastest as manufacturers adopt depth-mapping for complex assembly geometries. Machine Learning integration is migrating margin pools toward software licensing and algorithm training services rather than pure hardware sales.
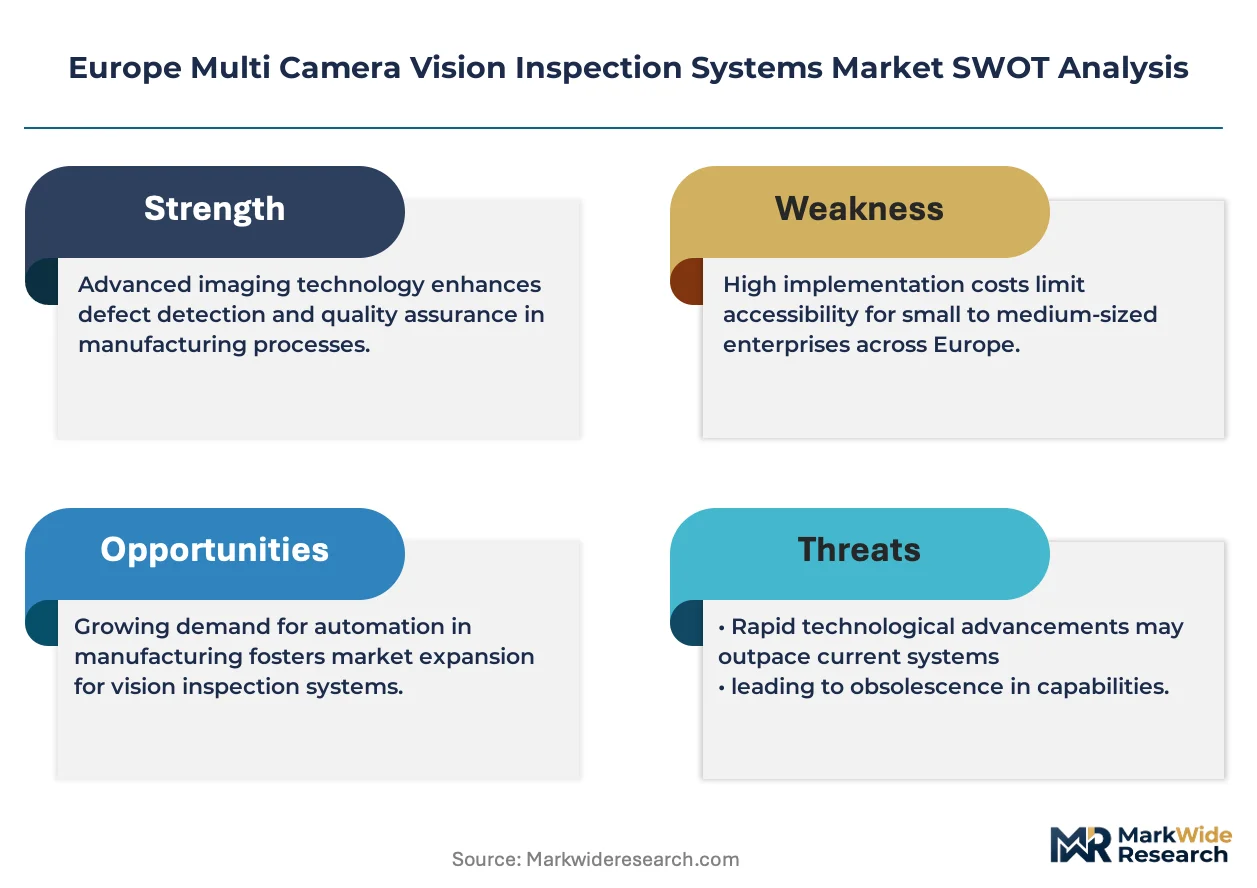
The EU Machinery Directive and CE marking requirements shape product certification pathways for vision system integrators serving European manufacturers. ECHA's REACH framework restricts certain optical coating chemistries, compelling Sick AG and IDS Imaging Development Systems GmbH to reformulate sensor housings and lens assemblies. Siemens AG navigates these standards through its embedded automation platforms that bundle pre-certified vision modules. Stakeholders must monitor how the EU AI Act's risk-classification rules will apply to self-learning defect-detection algorithms before committing to next-generation system architectures.
Market Dynamics
Automotive OEMs in Germany and France are consolidating supplier relationships around software-defined vision architectures, compressing vendor lists while demanding deeper integration with production line automation. This buyer concentration is redistributing margin pools from hardware sales toward algorithm licensing and training services.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification rules for self-learning defect-detection algorithms are compelling manufacturers to upgrade inspection infrastructure ahead of enforcement deadlines.
- Stuttgart-Munich-Wolfsburg industrial corridor expansion:Battery cell production facilities across this German cluster require multi-angle dimensional verification for electrode alignment and separator placement.
- 3D depth-mapping adoption:Complex assembly geometries in electric drivetrain manufacturing demand synchronized camera arrays capturing sub-millimeter tolerances from multiple viewpoints.
Market Restraints
- Specialized optical component supply concentration:High-resolution CMOS sensors and precision lens assemblies depend on a limited supplier base concentrated in East Asian manufacturing hubs.
- ECHA REACH restrictions on optical coatings:Reformulation requirements for sensor housings and lens assemblies extend certification timelines and increase material costs.
- Technical limitation in low-contrast surface inspection:Matte-finish carbon fiber composites and anodized aluminum surfaces challenge conventional edge-detection algorithms without supplemental structured lighting.
Strategic Opportunities
- Italian pharmaceutical packaging automation:Serialization mandates and track-and-trace requirements create demand for vision systems verifying label alignment and data matrix integrity at line speeds.
- EU Green Deal manufacturing incentives:Funding streams for sustainable production upgrades subsidize replacement of legacy inspection equipment with energy-efficient multi-camera platforms.
- Edge computing convergence with 5G factory networks:Distributed processing architectures reduce latency for real-time quality decisions while enabling predictive maintenance on camera arrays.
Industry Challenges
- Machine vision engineer scarcity:Shortages of specialists capable of calibrating multi-camera synchronization and training defect-classification models constrain deployment timelines.
- CE marking certification complexity:Machinery Directive compliance pathways vary across notified bodies, creating uncertainty for system integrators serving pan-European manufacturing networks.
- Legacy PLC integration friction:Retrofitting multi-camera platforms into existing Siemens or Rockwell automation stacks requires custom protocol gateways and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Multi Camera Vision Inspection Systems Market |
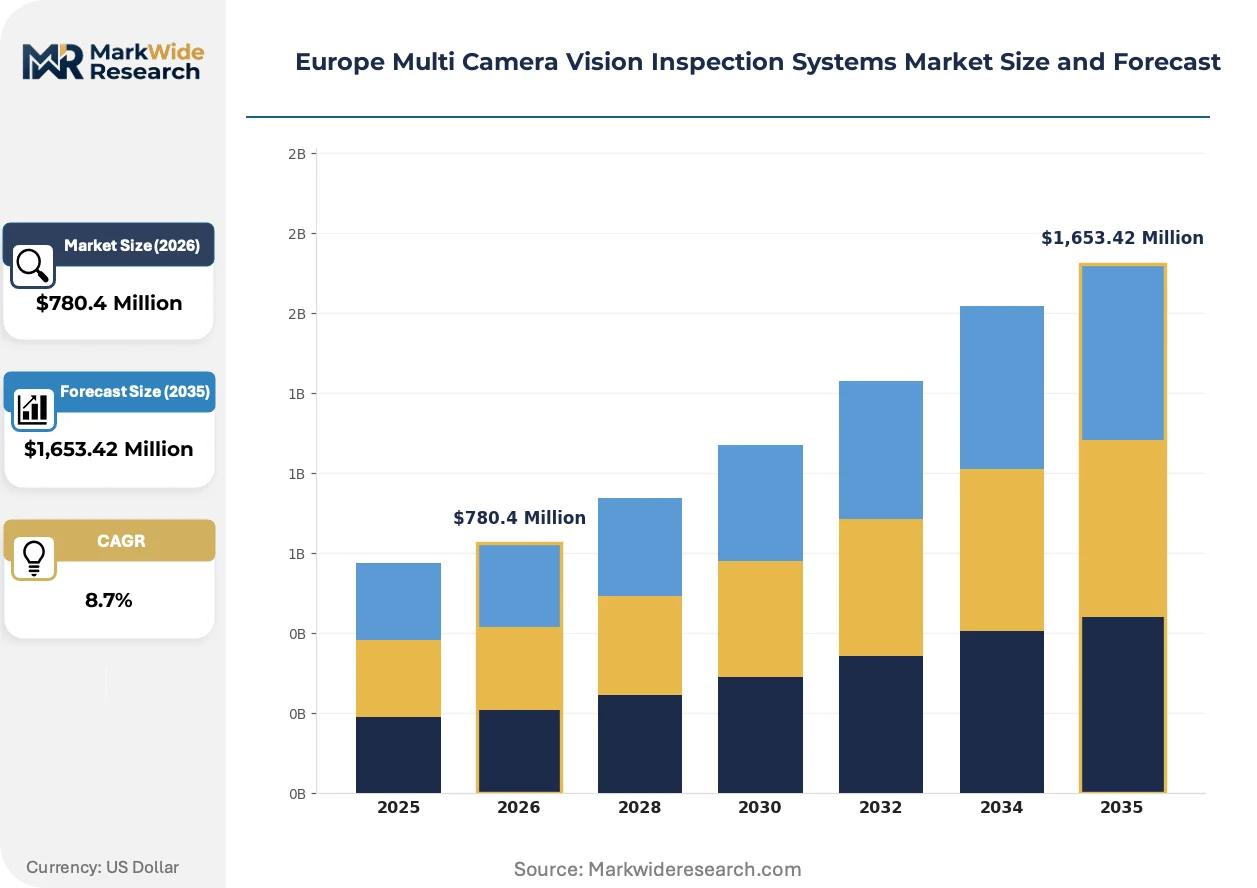
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,653.42 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Systems, Integrated Solutions, Standalone Units Application: Quality Control, Defect Detection, Assembly Verification, Process Monitoring End User: Manufacturing, Food & Beverage, Pharmaceuticals, Automotive Technology: 2D Vision, 3D Vision, Machine Learning, Image Processing |
| Companies Covered | Basler AG, Cognex Corporation, Keyence Corporation, Omron Corporation, Teledyne Technologies, Sick AG, IDS Imaging Development Systems GmbH, Siemens AG, Datalogic S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Multi Camera Vision Inspection Systems Market Trends and Innovations
Deep-learning inference is migrating from centralized servers toward camera-edge processors, altering how European manufacturers architect quality infrastructure. Three developments are restructuring competitive positioning.
Embedded GPU accelerators within IP camera housings are decentralizing computational workloads previously handled by dedicated vision controllers. Tier-one automotive suppliers in Bavaria are deploying these units at line rates exceeding 150 fps for real-time weld seam analysis. This shift compresses hardware BOM costs while elevating software licensing to the primary margin pool.
CE marking requirements under the EU Machinery Directive are tightening documentation standards for safety-related vision systems. Integrators must now submit comprehensive failure-mode analyses for multi-camera configurations deployed in collaborative robot cells. German system builders are responding by pre-certifying modular platform architectures that reduce per-deployment validation overhead.
Service unbundling is separating hardware procurement from algorithm training and ongoing model refinement. French automotive suppliers are contracting specialized vision consultancies to maintain defect-detection accuracy as product mix changes, rather than relying on OEM service agreements. This pattern concentrates recurring revenue with software-native vendors while commoditizing camera hardware.
Europe Multi Camera Vision Inspection Systems Market Segmentation
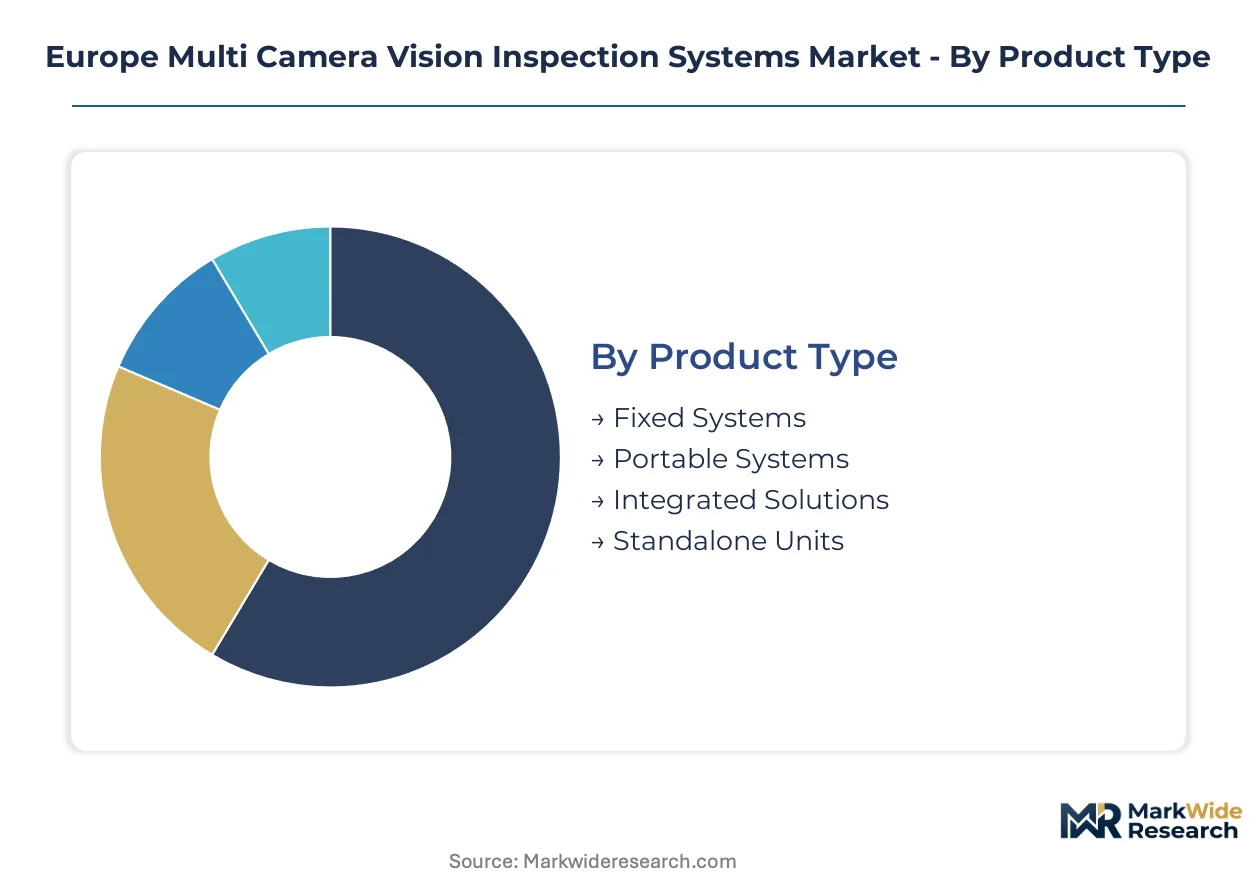
Segmentation in Europe's multi-camera vision inspection market reveals how procurement patterns diverge between standardized automation platforms and application-specific configurations. German automotive OEMs favor deeply integrated solutions while Italian pharmaceutical packagers prioritize rapid deployment flexibility. Understanding these fault lines shapes vendor positioning across the region's industrial corridors.
Product Type:
Customization intensity varies sharply across this category, with permanent installations demanding extensive line integration versus mobile units requiring plug-and-play interoperability.
- Fixed Systems:Permanent installations embedded directly into production line infrastructure with synchronized camera arrays operating at sustained high frame rates. Demand concentrates across Stuttgart, Munich, and Wolfsburg where battery cell manufacturing requires electrode alignment verification at sub-millimeter precision. The EU Machinery Directive's CE marking requirements extend commissioning timelines but lock in long-term vendor relationships.
- Portable Systems:Mobile inspection platforms enabling rapid redeployment across multiple production stages without permanent mechanical integration. French tier-one suppliers deploy these units for spot-checking weld seam quality across dispersed stamping facilities. Flexibility commands premium pricing but limits recurring software revenue attachment.
- Integrated Solutions:Bundled hardware-software architectures pre-certified for specific industrial automation stacks.
- Standalone Units:Self-contained inspection stations operating independently of broader factory control systems.
Leading the category by volume: Fixed Systems. Growing fastest: Integrated Solutions.
Application:
Margin distribution follows the complexity gradient from simple dimensional checks to adaptive defect classification requiring continuous algorithm refinement.
- Quality Control:Comprehensive dimensional and surface verification ensuring finished goods meet specified tolerances before release. German automotive suppliers deploy multi-camera arrays capturing 360-degree coverage of powertrain components at line speeds exceeding 120 parts per minute. Machine learning integration is migrating margin pools toward ongoing model training services rather than one-time hardware sales.
- Defect Detection:Automated identification of surface anomalies, structural flaws, and assembly errors through trained classification algorithms. Italian pharmaceutical packaging lines utilize these systems for verifying label alignment and data matrix integrity under EU serialization mandates. ECHA REACH restrictions on optical coatings complicate sensor specification but create barriers against low-cost imports.
- Assembly Verification:Real-time confirmation of component presence, orientation, and correct sequencing during production.
- Process Monitoring:Continuous surveillance of production parameters to enable predictive intervention before quality deviations occur.
Dominating current deployments: Quality Control. Expanding most quickly: Defect Detection.
End User:
Procurement sophistication separates capital-intensive sectors with dedicated automation engineering teams from price-sensitive industries prioritizing rapid payback periods.
- Manufacturing:Broad industrial base spanning metal fabrication, electronics assembly, and consumer goods production with varying degrees of automation maturity. Demand clusters in Germany's industrial corridor where the EU Green Deal subsidizes replacement of legacy inspection equipment with energy-efficient multi-camera platforms. Technical integration friction with existing Siemens or Rockwell PLC stacks extends commissioning timelines.
- Automotive:Tier-one suppliers and OEMs operating synchronized global production networks with standardized quality protocols. Battery cell production facilities across Bavaria and Lower Saxony require multi-angle dimensional verification for electrode alignment and separator placement. Buyer consolidation around software-defined architectures compresses vendor lists while demanding deeper algorithm licensing integration.
- Pharmaceuticals:Serialization compliance and track-and-trace requirements driving vision adoption across packaging operations.
- Food & Beverage:Hygienic design requirements and high-speed line rates shaping camera housing specifications and lighting configurations.
Commanding largest installed base: Manufacturing. Steepest expansion trajectory: Automotive.
Technology:
Capability layering distinguishes commodity image capture from value-added analytical intelligence embedded at the edge.
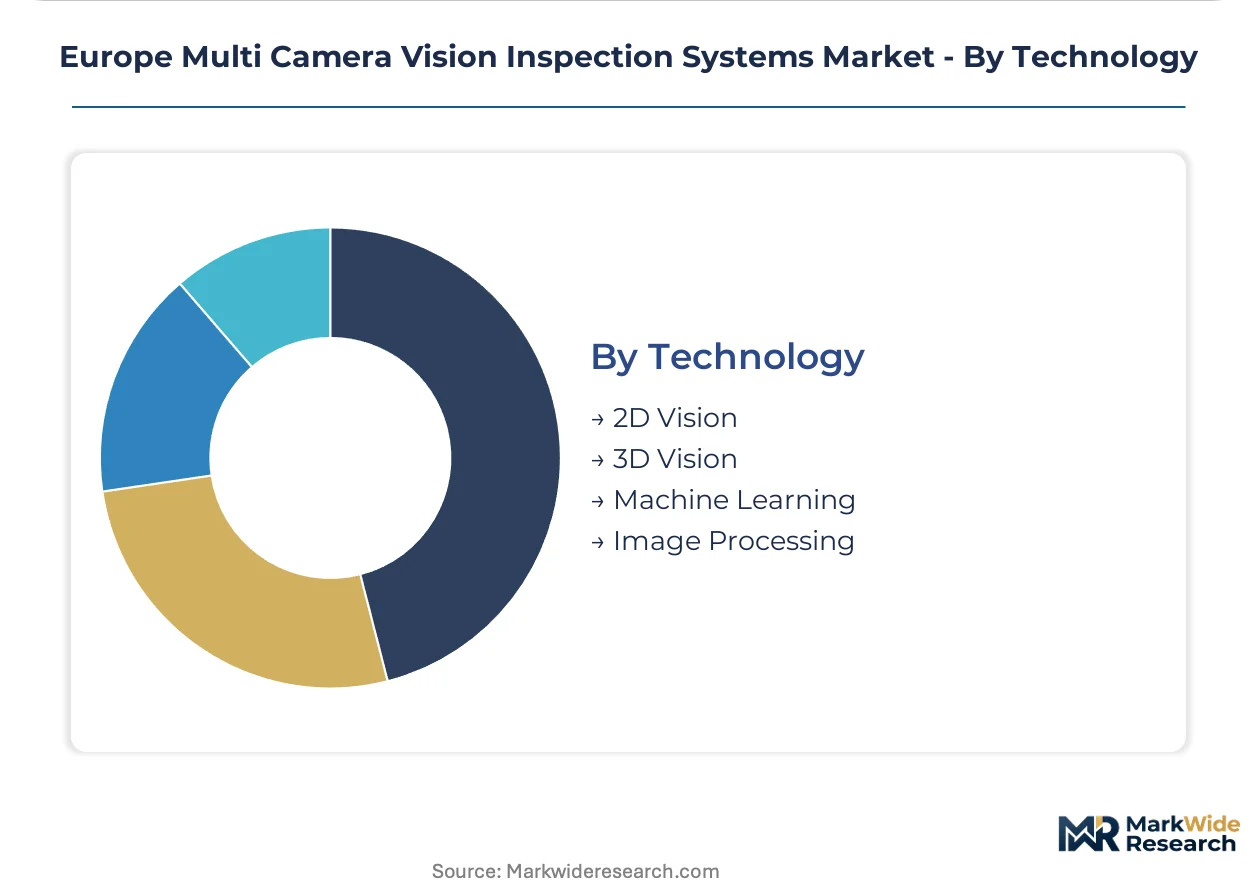
- 3D Vision:Depth-mapping systems capturing spatial geometry through structured light, stereo vision, or time-of-flight measurement. Complex assembly geometries in electric drivetrain manufacturing across France and Germany demand synchronized camera arrays resolving sub-millimeter tolerances from multiple viewpoints. Embedded GPU accelerators within camera housings are decentralizing computational workloads previously handled by dedicated vision controllers.
- Machine Learning:Self-learning defect-detection algorithms adapting to product mix changes without explicit reprogramming. The EU AI Act's risk-classification rules compel manufacturers to upgrade inspection infrastructure ahead of enforcement deadlines, redistributing investment toward software licensing and training services. French automotive suppliers increasingly contract specialized vision consultancies for ongoing model refinement rather than relying on OEM service agreements.
- 2D Vision:Conventional planar image analysis for dimensional measurement and pattern recognition.
- Image Processing:Computational techniques for enhancement, segmentation, and feature extraction from captured sensor data.
Highest current penetration: 2D Vision. Gaining share fastest: Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for multi-camera vision inspection systems concentrates in Germany's industrial corridor, with battery cell manufacturing and automotive assembly driving deployment across the continent.
Germany
Battery production facilities in Stuttgart, Munich, and Wolfsburg require electrode alignment verification at sub-millimeter precision. The EU AI Act's risk-classification rules compel manufacturers to upgrade inspection infrastructure ahead of enforcement deadlines. Embedded GPU accelerators within camera housings are decentralizing computational workloads across Bavarian automotive supplier networks.
France
Tier-one automotive suppliers deploy portable systems for spot-checking weld seam quality across dispersed stamping facilities. ECHA REACH restrictions on optical coatings extend certification timelines but create barriers against low-cost imports. French pharmaceutical packaging lines utilize vision systems for verifying label alignment under EU serialization mandates.
Italy
Pharmaceutical packaging automation creates demand for vision systems verifying data matrix integrity at line speeds. The EU Green Deal subsidizes replacement of legacy inspection equipment with energy-efficient multi-camera platforms. Specialized vision consultancies in Emilia-Romagna maintain defect-detection accuracy as product mix changes.
United Kingdom
Food and beverage manufacturers adopt hygienic design cameras for high-speed line rate applications. CE marking requirements under the Machinery Directive extend commissioning timelines for collaborative robot cells. London-based system integrators navigate certification complexity across pan-European manufacturing networks.
Netherlands
Electronics assembly operations demand rapid deployment flexibility for multi-angle dimensional verification. Edge computing convergence with 5G factory networks reduces latency for real-time quality decisions. Randstad region integrators bundle pre-certified vision modules with embedded automation platforms.
Europe Multi Camera Vision Inspection Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and edge AI integration. The vendor base stratifies across three tiers: component manufacturers supplying sensors and optics, system integrators bundling hardware-software platforms, and software-native vendors licensing algorithm training services. Three strategic archetypes dominate: scale-driven camera manufacturers, vertically integrated automation conglomerates, and specialized vision consultancies. Competitive moves concentrate on strategic partnerships for 5G factory integration and portfolio diversification into predictive maintenance services.
Within the component supply tier, Basler AG anchors camera manufacturing scale through its Ahrensburg operations. Cognex Corporation and Keyence Corporation exemplify contrasting distribution models—software-defined vision architectures versus aggressive direct sales force deployment. Sick AG and IDS Imaging Development Systems GmbH occupy positions navigating ECHA REACH reformulation requirements for sensor housings and lens assemblies.
| Leading Market Players |
|---|
| Basler AG |
| Cognex Corporation |
| Keyence Corporation |
| Omron Corporation |
| Teledyne Technologies |
| Sick AG |
| IDS Imaging Development Systems GmbH |
| Siemens AG |
| Datalogic S.p.A |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of embedded GPU accelerators and edge-computing modules anchors Basler AG's supply position while insulating its pricing power against East Asian component volatility. German automotive OEMs absorb premium positioning for pre-certified integrated solutions, whereas French tier-one suppliers negotiate harder on portable system contracts.
Pricing Analysis
Volume concentrates in fixed systems with compressed hardware margins, while machine learning licensing and algorithm training services capture expanding margin pools. Pricing stratifies across CE-marked premium tiers, software-integrated mid-market bundles, and economy hardware-only configurations. Cost compression in camera hardware intensifies as Basler AG scales Ahrensburg manufacturing. Pharmaceutical packagers in Italy exhibit highest price sensitivity due to rapid payback requirements, while battery cell manufacturers in Germany prioritize precision certification over unit cost.
Supply Chain Analysis
High-resolution CMOS sensor supply rests on Japanese and South Korean specialty semiconductor foundries, with precision lens assemblies drawing from German and Taiwanese optical manufacturers. ECHA REACH restrictions on optical coating chemistries tether reformulation timelines to extended certification cycles. Single-source vulnerability concentrates in sub-100 nanometer sensor fabrication nodes. Distribution runs through certified system integrators bundling hardware-software platforms for pan-European manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized machine vision engineer scarcity props pricing for algorithm training services and integration consulting across European manufacturing corridors. Capacity constraints in certified optical component supply extend lead times for tier-one automotive deployments.
For Market Incumbents: Anticipate margin erosion in standalone camera hardware as embedded GPU accelerators commoditize sensor procurement. Consolidate software licensing architectures to defend against software-native consultancies capturing recurring algorithm refinement revenue. Deepen backward integration into edge-computing module production to secure supply continuity ahead of EU AI Act enforcement deadlines. For New Entrants and Emerging Players: Direct-to-manufacturer digital sales channels bypass entrenched distributor relationships controlling French and Italian mid-market access. Target pharmaceutical packaging automation in Emilia-Romagna where serialization mandates outpace incumbent service capacity. Lead with rapid-deployment portable systems requiring minimal PLC integration to compress commissioning timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automation conglomerates seeking software-defined vision capabilities. Five-to-ten year viability hinges on algorithm training service attach rates exceeding hardware replacement cycles. Acquire specialized vision consultancies with established EU AI Act compliance documentation. Watch battery cell production capacity announcements across Stuttgart-Munich-Wolfsburg as inflection indicator for multi-camera array demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vision Architecture Investment | Cognex Corporation leverages this approach to sustain long-term German OEM contracts against hardware commoditization. |
| EU AI Act Pre-Certification Program | Siemens AG bundles pre-certified vision modules reducing per-deployment validation overhead for system integrators. |
| Edge Computing Convergence Partnership | 5G factory network integration reduces latency for real-time quality decisions across Dutch electronics assembly operations. |
| Optical Component Reformulation Initiative | Sick AG navigates ECHA REACH restrictions to maintain sensor housing supply continuity for European manufacturers. |
| Specialized Vision Consultancy Acquisition | Software-native vendors concentrate recurring revenue from French automotive suppliers outsourcing algorithm refinement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with vision system integrators, automotive platform engineers, pharmaceutical packaging operations managers, and optical component procurement leads. VDMA robotics sector reports, ECHA substance restriction databases, EU Machinery Directive notification files, and battery production facility permitting documents supplied quantitative benchmarks. Bottom-up deployment counts triangulated against top-down automation capital expenditure estimates across Germany, France, and Italy.
Granularity-level modeling distinguished fixed versus portable system configurations, 2D versus 3D versus machine learning technology tiers, and automotive versus pharmaceutical versus general manufacturing end-use segments. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion across the projection horizon. Battery cell production facility announcements, EU Green Deal subsidy disbursement trajectories, and machine vision engineer graduation rates from German technical universities informed sector-specific forecast adjustments.
The model holds under sustained EU AI Act implementation timelines; deviation in enforcement deadline delays or REACH restriction scope expansion would shift upgrade cycle assumptions. Forecasts reflect documented base conditions including continued automotive electrification investment and stable East Asian sensor supply. A small set of named triggers warrants ongoing watch: CE marking pathway harmonization across notified bodies, 5G factory network deployment pace, and machine learning inference chip availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
High-Speed Camera Market
Imaging
Global Digital Binoculars Market
Imaging
Global Automotive Imaging Market
Imaging
Global Digital Photo Frame Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Microwave Imaging Market
Imaging
Global AI in Computer Vision Market
Imaging
Global Image Processing Systems Market
Imaging
Photoacoustic Microscope Market
Imaging
Photoacoustic Tomography Market
Imaging
Acoustic Microscopy Market
Imaging
Digitizer Market