
 North America Photonic Sensors Market | 2026-2036
North America Photonic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Photonic Sensors Market Insights
The U.S. FDA's updated guidance on optical diagnostic devices is expanding the cost-of-entry calculus for photonic sensor manufacturers seeking healthcare approvals. Honeywell International Inc. leverages its aerospace heritage to dominate pressure and temperature sensing for commercial aviation. Banner Engineering Corporation specializes in industrial photoelectric sensors, anchoring its position in factory automation across the Midwest. Teledyne Technologies Incorporated extends its reach into defense and environmental monitoring through advanced imaging sensor portfolios.
Photonic sensors detect, measure, and transmit optical signals across ultraviolet to infrared wavelengths, typically operating at response times below one microsecond for precision feedback control. These devices serve industrial automation, medical diagnostics, and structural monitoring by converting light intensity, phase, or spectral changes into quantifiable electrical outputs. Fiber optic sensors lead product type adoption due to electromagnetic immunity and distributed sensing capability in harsh environments. Interferometry technology captures the fastest growth trajectory, driven by nanoscale measurement requirements in semiconductor fabrication. Industrial monitoring applications occupy the largest application share, though medical diagnostics presents the deepest margin pool as reimbursement pathways for optical biopsy tools mature.
The U.S. FDA and EPA jointly shape product standards, with FDA governing optical diagnostic safety and EPA mandating emissions compliance for laser-based environmental sensors. Health Canada's PMRA and the U.S. FAA impose additional certification layers for aerospace and agricultural photonic deployments. NIST calibration protocols further constrain market access for non-compliant suppliers. Stakeholders must monitor evolving cross-border harmonization between U.S. and Canadian medical device pathways to preempt regulatory fragmentation.
Market Dynamics
Defense procurement cycles across the United States and Canada are compressing validation timelines for LiDAR and fiber-optic systems, forcing suppliers to front-load R&D spend before contract awards materialize.
Growth Catalysts
- FDA Optical Diagnostic Pathway:The U.S. FDA's streamlined pre-submission process for photonic biopsy tools accelerates clinical validation for manufacturers targeting oncology diagnostics.
- Texas Aerospace Corridor Concentration:Prime contractors in the Dallas-Fort Worth and Houston metro areas are consolidating sensor procurement for next-generation satellite platforms.
- Silicon Valley Photonics Cluster:Vertical integration of III-V semiconductor foundries with sensor packaging houses reduces lead times for high-volume industrial automation contracts.
Market Restraints
- Rare Earth Dopant Volatility:Erbium and ytterbium supply concentration in Mountain Pass, California creates input cost instability for fiber amplifier production.
- Canadian Certification Layering:Health Canada's PMRA imposes additional electromagnetic compatibility testing on agricultural photonic sensors beyond U.S. FCC baseline requirements.
- Silicon Photonics Substitution:CMOS-compatible silicon photonic platforms threaten discrete III-V sensor architectures in cost-sensitive industrial monitoring applications.
Strategic Opportunities
- Mexico Nearshoring Expansion:Guadalajara's emerging electronics manufacturing cluster offers tariff-advantaged final assembly for U.S.-bound medical photonic devices.
- Interferometry-Semiconductor Convergence:Integration of optical coherence tomography with wafer inspection systems opens nanoscale metrology contracts with Arizona and Oregon fab operators.
- IRA Clean Energy Incentives:The U.S. Inflation Reduction Act's advanced manufacturing tax credits subsidize domestic production of laser-based environmental monitoring equipment.
Industry Challenges
- Photonic Packaging Talent Gap:Shortage of engineers skilled in free-space optics alignment and hermetic sealing constrains production scaling for defense contractors.
- NIST Calibration Backlogs:Extended queue times for traceable wavelength standards delay product launches for distributed temperature sensing suppliers.
- Legacy Avionics Integration:ARINC 429 protocol translation complexity slows fiber-optic gyroscope adoption in Boeing and Airbus retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Photonic Sensors Market |
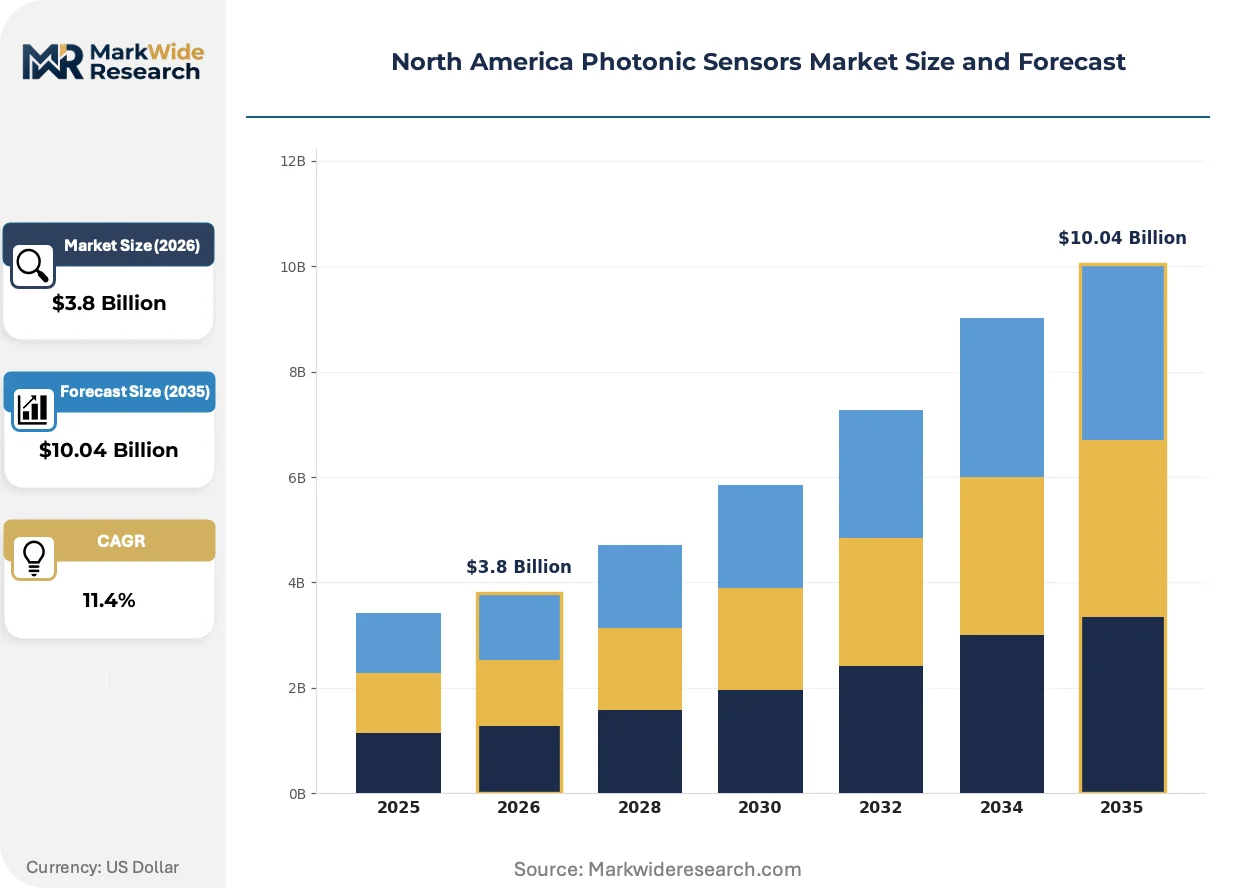
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Sensors, Imaging Sensors, Pressure Sensors, Temperature Sensors End User: Automotive, Aerospace, Defense, Healthcare Technology: Optical Resonance, Interferometry, Spectroscopy, Modulation Application: Industrial Monitoring, Environmental Sensing, Structural Health, Medical Diagnostics |
| Companies Covered | Banner Engineering Corporation, Honeywell International Inc., Teledyne Technologies Incorporated, STMicroelectronics N.V., Baumer Holding AG, Hamamatsu Photonics K.K., Omron Corporation, Keyence Corporation, Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Photonic Sensors Market Trends and Innovations
Photonic sensor architectures are fragmenting into application-specific configurations as end-users reject one-size-fits-all platforms. This specialization is compressing development cycles while fragmenting supplier ecosystems.
Silicon nitride photonic integrated circuits are modularizing. These platforms enable wafer-scale manufacturing of coherent LiDAR transceivers. Automotive Tier 1 suppliers in Michigan and Ontario are adopting them for 2027 model-year programs. The shift is modularizing the traditional discrete component supply chain into foundry-fabless partnerships.
The U.S. FAA's updated Technical Standard Order for fiber-optic gyroscopes mandates new environmental stress testing protocols. Manufacturers must now demonstrate performance across extended temperature ranges before airworthiness certification. Commercial aviation sensor suppliers in Kansas and Connecticut are restructuring qualification departments to absorb these timeline extensions.
Defense procurement officers are unbundling sensor hardware from embedded software maintenance contracts. Prime contractors now expect separate pricing for algorithm updates and calibration services. This unbundling is most visible in Pentagon-directed acquisitions for next-generation ground vehicle platforms, where Northrop Grumman and Raytheon have established distinct software sustainment business units.
North America Photonic Sensors Market Segmentation
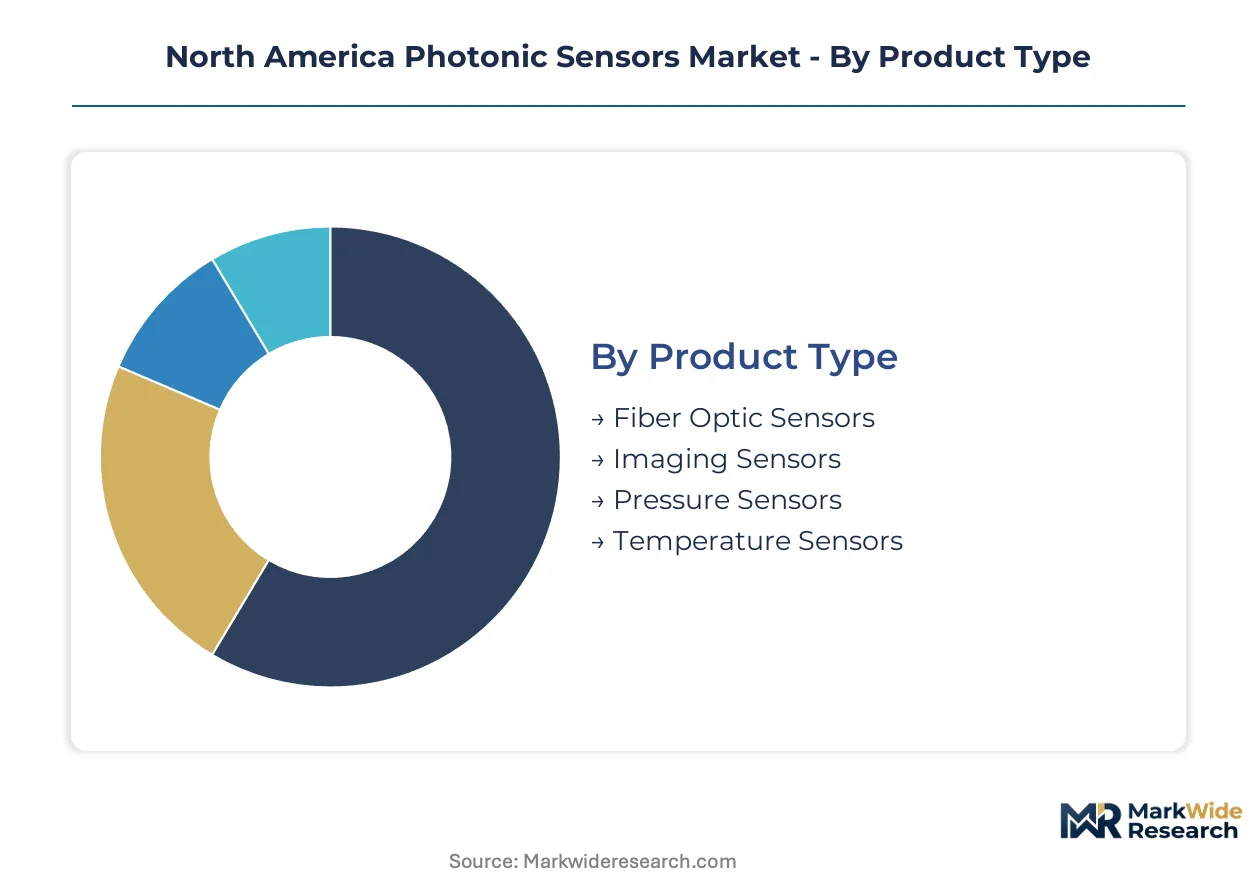
Photonic sensor architectures fragment sharply by deployment environment and signal processing requirements. Capital allocation across these segments reflects divergent certification burdens and manufacturing scale economies.
Product Type:
Fiber optic sensors demand the heaviest upfront investment due to specialized draw towers and rare-earth doping equipment. Imaging sensors require precision lithography but leverage semiconductor foundry infrastructure.
- Fiber Optic Sensors:These devices transmit light through doped silica cores to measure strain, temperature, and acoustic signatures with complete electromagnetic immunity. Demand concentrates in Texas aerospace corridors where defense contractors deploy distributed sensing for structural health monitoring of composite airframes. The U.S. FAA's updated fiber-optic gyroscope certification protocols extend validation timelines and lock in incumbent suppliers with existing airworthiness approvals.
- Imaging Sensors:CMOS and CCD architectures convert photon flux into electrical signals across ultraviolet through infrared wavelengths. California's Silicon Valley cluster dominates design activity for medical diagnostics applications, particularly optical coherence tomography systems awaiting FDA premarket notification. Foundry partnerships with Arizona and Oregon wafer fabs reduce non-recurring engineering costs for high-volume contracts.
- Pressure Sensors:Fabry-Perot and fiber Bragg grating configurations measure static and dynamic pressure in harsh chemical environments.
- Temperature Sensors:Distributed temperature sensing systems exploit Raman and Brillouin scattering in standard telecom fiber.
Most installed capacity flows through Fiber Optic Sensors. Expansion is steepest in Imaging Sensors.
End User:
Customer procurement patterns split between long-cycle defense contracts and high-volume automotive programs with compressed development windows.
- Automotive:LiDAR and in-cabin optical sensing modules for autonomous navigation and driver monitoring. Michigan and Ontario Tier 1 suppliers are consolidating photonic packaging partnerships for 2027 model-year coherent LiDAR transceivers.
- Aerospace:Fiber-optic gyroscopes, engine pressure monitoring, and structural load sensing for commercial and military platforms. Kansas and Connecticut suppliers absorb FAA-mandated environmental stress testing protocol extensions.
- Defense:Pentagon procurement officers unbundle sensor hardware from software maintenance contracts for next-generation ground vehicle platforms.
- Healthcare:Optical biopsy tools and non-invasive glucose monitors face FDA pre-submission pathway acceleration for oncology diagnostics.
Defense procurement volumes anchor supplier revenue stability. Healthcare applications are gaining share fastest as reimbursement pathways mature.
Technology:
Signal processing complexity determines intellectual property intensity and partnership structures with university photonics laboratories.
- Interferometry:Optical path difference measurement enables nanoscale resolution for semiconductor wafer inspection and biomedical imaging. Arizona and Oregon fab operators are integrating white-light interferometry with automated defect classification systems. The technology commands premium pricing in metrology applications where sub-nanometer precision justifies capital expenditure.
- Optical Resonance:Whispering-gallery mode and photonic crystal cavities achieve ultra-high quality factors for biochemical sensing. Silicon nitride platforms from foundries in New York and Vermont enable wafer-scale manufacturing.
- Spectroscopy:Absorption, emission, and Raman techniques identify molecular composition for environmental monitoring and pharmaceutical quality control.
- Modulation:Acousto-optic and electro-optic devices shift optical frequency or phase for signal processing and beam steering.
Interferometry captures the steepest expansion trajectory as semiconductor fabrication tolerances tighten. Optical Resonance maintains the deepest margin pool in specialized biochemical detection.
Application:
Deployment environment dictates packaging hermeticity requirements and calibration protocol rigor.
- Industrial Monitoring:Machine vision, position sensing, and process control in manufacturing facilities. Banner Engineering anchors factory automation deployments across the Midwest with photoelectric sensor portfolios.
- Medical Diagnostics:Optical biopsy, flow cytometry, and point-of-care testing with FDA 510(k) pathway requirements. Margin structures exceed industrial applications by 2-3x where reimbursement codes are established.
- Environmental Sensing:EPA-mandated emissions monitoring and atmospheric chemistry analysis using tunable diode laser absorption spectroscopy.
- Structural Health:Distributed fiber optic sensing for bridges, pipelines, and wind turbine blades under FERC and state-level safety mandates.
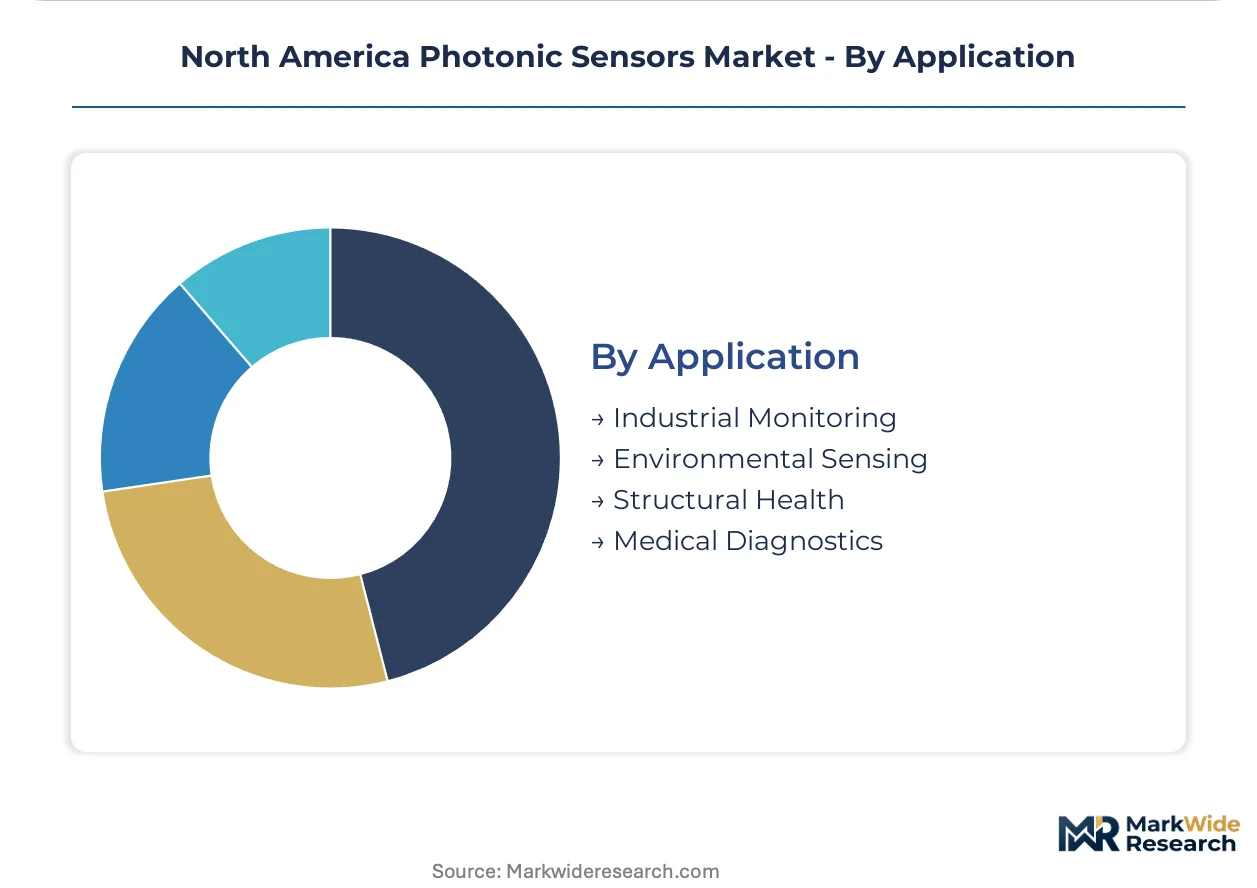
Industrial Monitoring deploys the largest sensor counts. Medical Diagnostics delivers the highest revenue per unit installed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized photonics engineers cluster in California's Silicon Valley, Texas's aerospace corridor, and Ontario's Waterloo-Toronto tech belt, anchoring North America's sensor design capacity.
United States
Defense procurement for LiDAR and fiber-optic systems drives demand concentration in Texas and California. The U.S. FDA's streamlined pre-submission pathway for optical biopsy tools accelerates clinical validation timelines for oncology diagnostic manufacturers. Silicon Valley's III-V semiconductor foundries integrate vertically with sensor packaging houses to reduce lead times for industrial automation contracts.
Canada
Agricultural photonic sensor deployments expand across Prairie Provinces for precision crop monitoring. Health Canada's PMRA mandates additional electromagnetic compatibility testing beyond U.S. FCC baselines for farm equipment sensors. The Waterloo-Toronto corridor concentrates quantum photonics research with commercial spin-offs targeting environmental monitoring applications.
Mexico
Medical device manufacturers nearshore final assembly operations to Guadalajara's electronics cluster for tariff-advantaged U.S. market access. Mexico's federal economic development programs subsidize cleanroom construction for photonic packaging facilities. The Bajío Region attracts Tier 2 suppliers supporting automotive LiDAR module production for Michigan-based Tier 1 integrators.
North America Photonic Sensors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Honeywell International Inc. leverages aerospace heritage to dominate pressure and temperature sensing for commercial aviation. The vendor base fragments between defense contractors with long-cycle validation capabilities and industrial automation suppliers with high-volume manufacturing scale. Strategic moves concentrate on unbundling hardware from software maintenance contracts and consolidating foundry-fabless partnerships for silicon nitride photonic integrated circuits.
Among North American-headquartered suppliers, Banner Engineering Corporation anchors factory automation deployments across the Midwest with photoelectric sensor portfolios. Teledyne Technologies Incorporated exemplifies the diversified defense-electronics archetype through imaging sensor portfolios extending into environmental monitoring. Honeywell International Inc. occupies the premium-tier position leveraging aerospace certification heritage. These three companies represent distinct competitive vectors: industrial volume, defense technology breadth, and aviation regulatory depth.
| Leading Market Players |
|---|
| Banner Engineering Corporation |
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| STMicroelectronics N.V. |
| Baumer Holding AG |
| Hamamatsu Photonics K.K. |
| Omron Corporation |
| Keyence Corporation |
| Rockwell Automation Inc. |
| Others |
Pricing and Supply Chain Analysis
Erbium oxide spot prices on the Shanghai Rare Earth Exchange cascade through fiber amplifier manufacturing into three distinct pricing tiers for photonic sensor procurement. Defense contractors absorbing FAA certification costs for fiber-optic gyroscopes occupy the premium bracket, while industrial automation buyers in the Midwest negotiate volume-based standard-tier contracts, and cost-sensitive environmental monitoring applications cluster in an economy tier shaped by silicon photonics substitution pressure.
Pricing Analysis
Bundled hardware-software maintenance contracts are unbundling across Pentagon procurement streams, forcing suppliers to price algorithm updates and calibration services separately from sensor hardware. Price differentiation separates FDA-cleared optical biopsy systems from uncertified industrial monitoring equivalents, with certification tier and volume scale as the dominant levers. Pricing pressure stems from silicon photonics platforms displacing discrete III-V architectures in factory automation. Healthcare buyers demonstrate lowest price sensitivity due to reimbursement code protection, while agricultural sensor purchasers in Prairie Provinces exhibit highest elasticity.
Supply Chain Analysis
Rare-earth dopant supply rests on Mountain Pass, California extraction and Chinese separation facilities, creating concentrated input dependency for fiber amplifier production. Photoresist and specialty gases for III-V semiconductor foundries draw from Japanese and South Korean chemical producers. Single-source vulnerability concentrates in erbium and ytterbium supply chains subject to export control fluctuations. Distribution runs through vertically integrated Silicon Valley packaging houses for high-volume industrial contracts, while defense programs rely on captive supply chains with Kansas and Connecticut qualification facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through silicon nitride photonic integrated circuit adoption, which collapses packaging costs while enabling premium-tier coherent LiDAR transceiver pricing.
For Market Incumbents: Lock in airworthiness certification moats by accelerating FAA Technical Standard Order compliance for fiber-optic gyroscopes ahead of protocol extensions. Acquire specialized photonic packaging talent pools in Texas and California to constrain competitor scaling. Silicon photonics substitution and emerging foundry-fabless partnerships represent the primary threats to discrete component margins. For New Entrants and Emerging Players: Begin with agricultural photonic sensors across Canadian Prairie Provinces, where Health Canada PMRA electromagnetic compatibility requirements create regulatory friction that favors agile specialists over established industrial players. Target nearshored final assembly in Guadalajara for tariff-advantaged U.S. medical device market access. Pursue foundry partnerships with New York and Vermont silicon nitride platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where NIST calibration backlog delays strand non-compliant suppliers without traceable wavelength standards. Long-term viability favors vertically integrated players with captive III-V foundry capacity and established defense contract relationships. Acquisition target archetypes include specialized interferometry metrology firms serving Arizona and Oregon semiconductor fabs. Watch for IRA advanced manufacturing tax credit utilization rates as the inflection signal for domestic laser-based environmental monitoring equipment production.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry-Fabless Partnership Formation | Silicon nitride platform access enables wafer-scale coherent LiDAR manufacturing for 2027 automotive programs. |
| FDA Pre-Submission Pathway Acceleration | Streamlined optical biopsy tool validation compresses oncology diagnostic commercialization timelines. |
| Defense Software Sustainment Unbundling | Separate algorithm pricing creates recurring revenue streams for Pentagon ground vehicle platform suppliers. |
| Mexico Nearshoring Expansion | Guadalajara cleanroom construction subsidies reduce tariff exposure for U.S.-bound medical photonic devices. |
| Interferometry-Semiconductor Integration | White-light interferometry wafer inspection contracts with Arizona and Oregon fabs capture nanoscale metrology premiums. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national cluster combining structured interviews with defense procurement officers, biomedical engineers at FDA-cleared device manufacturers, Tier 1 automotive supplier platform engineers, and agricultural equipment OEM technical directors. Secondary validation draws from U.S. FDA 510(k) filings, FAA Technical Standard Orders, Health Canada PMRA electromagnetic compatibility test summaries, and SEC 10-K disclosures from listed photonics suppliers. Bottom-up demand modeling triangulates against top-down semiconductor equipment capex forecasts.
Granularity-level framing segments the market by product type, end user, technology, and application, with additional modeling across certification tier and geographic production cluster. Volume and value outputs across the projection horizon derive from installed base growth rates, replacement cycle analysis, and content-per-platform estimates for aerospace and automotive deployments. CAGRs were synthesized from segment-level growth trajectories and input cost elasticity assumptions. Forecast inputs include rare-earth dopant price indices, FAA certification queue lengths, and IRA tax credit utilization tracking.
Several conditions sit outside the modeled scope, including sudden export control expansions on Chinese rare-earth processing, unscheduled FDA guidance revisions on optical diagnostic safety thresholds, and defense procurement freeze events. Forecasts reflect assumptions about continued cross-border harmonization between U.S. and Canadian medical device pathways. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Ellipsometer Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Silicon Photonics Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Europe Optical Imaging Market
Optical Components
Portable Lenses Market
Optical Components
Global Optical Imaging System Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Silicon Focus Ring Market
Optical Components
Optical Position Sensors Market
Optical Components
Pancake Optical Module Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Duplication Disc Market