
 Lab on Chips Market | 2026-2036
Lab on Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Lab on Chips Market Intelligence
The shift towards asset-light, subscription-based models for diagnostic instrumentation is reconfiguring competitive access for smaller biotechnology firms. Established players like Thermo Fisher Scientific leverage their extensive distribution networks to maintain market share in clinical settings. Danaher differentiates through a portfolio of specialized life science tools and consumables for research applications. Agilent Technologies specializes in high-performance analytical instruments that integrate advanced microfluidic chip technologies.
A lab-on-a-chip is a miniaturized device that integrates multiple laboratory functions onto a single integrated circuit, typically a few square millimeters to a few square centimeters in size. These devices utilize microfluidics to handle extremely small fluid volumes, enabling high-throughput screening and analysis. Within applications, point-of-care diagnostics shows significant expansion due to its speed and portability advantages. Among product types, microfluidic chips form the foundational component, while demand for integrated biosensors for real-time monitoring is accelerating.
Market access is governed by stringent regulatory frameworks, including the FDA's clearance process in the United States and the EU's In Vitro Diagnostic Regulation (IVDR). Concurrently, ISO 13485 standards dictate the quality management systems for medical device manufacturing, ensuring product safety and efficacy. Future competitive advantage will depend on navigating these complex approval pathways while innovating on material science for chip fabrication.
Market Dynamics
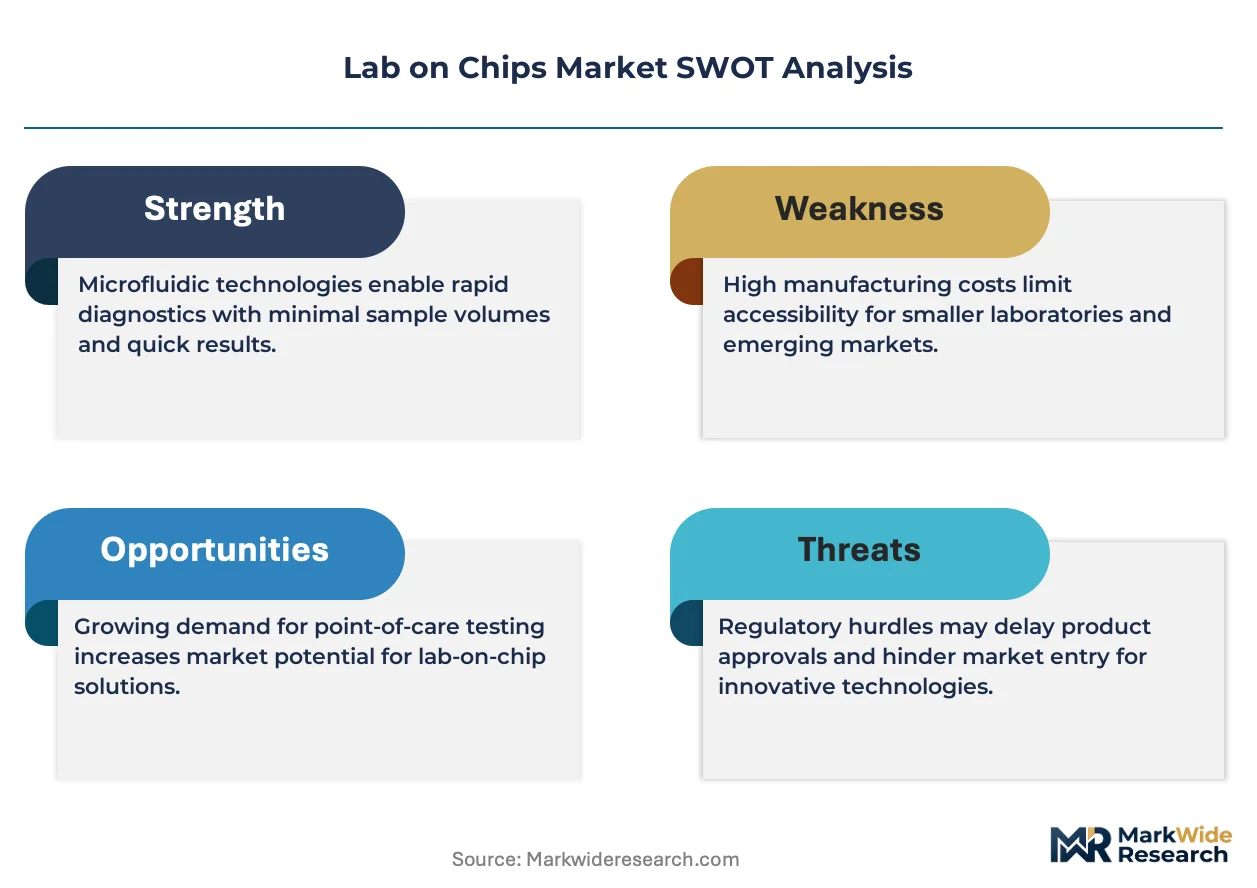
The central tension in the lab-on-a-chip market is the friction between rapid technological advancements in microfluidics and the rigorous, often slow, regulatory validation required for clinical applications, particularly under frameworks like the FDA and IVDR.
Growth Catalysts
- Point-of-Care Diagnostics:Demand for rapid, decentralized testing in clinical settings and resource-limited environments drives adoption. The portability and speed of lab-on-a-chip devices offer significant advantages over traditional laboratory-based tests for infectious disease screening and chronic disease management.
- Miniaturization Advances:Continuous progress in microfabrication techniques allows for the integration of more complex functions, such as sample preparation and analysis, onto a single chip. This enables higher throughput and reduces reagent consumption in biomedical research applications.
- Government R&D Funding:Significant public and private research funding in biomedical hubs, particularly in the United States and Germany, supports foundational innovation in microfluidics, material science, and biosensor technology, accelerating the development of next-generation devices.
Market Restraints
- High Fabrication Costs:The initial capital expenditure for photolithography equipment and the operational costs of maintaining cleanroom facilities for silicon and glass chip fabrication remain substantial, creating a high barrier for new entrants and smaller-scale producers.
- Lack of Standardization:A persistent lack of industry-wide standardization for chip formats, fluidic interconnects, and data output protocols hinders interoperability between devices and analytical instruments from different manufacturers, complicating workflow integration for end-users.
- Complex Material and Fluidic Behavior:Unpredictable interactions between biological samples and chip materials, along with challenges in controlling fluid behavior at the microscale, can affect the accuracy and reproducibility of results, slowing down product development and validation.
Strategic Opportunities
- Expansion into Agritech:There is an opportunity to apply lab-on-a-chip technology for on-site soil analysis, water quality testing, and early detection of plant pathogens in agriculture, providing farmers with real-time data for precision farming.
- Integration with Artificial Intelligence:Combining microfluidic devices with on-chip AI and machine learning algorithms can enable automated, real-time data interpretation and decision-making, significantly enhancing the capabilities of diagnostic and research tools without external computation.
- Development of Biodegradable Chips:Innovating with biodegradable polymers and sustainable materials for chip fabrication can address environmental concerns related to the disposal of single-use plastic devices, creating a competitive advantage with environmentally conscious customers.
Industry Challenges
- Data Integration with LIMS:A significant operational hurdle is the seamless integration of data generated by diverse lab-on-a-chip platforms with existing Laboratory Information Management Systems (LIMS) and electronic health records, which often requires custom software development.
- Manufacturing Scale-Up:Transitioning from prototype to high-volume, cost-effective manufacturing while ensuring low defect rates and consistent performance remains a major challenge, especially for complex, multi-layered microfluidic chip designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab on Chips Market |
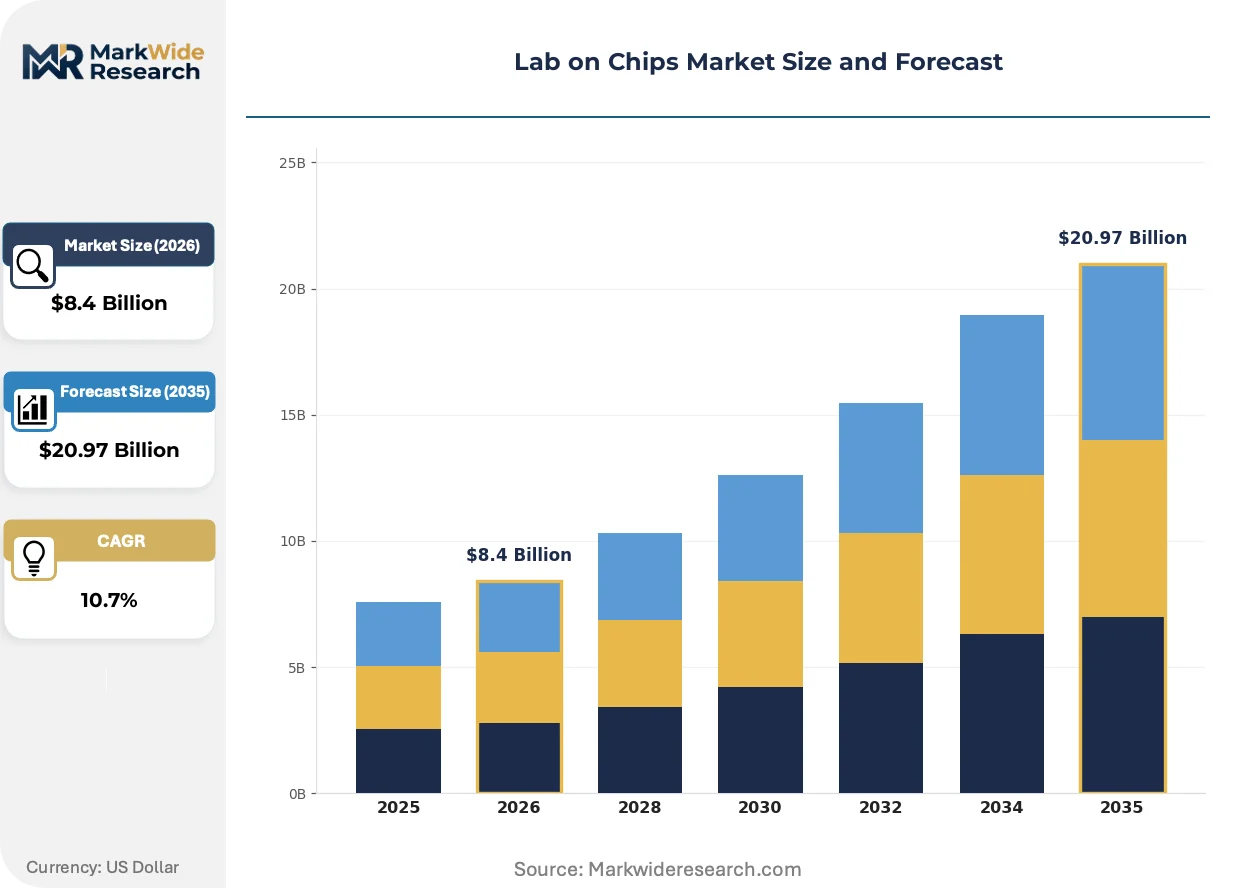
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $20.97 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
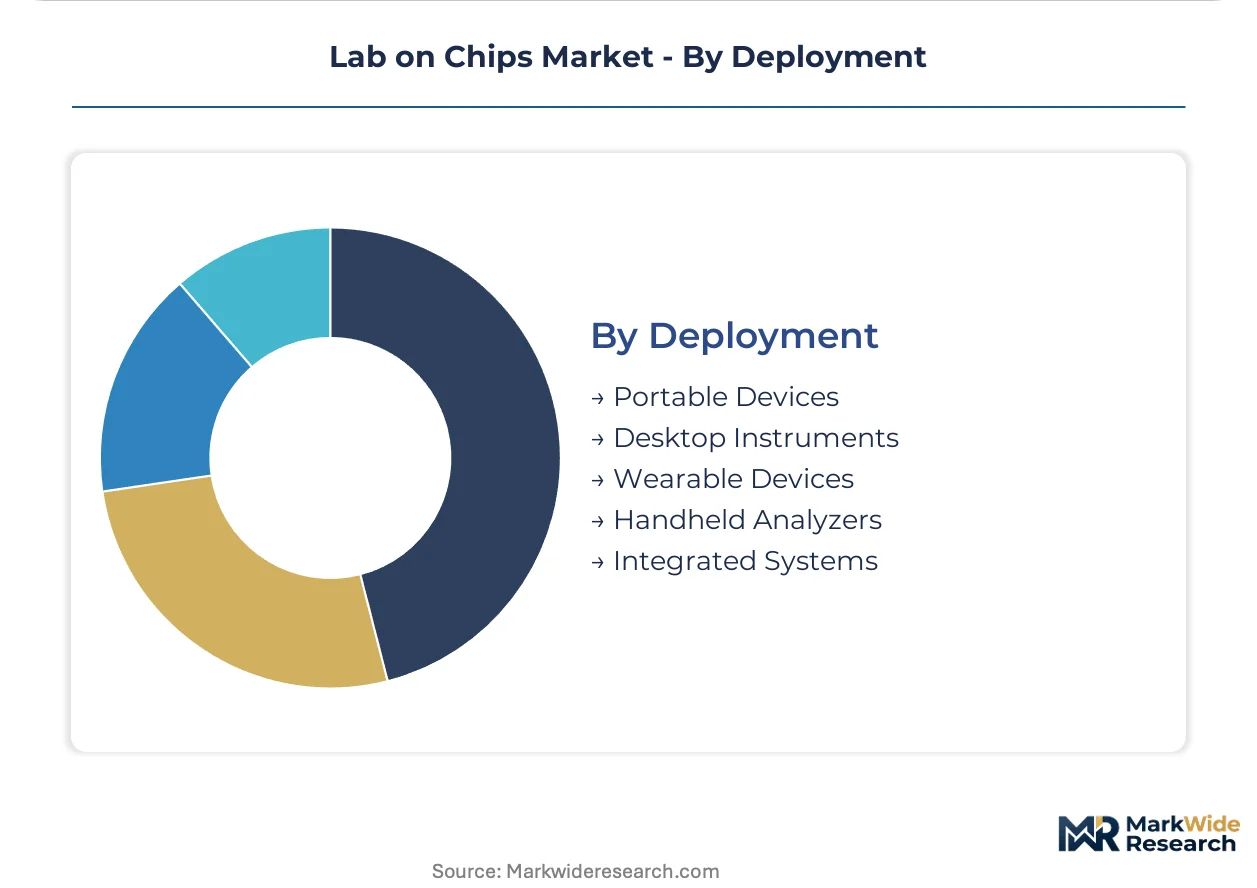
| Segmentation | Product Type: Microfluidic Chips, Biosensors, Microarrays, DNA Chips, Protein Chips Application: Point-of-Care Diagnostics, Drug Discovery, Environmental Monitoring, Food Safety, Biochemical Analysis End User: Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Academic Institutions, Biotechnology Firms Deployment: Portable Devices, Desktop Instruments, Wearable Devices, Handheld Analyzers, Integrated Systems |
| Companies Covered | Thermo Fisher Scientific, Illumina, Danaher, Merck KGaA, Abbott Laboratories, Agilent Technologies, Bio-Rad Laboratories, QIAGEN, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab on Chips Market Strategic Shifts & Innovations
The convergence of advanced data analytics and material science is transforming microfluidic devices from simple diagnostic tools into intelligent, interconnected systems. This evolution enables more sophisticated, predictive analyses at the point of need, moving beyond simple detection to providing actionable insights.
Digital microfluidics (DMF) technology manipulates discrete droplets of fluid on a surface of electrodes, offering precise, programmable liquid handling. Drug discovery and synthetic biology labs are adopting DMF for its flexibility in performing complex, multi-step protocols. This technology is virtualizing the fixed channels of traditional microfluidics, allowing researchers to dynamically reconfigure assays on a single device.
Regulatory frameworks are adapting to the pace of innovation. The European Union's In Vitro Diagnostic Regulation (IVDR) imposes stricter requirements for clinical evidence and post-market surveillance on all diagnostic devices. This is forcing manufacturers to invest more heavily in clinical performance studies and robust quality management systems. The point-of-care segment is most affected, as devices must now demonstrate efficacy comparable to central lab standards.
A shift from one-time capital equipment sales toward subscription-based access for instrumentation and associated consumables is gaining traction. This model lowers the entry barrier for smaller research labs and biotech startups, disrupting the traditional large-outlay procurement cycle. The trend is most visible within academic research and early-stage biopharmaceutical R&D, particularly in North America and Europe.
Lab on Chips Market Segmentation
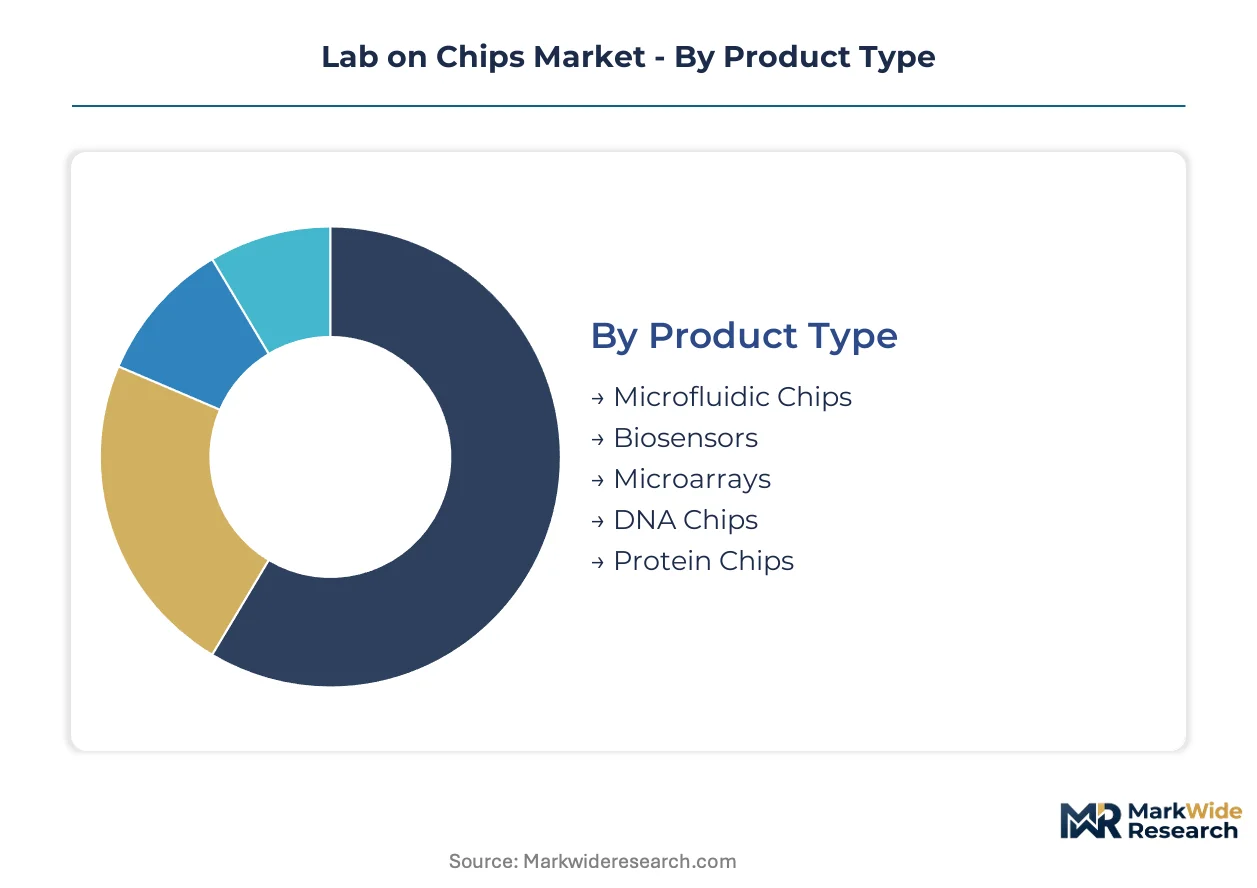
The Lab on Chips market is fundamentally shaped by how various product types, applications, end-users, and deployment models converge. Understanding these distinct segments provides clarity on market demand drivers and the strategic positioning of key technologies.
Product Type:
Product composition defines the core functionality and technical sophistication available within lab-on-a-chip devices, influencing their adoption across diverse scientific disciplines.
- Microfluidic Chips:These are foundational components, utilizing miniaturized channels to precisely control fluid volumes and enable complex analyses. Demand concentrates in biomedical research hubs across the United States for high-throughput screening applications.
- Biosensors:These integrate biological recognition elements with transducers for real-time detection of analytes, offering rapid diagnostic capabilities. Their demand is accelerating in point-of-care diagnostics for infectious disease screening.
- Microarrays:These permit the parallel analysis of numerous biological samples, crucial for genomic and proteomic studies in academic research.
- DNA Chips:These facilitate genetic analysis and gene expression profiling, primarily used by biotechnology firms for drug target identification.
- Protein Chips:These enable high-throughput protein analysis, supporting biomarker discovery and pharmaceutical development.
Microfluidic Chips hold installed capacity. Biosensors are rotating up the share rankings.
Application:
End-use scenarios dictate the specific performance requirements and regulatory pathways for lab-on-a-chip solutions across different sectors.
- Point-of-Care Diagnostics:This application focuses on rapid, decentralized testing in clinical settings and resource-limited environments, leveraging device portability. Demand for these devices is strong in both North America and Europe for infectious disease management.
- Drug Discovery:This involves high-throughput screening and multi-step protocols for identifying and validating drug candidates in pharmaceutical research. Pharmaceutical companies are the primary drivers of demand for these sophisticated systems.
- Environmental Monitoring:Lab-on-a-chip devices assess water quality and detect pollutants, providing real-time data for ecological studies.
- Food Safety:These systems identify contaminants and pathogens in food products, ensuring consumer safety and regulatory compliance for food processors.
- Biochemical Analysis:This covers a broad range of laboratory tests, including enzyme assays and cellular analysis, supporting fundamental biological research.
Point-of-Care Diagnostics demonstrates significant expansion. Drug Discovery applications are driving incremental adoption.
End User:
Institutional demand patterns highlight the primary beneficiaries and investment drivers for advanced microfluidic technologies across the healthcare ecosystem.
- Research Institutes:These entities drive foundational innovation and conduct complex analyses, often supported by significant government R&D funding. Institutes in Germany are particularly invested in new material science applications.
- Pharmaceutical Companies:These firms utilize lab-on-a-chip technology for drug development, preclinical testing, and high-throughput screening, supported by large R&D budgets. Major pharmaceutical players in the United States are key consumers.
- Diagnostic Laboratories:These facilities integrate lab-on-a-chip devices for routine testing and specialized assays, enhancing diagnostic capabilities.
- Academic Institutions:Universities and colleges employ these devices for educational purposes and early-stage research, fostering next-generation scientists.
- Biotechnology Firms:These companies leverage microfluidic platforms for novel product development, biomarker discovery, and genetic engineering.
Research Institutes consistently lead in foundational technology adoption. Pharmaceutical Companies are demonstrating robust investment in novel diagnostic tools.
Deployment:
Operational configurations differentiate how lab-on-a-chip devices integrate into existing workflows, impacting user accessibility and data management.
- Portable Devices:These compact, battery-powered units are designed for field diagnostics and remote healthcare settings, offering flexibility and rapid results. Demand for these devices is concentrated in point-of-care applications.
- Integrated Systems:These comprise multiple modules and automated workflows, providing comprehensive solutions for complex laboratory processes. Centralized laboratories and high-volume processing centers are the primary users.
- Desktop Instruments:These larger, benchtop units offer higher analytical capabilities and throughput for laboratory-based research and clinical diagnostics.
- Wearable Devices:These emerging forms of lab-on-a-chip technology monitor physiological parameters continuously, primarily for health tracking and early disease detection.
- Handheld Analyzers:These compact devices offer immediate results for specific tests, often used in rapid screening or emergency medical situations.
Portable Devices are exhibiting the steepest expansion trajectory. Integrated Systems continue to underpin high-throughput laboratory operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government R&D funding and supportive regulatory frameworks significantly influence the global Lab on Chips market trajectory. These policies accelerate foundational innovation and clinical adoption across key regions. Countries like the United States, Germany, Japan, and China are particularly active in fostering this technological advancement.
United States
The United States market demonstrates robust demand driven by extensive biomedical research and pharmaceutical R&D. The FDA's stringent clearance process ensures product safety and efficacy for clinical applications. Major biotechnology hubs like Boston and the San Francisco Bay Area attract significant public and private investment in microfluidic innovation.
Germany
Germany exhibits strong demand from research institutes and advanced material science applications. The EU's IVDR imposes rigorous requirements for clinical evidence and post-market surveillance for diagnostic devices. Cities such as Munich and Berlin are central to microfluidics research and high-precision manufacturing capabilities.
Japan
Japanese demand for Lab on Chips devices centers on advanced analytical instruments and pharmaceutical development. The PMDA oversees the approval of medical devices, ensuring strict quality and performance standards. Research and manufacturing clusters in Tokyo and Osaka actively develop next-generation microfluidic platforms for diverse applications.
China
China's market is expanding rapidly, fueled by healthcare infrastructure expansion and point-of-care diagnostics initiatives. The NMPA regulates medical devices, focusing on local innovation and market access for domestic producers. Major industrial zones like the Yangtze River Delta foster significant investment in microfluidic chip fabrication and application development.
Lab on Chips Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established global players dominating core segments. Several large diversified corporations compete alongside specialized technology providers and agile biotechnology firms. Strategic archetypes include broad life science tool providers, high-performance analytical instrument developers, and niche microfluidic component manufacturers. These entities primarily engage in portfolio diversification and strategic partnerships to expand market reach.
Within the established diversified player archetype, Thermo Fisher Scientific represents a broad supplier leveraging extensive distribution networks for clinical settings. Danaher exemplifies a specialized life science tool provider, offering a comprehensive portfolio of consumables for research applications. Agilent Technologies occupies a position as a high-performance analytical instrument specialist, integrating advanced microfluidic chip technologies into its offerings. These entities collectively anchor the market through their extensive product ranges and global operational footprints.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Danaher |
| Merck KGaA |
| Abbott Laboratories |
| Agilent Technologies |
| Bio-Rad Laboratories |
| QIAGEN |
| PerkinElmer |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's growing fabrication capacity for microfluidic chips influences the cost structure of lab-on-a-chip devices. This regional concentration impacts the pricing power of downstream diagnostic and research instrument manufacturers.
Pricing Analysis
Certification level (FDA/CE-IVD grade) creates the primary spread in lab-on-a-chip device pricing. A hybrid model combines upfront capital equipment purchases with recurring, subscription-based consumables for microfluidic chips and reagents. Performance accuracy and integration capabilities justify premium pricing for advanced analytical instruments. Pricing softness reflects increased competition from emerging players targeting less regulated research applications. Academic institutions and smaller biotech startups are most price-sensitive, while large pharmaceutical companies prioritize performance over cost.
Supply Chain Analysis
Upstream sourcing of specialized silicon wafers and glass substrates forms the foundation of the lab-on-a-chip supply chain. Component manufacturing concentrates in Taiwan, South Korea, and Germany for high-precision microfluidic elements. The industry relies on advanced photolithography equipment and specialized polymers for chip fabrication. Single-source vulnerability for certain high-performance biosensor components presents a structural risk. Distribution runs through established life science tool distributors and direct sales channels to research institutes and diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lab-on-a-chip market represents an early-cycle expansion story, propelled by the increasing decentralization of diagnostic testing. This fundamental shift drives broader adoption across clinical and research settings.
For Market Incumbents: Insulate core clinical diagnostic revenues by accelerating regulatory clearances for next-generation IVDR-compliant devices. Invest in advanced material science for chip fabrication to reduce per-unit costs and expand into emerging applications like agri-tech. Acquire specialized microfluidic component manufacturers to control critical supply chain nodes. Emerging digital microfluidics technologies pose a threat to traditional fixed-channel devices. Leverage extensive distribution networks and established relationships with diagnostic laboratories.
For New Entrants and Emerging Players: Niche point-of-care applications in resource-limited environments represent the most penetrable entry point for novel lab-on-a-chip solutions. Target unmet needs in infectious disease screening or environmental monitoring with cost-effective, portable devices. Focus on developing biodegradable chip solutions to appeal to environmentally conscious customers. Partner with non-governmental organizations or local health authorities for initial market access and validation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized microfluidics firms with strong intellectual property in biosensor integration. The long-term viability hinges on continued miniaturization and seamless data integration capabilities. Target agile biotechnology firms developing AI-enabled lab-on-a-chip platforms for automated data interpretation. Watch for increasing government R&D funding allocations specifically for advanced microfluidic material science.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Expedites market access for novel diagnostic devices under stringent frameworks like IVDR. |
| Manufacturing Scale-Up | Reduces per-unit costs and ensures consistent product availability for high-volume clinical demand. |
| Strategic Partnership | Combines microfluidic expertise with established distribution networks for broader market penetration. |
| Product Launch | Introduces new AI-integrated lab-on-a-chip devices to address complex analytical challenges. |
| Biodegradable Material Development | Addresses environmental concerns and creates a competitive advantage with sustainable product offerings. |
Research Approach
A standing panel of biomedical engineers, research scientists, and diagnostic lab directors provided ongoing calibration for market trends. Primary interviews with industry stakeholders were triangulated with extensive secondary validation. Secondary data sources included FDA filings, EU IVDR guidance documents, academic journals, and leading company reports. This approach ensured robust bottom-up and top-down data triangulation.
Scenario-bracketing frameworks were applied to model market growth across the analysis window, accounting for varying technological adoption rates. Segmentation dimensions included product type, application, end-user, deployment model, and material science innovation. Compound Annual Growth Rates were derived by analyzing historical growth trajectories and projected future demand dynamics. Key forecast inputs included government R&D spending and regulatory approval rates for new diagnostic platforms.
Practitioners should monitor regulatory bottlenecks and material supply disruptions for early signals of market shifts. Forecasts reflect assumptions regarding technological advancements and market acceptance. Cross-checking against national health expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Nanopatterning Market