
 Piezoelectric Nanogenerator Market | 2026-2036
Piezoelectric Nanogenerator Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Nanogenerator Market Analytics
Direct procurement between materials suppliers and original equipment manufacturers is reshaping traditional component distribution for piezoelectric nanogenerators. Morgan Advanced Materials leverages its ceramics expertise to supply high-purity lead zirconate titanate substrates to energy harvesting module builders. Murata Manufacturing Co., Ltd. anchors East Asian supply through vertically integrated capacitor and sensor fabrication. CeramTec GmbH specializes in medical-grade piezoceramics that meet implantable device biocompatibility requirements.
A piezoelectric nanogenerator converts ambient mechanical energy into electrical output through strain-induced polarization in nanostructured materials, typically achieving power densities from tens of nanowatts to several microwatts per square centimeter depending on active layer architecture and electrode configuration. Flexible nanogenerator architectures command premium positioning due to their compatibility with curved biological surfaces and textile integration, while rigid configurations retain cost advantages in industrial vibration harvesting installations. Zinc oxide and polyvinylidene fluoride material streams are gaining share against lead zirconate titanate as environmental compliance tightens across consumer electronics supply chains.
The EU REACH regulation and RoHS directive restrict lead content in electrical components, compelling reformulation of traditional piezoceramic compositions and opening qualification pathways for barium titanate alternatives. The FDA maintains stringent biocompatibility and electrical safety standards for implantable nanogenerator applications in cardiac and neuromuscular devices. Stakeholders must monitor evolving material certification requirements and foundry capacity for thin-film deposition processes to secure supply continuity.
Market Dynamics
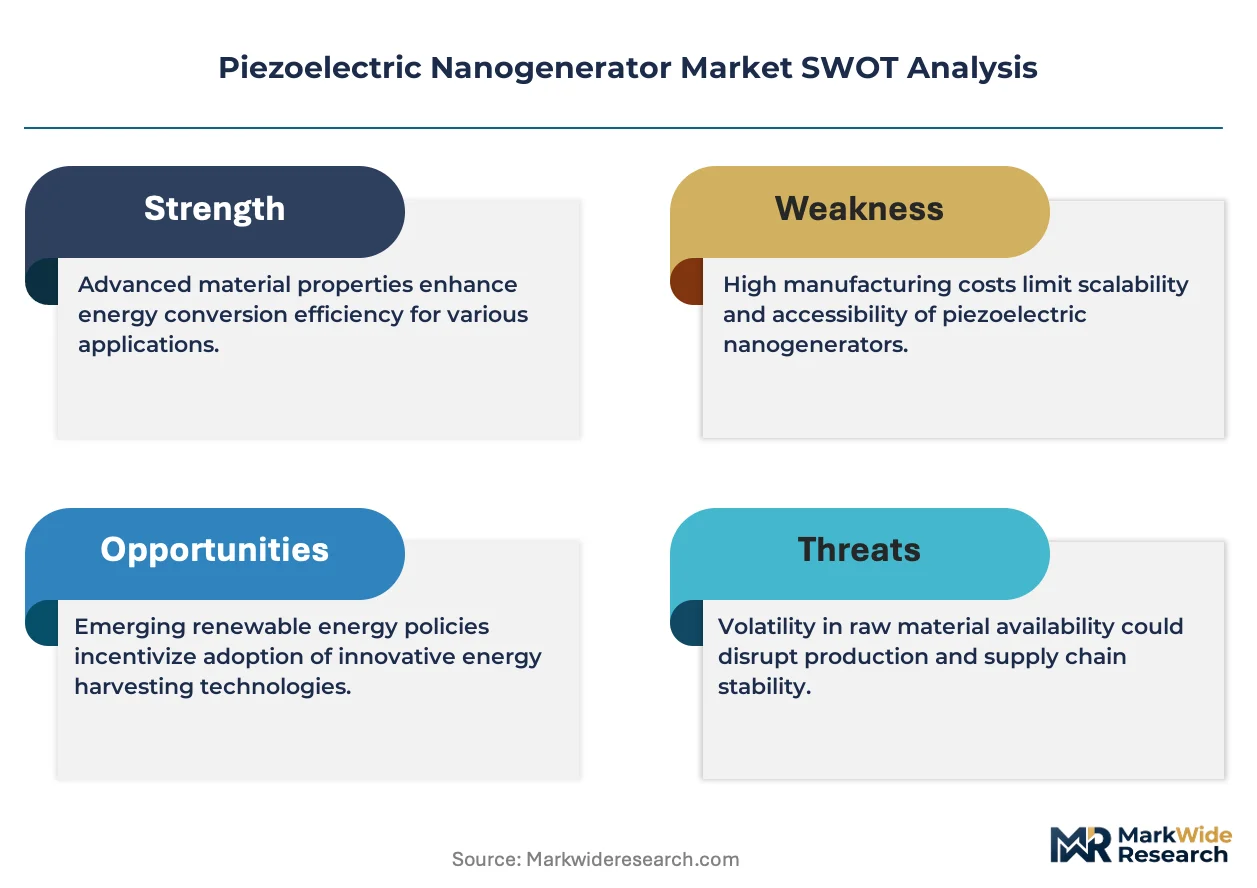
EU REACH restrictions on lead-based piezoceramics are forcing materials suppliers to requalify entire product portfolios around barium titanate and zinc oxide alternatives, compressing development timelines while opening substitution windows for compliant formulations.
Growth Catalysts
- EU Green Deal compliance mandates:REACH Phase-out schedules for lead zirconate titanate are accelerating R&D budgets at ceramics suppliers. Medical device OEMs now specify lead-free compositions for implantable energy harvesters.
- Wearable electronics integration:Samsung and LG supply chains in South Korea are volume-committing to flexible nanogenerator modules for biometric sensors. Textile-compatible architectures are qualifying for smart apparel programs.
- Self-powered sensor proliferation:Industrial IoT deployments in predictive maintenance are specifying vibration-harvesting nodes. Zinc oxide nanowire arrays are meeting power density thresholds for wireless condition monitoring.
Market Restraints
- Thin-film deposition capacity scarcity:Sputtering and sol-gel foundry bottlenecks in East Asia are extending lead times for piezoelectric active layers. Equipment utilization rates constrain batch scaling.
- Lead-free performance gap:Barium titanate alternatives exhibit lower electromechanical coupling coefficients than legacy PZT formulations. Energy conversion efficiency trade-offs limit deployment in high-strain applications.
- Biocompatibility certification timelines:FDA 510(k) pathways for implantable nanogenerators require extended electrical safety and cytotoxicity testing. Cardiac pacemaker integrations face multi-year qualification cycles.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing are attracting nanogenerator module assembly investments. Domestic medical device clusters in Hyderabad and Bengaluru offer captive demand.
- Energy harvesting-textile convergence:Polyvinylidene fluoride fiber spinning is enabling woven piezoelectric fabrics. Sportswear and military uniform programs are piloting self-powered physiological monitoring.
- ISO/IEC standardization acceleration:Emerging international standards for flexible energy harvesters are reducing buyer qualification burden. Certification harmonization opens cross-border procurement for mid-tier suppliers.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled electromechanical and fluid-structure modeling for nanogenerator optimization requires specialized finite-element expertise. Universities produce insufficient graduates in piezoelectric device physics.
- Electrode-interface degradation:Cyclic fatigue at silver nanowire-polymer junctions reduces operational lifetime. Reliability engineering for 10-year implantable service remains unresolved.
- Supply chain reconfiguration friction:Qualifying new lead-free ceramic powder sources requires recalibration of sintering protocols. Process drift risks during feedstock transitions consume engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Nanogenerator Market |
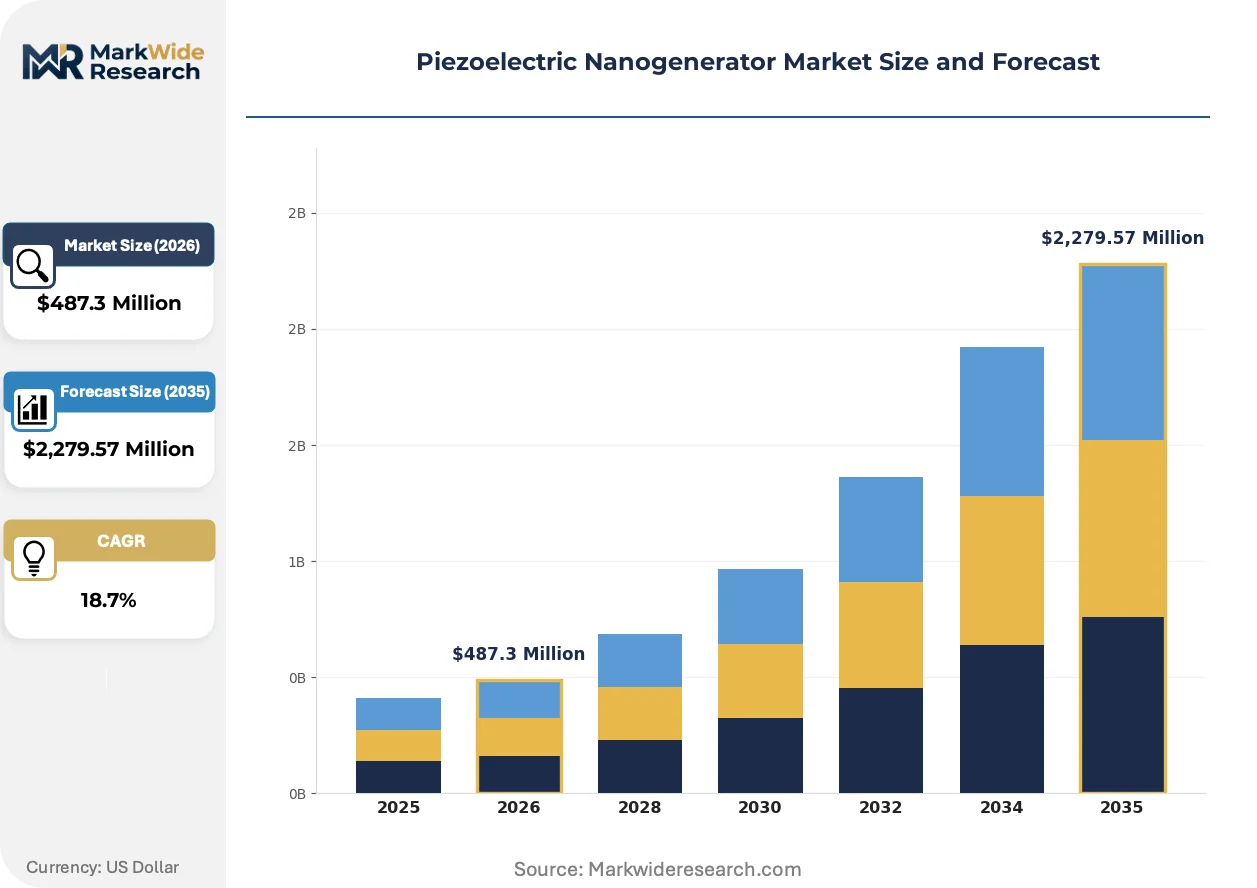
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,279.57 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Nanogenerator, Rigid Nanogenerator, Hybrid Nanogenerator, Arrays Material: Lead Zirconate Titanate, Polyvinylidene Fluoride, Barium Titanate, Zinc Oxide Application: Wearable Devices, Energy Harvesting, Biomedical Sensors, Structural Health Monitoring End User: Consumer Electronics, Healthcare, Automotive, Aerospace |
| Companies Covered | Morgan Advanced Materials, Murata Manufacturing Co., Ltd., PI (Physik Instrumente), CeramTec GmbH, APC International Ltd., TRS Technologies, Inc., Piezosystem Jena, Noliac A/S, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Nanogenerator Market Evolving Landscape
Materials innovation and regulatory compliance are converging to compress traditional product lifecycles. Suppliers must simultaneously manage lead-free reformulation, flexible architecture development, and medical-grade certification expansion.
Atomic layer deposition of aluminum-doped zinc oxide is rendering obsolete conventional sputtered electrode configurations in flexible nanogenerators. Medical textile manufacturers are adopting ALD-coated fiber architectures for implantable and wearable applications. Conformal coating uniformity is eliminating delamination failures that plagued laminated metal foil electrodes.
EU F-Gas Regulation restrictions on fluorinated polymer processing are tightening supply chains for polyvinylidene fluoride film production. Manufacturers are reformulating piezoelectric polymer compositions to reduce perfluorinated content while maintaining β-phase crystallinity. Medical device suppliers in Germany and Switzerland are qualifying alternative ferroelectric polymers for implantable sensor housings.
Direct materials supplier-OEM contracting is displacing traditional component distributor intermediaries in high-volume electronics procurement. Samsung and LG procurement teams are engaging CeramTec and Morgan Advanced Materials for dedicated lead-free ceramic supply agreements. South Korean consumer electronics clusters are consolidating vendor bases to secure capacity allocation and technical collaboration access.
Piezoelectric Nanogenerator Market Segmentation
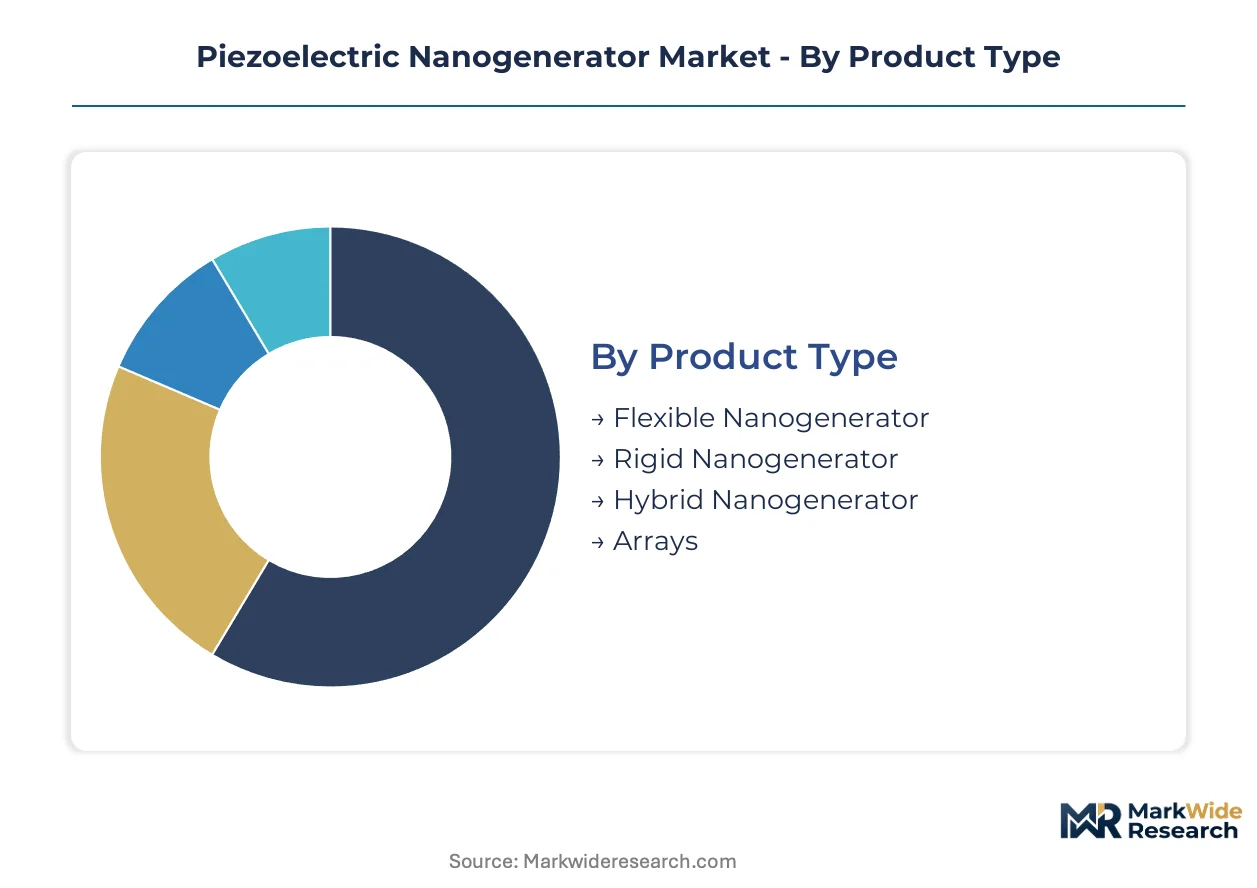
Segmentation in piezoelectric nanogenerators reflects competing pressures between performance optimization, environmental compliance, and manufacturing scalability. Material chemistry and mechanical architecture choices cascade through application suitability, certification pathways, and procurement economics.
Product Type:
Mechanical compliance requirements divide the product landscape between conformable surfaces and fixed installations.
- Flexible Nanogenerator:Thin-film architectures deposited on polyimide or PET substrates enable bending radii below 5mm for skin-contact and textile integration. Samsung and LG procurement teams in South Korea are volume-committing to these modules for biometric sensor arrays in wearable programs.
- Rigid Nanogenerator:Bulk piezoceramic wafers bonded to metal substrates deliver higher power density in vibration harvesting but sacrifice conformability. Industrial IoT deployments in predictive maintenance specify these for machinery-mounted condition monitoring nodes.
- Hybrid Nanogenerator:Combines rigid active layers with flexible interconnects to bridge performance and mechanical compliance. Medical device developers evaluate these for implantable applications requiring both durability and tissue accommodation.
- Arrays:Multiple nanogenerator units wired in series-parallel configurations multiply voltage output for wireless transmission. Smart infrastructure projects specify tiled arrays for roadway and bridge energy harvesting.
Flexible configurations command the established base. The steepest expansion runs through hybrid architectures as medical and industrial applications converge on intermediate compliance specifications.
Material:
Electromechanical coupling efficiency and regulatory compliance status now determine material selection priority.
- Lead Zirconate Titanate:Perovskite-structured ceramics deliver the highest piezoelectric coefficients among commercial materials. EU REACH Phase-out schedules are compressing qualified supply windows as ECHA restrictions tighten across consumer electronics supply chains.
- Barium Titanate:Lead-free perovskite alternative with moderate coupling coefficients and established ceramic processing protocols. Medical device OEMs specify these for implantable energy harvesters requiring biocompatibility certification under EU MDR pathways.
- Polyvinylidene Fluoride:Ferroelectric polymer films processed in β-phase crystallinity enable flexible, biocompatible active layers. EU F-Gas Regulation constraints on fluorinated polymer processing are forcing reformulation to reduce perfluorinated content.
- Zinc Oxide:Semiconducting oxide nanowire arrays grown by hydrothermal or vapor-phase methods offer low-temperature synthesis and environmental benignity. Atomic layer deposition of aluminum-doped formulations is displacing sputtered electrodes in next-generation flexible devices.
Lead Zirconate Titanate retains the installed base. Barium Titanate is climbing the fastest as lead-free mandates propagate through procurement specifications.
Application:
Power density requirements and mechanical loading conditions segment deployment contexts.
- Wearable Devices:Biomechanical energy harvesting from human motion demands sub-milliwatt output with gram-scale mass budgets. Textile-compatible architectures using polyvinylidene fluoride fibers are qualifying for smart apparel programs in South Korean consumer electronics clusters.
- Energy Harvesting:Ambient vibration and mechanical strain conversion for wireless sensor networks requires matched mechanical impedance to source frequencies. Industrial deployments specify zinc oxide nanowire arrays for extended operational lifetime in unmanned installations.
- Biomedical Sensors:Implantable and skin-mounted diagnostics demand hermetic packaging, biocompatibility, and stable electrical output under physiological conditions. FDA 510(k) pathways require extended electrical safety and cytotoxicity testing for cardiac and neuromuscular integrations.
- Structural Health Monitoring:Embedded or surface-mounted sensors detect crack propagation and strain accumulation in civil infrastructure and aircraft components. Aerospace qualification protocols specify rigid ceramic formulations for high-strain environments.
Energy Harvesting anchors current volume. Wearable Devices is gaining share fastest as consumer electronics integration accelerates.
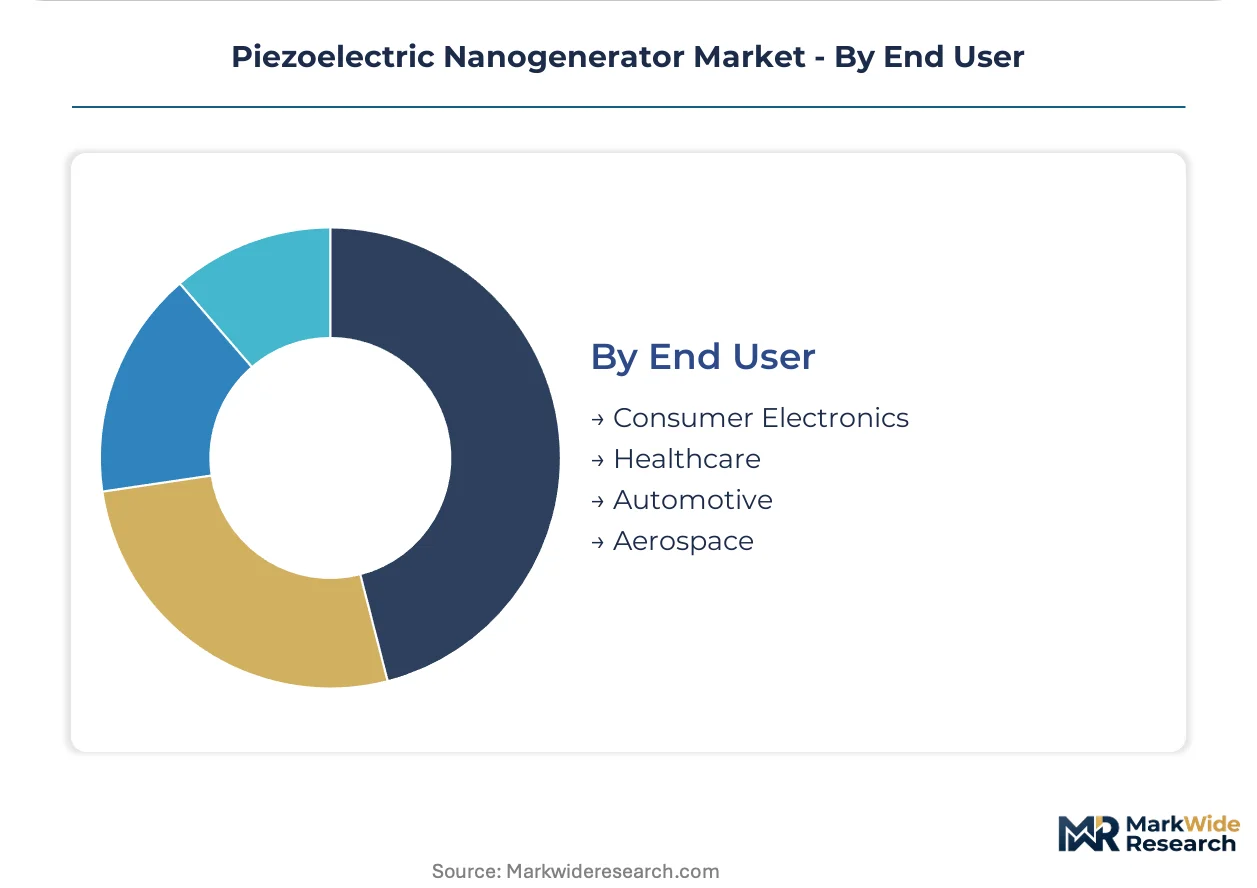
End User:
Certification burden and procurement scale separate addressable customer categories.
- Consumer Electronics:High-volume, cost-constrained procurement with compressed product lifecycles and fashion-driven redesign cycles. Samsung and LG supply chains in South Korea are consolidating vendor bases to secure capacity allocation.
- Healthcare:Extended qualification timelines, stringent biocompatibility requirements, and premium pricing tolerance for implantable and diagnostic applications. German and Swiss medical device suppliers are qualifying alternative ferroelectric polymers under EU MDR.
- Automotive:Vibration energy harvesting for tire pressure monitoring and structural sensing requires AEC-Q200 qualification and temperature extremes tolerance. Indian PLI scheme incentives are attracting module assembly investments for domestic vehicle electrification programs.
- Aerospace:Rigorous reliability standards, traceability requirements, and extended service life specifications for structural monitoring and power scavenging. Certification harmonization through emerging ISO/IEC standards is reducing buyer qualification burden.
Consumer Electronics commands the established base. Healthcare is expanding most quickly as implantable device applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and environmental compliance mandates are redirecting nanogenerator manufacturing capacity toward jurisdictions with active industrial policy support. South Korea, Germany, the United States, India, and Japan concentrate distinct competitive advantages across materials supply, medical device integration, and consumer electronics procurement.
South Korea
Samsung and LG procurement teams are volume-committing to flexible nanogenerator modules for biometric sensor arrays in wearable programs. The MFDS maintains stringent biocompatibility pathways for implantable energy harvesters. Seoul Capital Area fabrication clusters anchor East Asian supply chain consolidation for consumer electronics integration.
Germany
Medical device OEMs in Bavaria and Baden-Württemberg specify lead-free barium titanate compositions for implantable applications under EU MDR pathways. ECHA REACH Phase-out schedules for lead zirconate titanate are compressing qualified supply windows. CeramTec GmbH in Plochingen anchors European medical-grade piezoceramic production.
United States
FDA 510(k) pathways for cardiac and neuromuscular implantable nanogenerators require extended electrical safety testing. The EPA and OSHA maintain workplace exposure standards for piezoceramic powder handling. Greater Boston and Pacific Northwest research clusters concentrate atomic layer deposition expertise for next-generation flexible electrodes.
India
The PLI scheme for electronics manufacturing is attracting nanogenerator module assembly investments for domestic medical device and automotive programs. BIS certification requirements are harmonizing with IEC standards for flexible energy harvesters. Hyderabad and Bengaluru medical device clusters offer captive demand for implantable sensor applications.
Japan
METI funding programs support zinc oxide nanowire array development for industrial IoT vibration harvesting. JIS standards for piezoelectric materials provide qualification benchmarks for export-oriented suppliers. Kanto and Kansai industrial corridors concentrate thin-film deposition foundry capacity for East Asian supply chains.
Piezoelectric Nanogenerator Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated ceramics specialists and diversified electronics conglomerates with captive materials capabilities. Tiered competitive positioning separates premium medical-grade suppliers from volume-driven consumer electronics fabricators. Three archetypes dominate: legacy piezoceramic houses pivoting to lead-free formulations, diversified passive component manufacturers leveraging capacitor expertise, and medical device specialists qualifying implantable-grade materials. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure foundry allocation and OEM technical collaboration access.
Among European ceramics specialists, Morgan Advanced Materials and CeramTec GmbH exemplify the premium medical-grade archetype, occupying positions where biocompatibility certification and materials purity command procurement priority. Murata Manufacturing Co., Ltd. represents the diversified electronics conglomerate model, leveraging vertically integrated capacitor fabrication expertise to anchor East Asian supply. These three companies illustrate how geographic concentration and regulatory proximity shape competitive positioning across the lead-free transition.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Murata Manufacturing Co., Ltd. |
| PI (Physik Instrumente) |
| CeramTec GmbH |
| APC International Ltd. |
| TRS Technologies, Inc. |
| Piezosystem Jena |
| Noliac A/S |
| Kyocera Corporation |
| Others |
Value Network & Pricing Analysis
East Asian thin-film deposition foundries in South Korea and Japan anchor active-layer supply, concentrating margin capture with sputtering equipment operators and ceramic powder specialists while downstream module assemblers compete on scale economies.
Pricing Analysis
Volume-discount tiering separates medical-grade implantable specifications from consumer electronics procurement. Pricing stratifies across premium, standard, and economy tiers based on biocompatibility certification level and active-layer deposition method. Cost compression in standard-tier flexible modules is intensifying because foundry utilization constraints limit batch scaling. Consumer electronics OEMs exhibit highest price sensitivity, while healthcare procurement tolerates premium positioning for FDA-cleared implantable grades.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk planning for ceramic powder and electrode material flows. Active-layer fabrication concentrates in South Korea, Japan, and Germany, drawing from high-purity barium titanate and zinc oxide nanowire feedstocks. Single-source vulnerability in atomic layer deposition equipment creates foundry allocation bottlenecks. Distribution runs through direct supplier-OEM contracting that displaces traditional component distributors in high-volume electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized multiphysics simulation expertise for coupled electromechanical modeling remains scarce relative to commercial deployment timelines, compressing product development windows for firms without captive finite-element talent.
For Market Incumbents: Build certification moats around EU MDR and FDA 510(k) pathways for implantable nanogenerators. Deepen backward integration into lead-free ceramic powder synthesis to secure feedstock continuity during REACH phase-out transitions. Add sputtering capacity in South Korean fabrication clusters to lock in Samsung and LG supply allocation.
For New Entrants and Emerging Players: Establish a beachhead in Indian medical device clusters under PLI scheme incentives, where domestic assembly demand outpaces qualified local supply. Target energy harvesting-textile convergence applications with polyvinylidene fluoride fiber architectures, the most penetrable segment given sportswear pilot program expansion. Lead with ISO/IEC standardization compliance to reduce buyer qualification burden in cross-border procurement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ceramics specialists that completed lead-free reformulation but lack medical-grade certification expansion capital. Long-term viability hinges on implantable device integration maturation over extended regulatory timelines. Watch for FDA breakthrough device designations in cardiac energy harvesting as inflection indicators for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Ceramic Reformulation | REACH compliance opens substitution windows for barium titanate alternatives in EU supply chains. |
| Atomic Layer Deposition Capacity Expansion | ALD-coated electrodes eliminate delamination failures in next-generation flexible medical textiles. |
| Medical-Grade Certification Investment | FDA 510(k) pathways for implantable harvesters command premium positioning in cardiac applications. |
| Direct OEM Supply Agreement | Samsung and LG procurement teams consolidate vendor bases to secure technical collaboration access. |
| Energy Harvesting-Textile Joint Development | Polyvinylidene fluoride fiber spinning enables woven piezoelectric fabrics for military uniform programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with ceramics plant managers, medical device OEM procurement leads, thin-film deposition foundry engineers, and regulatory affairs specialists at notified bodies. Secondary validation drew from ECHA REACH substance restriction updates, FDA 510(k) submission databases, SEC filings from listed component manufacturers, and Korean customs trade statistics for piezoceramic powder imports. Bottom-up module shipment estimates triangulated against top-down addressable market sizing for wearable and implantable applications.
Calibration against historical capacity utilization rates at East Asian sputtering foundries anchored volume projections across the analysis window. Segmentation modeling spanned mechanical architecture, material chemistry, application power density requirements, and end-user certification burden. CAGRs derived from fitted growth curves against regulatory phase-out schedules and OEM procurement commitment timelines. Forecast inputs included EU F-Gas Regulation compliance cost trajectories and India PLI scheme disbursement pacing for electronics manufacturing.
Sensitivities concentrate around thin-film deposition equipment delivery delays, lead-free ceramic sintering protocol yield rates, and FDA electrical safety testing backlog durations. Forecasts reflect documented assumptions regarding REACH enforcement timing and medical device OEM integration roadmaps. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market