
 Metal Additive Manufacturing Systems Market | 2026-2036
Metal Additive Manufacturing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Additive Manufacturing Systems Market Analytics
A widening capital-intensity gap between laser-bed specialists and full-stack platform providers is reorganizing competitive tiers in metal additive manufacturing. EOS GmbH leverages its deep powder-bed fusion heritage to dominate European precision-metal contracts for aerospace and medical implants. GE Additive sustains unmatched vertical scope from superalloy powders to flight-qualified turbine blades, anchoring its position in defense and aviation supply chains. Bright Laser Technologies competes aggressively on machine throughput and localized service density across Asian industrial corridors.
Metal additive manufacturing systems fuse metallic powders or wires using directed energy sources to build dense, near-net-shape components layer by layer, typically achieving relative densities above 99.5% in nickel, titanium, and aluminum alloys for structural and thermal applications. Powder Bed Fusion retains the largest installed base and highest average selling prices among machine architectures, though Binder Jetting is gaining traction for cost-sensitive production runs where post-process sintering tolerances align with end-use requirements. Laser-Based systems lead technology bookings across aerospace tooling and custom orthopedic implant applications, while Electron Beam Melting occupies a specialized niche in reactive-titanium medical and space structures where vacuum environments prevent oxidation.
FAA airworthiness directives and EASA certification memoranda on additive manufacturing are tightening process traceability and material qualification requirements for flight-critical metal parts, elevating compliance costs but locking in qualified suppliers. FDA 21 CFR Part 820 quality system regulations and ISO/ASTM 52900 standards further govern medical-device and cross-border equipment classifications, shaping market access for system vendors and service bureaus alike. Stakeholders must monitor evolving regulator harmonization between FAA and EASA frameworks, as divergent qualification pathways threaten to fragment tooling investments and customer certification strategies across Atlantic supply chains.
Market Dynamics
Flight-certification protocols for additively manufactured metal components are compressing supplier qualification timelines while elevating compliance costs, forcing aerospace primes to consolidate qualified vendor pools and locking out unproven equipment makers from defense and aviation supply chains.
Growth Catalysts
- FAA Airworthiness Directives:Accelerated qualification pathways for critical flight components are expanding addressable demand within aerospace engine manufacturing, pulling investment toward certified production systems.
- Titanium Powder Bed Fusion:Reactive-alloy processing capabilities in vacuum or inert environments are unlocking structural applications in orbital launch vehicles and orthopedic implants where conventional machining fails.
- German Precision-Engineering Cluster:Dense supplier networks around EOS GmbH and SLM Solutions in Bavaria and North Rhine-Westphalia are concentrating R&D spillover and skilled technician pools.
Market Restraints
- Argon and Helium Supply Concentration:Inert gas dependencies for reactive metal processing expose machine operators to price volatility from Russian and Qatari supply disruptions.
- Post-Process Sintering Tolerance Limits:Binder Jetting's dimensional variability in green-state parts restricts adoption for tight-tolerance rotating machinery, capping addressable share in turbine applications.
- EASA-FAA Qualification Divergence:Non-harmonized certification memoranda force dual-track qualification investments, inflating compliance overhead for transatlantic suppliers.
Strategic Opportunities
- India Production-Linked Incentive Scheme:PLI scheme offsets for advanced manufacturing equipment are attracting machine vendors to establish localized service and powder supply operations in Pune and Bengaluru corridors.
- Copper and Refractory Metal Printing:Emerging laser and electron beam parameter sets for high-thermal-conductivity alloys are opening heat-exchanger and RF component applications in satellite and power electronics.
- Contract Manufacturing Channel Expansion:Service bureau networks are absorbing capital burden from mid-tier manufacturers, creating equipment pull-through from qualified production partners rather than direct machine sales.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Shortage of engineers capable of integrating thermal, mechanical, and microstructural modeling slows process development cycles for new alloy qualifications.
- ISO/ASTM 52900 Implementation Gaps:Inconsistent auditor interpretation of powder characterization and build-chamber monitoring standards delays facility certifications and customer approvals.
- Legacy MES Integration Friction:Proprietary machine data formats from incumbent vendors resist seamless connection to plant-wide quality systems, complicating traceability for regulated industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Additive Manufacturing Systems Market |
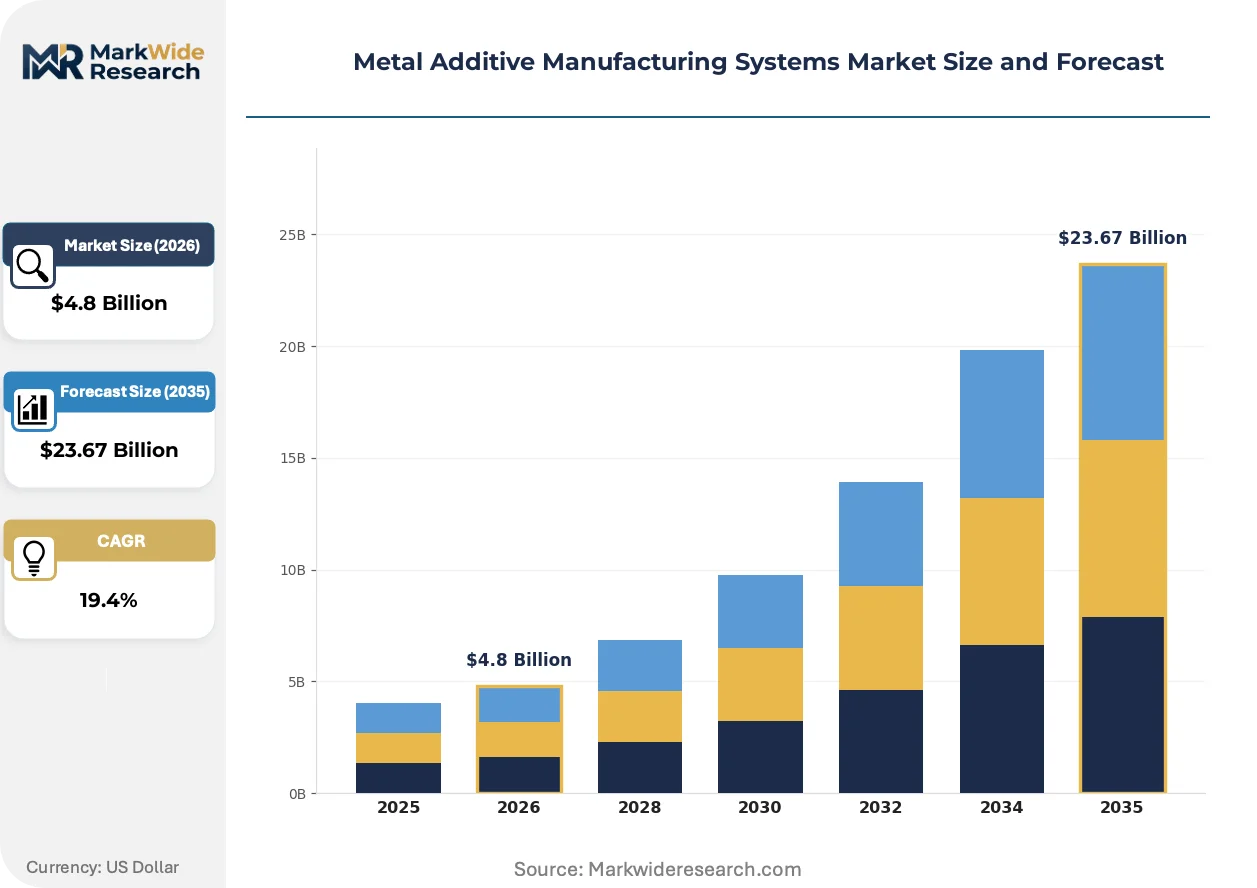
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $23.67 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Bed Fusion, Directed Energy Deposition, Material Extrusion, Binder Jetting End User: Aerospace, Automotive, Healthcare, Industrial Equipment Technology: Laser-Based, Electron Beam Melting, Hybrid Systems, Metal Injection Molding Application: Prototyping, Tooling, Production Parts, Custom Components |
| Companies Covered | EOS GmbH, 3D Systems, Inc., SLM Solutions, Renishaw plc, GE Additive, DMG MORI, Bright Laser Technologies, Velo3D, AddUp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Additive Manufacturing Systems Market Evolving Landscape
Process monitoring and closed-loop control architectures are displacing open-loop parameter sets as the baseline for production-qualified metal additive systems, reshaping equipment roadmaps and service revenue models simultaneously.
Hybrid manufacturing workflows combining directed energy deposition with CNC finishing are fragmenting the traditional boundary between near-net-shape additive and subtractive precision machining. Defense contractors and heavy equipment rebuilders in the US and Germany are piloting these cells for worn component restoration and structural repair. The technology is fragmenting capital allocation decisions, forcing machine buyers to evaluate integrated cells rather than standalone additive units.
REACH restrictions on nickel and cobalt compound emissions are tightening powder handling and waste management requirements for European machine operators and service bureaus. The regulation is elevating capital costs for extraction and filtration systems while favoring enclosed, automated powder management architectures over manual operations. Medical implant manufacturers in Ireland and Switzerland are accelerating migration to closed-loop systems ahead of enforcement deadlines.
Buyer preference is consolidating around qualified production partners rather than in-house machine ownership among mid-tier aerospace and medical device firms. Capital constraints and certification complexity are pushing procurement toward guaranteed-output contracts with certified service bureaus in Germany, Singapore, and the US. This channel shift is compressing direct equipment sales cycles while expanding recurring revenue streams for vertically integrated platform providers.
Metal Additive Manufacturing Systems Market Segmentation
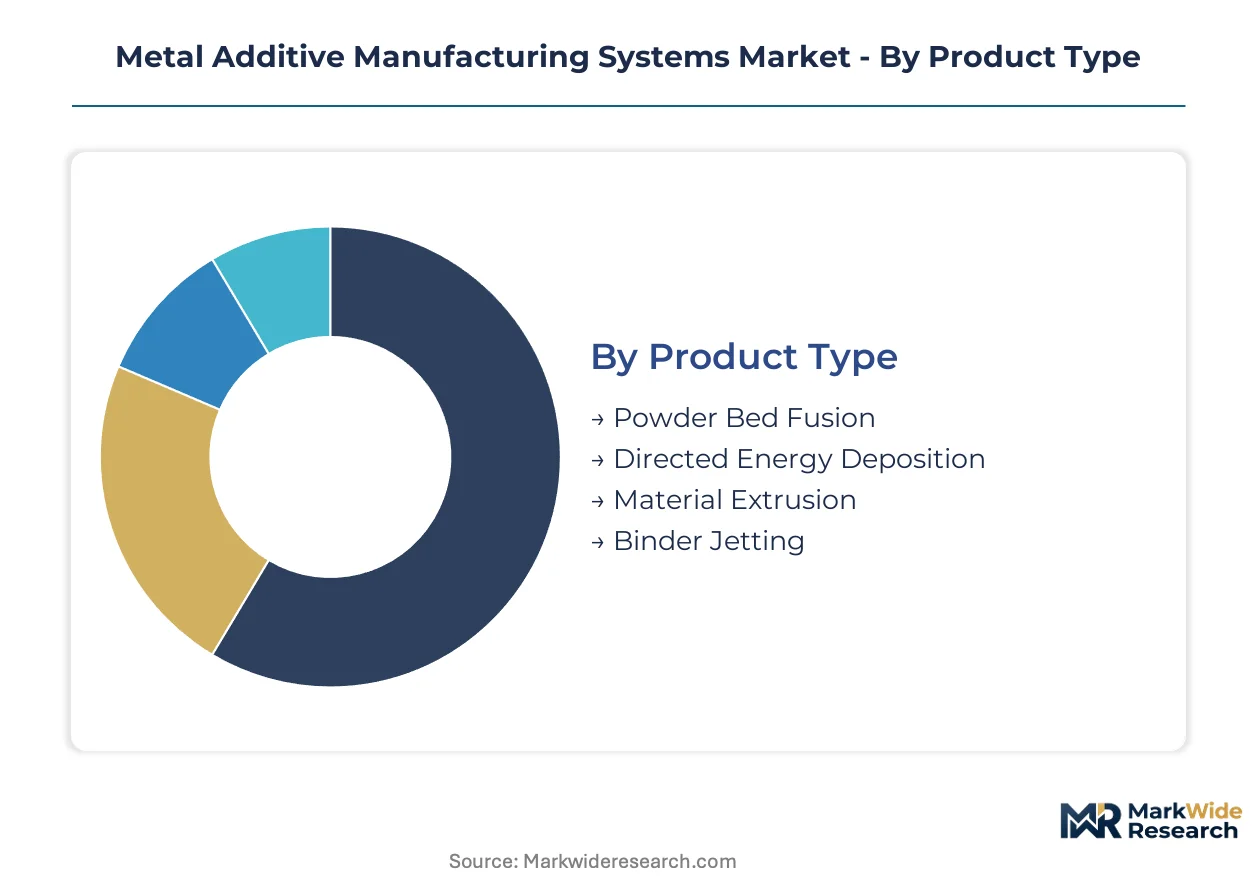
Segmentation in metal additive manufacturing reveals how technology architecture, end-use requirements, and certification barriers partition addressable demand. Equipment purchasing patterns diverge sharply between flight-critical aerospace programs and cost-sensitive industrial tooling, forcing vendors to configure distinct commercial approaches for each slice.
Product Type:
German and US manufacturers dominate Powder Bed Fusion exports, while Asian demand pulls Directed Energy Deposition through localized service partnerships.
- Powder Bed Fusion:Laser or electron beam selectively melts successive layers of metallic powder within a controlled atmosphere, achieving relative densities above 99.5% in nickel superalloys and titanium. Demand concentrates in aerospace engine manufacturing across Germany and the US, where FAA airworthiness certification locks in qualified machine architectures. The installed base commands premium pricing and longest replacement cycles.
- Directed Energy Deposition:Feedstock wire or powder melts under focused thermal energy to build or repair large structures, depositing material at rates exceeding Powder Bed Fusion by an order of magnitude. Repair applications in US defense and German heavy equipment drive procurement, with hybrid CNC integration expanding addressable use cases. The technology climbs fastest in worn-component restoration workflows.
- Material Extrusion:Bound metal filament extrudes through heated nozzles before debinding and sintering, lowering capital barriers for entry-level metal printing.
- Binder Jetting:Liquid binder selectively joins metal powder layers before furnace sintering, enabling batch production of stainless steel tooling at reduced cycle costs.
Powder Bed Fusion commands the established base. The steepest expansion runs through Directed Energy Deposition.
End User:
Aerospace primes absorb the highest machine prices, while Industrial Equipment buyers prioritize throughput metrics over qualification pedigree.
- Aerospace:Turbine blade, structural bracket, and fuel nozzle production for commercial and defense aviation. FAA and EASA certification protocols force dual-track qualification investments, consolidating procurement among vertically integrated platform providers with captive powder supply. German precision-engineering clusters anchor European demand.
- Healthcare:Patient-specific orthopedic implants and surgical instrumentation in titanium and cobalt-chrome alloys. FDA 21 CFR Part 820 quality system regulations and ISO/ASTM 52900 standards govern facility qualification, with Swiss and Irish manufacturers migrating to closed-loop powder systems ahead of REACH enforcement.
- Automotive:Motorsport components and luxury vehicle customization drive selective adoption, with series production remaining limited by cost-per-part economics.
- Industrial Equipment:Mold tooling, jigs, and fixturing applications where dimensional tolerance requirements align with Binder Jetting capabilities.
Aerospace absorbs the premium tier. Healthcare gains share fastest as regulatory pathways mature.
Technology:
Laser-Based systems span the widest geographic footprint, while Electron Beam Melting concentrates in vacuum-dependent reactive alloy processing.
- Laser-Based:Fiber or CO2 laser sources melt metallic feedstock across Powder Bed Fusion and Directed Energy Deposition architectures. The technology spans aerospace tooling in Germany, medical implants in Switzerland, and industrial repair in the US, with parameter development for copper and refractory alloys unlocking satellite heat-exchanger applications.
- Electron Beam Melming:High-energy electron beams melt powder layers within vacuum chambers, preventing oxidation of reactive titanium and aluminum alloys. Orbital launch vehicle structures and orthopedic implants in Sweden and the US drive specialized demand, with vacuum infrastructure requirements limiting installation flexibility.
- Hybrid Systems:Combined additive and subtractive cells integrate Directed Energy Deposition with CNC finishing in single platforms.
- Metal Injection Molding:Conventional powder metallurgy process competing for high-volume small-component production against emerging Binder Jetting alternatives.
Laser-Based technology holds the volume lead. Hybrid Systems expand most quickly as capital allocation shifts toward integrated cells.
Application:
Production Parts demand pulls the longest sales cycles, while Prototyping concentrates in service bureau networks with shorter equipment refresh intervals.
- Production Parts:Flight-certified components, implantable medical devices, and qualified industrial hardware manufactured under regulated quality systems. Aerospace engine manufacturers in Germany and the US constitute the fastest-expanding buyer segment as FAA airworthiness directives compress supplier qualification timelines.
- Tooling:Conformal-cooled molds, die inserts, and manufacturing aids where additive geometries outperform conventional machining. Automotive and industrial equipment sectors in Germany and Japan drive replacement of P20 and H13 steel tooling.
- Prototyping:Design validation and form-fit-function testing prior to hard tooling commitment, concentrated in contract manufacturing channels.
- Custom Components:Low-volume specialized hardware for defense, research, and luxury applications.
Tooling represents the established revenue base. Production Parts capture the steepest trajectory as certification barriers convert to competitive moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German precision-engineering clusters while US defense procurement absorbs premium qualification costs. Aerospace certification timelines and powder supply security now dictate regional equipment deployment patterns.
United States
FAA airworthiness directives compress supplier qualification timelines for flight-critical components. Defense contractors anchor demand in the Southeast and Texas corridors. GE Additive sustains vertical scope from superalloy powders to qualified turbine blades across these regions.
Germany
EOS GmbH and SLM Solutions anchor dense supplier networks in Bavaria and North Rhine-Westphalia. REACH restrictions on nickel and cobalt emissions tighten powder handling requirements for European operators. Medical implant manufacturers in Baden-Württemberg accelerate migration to closed-loop systems.
China
Bright Laser Technologies competes aggressively on machine throughput across Asian industrial corridors. MIIT standards for advanced manufacturing equipment shape local certification pathways. Yangtze River Delta clusters concentrate R&D spillover for laser-based systems.
India
Production-Linked Incentive scheme offsets attract machine vendors to establish localized service operations. CDSCO quality system regulations govern medical device qualification timelines. Pune and Bengaluru corridors concentrate contract manufacturing channel expansion.
Japan
METI industrial technology roadmaps prioritize hybrid manufacturing workflows combining additive with CNC finishing. Kansai and Chubu regions pilot worn-component restoration cells for heavy equipment rebuilders. JIS standards implementation gaps delay facility certifications for new entrants.
Metal Additive Manufacturing Systems Market Competitive Landscape
Concentration sits with laser-bed specialists and full-stack platform providers that control captive powder supply. The vendor base organizes around three strategic archetypes: European precision-metal contract specialists, vertically integrated aerospace primes, and Asian throughput-focused fabricators. Consolidation pressures intensify as FAA and EASA qualification divergence forces dual-track compliance investments. M&A activity targets qualified production partners rather than standalone equipment makers.
Within the European precision-engineering tier, EOS GmbH and SLM Solutions represent the established heritage in powder-bed fusion architectures. GE Additive occupies a position exemplifying vertical integration from material feedstock through flight-qualified component delivery. Bright Laser Technologies anchors the Asian competitive vector through localized service density and machine throughput optimization across industrial corridors.
| Leading Market Players |
|---|
| EOS GmbH |
| 3D Systems, Inc. |
| SLM Solutions |
| Renishaw plc |
| GE Additive |
| DMG MORI |
| Bright Laser Technologies |
| Velo3D |
| AddUp |
| Others |
Value Network & Pricing Analysis
Fourteen-week lead times for certified superalloy powders concentrate pricing power with German and US suppliers who maintain FAA-qualified material streams, while buyers absorbing REACH compliance costs face compressed negotiation leverage on machine procurement.
Pricing Analysis
Configured-to-order pricing for flight-qualified Powder Bed Fusion systems commands spreads exceeding standard industrial configurations by factors tied to certification pedigree. Three-tier pricing structure across premium flight-certified, standard production, and economy prototyping levels segments buyer access, with aerospace primes absorbing premium tiers and mid-tier manufacturers migrating toward contract manufacturing channels. Cost compression in economy-tier Binder Jetting systems intensifies as Asian vendors optimize throughput metrics, though price sensitivity concentrates most acutely among industrial equipment buyers lacking qualification burdens.
Supply Chain Analysis
Strategic stockpiling of argon and helium dominates inventory strategy among European operators confronting Russian supply disruption risks, while just-in-time powder replenishment persists for non-reactive alloys. Feedstock supply concentrates in Germany, China, and the US for titanium and nickel superalloy powders, with machine architecture drawing from specialized laser source providers in Japan and Germany. Single-source vulnerability in inert gas supply chains threatens operational continuity, while distribution runs through qualified service bureau networks rather than direct OEM channels for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal additive manufacturing systems face substitution pressure from advanced CNC machining and hybrid manufacturing workflows that fragment capital allocation decisions away from standalone additive units.
For Market Incumbents: Fortify captive powder supply positions through backward integration into gas atomization capacity, locking in material traceability for FAA qualification pathways. Accelerate closed-loop process monitoring architectures to defend against emerging hybrid CNC-additive cells that threaten near-net-shape applications in heavy equipment restoration. For New Entrants and Emerging Players: Contract manufacturing service gaps in India's Pune and Bengaluru corridors offer white-space entry where PLI scheme offsets reduce capital barriers. Target medical implant production partnerships in Swiss and Irish markets migrating toward closed-loop powder systems ahead of REACH enforcement deadlines, leveraging localized technical service density as the primary go-to-market wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace prime captive AM divisions seeking to monetize non-core equipment manufacturing capabilities. Long-term viability hinges on qualification moats rather than machine throughput metrics, with acquisition focus on service bureaus holding dual FAA-EASA certification. Watch EASA-FAA harmonization negotiations as the critical inflection signal; convergence would compress dual-track compliance overhead and revalue qualified asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Supply Integration | Backward integration into gas atomization secures FAA traceability requirements for flight-critical superalloy feedstock. |
| Closed-Loop Process Control Deployment | Real-time melt pool monitoring architectures displace open-loop parameter sets as the production qualification baseline. |
| Hybrid Manufacturing Cell Partnership | Directed Energy Deposition-CNC integration expands addressable share in worn-component restoration and heavy equipment repair. |
| Service Bureau Network Expansion | Qualified production partnerships absorb capital burden from mid-tier buyers, shifting revenue from equipment sales to output contracts. |
| Dual Certification Pathway Investment | Simultaneous FAA and EASA qualification hedges against regulatory divergence while locking in transatlantic supplier status. |
Research Methodology
Operator-level perspectives from powder metallurgy engineers, aerospace procurement leads, medical device quality managers, and service bureau operations directors anchored the qualitative base. Primary interview findings triangulated against secondary sources including FAA airworthiness directive filings, EASA certification memoranda, ISO/ASTM 52900 implementation audits, and customs trade data for metal powder flows. Bottom-up equipment shipment analysis and top-down end-use demand modeling converged on segment-level estimates.
Sensitivity analysis tested forecast outputs against variable penetration scenarios for Binder Jetting adoption and hybrid manufacturing displacement across the projection horizon. Segmentation dimensions modeled include technology architecture, end-use industry, certification tier, and geographic regulatory cluster. CAGRs derived from equipment replacement cycles, greenfield facility commissioning rates, and qualified supplier capacity expansion trajectories, with specific inputs capturing titanium powder price volatility and inert gas supply disruption probabilities.
Forecasts assume regulatory continuity in FAA and EASA frameworks; material policy shifts toward harmonized or divergent qualification pathways would require re-modeling. Revision becomes warranted when EASA-FAA memoranda alignment crosses implementation thresholds or when argon supply concentration triggers sustained price shocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
North America Wigig Market