
 Inp Lasers Market | 2026-2036
Inp Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Inp Lasers Market Analytics
Equipment leasing and project finance for photonics foundries is reshaping competitive entry barriers in the InP Lasers Market. Coherent leverages captive epitaxial growth capacity to sustain wafer-level cost structures. Lumentum anchors North American supply chains through vertical control over chip-on-carrier assembly. MACOM competes via merchant foundry partnerships that reduce capital intensity for specialized telecom customers.
Indium phosphide lasers are semiconductor devices fabricated from III-V compound wafers emitting in the 1.0–2.0 μm wavelength range, with distributed feedback gratings enabling single-mode operation critical for coherent optical transmission. DFB technology dominates telecommunications backbone deployments where narrow linewidth requirements exceed gallium arsenide capabilities. Quantum cascade architectures are capturing sensing applications requiring mid-infrared emission for gas spectroscopy. Fiber laser product types occupy industrial material processing segments where beam quality and thermal stability determine equipment selection.
FCC equipment authorization rules govern laser product imports into the United States, while CE marking under the EU RoHS directive restricts hazardous substance content in optoelectronic components. China's MIIT issues compulsory certification for optical communication equipment deployed in state-backed broadband infrastructure. Stakeholders must monitor evolving spectrum allocation decisions and foundry utilization rates as capacity constraints ripple through epitaxial wafer supply chains.
Market Dynamics
Epitaxial wafer supply concentration in East Asian foundries is compressing lead times and amplifying price volatility for InP laser manufacturers serving datacenter interconnect buildouts.
Growth Catalysts
- MIIT optical equipment standards:China's compulsory certification requirements for state-backed broadband infrastructure are mandating higher-performance indium phosphide components in 400G and 800G coherent transmission systems.
- Datacenter interconnect buildouts:Hyperscale operators in Virginia, Frankfurt, and Singapore are deploying coherent optical engines requiring narrow-linewidth DFB lasers for intra-campus and metro links.
- Silicon photonics co-packaging:The convergence of InP light sources with silicon photonic modulators is enabling pluggable coherent transceivers that slash power consumption in cloud switching fabrics.
Market Restraints
- Indium metal price volatility:Refining capacity constraints and geopolitical trade flows are amplifying input cost swings for III-V compound substrate production.
- Single-source epitaxial dependence:Merchant foundry concentration in Taiwan and Japan creates vulnerability to seismic disruption and export control friction.
- Gallium arsenide substitution in access networks:Lower-cost GaAs DFB lasers are capturing price-sensitive 25G and 50G PON deployments where linewidth tolerance permits.
Strategic Opportunities
- Quantum cascade sensing expansion:Mid-infrared spectroscopy applications in oilfield methane monitoring and industrial emissions compliance are opening volume channels outside telecommunications.
- US CHIPS Act fab incentives:Domestic epitaxial growth capacity investments in Arizona and Texas are creating geographic diversification options for defense-qualified supply chains.
- Lidar integration partnerships:Automotive Tier 1s are qualifying 1550nm InP lasers for long-range FMCW systems, transferring telecom reliability standards to mobility applications.
Industry Challenges
- MOCVD reactor operator scarcity:Specialized epitaxial growth technicians command premium wages as compound semiconductor training programs lag equipment deployment.
- FCC equipment authorization timelines:Laser product import certification delays are extending customer qualification cycles for North American telecom deployments.
- RoHS exemption management:EU hazardous substance restrictions on lead-based solders and cadmium-containing coatings are forcing process requalification for chip-on-carrier assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inp Lasers Market |
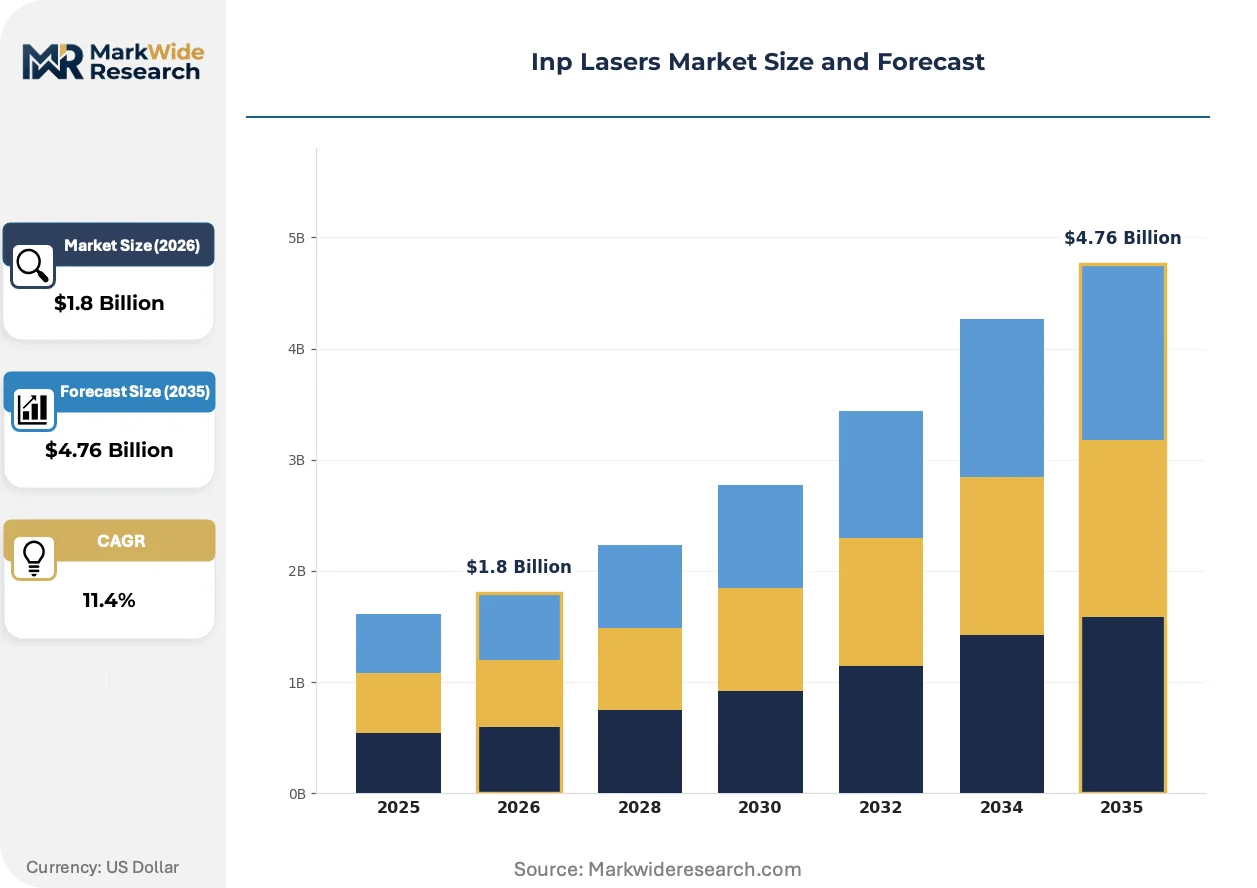
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Quantum Cascade, Dispersion-Managed, DFB, VECSEL End User: Telecommunications, Medical Devices, Industrial Applications, Research Facilities Application: Sensing, Imaging, Communication, Material Processing Product Type: Laser Diodes, Fiber Lasers, Solid-State Lasers, Others |
| Companies Covered | MACOM, Lumentum, Coherent, InPhenix, Sheaumann Laser, SemiNex, Eblana Photonics, Akela Laser, Oxford Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inp Lasers Market Evolving Landscape
Process integration advances and regulatory pressure on energy efficiency are compressing the technology refresh cycle across optical communications infrastructure.
Hybrid silicon-InP integration is collapsing the cost structure of coherent optical engines by bonding III-V gain sections directly onto silicon photonic interposers. Cloud operators in Oregon and Dublin are qualifying these co-packaged assemblies for 800G ZR+ transceivers. The elimination of discrete laser packages is collapsing subsystem footprint and thermal management overhead in faceplate-constrained router designs.
EU F-Gas Regulation phase-down schedules are restricting sulfur hexafluoride use in semiconductor etching processes, forcing foundries to adopt alternative chemistries for InP grating fabrication. German and Dutch epitaxial houses are retooling plasma etch platforms to maintain linewidth precision under modified process chemistries. This regulatory compression is accelerating capital refresh cycles for European photonics manufacturing infrastructure.
Hyperscale procurement teams are consolidating vendor panels and demanding multi-year fixed-price agreements with volume commitments, displacing spot-market purchasing for high-volume datacenter interconnect programs. This concentration is compressing margins for merchant laser suppliers while favoring captive-integrated component divisions. The shift is most visible in Singapore and Northern Virginia, where cloud campus buildouts dominate coherent optical demand.
Inp Lasers Market Segmentation
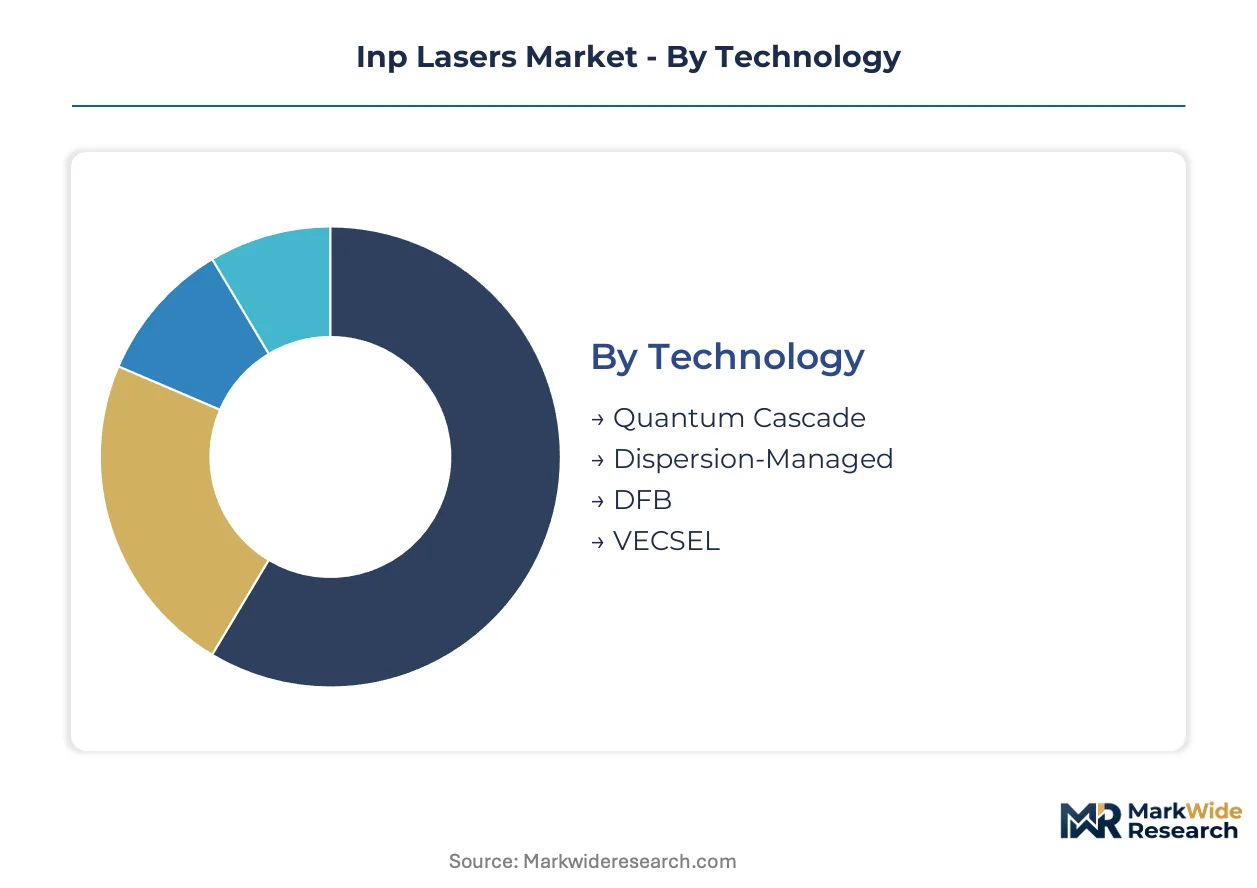
InP laser segmentation reveals how wavelength precision requirements and thermal management constraints fragment addressable markets across telecommunications, sensing, and industrial domains. Technology choice determines epitaxial growth complexity and foundry qualification pathways. Product architecture governs packaging density and power dissipation profiles in end-use equipment.
Technology:
Cost tier stratification separates merchant-foundry-dependent designs from captive-integrated architectures requiring MOCVD reactor investments.
- DFB:Distributed feedback gratings etched into InP substrates enable single-mode emission with sub-MHz linewidth, essential for coherent optical transmission. Hyperscale datacenter interconnect programs in Singapore and Virginia are specifying these devices for 400G and 800G pluggable transceivers, with MIIT certification requirements in China tightening performance benchmarks for state-backed broadband infrastructure.
- Quantum Cascade:Intersubband transitions in engineered quantum wells generate mid-infrared emission without interband recombination, enabling room-temperature operation at 4–10 μm wavelengths. Oilfield methane monitoring in Texas and North Dakota plus EU F-Gas Regulation compliance programs are expanding volume channels outside traditional telecommunications.
- Dispersion-Managed:Chirped grating structures compensate chromatic dispersion in long-haul fiber links, preserving pulse integrity across submarine cable systems.
- VECSEL:Vertical external-cavity surface-emitting lasers combine semiconductor gain with external resonator optics, delivering high beam quality for precision sensing applications.
DFB holds installed capacity. Quantum Cascade is rotating up the share rankings.
End User:
Application maturity determines procurement sophistication, with telecommunications buyers demanding multi-year fixed-price agreements while research facilities tolerate spot-market volatility.
- Telecommunications:Coherent optical engine manufacturers in Germany, Japan, and the United States consume narrow-linewidth devices for backbone and metro networks. FCC equipment authorization timelines and RoHS exemption management for lead-based solders are extending qualification cycles for North American deployments.
- Industrial Applications:Material processing and precision manufacturing operations require thermal stability under high-duty-cycle operation. German machine tool builders and Japanese factory automation integrators are qualifying 1550nm sources for direct-diode welding systems.
- Medical Devices:Ophthalmic and dermatological equipment manufacturers specify wavelength stability for therapeutic and diagnostic platforms.
- Research Facilities:National laboratories and university consortia purchase low-volume, high-specification devices for spectroscopy and quantum communication experiments.
Telecommunications commands procurement scale. Industrial Applications are climbing the fastest.
Application:
Volume concentration varies sharply by use case, with communication applications consuming wafer-scale quantities while sensing maintains premium pricing.
- Communication:Datacenter interconnect and coherent transmission systems absorb the majority of DFB laser output. Cloud operators in Oregon, Dublin, and Singapore are consolidating vendor panels and demanding volume commitments for 800G ZR+ transceiver programs.
- Sensing:Gas spectroscopy, LIDAR, and environmental monitoring applications exploit the tunability and linewidth characteristics of InP devices. Automotive Tier 1 suppliers are qualifying 1550nm sources for long-range FMCW LIDAR systems.
- Imaging:Optical coherence tomography and industrial inspection systems utilize swept-source and broadband emitters.
- Material Processing:Direct-diode and fiber-coupled systems compete with solid-state alternatives in cutting and welding operations.
Communication dominates wafer consumption. Sensing is gaining share fastest.
Product Type:
Packaging architecture determines thermal management overhead and subsystem integration complexity in faceplate-constrained equipment.
- Laser Diodes:Bare chip and chip-on-carrier formats enable hybrid silicon-InP integration, collapsing footprint and power consumption in co-packaged coherent engines. Elimination of discrete packages is accelerating adoption in cloud switching fabrics.
- Fiber Lasers:InP-pumped or InP-seeded systems deliver high beam quality for industrial material processing where thermal stability determines equipment selection.
- Solid-State Lasers:Diode-pumped configurations utilize InP pump sources for frequency conversion and amplification stages.
- Others:Integrated photonic assemblies and custom module formats serve specialized defense and scientific applications.
Laser Diodes anchor manufacturing scale. Fiber Lasers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CHIPS Act is channeling subsidies toward domestic epitaxial growth capacity, reshaping geographic sourcing patterns for defense-qualified supply chains. China tightened MIIT performance benchmarks for optical communications equipment in 2024. European foundries face accelerated capital refresh cycles under F-Gas Regulation phase-down schedules.
United States
Hyperscale datacenter buildouts in Northern Virginia and Oregon are consuming narrow-linewidth DFB lasers for 800G coherent transceivers. FCC equipment authorization timelines extend qualification cycles for telecom deployments. Arizona and Texas are attracting epitaxial growth investments under CHIPS Act incentives, creating domestic alternatives to East Asian wafer supply.
China
State-backed broadband infrastructure programs are mandating InP components for 400G and 800G coherent transmission systems under compulsory MIIT certification. The country's national standards body issues tightened performance benchmarks annually. Yangtze River Delta manufacturing clusters serve domestic datacenter interconnect programs while exporting to Southeast Asian markets.
Germany
Industrial automation integrators and machine tool builders are qualifying 1550nm sources for direct-diode welding systems. ECHA oversees RoHS compliance for lead-based solders in chip-on-carrier assembly. Bavarian and North Rhine-Westphalian epitaxial houses are retooling plasma etch platforms to maintain linewidth precision under modified F-Gas Regulation chemistries.
Japan
Telecommunications equipment manufacturers source DFB lasers for submarine cable and metro network deployments. METI coordinates national photonics initiatives supporting compound semiconductor training programs. Tokyo-Osaka industrial corridors concentrate merchant foundry capacity for III-V epitaxial wafers serving regional supply chains.
Singapore
Cloud campus expansions are consolidating vendor panels and demanding multi-year fixed-price agreements for coherent optical engines. The country's national telecommunications regulator monitors spectrum allocation decisions affecting datacenter interconnect buildouts. Jurong and Tuas manufacturing zones host assembly operations for pluggable transceiver programs serving Asia-Pacific hyperscale operators.
Inp Lasers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure favoring captive-integrated architectures over merchant-foundry dependence. Consolidation pressure concentrates around epitaxial growth capacity and chip-on-carrier assembly capabilities. Three archetypes dominate: vertically integrated device manufacturers with in-house MOCVD reactors, merchant laser suppliers leveraging external foundry partnerships, and hybrid silicon-InP integrators collapsing packaging overhead. Capacity expansion and strategic partnerships represent the dominant competitive moves as stakeholders secure wafer supply and qualification pathways.
Among North American suppliers, Coherent and Lumentum occupy distinct positions within the integrated-device tier, while MACOM exemplifies the merchant-foundry partnership model. Coherent represents captive epitaxial growth capacity sustaining wafer-level cost structures. Lumentum anchors supply chain positioning through upstream control over chip-on-carrier assembly. MACOM competes via reduced capital intensity arrangements serving specialized telecom customers.
| Leading Market Players |
|---|
| MACOM |
| Lumentum |
| Coherent |
| InPhenix |
| Sheaumann Laser |
| SemiNex |
| Eblana Photonics |
| Akela Laser |
| Oxford Instruments |
| Others |
Value Network & Pricing Analysis
The Kaohsiung-to-Long Beach transpacific corridor carries epitaxial wafer shipments where container rate volatility amplifies landed cost spreads between captive-integrated and merchant-foundry-dependent suppliers, compressing margins for spot-market purchasers while rewarding long-term contract holders with price stability.
Pricing Analysis
Certification level creates the primary spread across the InP laser market, with MIIT-compulsory and CE-marked devices commanding substantial premia over commercial-grade alternatives lacking telecom infrastructure qualification. Three-tier pricing structure across defense-qualified, telecom-certified, and industrial-commercial levels reflects the cost of regulatory compliance and foundry qualification pathways. Price erosion runs through the industrial-commercial tier as gallium arsenide substitutes capture cost-sensitive access network deployments. Telecommunications equipment manufacturers exhibit lowest price sensitivity due to multi-year vendor panel commitments, while research facilities and industrial integrators negotiate aggressively on unit economics.
Supply Chain Analysis
Export control restrictions on MOCVD reactor technology and indium phosphide substrate manufacturing equipment limit capacity expansion outside East Asian jurisdictions, constraining geographic diversification efforts despite CHIPS Act incentives. Epitaxial wafer supply concentrates in Taiwan, Japan, and China, with merchant foundry dependence creating single-source vulnerability for North American and European device manufacturers. Raw material flows draw from Chinese indium refining capacity, Japanese substrate polishing operations, and German precursor chemical production. Distribution runs through chip-on-carrier assembly houses in Singapore and Malaysia before final integration into pluggable transceiver modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The InP laser market sustains durable competitive moats through regulatory entrenchment, where MIIT certification timelines and FCC equipment authorization cycles create switching costs that lock qualified suppliers into long-term procurement relationships.
For Market Incumbents: Insulate wafer supply positions through captive epitaxial growth investments in Arizona and Texas under CHIPS Act incentives, while accelerating chip-on-carrier automation to offset MOCVD reactor operator scarcity. Defensive consolidation around foundry qualification pathways will raise barriers against merchant-foundry-dependent challengers facing single-source vulnerability in Taiwan and Japan. For New Entrants and Emerging Players: Quantum cascade sensing applications in methane monitoring and emissions compliance represent the most penetrable entry point outside telecommunications procurement concentration, with oilfield operators in Texas and North Dakota tolerating spot-market purchasing. Automotive FMCW LIDAR qualification programs offer a secondary channel where telecom reliability standards transfer to mobility applications with modified packaging requirements. For Investors and Strategic Acquirers: Merchant laser suppliers with established foundry partnerships and MIIT certification pathways present acquisition targets with embedded regulatory entrenchment and hyperscale vendor panel positioning. Monitor foundry utilization rates and export control friction indices as inflection signals for supply-constraint-driven pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Epitaxial Growth Investment | CHIPS Act subsidies in Arizona and Texas reduce dependence on Taiwanese merchant foundry capacity. |
| MIIT Certification Acceleration | Compulsory Chinese optical equipment standards lock suppliers into state-backed broadband infrastructure programs. |
| Hybrid Silicon-InP Integration | Co-packaged coherent engines slash power consumption for 800G ZR+ transceivers in Oregon and Dublin cloud campuses. |
| Quantum Cascade Sensing Expansion | Mid-infrared spectroscopy opens volume channels in Texas oilfield methane monitoring outside telecom procurement. |
| MOCVD Operator Training Programs | METI-coordinated Japanese initiatives address specialized epitaxial technician scarcity compressing foundry expansion. |
Research Methodology
A spread of perspectives from epitaxial growth technicians, telecommunications procurement directors, cloud hyperscale infrastructure planners, and compound semiconductor equipment manufacturers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with MOCVD reactor operators and chip-on-carrier assembly managers alongside secondary validation through SEC 10-K filings, MIIT certification databases, and hyperscaler capital expenditure disclosures. Bottom-up wafer consumption estimates and top-down coherent transceiver deployment projections were triangulated to anchor segmentation outputs.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with technology segmentation by DFB, quantum cascade, and hybrid integration architectures crossed against end-user procurement sophistication tiers. CAGRs were derived from installed base replacement cycles, datacenter interconnect buildout trajectories, and regulatory-driven equipment refresh mandates. Forecast inputs incorporated F-Gas Regulation phase-down schedules affecting European foundry etching chemistries and indium metal price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, cloud infrastructure deployment timelines, or compound semiconductor trade flows would shift the trajectory. Material shifts in export control regimes, foundry qualification pathways, or substitute technology performance thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market