
 Lab-On-A-Chip Device Market | 2026-2036
Lab-On-A-Chip Device Market Size, Share, and Industry Trends Forecast 2026-2036
Lab-On-A-Chip Device Market Outlook
Buyer concentration among hospital networks and pharmaceutical companies is decoupling from traditional centralized laboratory procurement patterns. Thermo Fisher Scientific leverages its reagent-chip integration capabilities to anchor long-term supply contracts with major health systems. Danaher Corporation competes through vertical control over microfluidic manufacturing workflows, sustaining margin advantages in high-complexity assay development.
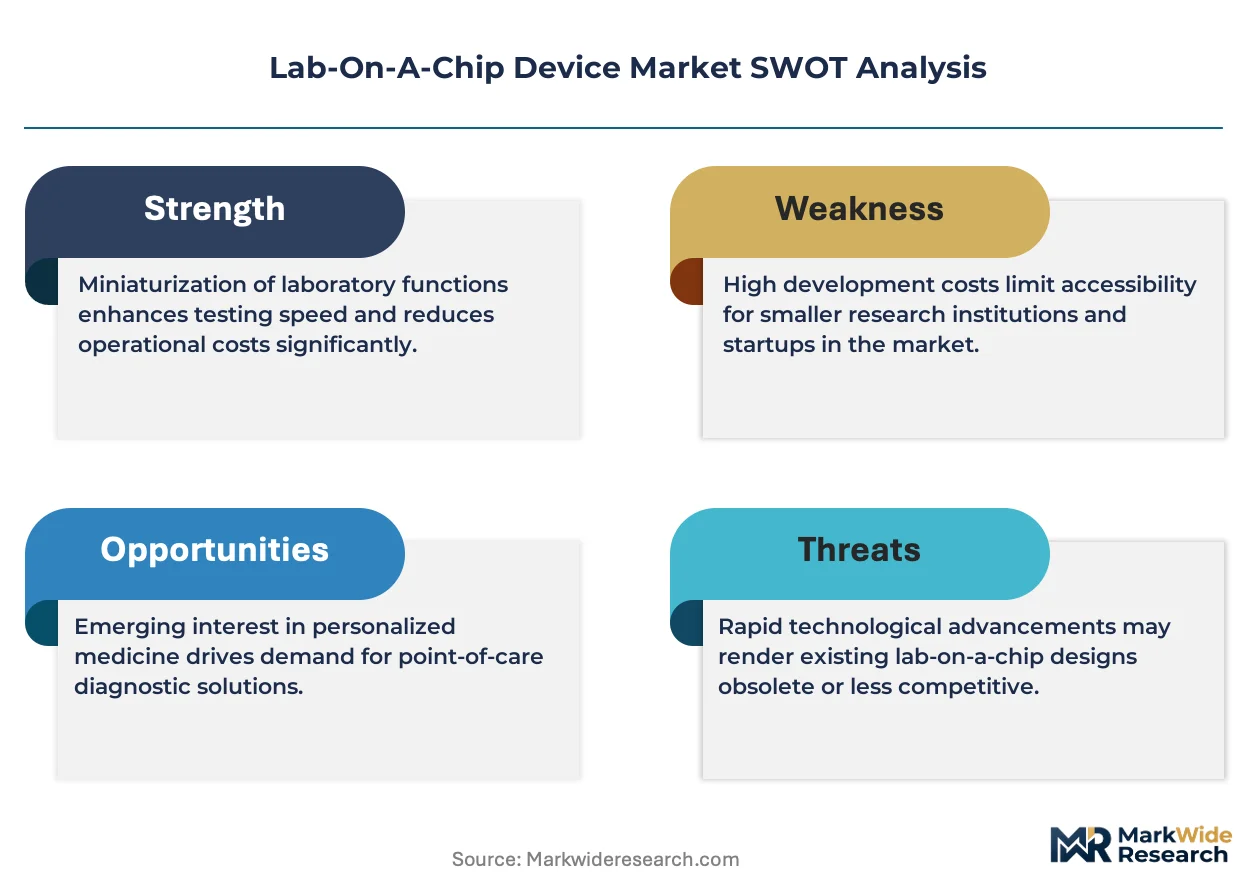
A lab-on-a-chip device integrates microfluidic channels, sensors, and reaction chambers onto a single substrate—typically glass, silicon, or polymer—enabling automated chemical or biological analysis at microliter scales with throughput exceeding conventional benchtop methods. PCR technology leads the technology segment due to its entrenched role in infectious disease diagnostics, while immunoassay platforms represent the fastest-expanding category as multiplexed protein detection gains traction in autoimmune and oncology screening. Microfluidics products capture the largest product-type revenue pool, though sensor chips command premium pricing where real-time electrochemical readout replaces optical detection.
The FDA's premarket notification and quality system regulation frameworks shape device validation timelines and clinical evidence requirements for US market entry, while the EU MDR and IVDR impose stricter post-market surveillance and notified-body oversight on European commercialization. Japan's PMDA maintains distinct technical standards for regenerative medicine applications that influence microfluidic design specifications. Stakeholders must monitor evolving harmonization gaps between these regimes when allocating regulatory affairs resources across development pipelines.
Market Dynamics
Point-of-care diagnostic procurement is decoupling from centralized hospital laboratory purchasing, creating direct contracting relationships between device manufacturers and pharmaceutical companies seeking rapid biomarker validation pipelines.
Growth Catalysts
- IVDR Compliance Deadlines:The EU's In Vitro Diagnostic Regulation mandates performance validation upgrades that accelerate replacement cycles for legacy benchtop equipment. Diagnostic networks in Germany and France are consolidating vendor relationships around pre-certified microfluidic platforms.
- Multiplexed Protein Detection:Immunoassay platforms capable of simultaneous cytokine and autoantibody quantification are displacing sequential ELISA workflows in rheumatology and oncology screening protocols.
- Japan:PMDA technical standards for regenerative medicine applications are driving specialized microfluidic designs for cell therapy quality control, opening procurement channels distinct from general diagnostics.
Market Restraints
- Polymer Supply Concentration:High-grade cyclic olefin copolymer for disposable chip substrates depends on limited Asian petrochemical suppliers, exposing molding operations to feedstock volatility.
- FDA 510(k) Pathway Complexity:Substantial equivalence determinations for novel microfluidic architectures require predicate device identification that delays first-mover products by 12-18 months versus incremental innovations.
- Optical Detection Substitution:Smartphone-integrated colorimetric readouts for lateral flow assays capture price-sensitive infectious disease screening in resource-limited settings, compressing addressable volume for instrumented lab-on-a-chip systems.
Strategic Opportunities
- India:CDSCO streamlined medical device registration and PLI scheme incentives for domestic manufacturing create first-mover advantages for localized chip fabrication partnerships.
- Continuous Bioprocessing Integration:Real-time electrochemical sensor chips embedded in perfusion bioreactors enable automated metabolite monitoring that reduces manual sampling labor in contract development organizations.
- Direct-to-Consumer Channel:Pharmacy retail networks in the United States are piloting self-collection microfluidic kits for HbA1c and lipid panels, bypassing clinical laboratory intermediaries.
Industry Challenges
- Multiphysics Simulation Talent:Computational fluid dynamics expertise combining electrokinetic, thermal, and surface chemistry modeling remains scarce in device engineering teams, extending design iteration cycles.
- ISO 13485 Certification Burden:Small-scale microfluidic foundries face disproportionate quality management system documentation costs relative to revenue when serving diversified diagnostic portfolios.
- Legacy LIMS Integration:Hospital information systems built around barcode-tracked tube workflows require custom middleware development to accommodate chip-based sample identifiers and reduced aliquot volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab-On-A-Chip Device Market |
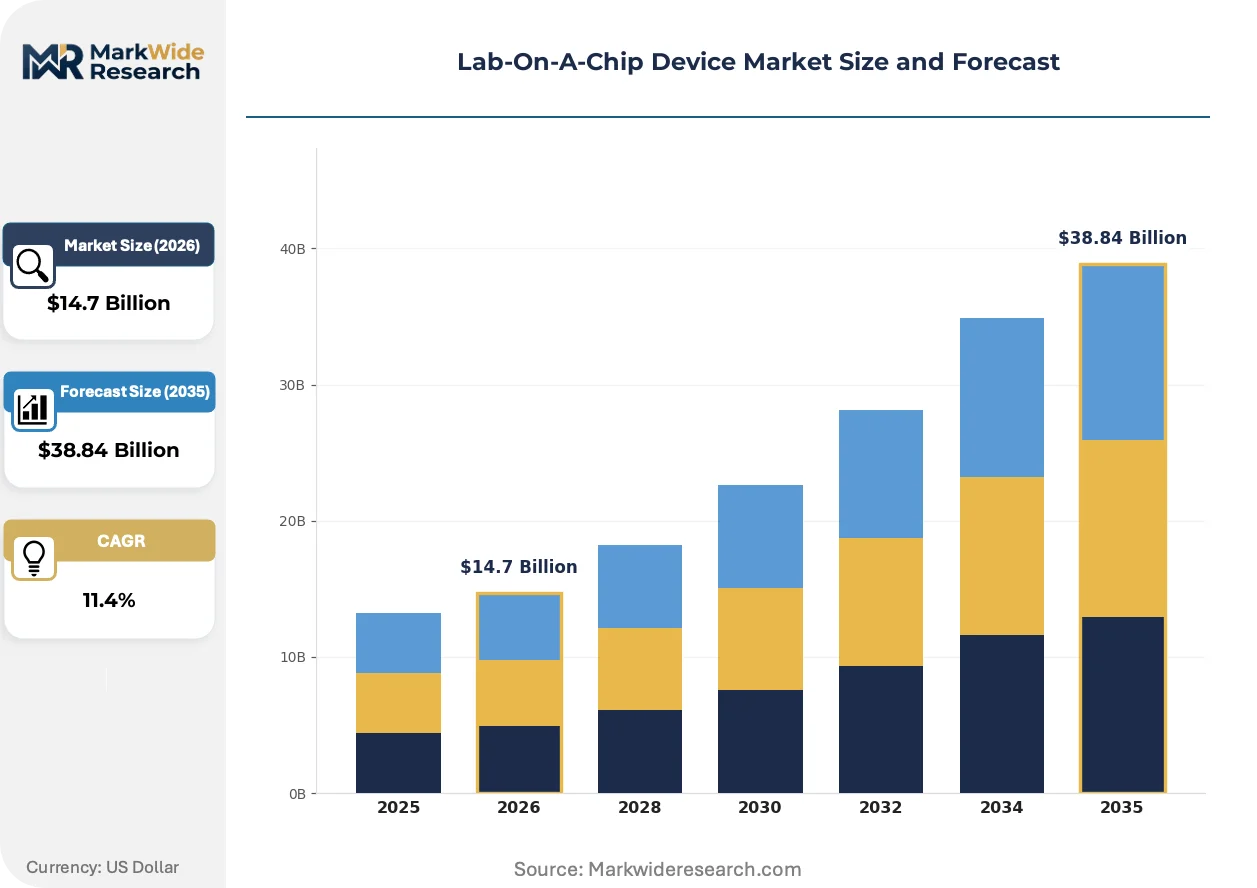
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidics, Biochips, Sensor Chips, Reagent Chips Technology: PCR, Immunoassay, Microarray, Electrophoresis End User: Laboratories, Hospitals, Research Institutes, Pharmaceutical Companies Application: Medical Diagnostics, Environmental Monitoring, Drug Development, Food Safety Testing |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, Becton Dickinson and Company, Bio-Rad Laboratories, Abbott Laboratories, PerkinElmer, F. Hoffmann-La Roche AG, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab-On-A-Chip Device Market Strategic Shifts
Silicon photonics integration and electrochemical transduction architectures are compressing detection limits while eliminating optical alignment complexity. These advances are reshaping competitive differentiation around readout modality rather than fluidic design alone.
Digital microfluidics based on electrowetting-on-dielectric substrates is unifying reagent handling, thermal cycling, and detection on a single electrode array. Contract research organizations running high-throughput screening programs are adopting these platforms to reduce per-assay liquid consumption by two orders of magnitude. The technology is unifying previously discrete workflow steps, collapsing capital equipment footprints and enabling mobile deployment configurations.
REACH substance restrictions on perfluorinated materials are forcing reformulation of hydrophobic surface coatings for droplet microfluidics. European manufacturers are accelerating qualification of hydrocarbon-based alternatives ahead of 2026 authorization sunset dates. Droplet generation chips for single-cell encapsulation face the steepest reformulation costs given surface energy precision requirements.
Pharmaceutical toxicology departments are consolidating vendor contracts around integrated reagent-instrument-service bundles. This purchasing pattern displaces component sourcing from separate fluidic, detection, and consumables suppliers. The United States exhibits the most pronounced consolidation, where top-ten drug developers now specify multi-year sole-source agreements for IND-enabling bioanalytical workflows.
Lab-On-A-Chip Device Market Segmentation
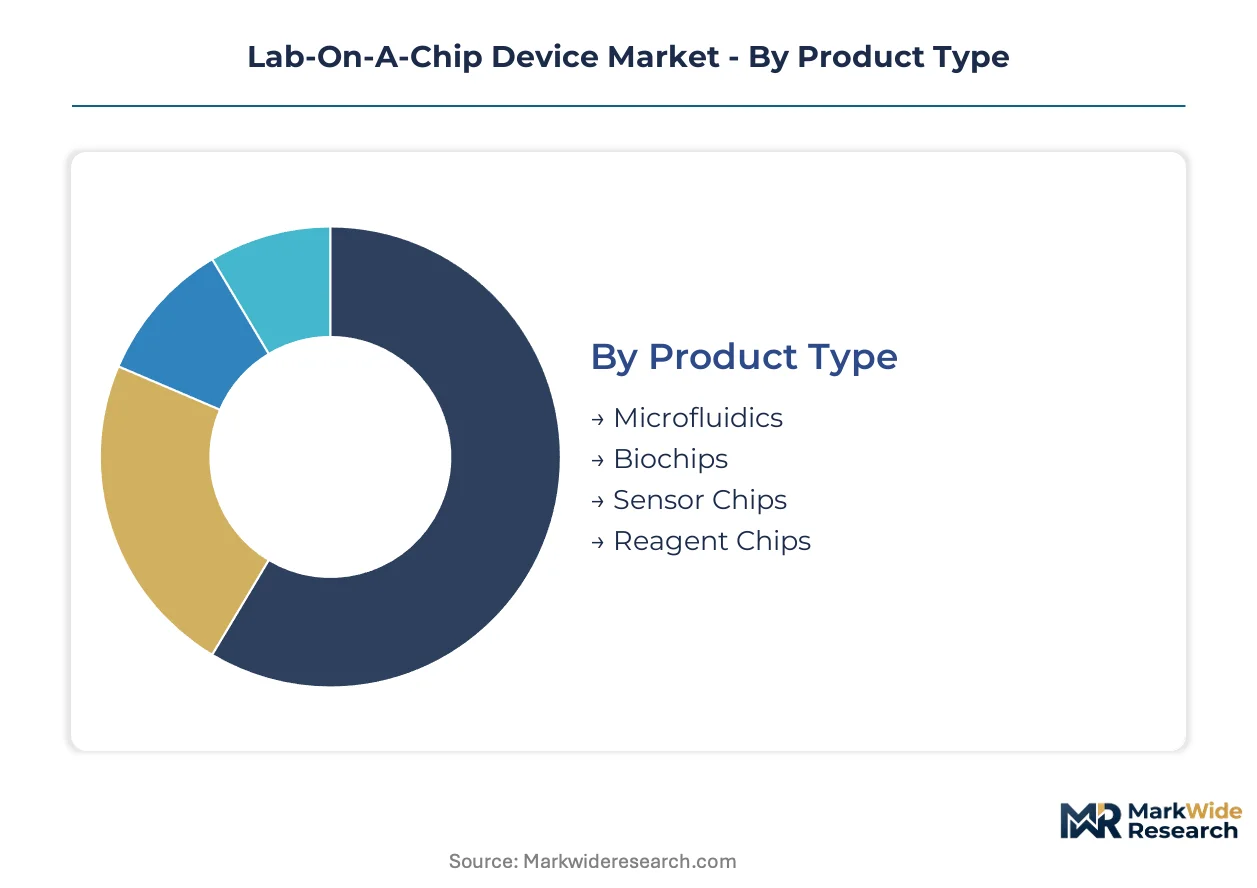
Device architecture determines procurement economics for lab-on-a-chip systems. Buyers select product types based on workflow integration depth, while technology choices hinge on detection sensitivity requirements and regulatory validation burden.
Product Type:
Capital intensity separates disposable chip buyers from integrated platform purchasers.
- Microfluidics:Polymer-based channel networks manipulate microliter-scale fluid volumes through pressure-driven or electrokinetic flow. Hospital networks in the United States favor these platforms for high-throughput infectious disease panels where throughput exceeds conventional benchtop methods.
- Sensor Chips:Electrochemical or optical transducers embedded in silicon or glass substrates enable real-time analyte quantification without external instrumentation. German clinical laboratories command premium pricing for these devices where point-of-care deployment eliminates centralized laboratory logistics.
- Biochips:DNA or protein capture arrays on functionalized surfaces support genomic and proteomic screening workflows.
- Reagent Chips:Pre-loaded reaction chambers with lyophilized or liquid reagents reduce operator handling errors in resource-limited settings.
Microfluidics leads volumes today; sensor chips are gaining share fastest.
Technology:
Detection chemistry dictates equipment footprint and operator skill requirements.
- PCR:Thermal cycling microchambers amplify nucleic acid targets with cycle times compressed to minutes versus hour-long conventional protocols. Japanese diagnostic networks specify these platforms for respiratory pathogen surveillance where rapid turnaround supports infection control protocols.
- Immunoassay:Antigen-antibody binding reactions on functionalized surfaces enable multiplexed protein detection with single-piconogram sensitivity. Pharmaceutical toxicology departments in the United States displace sequential ELISA workflows with these platforms for cytokine profiling in drug safety studies.
- Microarray:High-density probe grids support genome-wide association studies and expression profiling.
- Electrophoresis:Electric field-driven separation of charged molecules resolves protein isoforms and nucleic acid fragments.
PCR anchors installed base today; immunoassay platforms are climbing the fastest.
End User:
Procurement authority and reimbursement pathways shape vendor engagement models.
- Laboratories:Centralized clinical and reference laboratories deploy high-throughput microfluidic analyzers for routine diagnostic menus. German hospital networks consolidate vendor contracts around pre-certified platforms that satisfy EU IVDR performance validation requirements.
- Pharmaceutical Companies:Drug developers specify integrated reagent-instrument-service bundles for IND-enabling bioanalytical workflows. United States-based top-ten drug developers now execute multi-year sole-source agreements that displace component sourcing from separate suppliers.
- Hospitals:Point-of-care testing units seek compact, operator-agnostic devices for emergency department and bedside deployment.
- Research Institutes:Academic and government laboratories prioritize flexibility over throughput for method development and grant-funded studies.
Laboratories dominate procurement volumes today; pharmaceutical companies are expanding fastest.
Application:
Regulatory classification and reimbursement coding determine commercialization timelines.
- Medical Diagnostics:FDA-cleared and CE-marked devices for infectious disease, oncology, and metabolic screening command the largest revenue pool. United States hospital networks drive procurement of multiplexed respiratory panels and pharmacogenomic assays.
- Drug Development:Bioanalytical platforms for pharmacokinetic and biomarker studies support pharmaceutical pipeline decisions. Contract research organizations adopt digital microfluidics to reduce per-assay liquid consumption and accelerate screening throughput.
- Environmental Monitoring:Field-deployable sensors detect waterborne pathogens and chemical contaminants.
- Food Safety Testing:Rapid pathogen detection chips address supply chain verification requirements.
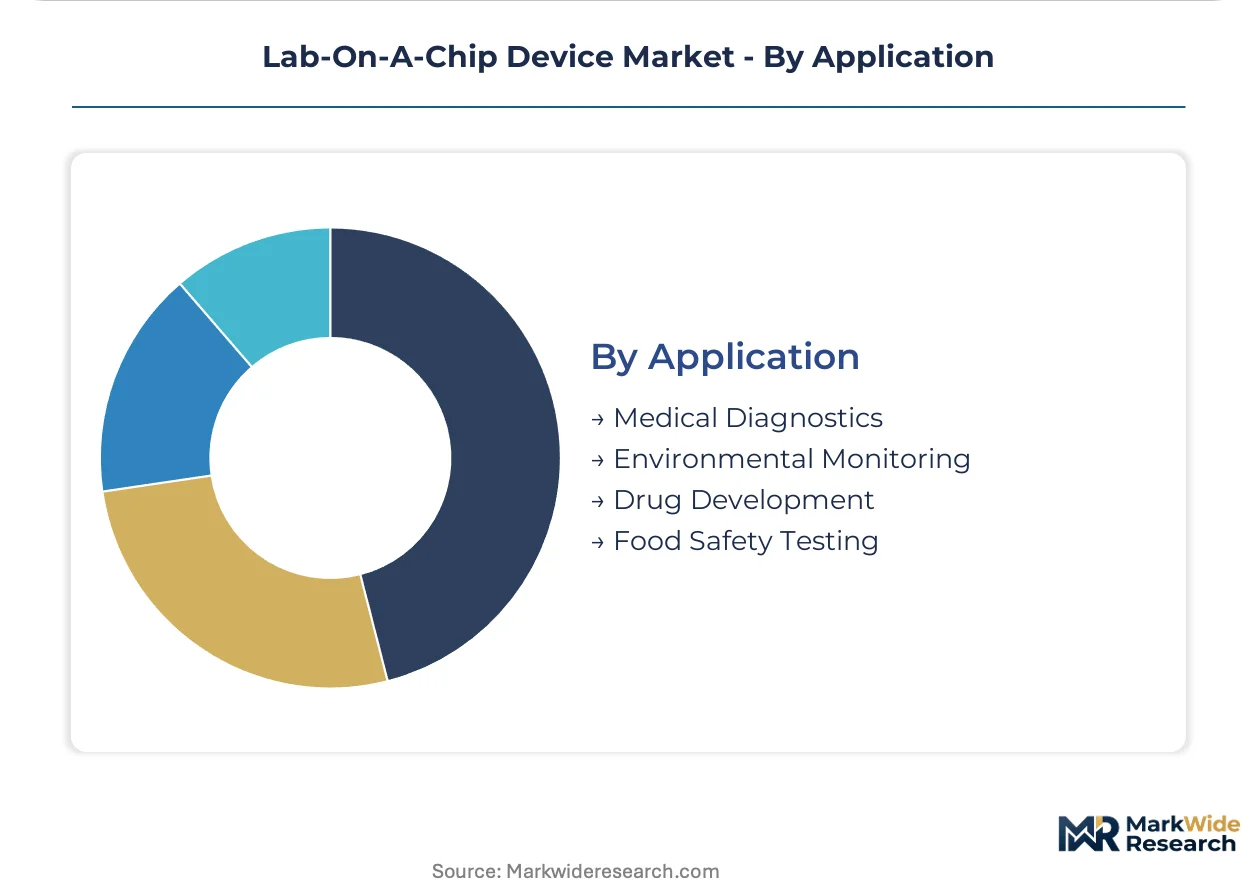
Medical diagnostics leads revenue today; drug development applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microfluidic engineering talent clusters in Germany's precision manufacturing belt, the United States' biomedical research corridors, and Japan's semiconductor fabrication hubs anchor regional competitive positioning.
United States
Hospital networks in Massachusetts and California drive point-of-care diagnostic procurement decoupled from centralized laboratory purchasing. FDA premarket notification pathways for novel microfluidic architectures extend validation timelines for first-mover products. The Boston-Cambridge corridor concentrates contract research organizations adopting digital microfluidics for high-throughput screening programs.
Germany
Clinical laboratories in Bavaria and North Rhine-Westphalia consolidate vendor contracts around pre-certified platforms satisfying EU IVDR performance validation requirements. REACH substance restrictions on perfluorinated materials accelerate hydrocarbon-based surface coating qualification ahead of 2026 authorization sunsets. The Munich-Stuttgart industrial corridor hosts precision polymer molding operations for disposable chip substrates.
Japan
Diagnostic networks in Kanto and Kansai specify PCR microchambers for respiratory pathogen surveillance supporting infection control protocols. PMDA technical standards for regenerative medicine applications drive specialized microfluidic designs for cell therapy quality control. The Tokyo-Yokohama metro anchors pharmaceutical toxicology departments consolidating vendor contracts around integrated reagent-instrument-service bundles.
India
CDSCO streamlined medical device registration and PLI scheme incentives for domestic manufacturing create first-mover advantages for localized chip fabrication partnerships. Contract development organizations in Hyderabad and Bengaluru adopt real-time electrochemical sensor chips for automated metabolite monitoring in perfusion bioreactors. The Genome Valley-Telangana cluster concentrates microfluidic foundry capacity serving diversified diagnostic portfolios.
United Kingdom
Academic and government laboratories in Oxford and Cambridge prioritize flexibility over throughput for method development and grant-funded studies. EU MDR and IVDR post-market surveillance requirements influence European commercialization strategies for UK-based device developers. The Golden Triangle research corridor anchors silicon photonics integration advancing electrochemical transduction architectures.
Lab-On-A-Chip Device Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Thermo Fisher Scientific and Danaher Corporation anchor the consolidated upper tier through reagent-chip integration and microfluidic manufacturing workflow control respectively. Mid-scale specialists occupy technology-specific niches in digital microfluidics and sensor chip fabrication. Strategic moves concentrate on vertical integration into polymer substrate supply and multi-year sole-source agreements with pharmaceutical developers.
Among diversified life science conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify contrasting anchoring strategies—one through reagent-instrument bundling, the other through captive manufacturing workflow control. Agilent Technologies occupies a position within the analytical instrumentation tier where detection modality integration drives competitive differentiation. These three entities represent the dominant competitive archetypes: integrated platform providers, manufacturing-centric conglomerates, and analytical instrumentation specialists.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| Becton Dickinson and Company |
| Bio-Rad Laboratories |
| Abbott Laboratories |
| PerkinElmer |
| F. Hoffmann-La Roche AG |
| Illumina |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-cleared platforms and research-use-only devices manifests in both pricing premiums and supply chain sourcing strategies. Premium-tier manufacturers in the United States and Germany command higher unit economics through validated polymer substrate traceability and captive reagent production, while commodity-tier suppliers in Asia face margin compression from optical detection substitution and smartphone-integrated lateral flow competition.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for disposable polymer microfluidic chips. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from CE-marked devices and research-grade consumables. Price differentiation hinges on ISO 13485 certification burden and after-sales service bundling. Cost compression in the economy tier is intensifying because smartphone-integrated colorimetric readouts capture price-sensitive infectious disease screening. Pharmaceutical companies exhibit the least price sensitivity due to IND-enabling workflow requirements, while hospital procurement committees in resource-limited settings drive hardest bargain.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand, while distributor networks serve fragmented hospital procurement. Geographic supply concentration centers on Germany for precision polymer molding, Japan for silicon photonics integration, and the United States for reagent-instrument bundling. Raw material dependencies draw from high-grade cyclic olefin copolymer, electrochemical sensor substrates, and lyophilized reagent formulations. Single-source vulnerability concentrates in Asian petrochemical suppliers for disposable chip substrates. Distribution runs through integrated reagent-instrument-service bundles that displace component sourcing from separate fluidic, detection, and consumables suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO streamlined registration and PLI scheme incentives in India create cost advantages against EU IVDR compliance burdens and FDA premarket notification timelines in Western markets.
For Market Incumbents: To counter optical detection substitution from smartphone-integrated lateral flow assays, anchor long-term supply contracts through reagent-chip integration capabilities and backward integration into polymer substrate supply. Thermo Fisher Scientific exemplifies this defensive posture through captive manufacturing of high-grade cyclic olefin copolymer components. Certification investment in EU IVDR pre-certification creates switching costs that lock German and French diagnostic networks into validated vendor relationships. For New Entrants and Emerging Players: Capture first-mover positioning in India's CDSCO streamlined registration environment through localized chip fabrication partnerships with Genome Valley-Telangana microfluidic foundries. Contract development organizations in Hyderabad and Bengaluru represent the most penetrable buyer segment due to adoption of real-time electrochemical sensor chips for automated metabolite monitoring. Direct contracting with pharmaceutical toxicology departments bypasses consolidated hospital laboratory procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification burden disproportionately burdens small-scale microfluidic foundries relative to revenue. Long-term viability favors vertically integrated platform providers with reagent-instrument bundling capabilities over pure-play component suppliers. Acquisition target archetype: mid-scale specialists in digital microfluidics and sensor chip fabrication with established pharmaceutical sole-source agreements. Signal to watch: multi-year contract announcements from top-ten drug developers specifying integrated bioanalytical workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Bundling | Pharmaceutical toxicology departments in the United States now specify multi-year sole-source agreements displacing component sourcing. |
| Digital Microfluidics Platform Launch | Contract research organizations adopt electrowetting-on-dielectric substrates reducing per-assay liquid consumption by two orders of magnitude. |
| EU IVDR Pre-Certification Pathway | German clinical laboratories consolidate vendor contracts around pre-certified platforms satisfying performance validation requirements ahead of compliance deadlines. |
| Silicon Photonics Integration | Electrochemical transduction architectures compress detection limits while eliminating optical alignment complexity in point-of-care deployment. |
| Localized Chip Fabrication Partnership | CDSCO streamlined registration and PLI scheme incentives in India create first-mover advantages for domestic manufacturing of disposable substrates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with microfluidic device engineers, hospital procurement managers, pharmaceutical toxicology directors, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU IVDR notified-body documentation, PMDA technical standards, and hospital GPO contract databases. Bottom-up triangulation across product-type volumes and top-down cross-checks against end-user procurement patterns anchored forecast integrity.
Segment-weighting approaches distributed analytical emphasis across technology choices, product-type capital intensity, and end-user procurement authority. Modeling dimensions spanned PCR versus immunoassay detection chemistry, disposable chip versus integrated platform economics, and laboratory versus pharmaceutical company buyer archetypes. CAGRs derived from iterative reconciliation of historical replacement cycles, regulatory-driven upgrade timelines, and pharmaceutical pipeline biomarker validation demand.
Regulatory harmonization gaps, polymer feedstock volatility, and optical detection substitution are the dominant revision risks to base-case projections. Forecasts reflect assumptions about IVDR compliance deadline adherence and pharmaceutical R&D spending continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Trace Oxygen Analyzer Market