
 Next-Generation Organic Solar Cell Market | 2026-2036
Next-Generation Organic Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Organic Solar Cell Market Analysis
Perovskite tandem architectures are restructuring cost-performance trade-offs across the organic photovoltaics value chain. Oxford Photovoltaics Ltd. leverages its proprietary perovskite-on-silicon tandem technology to anchor premium positioning in building-integrated applications. BASF SE sustains deep materials science competencies that differentiate its polymer donor and acceptor portfolios for flexible panel manufacturers.
Next-generation organic solar cells are thin-film photovoltaic devices that utilize organic semiconductors—typically polymer or small-molecule donor-acceptor blends processed from solution—to convert sunlight into electricity, with power conversion efficiencies now exceeding 18% in laboratory tandem configurations and primary deployment targeting lightweight, conformal, and semi-transparent installations where conventional silicon modules face physical constraints. Tandem cells command the highest margin pools as they stack perovskite and organic layers to harvest broader spectral ranges, while transparent solar cells represent the fastest-growing product type as architectural glass manufacturers integrate power generation into facades and windows. Flexible panels retain mature volume leadership in consumer electronics and portable applications, though their growth rate lags behind building-integrated and automotive segments.
The EU Green Deal and REACH frameworks in Europe, alongside China's GB standards and dual carbon goals administered by MEE, are tightening material disclosure and lifecycle efficiency requirements that shape module certification and market access across major demand centers. The US IRA provisions channel investment tax credits toward domestic thin-film manufacturing, directly influencing where capacity expansion occurs. Stakeholders must monitor how perovskite stability standards evolve under these overlapping regulatory regimes to time capital deployment and product qualification strategies effectively.
Market Dynamics
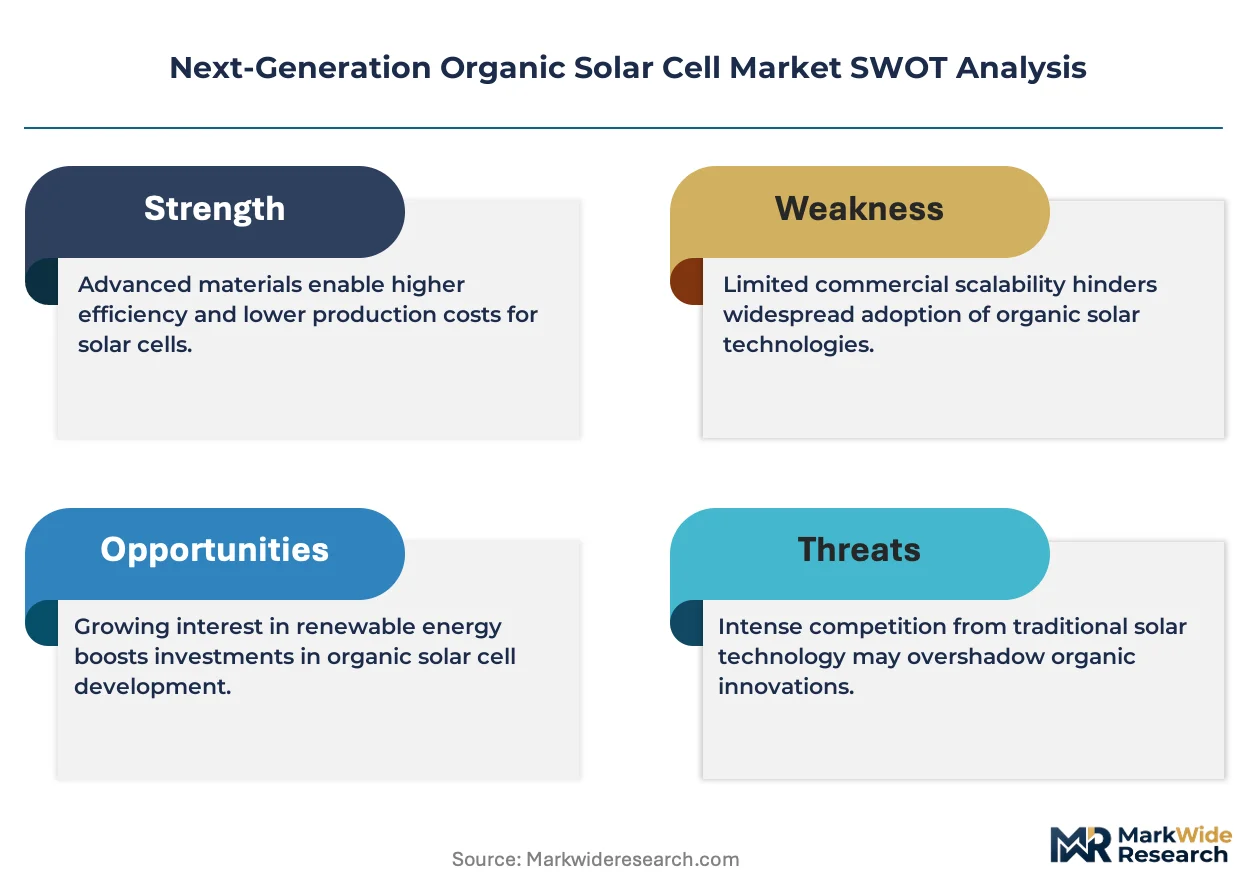
Perovskite tandem architectures are compressing the cost-efficiency frontier for organic photovoltaics, forcing incumbent polymer-blend suppliers to accelerate R&D timelines or cede position in building-integrated applications.
Growth Catalysts
- EU Green Deal efficiency mandates:Tightening renewable energy benchmarks for building materials are compelling commercial real estate developers to specify semi-transparent solar glass in new construction and retrofit projects.
- Tandem cell spectral harvesting:Stacked perovskite-organic configurations now capture broader wavelength ranges than single-junction alternatives, unlocking premium pricing in architectural integration where space constraints limit module area.
- German manufacturing scale-up:Domestic capacity expansion for flexible panel production is reducing lead times for European building-integrated photovoltaic installers and lowering logistics costs for facade system integrators.
Market Restraints
- Lead halide supply concentration:Perovskite precursor materials rely on concentrated Chinese chemical processing capacity, exposing cell manufacturers to input cost volatility and geopolitical supply disruption risks.
- Moisture-induced degradation:Organic semiconductor layers exhibit rapid performance decay under unencapsulated humidity exposure, limiting warranty terms and insurability for outdoor installations without hermetic barrier films.
- SILICON COST COMPETITIVENESS:Crystalline silicon module prices have compressed faster than organic cell manufacturing learning curves, narrowing the addressable market to weight-constrained and conformal applications where silicon cannot compete.
Strategic Opportunities
- Automotive-integrated photovoltaics:Curved roof and glazing applications in electric vehicles represent an underpenetrated demand pool where flexible organic cells bypass silicon's rigidity constraints.
- US IRA domestic content bonuses:Investment tax credit adders for thin-film manufacturing equipment are incentivizing capital deployment to American production facilities serving North American architectural glass markets.
- Agrivoltaic dual-use installations:Semi-transparent organic panels enable simultaneous crop cultivation and power generation, opening agricultural land previously excluded from conventional solar development due to shading intensity.
Industry Challenges
- Perovskite stability certification timelines:IEC 61215 adaptation for tandem cell architectures remains incomplete, delaying bankability and project finance access for commercial-scale deployments.
- Solution-processing equipment specialization:Roll-to-roll coating and printing systems require distinct engineering competencies from silicon wafer handling, constraining talent pools for manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Organic Solar Cell Market |
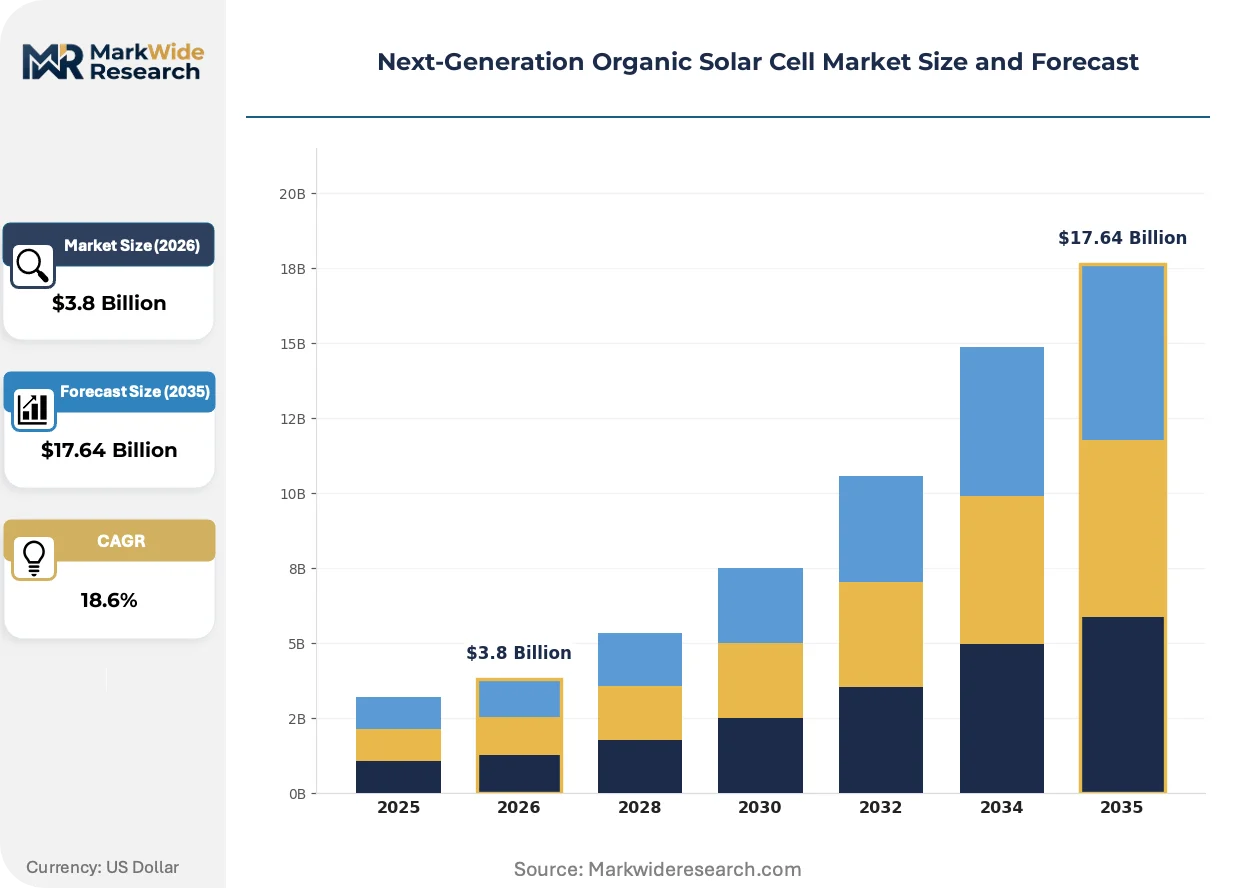
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Panels, Bifacial Cells, Tandem Cells, Transparent Solar Cells Material: Polymer, Small Molecule, Hybrid Perovskite, Electrode Coatings End User: Residential, Commercial, Automotive, Aerospace Installation: Roof-mounted, Building-integrated, Ground-mounted, On-demand |
| Companies Covered | JinkoSolar, Kaneka Corporation, Oxford Photovoltaics Ltd., BASF SE, Hanwha Q CELLS, First Solar, Inc., JA Solar, Bayer AG, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Organic Solar Cell Market Emerging Trajectories
Active materials innovation and regulatory recalibration are converging to redefine where organic photovoltaics compete against incumbent silicon and emerging thin-film alternatives.
Non-fullerene acceptor molecules are rewriting efficiency benchmarks for single-junction organic cells by reducing voltage losses and extending absorption into the near-infrared. Materials suppliers are shipping these compounds to flexible panel manufacturers in Germany and South Korea at commercial volumes for consumer electronics integration. The technology is compressing the efficiency gap with silicon in indoor and low-light applications where spectral matching favors organic semiconductors.
REACH substance restriction proposals under ECHA review are forcing reformulation of solvent systems used in organic semiconductor deposition. European module assemblers are qualifying aqueous and bio-based processing chemistries to maintain CE marking eligibility for building-integrated sales. German facade engineering firms are prioritizing suppliers with pre-registered alternative chemistries to avoid construction timeline delays from regulatory non-compliance.
Architectural glass procurement teams are unbundling power generation specifications from traditional glazing contracts, creating direct sourcing relationships with organic cell manufacturers. Skanska and similar construction managers are establishing preferred supplier agreements for semi-transparent solar glass to secure capacity for net-zero building certifications. This pattern is most visible in Frankfurt and Copenhagen commercial towers where local building codes mandate renewable energy integration percentages.
Next-Generation Organic Solar Cell Market Segmentation
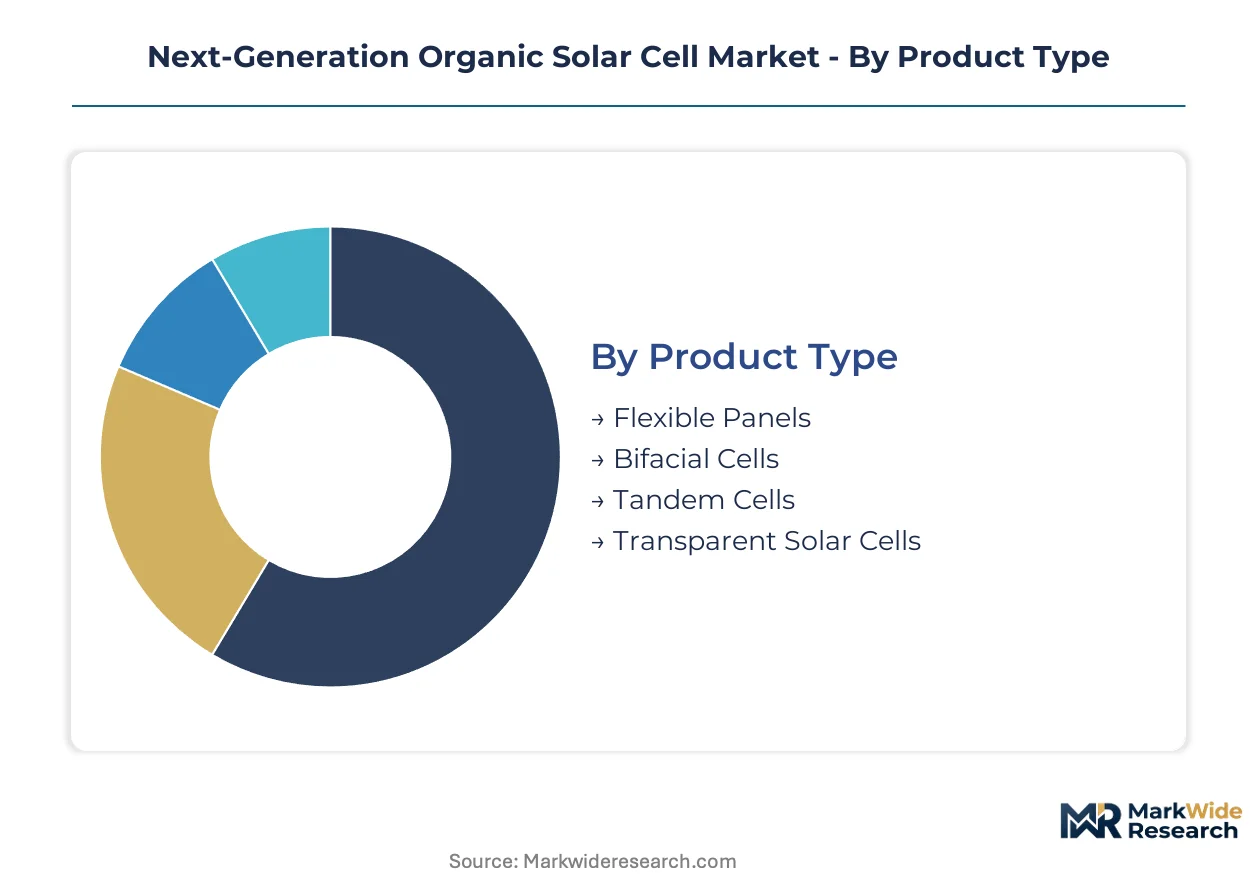
Organic solar cell manufacturers must align production capabilities with divergent technical requirements across installation environments. Each segment demands distinct encapsulation chemistries, substrate flexibility, and spectral tuning that reshape procurement patterns for materials suppliers.
Product Type:
Supply concentration in roll-to-roll coating equipment favors manufacturers with established flexible substrate processing lines, while emerging tandem architectures require entirely different vapor deposition toolsets.
- Tandem Cells:Stacked perovskite-organic junctions harvest broader spectral ranges than single-junction alternatives. Demand concentrates in German and Danish commercial facade projects where space constraints limit module area and premium pricing absorbs higher manufacturing costs. IEC 61215 adaptation delays constrain bankability for utility-scale deployments.
- Transparent Solar Cells:Semi-transparent architectures integrate power generation into architectural glazing with visible light transmission exceeding 20%. Skanska and similar construction managers in Frankfurt and Copenhagen specify these for net-zero building certifications under tightening EU Green Deal mandates. Glass manufacturers are unbundling power generation from traditional glazing contracts.
- Flexible Panels:Polymer substrate compatibility enables conformal mounting on curved surfaces. Mature volume leadership in consumer electronics and portable applications.
- Bifacial Cells:Dual-sided light harvesting architectures capture albedo reflection from underlying surfaces. Limited organic photovoltaic deployment due to encapsulation challenges.
Today's leader: Tandem Cells. Tomorrow's challenger: Transparent Solar Cells.
Material:
Cost tier differentiation separates commodity polymer feedstocks from specialized perovskite precursors with concentrated Chinese chemical processing exposure.
- Hybrid Perovskite:Lead halide frameworks enable the highest laboratory efficiencies in tandem configurations. Supply chains concentrate in Chinese chemical processing capacity, exposing cell manufacturers to input cost volatility and geopolitical disruption risks. ECHA REACH substance reviews are forcing reformulation timelines for European market access.
- Polymer:Donor-acceptor blend systems dominate flexible panel manufacturing with established roll-to-roll compatibility. BASF SE and similar materials suppliers maintain deep competencies in molecular design for architectural integration customers.
- Small Molecule:Vacuum-processable compounds enable precise layer thickness control in tandem architectures. Higher manufacturing costs limit deployment to premium building-integrated applications.
- Electrode Coatings:Transparent conductive oxides and silver nanowire formulations determine sheet resistance and optical transmission trade-offs.
Volume concentrates in Polymer. Margin concentrates in Hybrid Perovskite.
End User:
Application-driven specifications reshape module durability requirements, with automotive and aerospace segments demanding hermetic barrier films that residential installations rarely require.
- Commercial:Building-integrated photovoltaic specifications dominate procurement volumes for semi-transparent and flexible architectures. EU Green Deal efficiency mandates compel real estate developers in Germany and Denmark to specify renewable energy integration percentages in new construction and retrofit projects.
- Automotive:Curved roof and glazing applications in electric vehicles represent underpenetrated demand where flexible organic cells bypass silicon rigidity constraints. US IRA domestic content bonuses incentivize capital deployment to American production facilities serving Detroit and California automotive supply chains.
- Residential:Distributed rooftop installations favor lightweight modules that reduce structural loading requirements.
- Aerospace:Weight-constrained satellite and unmanned aerial vehicle applications prioritize power-to-mass ratios over cost minimization.
Commercial anchors current revenue. Automotive offers the steepest expansion trajectory.
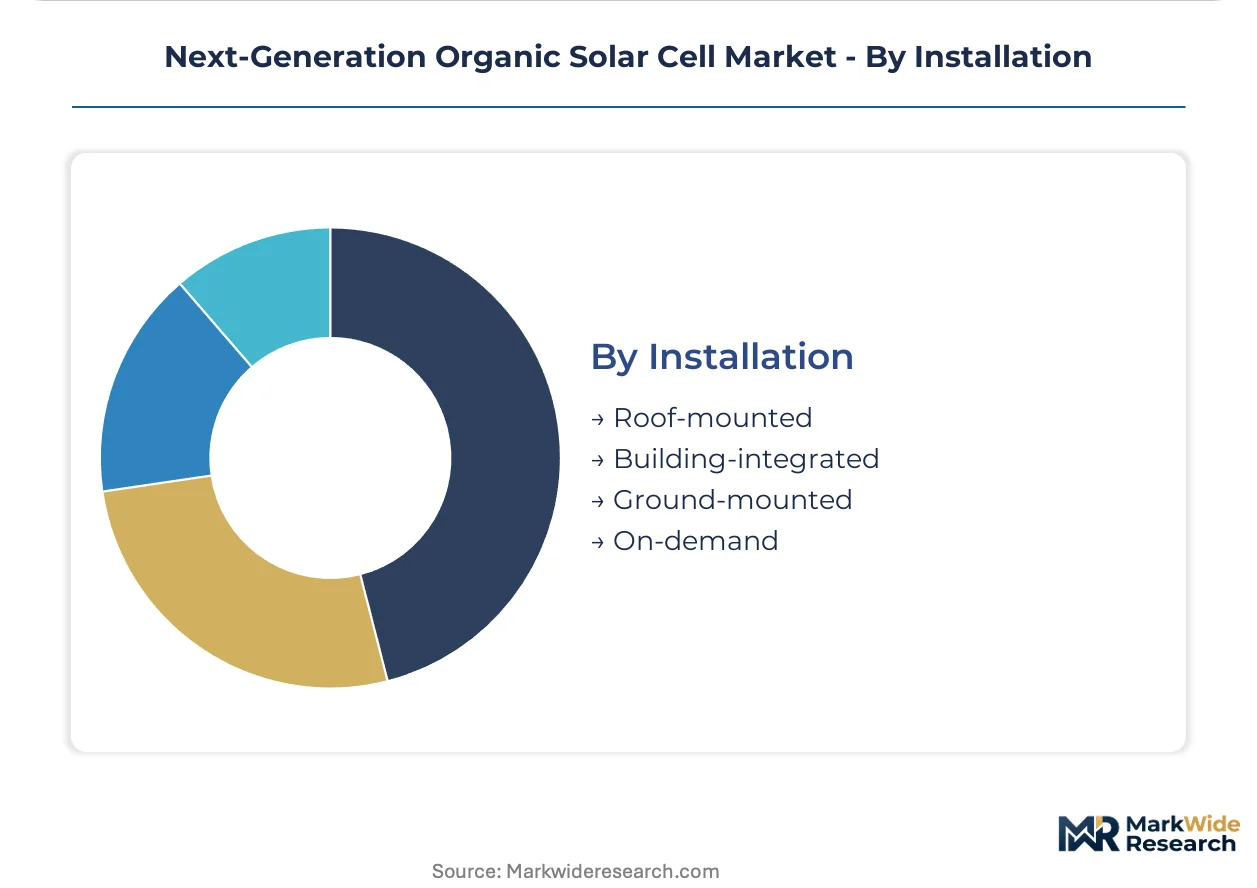
Installation:
Customer type stratification separates specification-driven architectural engineers from price-sensitive residential installers.
- Building-integrated:Facade and glazing integration demands semi-transparent cells with customized aesthetic properties. Frankfurt and Copenhagen commercial towers drive specification intensity as local building codes mandate renewable energy percentages. Architectural glass procurement teams are establishing direct sourcing relationships with organic cell manufacturers.
- Roof-mounted:Conventional tilted installations compete directly with silicon on cost metrics, limiting organic photovoltaic penetration to weight-constrained retrofit applications.
- Ground-mounted:Utility-scale deployments favor silicon cost structures except where agrivoltaic dual-use requirements favor semi-transparent organic panels for simultaneous crop cultivation.
- On-demand:Portable and consumer electronics applications leverage flexible panel form factors for rapid deployment scenarios.
Building-integrated commands premium positioning. Agrivoltaic dual-use is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processing clusters anchor organic solar cell materials supply, while manufacturing scale-up concentrates in Chinese roll-to-roll coating facilities and US thin-film incentives reshape North American production geography.
United States
Investment Tax Credit adders under the IRA channel capital toward domestic thin-film manufacturing equipment. Detroit and California automotive supply chains source curved-roof photovoltaic modules from expanding American production facilities. Project developers in Arizona and Texas agrivoltaic installations specify semi-transparent panels for dual-use crop cultivation.
Germany
Frankfurt and Copenhagen commercial towers drive specification intensity for building-integrated glazing under EU Green Deal efficiency mandates. BASF SE maintains deep polymer donor and acceptor competencies for architectural integration customers. The KBA and federal building codes tighten renewable energy integration percentages in new construction permits.
China
GB standards administered by MEE and dual carbon goals compress manufacturing emissions intensity for export-bound module production. Concentrated chemical processing capacity for lead halide perovskite precursors exposes cell manufacturers to input cost volatility. Yangtze River Delta roll-to-roll coating facilities supply flexible panel substrates to German and South Korean consumer electronics integrators.
Japan
METI efficiency benchmarks and JIS standards shape module certification requirements for building-integrated deployments. Kaneka Corporation leverages domestic polymer science competencies for flexible substrate development. Osaka-based materials suppliers ship non-fullerene acceptor compounds to tandem cell manufacturers qualifying for European CE marking.
South Korea
MFDS chemical safety reviews and national renewable portfolio standards accelerate qualification timelines for aqueous processing chemistries. Seoul Capital Area electronics manufacturers integrate flexible organic cells into portable device form factors. Busan-Ulsan chemical clusters supply transparent conductive oxide formulations for architectural glass integration.
Next-Generation Organic Solar Cell Market Vendor Landscape
Global majors compete with regional champions across materials science and manufacturing equipment domains, producing a tiered structure where chemical conglomerates, specialized thin-film developers, and solar incumbents each occupy distinct margin pools. Three strategic archetypes dominate: diversified chemical suppliers controlling donor-acceptor molecular design, dedicated perovskite tandem technology developers, and scaled solar manufacturers backward-integrating into organic semiconductor deposition. Competitive moves center on capacity expansion in IRA-eligible US facilities and strategic partnerships between architectural glass manufacturers and cell developers.
Within the diversified chemical supplier tier, BASF SE and Bayer AG exemplify European materials science incumbents leveraging polymer competency depth. Oxford Photovoltaics Ltd. occupies a specialized position as a perovskite-on-silicon tandem developer targeting premium building-integrated applications. Among scaled solar manufacturers, First Solar, Inc. and Hanwha Q CELLS represent thin-film and silicon incumbents respectively, each evaluating organic photovoltaic integration vectors.
| Leading Market Players |
|---|
| JinkoSolar |
| Kaneka Corporation |
| Oxford Photovoltaics Ltd. |
| BASF SE |
| Hanwha Q CELLS |
| First Solar, Inc. |
| JA Solar |
| Bayer AG |
| Trina Solar |
| Others |
Supply Flow & Price Mechanics
EU Green Deal efficiency mandates compelling semi-transparent solar glass specifications in Frankfurt and Copenhagen commercial towers are forcing module assemblers to qualify aqueous processing chemistries and hermetic barrier films, compressing margins for manufacturers without pre-registered alternative formulations while premium pricing persists for tandem cell architectures with certified stability data.
Pricing Analysis
Lead halide precursor cost pass-through from concentrated Chinese chemical processing capacity is intensifying margin pressure at the hybrid perovskite tier while polymer donor-acceptor blends maintain pricing stability through BASF SE's captive supply advantages. Three-tier pricing structure across premium tandem, standard flexible, and economy transparent tiers differentiates by IEC 61215 certification status and volume scale. Cost compression in the transparent cell segment is accelerating because architectural glass manufacturers are unbundling power generation from traditional glazing contracts. Commercial building-integrated photovoltaic installers show highest price sensitivity due to project finance constraints, while aerospace applications demonstrate least sensitivity given power-to-mass ratio priorities.
Supply Chain Analysis
Perovskite precursor supply rests on Yangtze River Delta chemical processing clusters in China, with secondary concentration in German polymer science competencies and South Korean transparent conductive oxide formulation capabilities. Raw material dependencies span lead halide frameworks, non-fullerene acceptor molecules, and silver nanowire electrode coatings. Single-source vulnerability in Chinese lead halide supply exposes cell manufacturers to geopolitical disruption risks and input cost volatility. Distribution runs through direct sourcing relationships between architectural glass procurement teams and organic cell manufacturers, bypassing traditional solar distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The next-generation organic solar cell market functions as a geographic-arbitrage play where US IRA domestic content bonuses create 30-40% effective cost differentials against European manufacturing, incentivizing capital deployment to Detroit and California automotive supply chains over Frankfurt facade engineering corridors.
For Market Incumbents: Anchor polymer donor-acceptor molecular design competencies through backward integration into specialized precursor synthesis, defending against perovskite tandem displacement in building-integrated applications by accelerating IEC 61215 stability certification timelines. Capacity addition in IRA-eligible Arizona and Texas facilities captures domestic content bonus structures while channel control over architectural glass direct sourcing relationships limits emerging entrant access to premium facade projects. For New Entrants and Emerging Players: Non-fullerene acceptor formulation expertise offers a technology-first wedge into the South Korean consumer electronics integration segment, where flexible panel demand from Seoul Capital Area device manufacturers outpaces incumbent supply capacity. Agrivoltaic dual-use installations in US Southwest agricultural corridors represent the most penetrable white-space target, with semi-transparent organic panels enabling simultaneous crop cultivation where silicon shading intensity excludes conventional development. Go-to-market execution should prioritize EPC contractor partnerships over direct utility sales. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized perovskite tandem technology developers possessing proprietary vapor deposition toolsets and pre-qualified European CE marking pathways, given bankability premium capture potential as IEC 61215 adaptation completes. Long-term viability over the analysis window favors acquisition targets with demonstrated hermetic encapsulation solutions for moisture-sensitive organic semiconductor layers. The signal to watch as inflection indicator is lead halide supply contract renegotiation patterns between Chinese chemical processors and German cell manufacturers, with pricing volatility spikes signaling margin compression ahead.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Stability Certification Investment | Accelerated IEC 61215 adaptation unlocks project finance access for commercial-scale tandem deployments. |
| US IRA Domestic Content Capacity Buildout | Arizona and Texas manufacturing facilities capture investment tax credit adders for thin-film equipment deployment. |
| Aqueous Processing Chemistry Reformulation | ECHA REACH pre-registration maintains CE marking eligibility for EU building-integrated sales channels. |
| Architectural Glass Direct Supply Agreement | Skanska-preferred supplier status secures capacity allocation for net-zero certification projects in Copenhagen. |
| Hermetic Barrier Film Technology Licensing | Moisture protection IP monetization addresses warranty and insurability constraints for outdoor installations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at Yangtze River Delta roll-to-roll coating facilities, procurement leads at German facade engineering firms, regulatory affairs specialists navigating ECHA REACH substance reviews, and technical R&D directors at polymer materials suppliers. Secondary validation drew from IEC certification databases, SEC 10-K filings of thin-film equipment manufacturers, EU Green Deal directive documentation, and customs trade data for perovskite precursor imports. Bottom-up capacity build-up and top-down demand segmentation triangulated volume estimates across the analysis window.
Segment-weighting approaches distributed value projections across tandem, transparent, flexible, and bifacial product architectures, with further stratification by hybrid perovskite, polymer, and small molecule material chemistries. End-user segmentation incorporated commercial, automotive, residential, and aerospace application durability requirements, while installation-type modeling distinguished building-integrated, roof-mounted, ground-mounted, and on-demand deployment scenarios. CAGRs derived from manufacturing learning curve analysis and efficiency benchmark trajectories, with explicit incorporation of IRA domestic content bonus phase-out assumptions and EU efficiency mandate tightening schedules.
The model holds under stable lead halide supply access and gradual IEC 61215 certification completion; deviation in Chinese export restriction implementation or perovskite moisture degradation rate discoveries would shift capacity deployment geography and product mix assumptions materially. Forecasts reflect documented assumptions around regulatory timeline adherence and technology stability improvement curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Haptic Technology Market