
 Laser Plastic Welding Market | 2026-2036
Laser Plastic Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Plastic Welding Market Analysis
Medical device OEMs is bifurcating demand away from traditional automotive buyers as miniaturized implantable devices require hermetic polymer seals. TRUMPF GmbH + Co. KG dominates high-power fiber laser system supply for automotive underbody applications. LPKF Laser & Electronics AG specializes in contour welding platforms for medical microfluidics. Han's Laser Technology Industry Group Co., Ltd. anchors volume production of mid-range equipment serving Asian consumer electronics suppliers.
Laser plastic welding joins thermoplastic components through controlled absorption of monochromatic radiation at wavelengths between 800 nm and 2000 nm, creating molecular diffusion bonds without particulate generation or thermal degradation of substrate properties. The process serves critical sealing and structural assembly roles where contamination control and aesthetic finish requirements exclude mechanical fastening or adhesive bonding. Fiber laser technology leads installed capacity due to wall-plug efficiency and beam quality advantages in high-speed contour applications. Medical devices represents the fastest-growing application segment as biocompatible polymer assemblies for diagnostic cartridges and drug delivery systems displace ultrasonic welding. Instruments command premium pricing relative to systems and accessories due to embedded optical path calibration and real-time pyrometry integration.
FDA 21 CFR Part 820 quality system requirements and EU MDR technical documentation standards shape validation protocols for medical welding equipment, extending sales cycles but creating durable supplier relationships. REACH substance restrictions on adhesive constituents and EPA hazardous air pollutant regulations for solvent-based bonding redirect capital expenditure toward laser joining platforms. Stakeholders must monitor divergence between FDA device validation timelines and EU MDR notified body capacity constraints when allocating regional service infrastructure.
Market Dynamics
Vehicle electrification is restructuring polymer joining requirements as battery enclosures and thermal management modules demand hermetic seals without adhesive outgassing. This shift compresses supplier qualification timelines while expanding addressable applications beyond traditional interior trim.
Growth Catalysts
- EU Green Deal solvent elimination mandates:REACH compliance deadlines are accelerating capital reallocation from adhesive bonding toward laser joining platforms across German and French automotive supply chains.
- Miniaturized medical device assembly:Diagnostic cartridge manufacturers require particulate-free sealing methods that preserve sterile fluid pathways in polymer microfluidics.
- Fiber laser wall-plug efficiency gains:Improved beam quality at 1070 nm wavelengths enables high-speed contour welding of polyamide battery housings without thermal degradation.
Market Restraints
- High-purity optical component costs:Fused silica beam delivery systems and galvo scanner assemblies concentrate supply risk among German and Japanese specialty optics suppliers.
- Polymer substrate absorption mismatch:Unfilled polypropylene and polyethylene variants transmit near-infrared wavelengths, requiring carbon black doping or surface coating that adds process steps.
- MDR notified body capacity constraints:EU medical device regulation technical documentation backlogs extend equipment validation cycles by 8-14 months for welding system OEMs.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO quality system requirements for pre-filled syringes and blister packs create demand for hermetic polymer joining without particulate generation.
- Real-time pyrometry integration:Closed-loop temperature monitoring converges with machine vision for adaptive weld depth control in multi-layer automotive lighting assemblies.
- US IRA clean manufacturing incentives:Domestic content bonuses for electric vehicle production are pulling laser welding system procurement toward Michigan and Tennessee battery gigafactories.
Industry Challenges
- Multi-physics simulation expertise gaps:Finite element modeling of laser absorption, heat transfer, and polymer viscoelastic flow requires rare cross-trained process engineers.
- FDA 21 CFR Part 820 validation documentation:Design history file completeness for medical welding equipment demands specialized quality assurance resources that smaller system integrators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Plastic Welding Market |
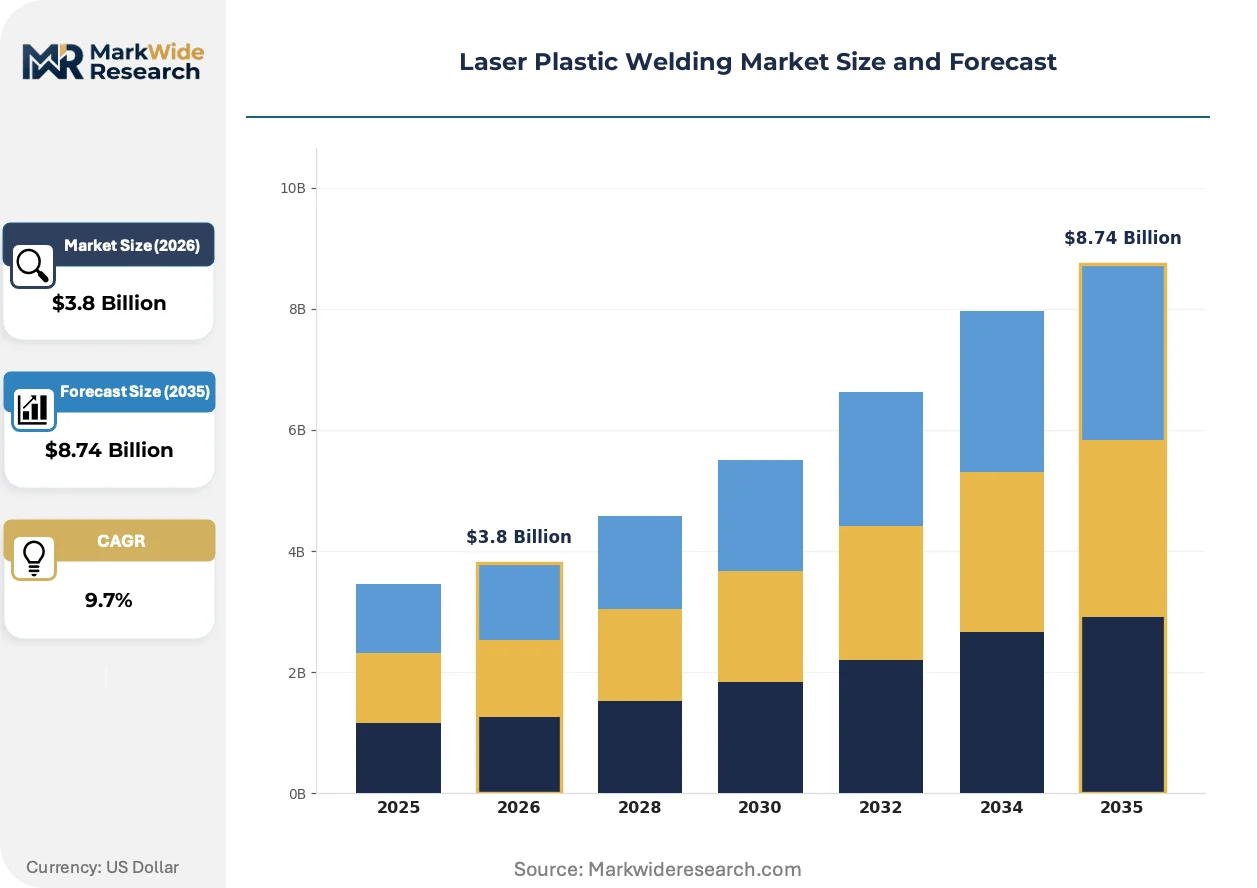
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Systems, Equipment, Accessories Technology: Fiber Laser, CO2 Laser, Solid-state Laser, Ultraviolet Laser Application: Automotive Interiors, Electronics Enclosures, Medical Devices, Consumer Goods End User: Manufacturers, Suppliers, OEMs, Aftermarket Providers |
| Companies Covered | TRUMPF GmbH + Co. KG, Han's Laser Technology Industry Group Co., Ltd., LPKF Laser & Electronics AG, Jenoptik AG, Leister Technologies AG, Dukane IAS LLC, Emerson Electric Co., Amada Miyachi Co. Ltd., DILAS Diodelaser GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Plastic Welding Market Emerging Trajectories
Process control architectures and beam delivery modalities are diverging as end-use requirements splinter between high-volume automotive throughput and medical device precision. Equipment suppliers are engineering distinct platform families rather than configurable universal systems.
Quasi-simultaneous welding using high-speed galvo scanning is fragmenting the contour welding market. Automotive lighting manufacturers adopt this modality for complex three-dimensional seam geometries in tail lamp housings. The technology compresses cycle times by 40-60% compared to traditional Cartesian motion systems while enabling simultaneous multi-spot heating that reduces internal stress in polycarbonate lenses.
REACH substance restrictions on adhesive constituents are redirecting capital expenditure across European appliance and consumer electronics assembly operations. Manufacturers of washing machine control panels and smartphone housings are qualifying laser transmission welding as the default joining method. German white goods producers in North Rhine-Westphalia lead this transition, driven by ECHA enforcement timelines and corporate sustainability commitments.
After-sales service unbundling is disrupting traditional equipment procurement in Asian consumer electronics supply chains. Contract manufacturers in Guangdong and Jiangsu provinces now purchase welding stations without bundled maintenance agreements, instead sourcing spare optics and field service from third-party providers. This behavior compresses OEM service margins while expanding the addressable market for independent calibration and beam path alignment specialists.
Laser Plastic Welding Market Segmentation
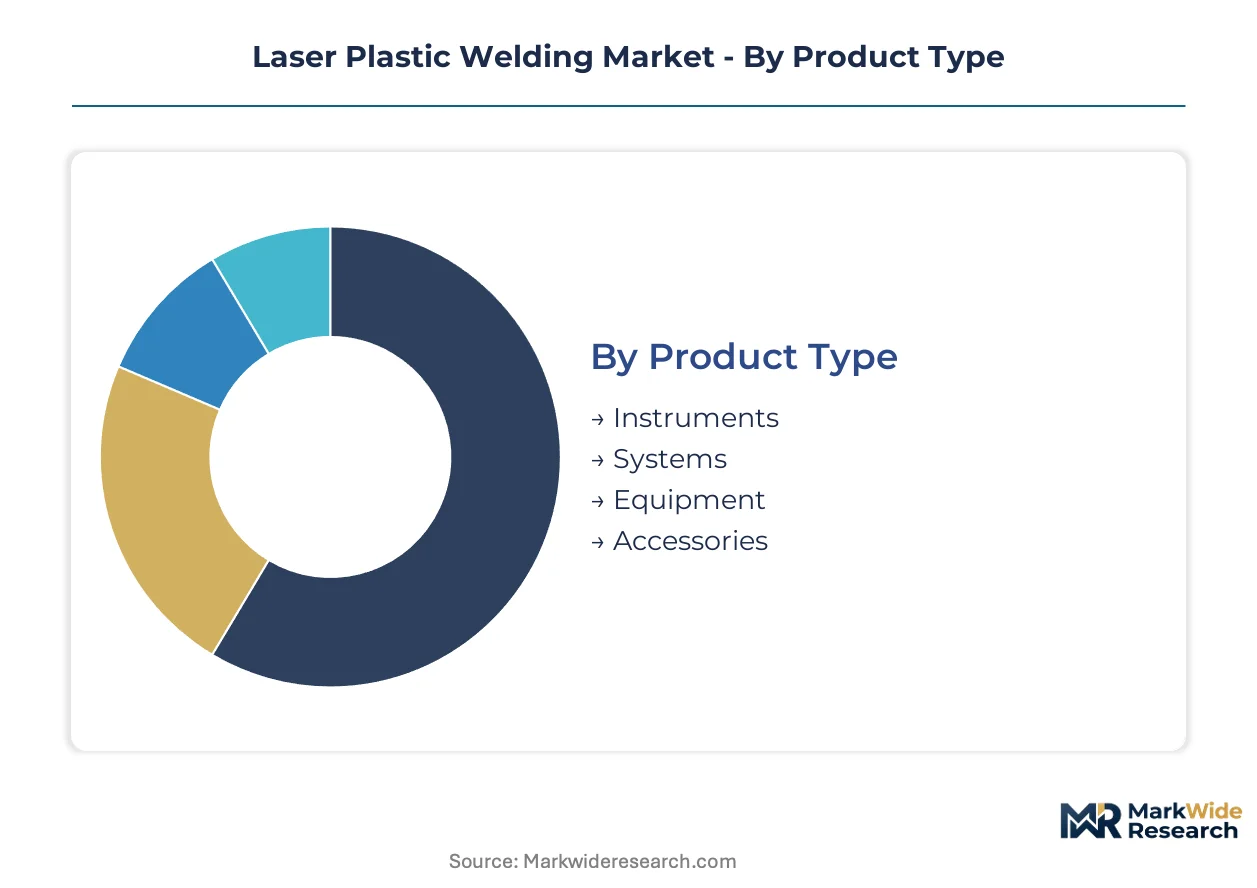
Segmentation in laser plastic welding reveals distinct procurement channels and technical requirements that shape supplier positioning. Equipment buyers diverge sharply between high-volume automotive integrators seeking throughput-optimized systems and medical device specialists prioritizing validation documentation and precision control.
Product Type:
Systems and instruments flow through direct OEM sales channels serving tier-one automotive and medical device manufacturers, while accessories and standalone equipment concentrate in distributor networks supplying mid-tier contract manufacturers and aftermarket service providers.
- Instruments:Embedded optical path calibration modules with real-time pyrometry integration command premium pricing. Demand concentrates in Baden-Württemberg medical device clusters and Michigan battery gigafactories where FDA 21 CFR Part 820 and IRA clean manufacturing incentives drive precision requirements.
- Systems:Turnkey welding platforms with integrated motion control and beam delivery dominate automotive procurement. German and French OEMs prioritize REACH-compliant solvent-free joining configurations for interior trim and battery enclosure applications.
- Equipment:Standalone laser sources and motion stages serve mid-volume manufacturers through regional distributors.
- Accessories:Consumable optics, protective windows, and beam expanders generate recurring revenue in aftermarket channels.
Systems dominate installed base. Instruments is where expansion concentrates.
Technology:
Cost tiers separate high-efficiency fiber platforms from legacy alternatives, with wall-plug efficiency and beam quality determining price positioning across automotive and medical end-uses.
- Fiber Laser:1070 nm wavelength output with superior wall-plug efficiency enables high-speed contour welding of polyamide battery housings without thermal degradation. German automotive supply chains and Asian consumer electronics manufacturers anchor demand.
- CO2 Laser:10.6 µm far-infrared emission suits thick-section welding of opaque polymers where surface absorption dominates. Mature pricing and established service networks sustain presence in appliance and packaging applications.
- Solid-state Laser:Diode-pumped Nd:YAG and Yb:YAG architectures serve legacy medical device installations requiring specific wavelength flexibility.
- Ultraviolet Laser:355 nm and shorter wavelengths enable cold welding of temperature-sensitive biopolymers and transparent substrates.
Fiber laser technology captures the steepest expansion trajectory. CO2 laser retains installed base in thick-section applications.
Application:
Volume concentration varies dramatically by end-use maturity, with automotive interiors representing established high-unit demand and medical devices exhibiting premium pricing per installation.
- Automotive Interiors:Dashboard assemblies, door panels, and center console components require aesthetic finish without witness marks. EU Green Deal solvent elimination mandates accelerate laser adoption across German and French supply chains.
- Medical Devices:Diagnostic cartridges, drug delivery systems, and implantable components demand hermetic polymer seals without particulate generation. FDA validation protocols and EU MDR technical documentation extend sales cycles but lock in supplier relationships.
- Electronics Enclosures:Smartphone housings and wearable device sealing prioritize miniaturization and contamination control.
- Consumer Goods:Appliance control panels and personal care product assembly follow REACH-driven adhesive substitution patterns.
Automotive interiors dominates installed base. Medical devices is where expansion concentrates.
End User:
Customer type determines procurement complexity, with OEMs demanding integrated validation support and aftermarket providers focusing on spare optics and field service availability.
- OEMs:Original equipment manufacturers in automotive and medical sectors specify complete welding cells with documentation packages. CDSCO quality system requirements for Indian pharmaceutical packaging and US IRA domestic content bonuses reshape regional procurement.
- Manufacturers:Tier-two component producers purchase standardized platforms through regional distributors.
- Suppliers:Material and sub-assembly vendors qualify welding capability for upstream integration.
- Aftermarket Providers:Independent calibration specialists and third-party service firms source spare optics and alignment tools.
OEMs dominate installed base. Aftermarket providers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German precision optics manufacturers to Asian battery gigafactories, underwriting laser welding equipment trade flows across the Atlantic and Pacific corridors.
Germany
Baden-Württemberg medical device clusters and Bavarian automotive supply chains drive system procurement for hermetic polymer sealing. EU Green Deal REACH compliance deadlines accelerate capital reallocation from adhesive bonding toward laser joining platforms. Stuttgart and Munich anchor demand concentration for FDA-validated welding cells serving diagnostic cartridge manufacturers.
United States
Michigan and Tennessee battery gigafactories pull laser welding system procurement through IRA clean manufacturing domestic content bonuses. EPA hazardous air pollutant regulations for solvent-based bonding redirect capital expenditure toward laser joining platforms in appliance assembly. Detroit thermal management module producers qualify hermetic sealing systems without adhesive outgassing.
China
Guangdong and Jiangsu contract manufacturers purchase welding stations without bundled maintenance agreements, sourcing spare optics from third-party providers. MIIT industrial upgrading programs support fiber laser adoption in consumer electronics sealing applications. Shenzhen smartphone housing producers drive volume demand for mid-range contour welding equipment.
India
Maharashtra and Gujarat pharmaceutical packaging expansion creates demand for hermetic polymer joining without particulate generation. CDSCO quality system requirements for pre-filled syringes and blister packs reshape equipment validation protocols. Mumbai and Ahmedabad medical device subcontractors qualify laser transmission welding for sterile fluid pathway preservation.
Japan
Kanto region automotive lighting manufacturers adopt quasi-simultaneous welding for complex three-dimensional seam geometries in tail lamp housings. METI carbon neutrality roadmaps push appliance producers toward solvent-free joining processes. Nagoya polycarbonate lens suppliers compress cycle times through high-speed galvo scanning adoption.
Laser Plastic Welding Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and validation documentation capabilities. The vendor base stratifies between high-power system OEMs serving automotive throughput requirements and precision platform builders for medical device hermetic sealing. Three archetypes dominate: German-engineered premium systems, Chinese volume equipment fabricators, and Japanese precision automation specialists. Competitive moves concentrate on regional service infrastructure expansion and real-time process control software unbundling.
Within the premium-system tier, TRUMPF GmbH + Co. KG and Jenoptik AG represent German-engineered archetypes emphasizing optical path calibration and validation documentation. Han's Laser Technology Industry Group Co., Ltd. occupies a position among Chinese volume fabricators serving Asian consumer electronics supply chains. LPKF Laser & Electronics AG exemplifies precision platform specialization for medical microfluidics applications.
| Leading Market Players |
|---|
| TRUMPF GmbH + Co. KG |
| Han's Laser Technology Industry Group Co., Ltd. |
| LPKF Laser & Electronics AG |
| Jenoptik AG |
| Leister Technologies AG |
| Dukane IAS LLC |
| Emerson Electric Co. |
| Amada Miyachi Co. Ltd. |
| DILAS Diodelaser GmbH |
| Others |
Supply Flow & Price Mechanics
Carbon black doping substitution for unfilled polypropylene is redrawing procurement geography as Asian compounders undercut German specialty chemical suppliers, compressing margins on laser-weldable resin formulations while elevating pricing power among beam delivery integrators who control optical path calibration IP.
Pricing Analysis
Volume-discount tiering separates turnkey system OEMs from standalone equipment vendors. Three-tier pricing structure across premium, standard, and economy levels tracks FDA validation documentation depth and real-time pyrometry integration. Cost compression in mid-range fiber laser platforms is intensifying because Chinese volume fabricators are unbundling after-sales service from hardware. Tier-two contract manufacturers in Guangdong exhibit highest price sensitivity; Baden-Württemberg medical device clusters show lowest sensitivity due to hermetic sealing compliance requirements.
Supply Chain Analysis
Straits of Malacca transit underwrites fused silica beam delivery logistics from German precision optics manufacturers to Asian battery gigafactories. High-purity optical components draw from Schott AG and Heraeus operations in Germany, Nippon Electric Glass in Japan, and Corning facilities in the United States. Single-source vulnerability concentrates in galvo scanner assemblies where SCANLAB and Raylase anchor supply. Distribution runs through direct OEM channels for validated medical welding cells and regional distributor networks for mid-volume automotive equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive OEMs consolidate laser welding system procurement through platform standardization mandates, squeezing tier-two equipment vendors who lack validation documentation capabilities.
For Market Incumbents: Compound defensive moats by deepening backward integration into optical path calibration modules and expanding FDA-validated service infrastructure in Michigan battery corridors. Threat from unbundled aftermarket providers in Guangdong demands channel control investments. Certification leverage remains the priority defensive asset. For New Entrants and Emerging Players: Lead with real-time pyrometry software unbundling as the go-to-market angle. Indian pharmaceutical packaging offers the most penetrable white space given CDSCO quality system requirements and limited incumbent validation support. Medical microfluidics contract manufacturers in Maharashtra represent an underserved buyer archetype seeking hermetic sealing without full system procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision platform builders with embedded regulatory documentation capabilities. Long-term viability over the coming decade hinges on medical device validation IP rather than automotive throughput optimization. Watch FDA 21 CFR Part 820 audit backlog resolution as the inflection signal for equipment validation service pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Calibration Modules | Captures margin from German specialty optics suppliers while locking in FDA validation workflows. |
| Real-Time Pyrometry Software Unbundling | Enables adaptive weld depth control for multi-layer automotive lighting assemblies in Nagoya supply chains. |
| FDA 21 CFR Part 820 Validation Infrastructure Expansion | Creates durable supplier relationships with Baden-Württemberg diagnostic cartridge manufacturers. |
| REACH-Compliant Solvent-Free Joining Platform Launch | Accelerates capital reallocation from adhesive bonding across German and French automotive OEMs. |
| Third-Party Aftermarket Service Partnership | Addresses unbundled procurement behavior among Guangdong contract manufacturers seeking spare optics independence. |
Methodological Framework
Initial hypotheses were tested against primary input from laser system procurement directors at Tier 1 automotive suppliers, biomedical engineers at medical device OEMs, and aftermarket service heads at contract manufacturers, then refined against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, SEC 10-K disclosures of listed equipment vendors, and MIIT industrial upgrading program announcements. Bottom-up equipment shipment data triangulated with top-down capital expenditure tracking across battery gigafactory and pharmaceutical packaging investments.
Variance-decomposition across product type, technology wavelength, application end-use, and customer tier shaped the analytical framework over the projection horizon. CAGRs derived from modeled unit economics and replacement cycle assumptions. Industry-specific forecast inputs incorporated fiber laser wall-plug efficiency trajectories and MDR notified body capacity constraints.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 and EU MDR regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as IRA domestic content bonus thresholds and ECHA REACH enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Liquid Cold Plates Market