
 AI-Based Fever Detection Camera Market | 2026-2036
AI-Based Fever Detection Camera Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Based Fever Detection Camera Market Intelligence
Healthcare facilities is recalibrating procurement priorities toward non-contact thermal screening, while transportation authorities scale back pandemic-era bulk orders. Axis Communications AB leverages its Nordic engineering heritage to dominate European healthcare compliance standards. NEC Corporation anchors its position through deep integration of facial recognition with thermal analytics for Japanese transit hubs. Wuhan Guide Infrared Co. Ltd. specializes in uncooled infrared detector manufacturing, sustaining cost advantages in handheld scanner production.
AI-based fever detection cameras combine infrared thermal sensors with machine learning algorithms to measure skin-surface temperature from distances of one to ten meters, typically achieving measurement precision within 0.3 degrees Celsius for fever screening protocols. Their primary purpose is automated, non-invasive triage at high-throughput entry points such as airports, hospitals, and corporate lobbies. Stationary fever detection cameras occupy the mature revenue core as permanent infrastructure in transportation terminals, while multi-sensor fever cameras represent the fastest-expanding category through fusion of thermal, visible-light, and edge-AI analytics. Cloud-based AI processing concentrates margin pools among vendors offering subscription-based fever-alert management platforms for enterprise security teams.
FDA 510(k) clearance pathways and EU MDR Class IIa medical device rules shape product development timelines and market access costs for manufacturers seeking clinical-grade certification. China's NMPA medical device registration and GB standard compliance requirements create additional regulatory filtration for domestic and imported thermal imaging systems. Stakeholders must monitor evolving data privacy frameworks governing facial recognition integration, as GDPR enforcement in Europe and state-level biometric laws in the United States threaten to fragment deployment permissions across jurisdictions.
Market Dynamics
Healthcare procurement teams are consolidating vendor relationships around FDA 510(k)-cleared platforms while phasing out uncertified pandemic-era installations, compressing supplier margins and accelerating certification investments across the supplier base.
Growth Catalysts
- EU MDR Class IIa medical device rules:Hospital procurement committees in Germany and France now mandate CE-marked clinical-grade thermal cameras for patient-facing triage, displacing security-grade alternatives in acute care settings.
- Uncooled infrared detector advances:Microbolometer resolution improvements enable sub-0.3°C precision at 5-meter standoff distances, satisfying airport authority specifications for high-throughput passenger screening without active cooling systems.
- Chinese hospital network expansion:Tier-2 and Tier-3 municipal hospitals under NMPA jurisdiction are retrofitting emergency department entryways with AI-integrated fever screening as standard infrastructure.
Market Restraints
- Vanadium oxide microbolometer supply concentration:Detector wafer fabrication concentrates among three Asian foundry operators, exposing camera OEMs to input cost volatility and allocation constraints during semiconductor demand cycles.
- GDPR biometric data governance:Facial recognition integration with thermal analytics triggers Article 9 special-category data processing restrictions across EU member states, forcing deployment architecture redesigns and legal review costs.
- Handheld infrared thermometer substitution:Low-cost contactless alternatives priced at 15-20% of fixed camera systems satisfy basic fever screening requirements for small clinic and retail environments with lower throughput needs.
Strategic Opportunities
- Indian healthcare infrastructure:CDSCO medical device registration pathways and Ayushman Bharat hospital accreditation standards create first-mover advantages for certified suppliers targeting 150,000+ public health facilities.
- Edge-AI and visible-light sensor convergence:Multi-spectral camera architectures unifying thermal cores with RGB imaging and on-device neural processing enable mask-detection and occupancy-counting revenue streams beyond temperature screening.
- Cloud-based alert management platforms:Enterprise security teams are adopting subscription fever-monitoring dashboards that aggregate camera feeds across distributed facilities, shifting vendor economics toward recurring revenue models.
Industry Challenges
- FDA 510(k) clearance timelines:Clinical validation studies for diagnostic-grade thermal cameras require 18-24 month regulatory cycles, delaying product launches and freezing R&D capital in pre-revenue phases.
- Legacy access control integration:Hospital IT departments struggle to embed AI fever cameras into existing badge-reader and visitor-management workflows without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Based Fever Detection Camera Market |
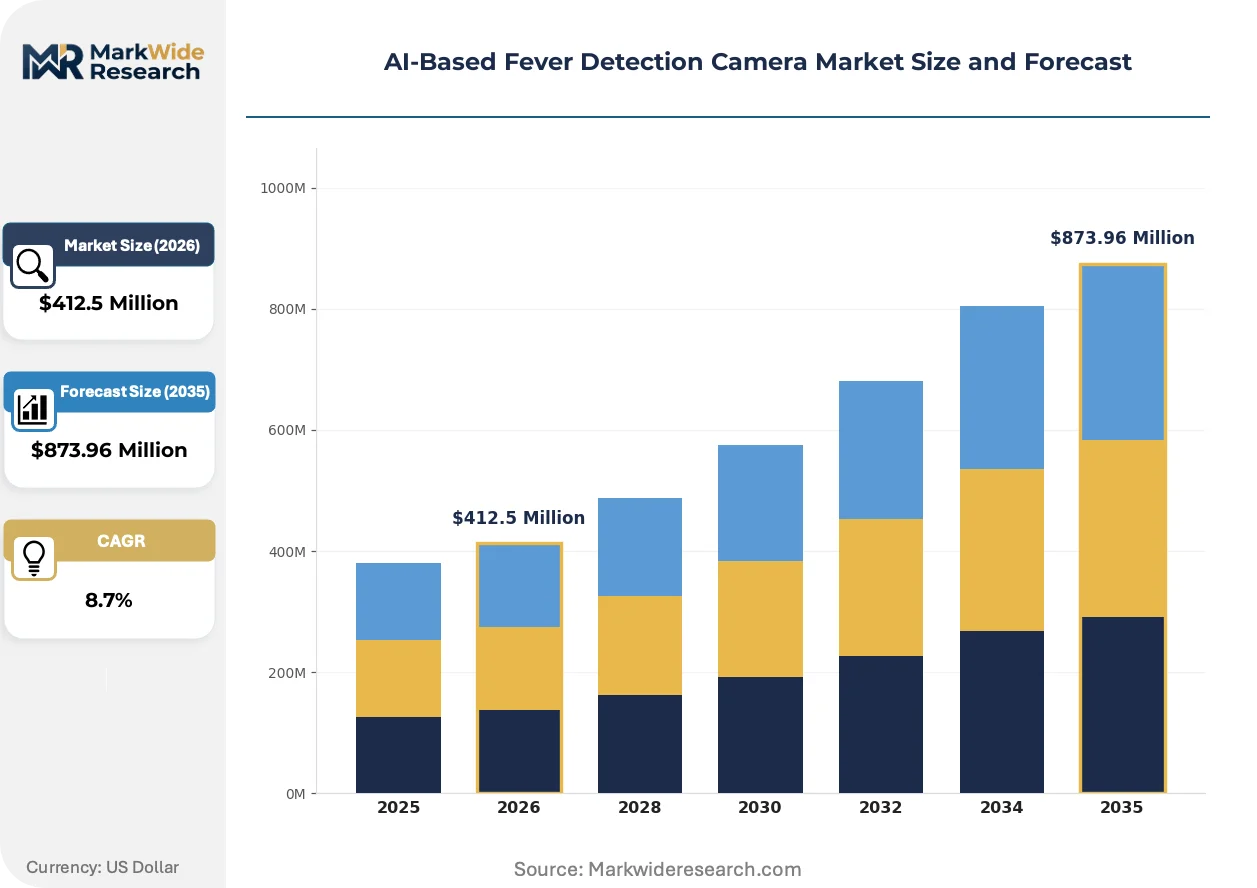
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Fever Detection Cameras, Handheld Fever Scanners, Thermal Imaging Cameras, Multi-Sensor Fever Cameras, Portable Fever Monitors Technology: Infrared Thermal Imaging, Machine Learning Algorithms, Facial Recognition, Edge Computing, Cloud-Based AI Processing Application: Airports Screening, Office Buildings, Public Transport Stations, Educational Institutions, Event Venues End User: Corporate Security Teams, Healthcare Facilities, Transportation Authorities, Educational Administrators, Hospitality Management |
| Companies Covered | Zhejiang Dahua Technology Co. Ltd., Axis Communications AB, NEC Corporation, Nippon Avionics Co. Ltd., Wuhan Guide Infrared Co. Ltd., Baidu Inc., VVDN Technologies, Thermoteknix Systems Ltd., Hangzhou Hikvision Digital Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Based Fever Detection Camera Market Strategic Shifts & Innovations
Sensor fusion architectures and on-device inference capabilities are redefining product roadmaps, while regulatory frameworks governing biometric data processing force hardware-software decoupling in certain jurisdictions.
Multi-spectral fever detection systems are unifying thermal microbolometers, visible-light CMOS sensors, and edge-AI accelerators into single enclosures. Airport authorities in the United States and Germany are specifying these platforms for international terminal deployments. This convergence is unifying what were previously separate security and medical-device procurement categories, forcing vendors to maintain dual certification portfolios.
REACH restrictions on substance-of-very-high-concern (SVHC) content in electronics are pressuring camera manufacturers to reformulate solder alloys and thermal interface materials. Industrial consequences include supply chain requalification costs and extended component qualification timelines. German and French healthcare procurement teams are now requiring full material disclosure documentation, favoring suppliers with established compliance databases.
Enterprise buyers are consolidating fever-screening contracts under integrated facility security vendors rather than standalone thermal camera specialists. Hospital networks and corporate campus operators favor single-source accountability for access control, video management, and health screening. This concentration is most visible in United States metropolitan markets where three national security integrators now control majority share of large-scale deployment contracts.
AI-Based Fever Detection Camera Market Segmentation
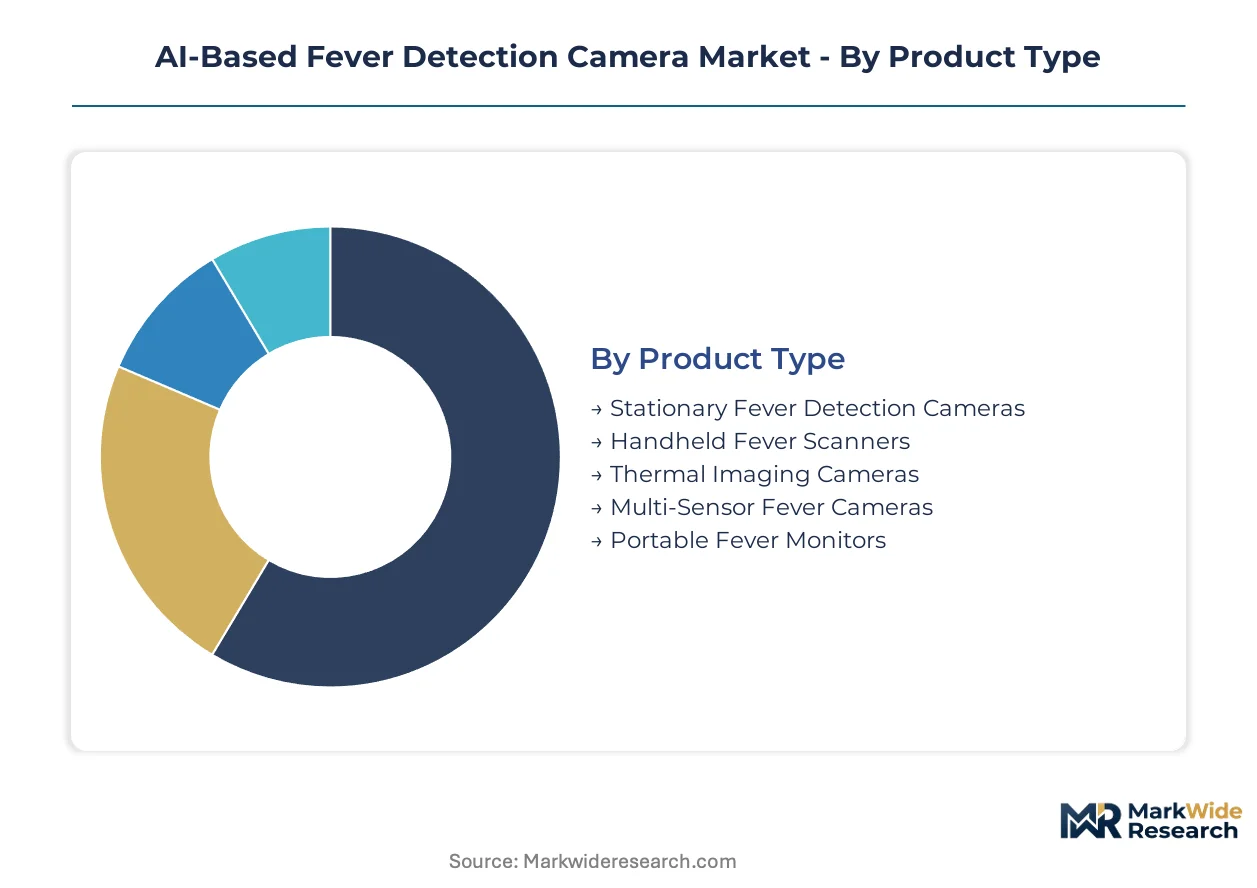
Product differentiation in fever detection cameras hinges on thermal sensor resolution, AI processing location, and integration depth with facility infrastructure. Procurement committees evaluate segments against throughput requirements, regulatory certification tiers, and total cost of ownership across deployment lifecycles.
Product Type:
Thermal sensor form factor and mounting permanence define the hardware segmentation axis, with uncooled microbolometer specifications varying by intended screening distance and environmental conditions.
- Stationary Fever Detection Cameras:Fixed-mount enclosures with calibrated thermal reference sources achieve measurement stability across 3-10 meter standoff distances. Airport authorities in the United States and Germany specify these for international terminal entryways where passenger throughput exceeds 2,000 individuals per hour.
- Multi-Sensor Fever Cameras:Architectures fusing thermal microbolometers with visible-light CMOS and edge-AI accelerators enable mask-detection and occupancy-counting beyond temperature screening. Healthcare facilities in China are retrofitting emergency department entryways with these platforms as standard infrastructure under NMPA jurisdiction.
- Handheld Fever Scanners:Battery-operated pistol-grip units with single-point IR sensors serve mobile triage and secondary confirmation roles.
- Thermal Imaging Cameras:Pan-tilt-zoom capable systems with radiometric video output support forensic temperature logging and retrospective contact tracing.
- Portable Fever Monitors:Tripod-mounted or wheeled cart configurations enable rapid deployment at temporary checkpoints and construction site entryways.
Mature deployment sits with stationary fever detection cameras as permanent transportation infrastructure. Newer deployment is concentrated in multi-sensor fever cameras gaining share fastest through visible-light convergence.
Technology:
Processing architecture location—on-device versus remote—shapes procurement economics, with subscription-based cloud platforms shifting vendor revenue toward recurring models.
- Cloud-Based AI Processing:Centralized neural inference enables model updates without hardware replacement and aggregates fever-alert dashboards across distributed facility networks. Enterprise security teams in the United States metropolitan markets favor these platforms for multi-campus contract consolidation.
- Edge Computing:On-camera GPU or NPU execution eliminates network latency for real-time fever gating decisions and reduces bandwidth requirements for remote facility deployments. German healthcare procurement committees specify edge-AI architectures to satisfy GDPR data minimization principles for biometric processing.
- Infrared Thermal Imaging:Microbolometer-based radiometric measurement provides the foundational temperature-sensing layer across all product configurations.
- Machine Learning Algorithms:Neural networks for skin-region detection and emissivity compensation improve measurement accuracy across varying facial geometries and ethnic skin tones.
- Facial Recognition:Identity verification integration triggers Article 9 special-category data restrictions under GDPR, forcing architecture redesigns in EU member states.
Established revenue concentration remains with infrared thermal imaging as the base sensing layer. Steepest expansion trajectory belongs to edge computing as hospitals prioritize data sovereignty and millisecond-latency screening decisions.
Application:
Throughput intensity and regulatory scrutiny intensity vary sharply across deployment environments, with aviation and healthcare settings commanding premium certification requirements.
- Airports Screening:International terminal deployments require FDA 510(k) or EU MDR Class IIa clinical-grade certification for passenger-facing triage. United States Transportation Security Administration procurement specifications mandate 0.3°C precision at 5-meter distances with active blackbody reference integration.
- Healthcare Facilities:Hospital emergency department entryways and outpatient clinic reception areas demand continuous operation reliability and integration with electronic health record visitor management workflows. Chinese Tier-2 and Tier-3 municipal hospitals under NMPA jurisdiction are standardizing AI-integrated fever screening as infrastructure.
- Office Buildings:Corporate lobby deployments prioritize speed over clinical precision, with security-grade thermal cameras satisfying basic screening protocols.
- Public Transport Stations:Subway and rail hub installations face vandalism resistance and wide temperature operating range requirements.
- Educational Institutions:K-12 and university campus deployments emphasize ease of use for non-technical staff and minimal false-positive alert rates.
- Event Venues:Stadium and convention center temporary installations favor rapid-deployment portable configurations over permanent infrastructure.
Certification-heavy procurement dominates airports screening with the longest sales cycles. Fastest volume growth is appearing in healthcare facilities as pandemic-era temporary installations convert to permanent infrastructure.
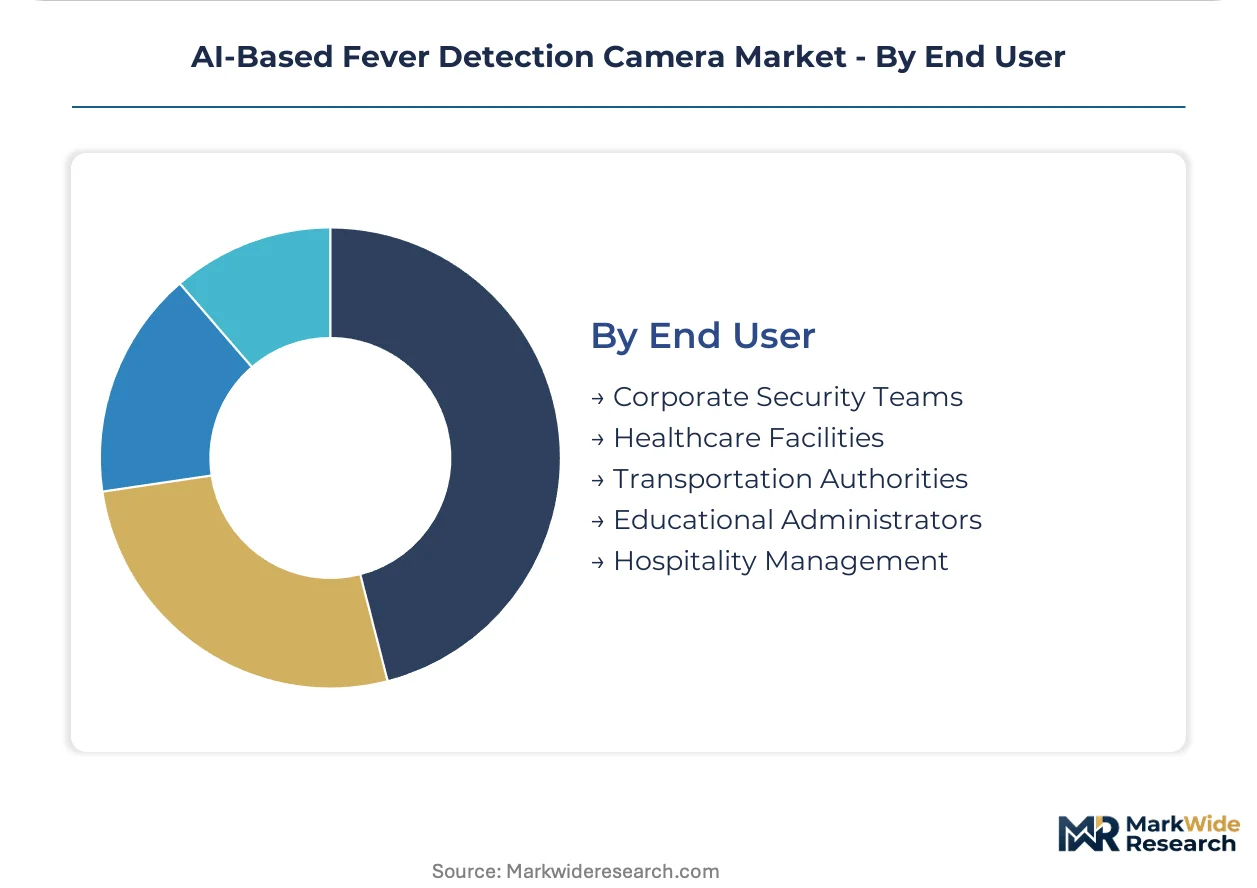
End User:
Budget authority and technical evaluation capability diverge across buyer types, with healthcare procurement teams demanding clinical-grade documentation that corporate security departments rarely require.
- Healthcare Facilities:Hospital infection control committees and biomedical engineering departments evaluate thermal cameras against IEC 60601 medical electrical safety standards and FDA 510(k) diagnostic device pathways. German and French acute care settings now mandate CE-marked clinical-grade platforms, displacing security-grade alternatives.
- Transportation Authorities:Airport and rail network operators specify integration with existing access control and passenger flow management systems, favoring vendors with certified middleware for legacy infrastructure.
- Corporate Security Teams:Facility managers prioritize single-source accountability for video management, access control, and health screening, consolidating contracts under integrated security vendors.
- Educational Administrators:K-12 districts and university facilities departments emphasize total cost of ownership and vendor training support for non-technical staff operation.
- Hospitality Management:Hotel and resort operators deploy lobby screening as guest experience infrastructure, with aesthetic enclosure design influencing procurement decisions alongside technical specifications.
Technical evaluation sophistication peaks with healthcare facilities requiring dual medical-device and security-system certification. Procurement velocity runs fastest with corporate security teams consolidating under facility-wide security integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate thermal imaging component manufacturing, while special economic zones in Bavaria and Texas anchor clinical-grade system assembly for Western markets.
United States
Transportation Security Administration procurement specifications drive demand for FDA 510(k)-cleared thermal cameras at international terminals in Atlanta, Chicago, and Los Angeles. Hospital networks in Texas and California are consolidating vendor relationships around clinical-grade platforms. Dallas-Fort Worth and Houston medical centers lead deployment of AI-integrated fever screening in emergency department entryways.
Germany
EU MDR Class IIa certification requirements now mandate CE-marked clinical-grade thermal cameras for patient-facing triage in acute care settings. Bavarian healthcare procurement committees specify edge-AI architectures to satisfy GDPR data minimization principles. Munich and Stuttgart industrial clusters supply precision thermal reference sources and calibrated mounting hardware for airport installations.
China
Tier-2 and Tier-3 municipal hospitals under NMPA jurisdiction are retrofitting emergency department entryways with AI-integrated fever screening as standard infrastructure. GB standard compliance requirements create regulatory filtration for domestic and imported thermal imaging systems. Wuhan and Shenzhen manufacturing bases specialize in uncooled infrared detector production for cost-optimized handheld scanner exports.
Japan
Transit authorities in Tokyo and Osaka specify deep integration of facial recognition with thermal analytics for high-throughput rail hub screening. METI industrial standards shape product development timelines for medical-grade certification pathways. Nagoya and Yokohama technology clusters advance multi-spectral sensor fusion for next-generation platform development.
India
CDSCO medical device registration pathways and Ayushman Bharat hospital accreditation standards create first-mover advantages for certified suppliers targeting public health facility deployment. Maharashtra and Karnataka state health departments prioritize non-contact screening infrastructure in government medical college hospitals. Mumbai and Bangalore urban clusters concentrate demand from corporate campus security integrators.
AI-Based Fever Detection Camera Market Key Industry Players
Top-tier vendors anchor clinical-grade certification portfolios, while mid-tier specialists compete on uncooled detector cost engineering and rapid deployment flexibility. The vendor base stratifies across three functional tiers: integrated security conglomerates with dual medical-device and surveillance certification, thermal sensor specialists with captive microbolometer manufacturing, and AI software houses licensing analytics to hardware OEMs. Dominant competitive moves include strategic partnerships for legacy access control integration and portfolio diversification into multi-spectral sensor fusion architectures.
Within the thermal sensor specialist tier, Wuhan Guide Infrared Co. Ltd. and Zhejiang Dahua Technology Co. Ltd. represent Chinese manufacturing scale advantages in uncooled microbolometer production. Axis Communications AB occupies a position exemplifying Nordic engineering heritage compliance with European healthcare standards. These three anchors illustrate the geographic segmentation of competitive positioning across cost-optimized manufacturing, regulatory compliance depth, and integrated security ecosystem access.
| Leading Market Players |
|---|
| Zhejiang Dahua Technology Co. Ltd. |
| Axis Communications AB |
| NEC Corporation |
| Nippon Avionics Co. Ltd. |
| Wuhan Guide Infrared Co. Ltd. |
| Baidu Inc. |
| VVDN Technologies |
| Thermoteknix Systems Ltd. |
| Hangzhou Hikvision Digital Technology Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Vanadium oxide spot pricing volatility cascades through microbolometer wafer fabrication costs, compressing margins for camera OEMs while forcing tiered procurement strategies across clinical-grade and security-grade thermal imaging tiers.
Pricing Analysis
Short-lead-time premiums of 15-25% apply to FDA 510(k)-cleared platforms with validated blackbody reference integration, while spot inventory of uncertified security-grade units trades at distressed levels. Pricing stratifies across clinical-grade, security-grade, and economy tiers based on certification tier and thermal sensor resolution. Cost compression in the security-grade tier is intensifying because handheld infrared thermometer substitution erodes fixed-camera value propositions. Corporate security teams exhibit highest price sensitivity, while German hospital procurement committees absorb premiums for EU MDR Class IIa compliance.
Supply Chain Analysis
Reverse-logistics flows for thermal camera refurbishment concentrate in Shenzhen and Dongguan, where component recovery yields 60-70% reuse rates for microbolometer arrays and edge-AI accelerators. Detector wafer fabrication draws from China, Japan, and Taiwan, with uncooled microbolometer cores, thermal reference sources, and visible-light CMOS sensors as critical inputs. Single-source vulnerability concentrates in vanadium oxide microbolometer supply among three Asian foundry operators. Distribution runs through security integrators and medical-device distributors to end-use facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-based fever detection camera economics function as a cost-of-compliance story where FDA 510(k) clearance timelines and EU MDR Class IIa certification requirements erect barrier-to-entry moats favoring incumbent vendors with established regulatory affairs infrastructure.
For Market Incumbents: Lock in hospital network relationships through multi-year service contracts bundling thermal camera maintenance with software update subscriptions. Deepen backward integration into calibrated blackbody reference source manufacturing to secure supply continuity. Certification investment in India's CDSCO registration pathways defends against emerging Chinese competitors targeting Ayushman Bharat infrastructure. For New Entrants and Emerging Players: Enter via India's Tier-2 and Tier-3 municipal hospital segment where CDSCO registration creates first-mover positioning ahead of incumbent certification completion. Target corporate campus security integrators in United States metropolitan markets seeking single-source accountability for access control and health screening convergence. Pursue OEM licensing arrangements with established thermal sensor specialists rather than vertical manufacturing buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor edge-AI software houses with validated neural processing architectures in Germany and Japan, where GDPR compliance engineering and METI certification depth create durable intangible assets. Long-term viability hinges on multi-spectral sensor fusion capabilities spanning thermal, visible-light, and biometric analytics. Monitor NMPA registration acceleration rates for domestic Chinese manufacturers as inflection indicator for pricing pressure direction in export markets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Clinical-grade certification unlocks hospital procurement committees and TSA aviation specifications. |
| EU MDR Class IIa Registration | CE marking mandates displace security-grade alternatives in German and French acute care settings. |
| Multi-Spectral Sensor Fusion | Thermal-visible-AI convergence enables mask-detection and occupancy-counting revenue streams beyond fever screening. |
| Cloud Alert Management Platform | Subscription dashboards aggregate distributed facility feeds, shifting vendor economics toward recurring revenue models. |
| Indian CDSCO Registration | First-mover certification under Ayushman Bharat standards targets 150,000+ public health facility deployments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with hospital biomedical engineers, airport procurement officers, security integrator technical directors, and thermal sensor manufacturing executives. FDA 510(k) premarket notification database, EU MDR notified body certificates, NMPA registration records, and import-export statistics for HS code 9025 thermal imaging apparatus supplied quantitative foundations. Bottom-up facility deployment counts and top-down vendor revenue estimates were reconciled across the analysis window.
Segment-level modeling addressed product type, processing architecture, application environment, and end-user procurement sophistication dimensions across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical certification timeline data and infrastructure replacement cycle patterns. Pricing trajectories incorporated vanadium oxide input cost indices and certification cost amortization schedules. Regional splits reflected national healthcare infrastructure investment programs and aviation authority procurement specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory acceleration or GDPR biometric enforcement expansion scenarios. Practitioners should monitor CDSCO registration completion rates and vanadium oxide foundry capacity utilization for early signals of competitive intensity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Raman-Imaging System Market
Imaging
Frame Grabber Market
Imaging
Camera Lens Market
Imaging
Machine Vision Market
Imaging
Photo Kiosk Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Global AI in Computer Vision Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Industrial Machine Vision Market
Imaging
Photography Ring Flash Market
Imaging
Global 3D Camera Market
Imaging
Digital Camera Market