
 Global Flexible and Printed Electronics Market | 2026-2036
Global Flexible and Printed Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible and Printed Electronics Market Foresight
Modular sensor-to-display bundling is shifting procurement patterns across wearable device supply chains. Samsung Display Co. Ltd leverages vertical integration to sustain captive supply of flexible OLED substrates. DuPont de Nemours, Inc. anchors its position through advanced polyimide substrate chemistry for high-temperature processing. BOE Technology Group Co. Ltd competes aggressively on manufacturing scale, extending roll-to-roll capacity across multiple production sites.
Flexible and printed electronics encompass thin-film semiconductor devices, conductive traces, and functional layers deposited on bendable polymer substrates typically below 0.3 mm thickness, enabling conformal integration with curved surfaces for applications ranging from epidermal health monitors to logistics tracking. The primary commercial purpose centers on replacing rigid glass-and-silicon assemblies with mechanically compliant alternatives that reduce weight and enable new product geometries. Flexible sensors and printed circuit boards concentrate margin pools near automotive and medical certification tiers, while E-paper displays dominate volume in retail and logistics applications where ultra-low power draw determines procurement decisions. Roll-to-roll processing leads technology adoption for high-throughput film production, though inkjet printing captures precision segments requiring non-contact deposition on delicate substrates.
EPA guidelines govern volatile organic compound emissions from solvent-based printing processes in US manufacturing facilities, while REACH restricts specific phthalate plasticizers and heavy metal pigments across European supply chains. FDA biocompatibility standards for skin-contact wearable devices create additional compliance layers for medical-oriented flexible electronics entrants. Korea's Ministry of Trade, Industry and Energy (METI-equivalent functional role) and China's Ministry of Industry and Information Technology (MIIT) both channel industrial policy support into domestic display and printed electronics ecosystems. Stakeholders must monitor evolving substance restrictions and recyclability mandates as regulatory divergence between jurisdictions threatens to fragment material qualification pathways.
Market Dynamics
Roll-to-roll manufacturing scale-up is compressing unit economics for flexible substrates while REACH substance restrictions force reformulation of conductive inks across European supply chains.
Growth Catalysts
- Wearable Device Conformality Requirements:Consumer electronics OEMs demand epidermal-grade form factors for health monitoring patches, pulling polyimide substrate volumes into medical certification tiers.
- REACH-Driven Material Innovation:ECHA restrictions on phthalate plasticizers and heavy metal pigments accelerate bio-based conductive ink development for European medical wearable entrants.
- South Korea Display Ecosystem Concentration:Domestic panel manufacturing clusters anchor captive demand for flexible OLED backplanes and printed circuit integration.
Market Restraints
- Silver Flake Input Volatility:Conductive ink formulations depend on precious metal feedstocks whose price swings compress margin predictability for printed electronics converters.
- Single-Source Equipment Dependency:High-precision roll-to-roll coating lines concentrate among German and Japanese capital equipment suppliers, creating delivery bottlenecks during capacity expansions.
- Thermal Stability Ceiling:Polymer substrate glass transition temperatures below 400°C limit semiconductor processing options versus rigid silicon alternatives.
Strategic Opportunities
- India Domestic Manufacturing Incentives:PLI scheme allocations for electronics manufacturing services attract flexible circuit board assembly investments outside traditional East Asian supply nodes.
- Automotive Interior Surface Integration:HMI designers embed capacitive touch sensors directly into curved dashboard substrates, displacing discrete mechanical switch assemblies.
- EU Battery Passport Mandates:CSRD-adjacent traceability requirements create demand for printed RFID-integrated smart labels across European EV supply chains.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Convergent expertise spanning polymer chemistry, semiconductor thin-film processing, and roll-to-roll mechanical engineering remains concentrated among veteran practitioners in Korea and Japan.
- Medical Certification Timeline Compression:FDA 510(k) pathways for skin-contact wearable electronics extend 18-24 months, delaying revenue recognition for flexible sensor entrants targeting remote patient monitoring contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible and Printed Electronics Market |
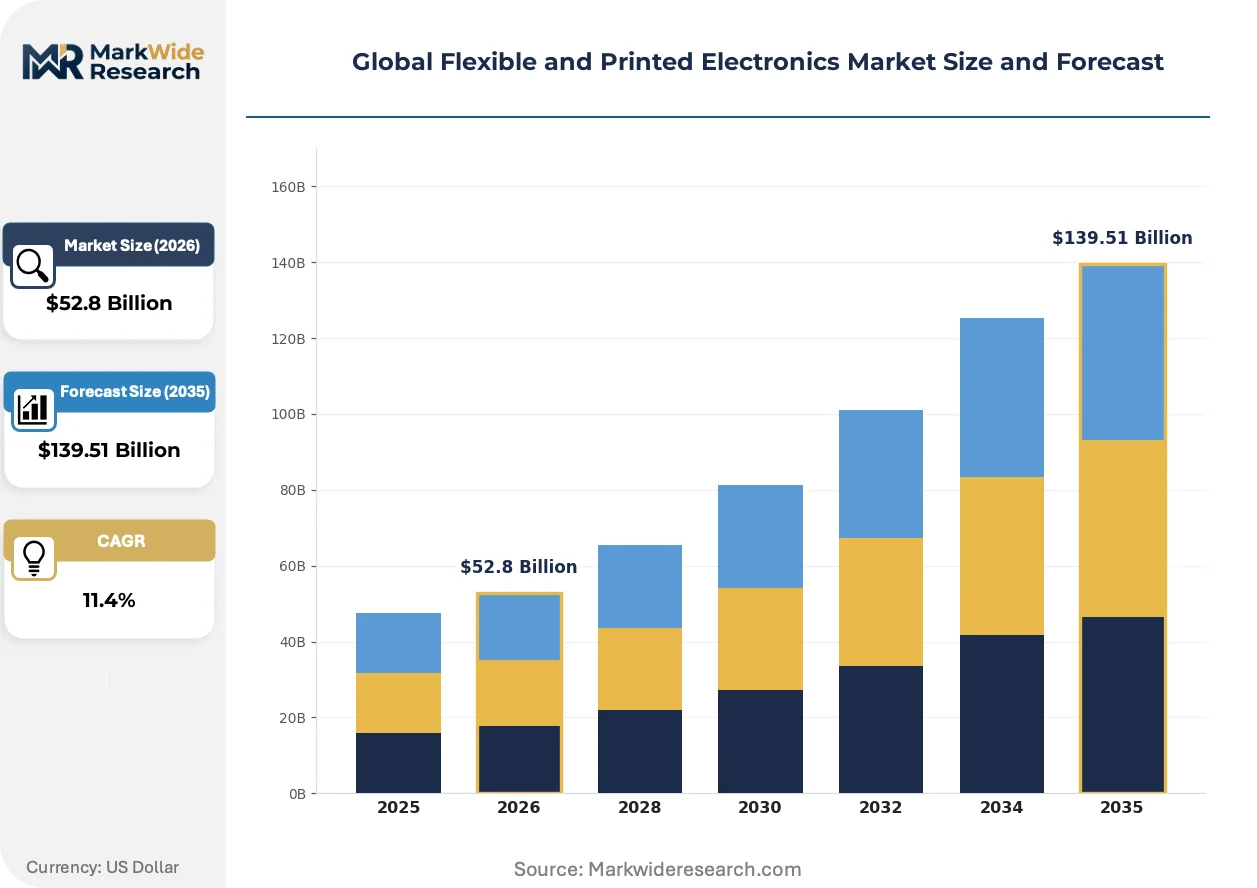
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $139.51 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Sensors, Organic Photovoltaics, Printed Circuit Boards, E-Paper Displays, RFID Tags Technology: Organic Electronics, Thin-Film Transistors, Inkjet Printing, Roll-to-Roll Processing, Screen Printing Application: Wearable Devices, Smart Packaging, Consumer Electronics, Aerospace Electronics, Smart Cards End User: Electronics Manufacturers, Defense Contractors, Aerospace Suppliers, Packaging Firms, Consumer Device OEMs |
| Companies Covered | AU Optronics Corp., DuPont de Nemours, Inc., Samsung Display Co. Ltd, Royole Corporation, 3M Company, LG Display Co. Ltd, E Ink Holdings Inc., FlexEnable Ltd, BOE Technology Group Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible and Printed Electronics Market Shifts & Advancements
Hybrid manufacturing workflows are dissolving boundaries between precision printing and conventional semiconductor fabrication, enabling new substrate-material combinations previously excluded by thermal budget constraints.
Micro-LED transfer printing is converging with flexible polyimide carrier films to enable direct-view displays on curved automotive surfaces. Tier 1 suppliers in Germany and Japan are piloting this integration for next-generation instrument clusters. The process compression eliminates wire-bonding steps that previously constrained form factor freedom.
EPA volatile organic compound emission limits for solvent-based screen printing are forcing US-based converters toward water-borne or UV-curable ink systems. Reformulation costs concentrate among smaller job shops lacking in-house analytical chemistry capabilities. Medical wearable specialists with FDA-registered facilities face accelerated compliance timelines versus industrial labeling segments.
Modular sensor-to-display bundling contracts now dominate procurement for fitness and medical wearable OEMs, displacing discrete component sourcing. Contract manufacturers in China and Vietnam capture assembly margin pools previously held by brand-owned facilities. Korean consumer electronics groups lead this consolidation, leveraging captive substrate supply to compress vendor counts.
Global Flexible and Printed Electronics Market Segmentation
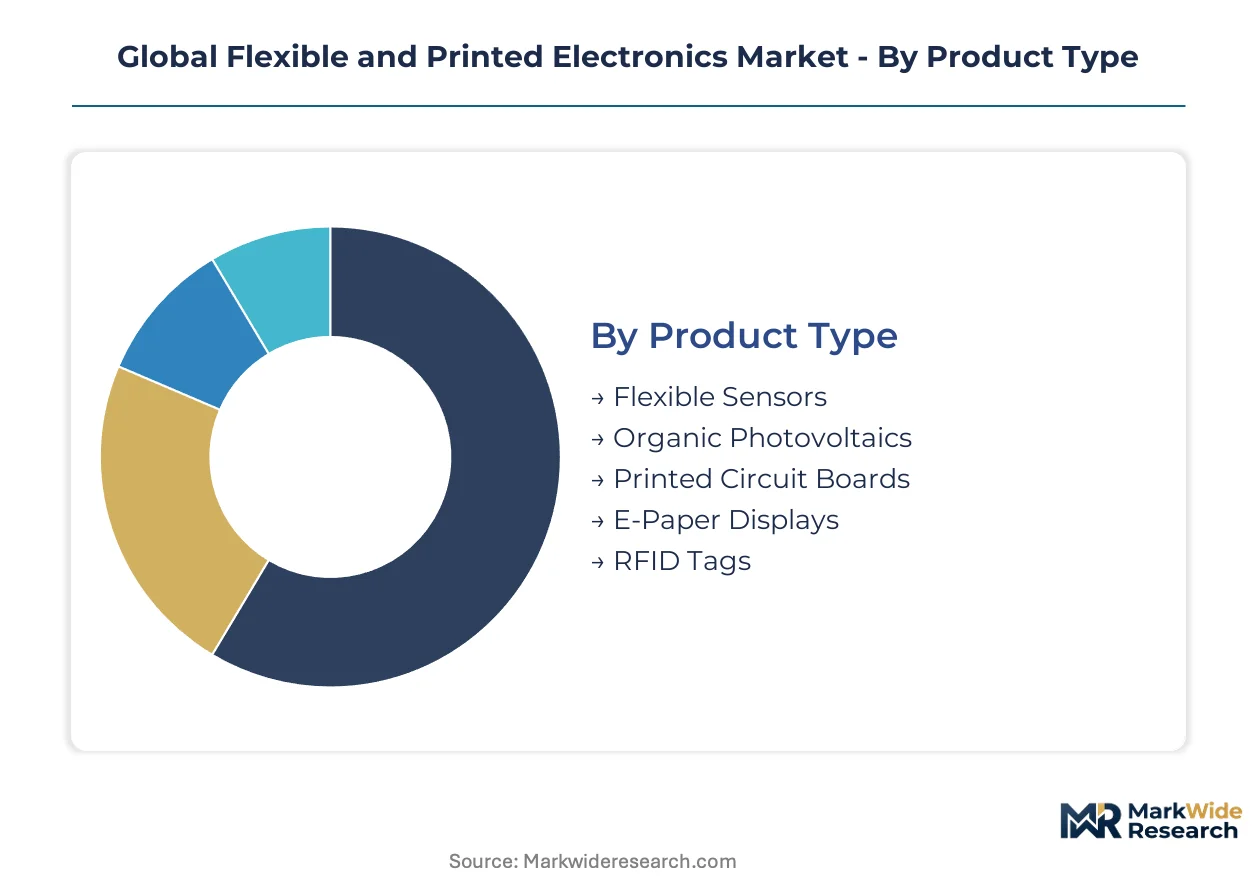
Segmentation in flexible and printed electronics reveals how substrate properties, deposition precision, and certification tiers fragment procurement decisions across medical, automotive, and logistics end-uses. Buyers prioritize thermal budget compatibility, biocompatibility clearance, or unit cost depending on whether the application demands epidermal contact, curved dashboard integration, or disposable supply chain tracking.
Product Type:
End-users select product categories based on mechanical compliance requirements and power budget constraints rather than raw performance metrics.
- Flexible Sensors:Polyimide or PET substrates carry conductive traces for strain, temperature, or bioimpedance measurement in skin-contact wearables. Demand clusters in South Korea and China where consumer electronics OEMs source epidermal health monitoring patches requiring ISO 10993 biocompatibility certification.
- E-Paper Displays:Bistable electrophoretic films on flexible backplanes enable ultra-low-power signage and shelf labels. Logistics operators in Germany and Japan deploy these for warehouse inventory systems where battery replacement cycles stretch across multiple years.
- Printed Circuit Boards:Silver or copper traces on polyimide substrates replace rigid FR-4 assemblies in space-constrained devices.
- Organic Photovoltaics:Solution-processed active layers on barrier-coated films target indoor energy harvesting for IoT sensors.
- RFID Tags:Printed antenna coils on paper or PET substrates serve retail and pharmaceutical supply chain authentication.
Volume sits with E-Paper Displays; growth tilts toward Flexible Sensors.
Technology:
Process selection hinges on throughput requirements versus pattern resolution, with high-volume film production favoring continuous methods and precision electronics demanding droplet-level control.
- Roll-to-Roll Processing:Continuous coating and patterning of flexible substrates at web speeds exceeding meters per minute drives unit cost compression for film-based products. South Korean display panel ecosystems anchor captive demand for OLED backplane manufacturing where thermal annealing steps require synchronized tension control.
- Inkjet Printing:Non-contact droplet deposition enables multimaterial stacking on delicate or pre-patterned substrates without mechanical damage. Medical wearable specialists in Switzerland and the United States leverage this for customized sensor geometries where screen printing squeegee pressure would fracture functional layers.
- Screen Printing:High-viscosity paste deposition for thick-film conductive traces on textile or rough substrates.
- Thin-Film Transistors:Vacuum-deposited semiconductor channels on flexible carriers enable active-matrix backplane switching.
- Organic Electronics:Solution-processed semiconducting polymers and small molecules for low-cost, large-area optoelectronics.
Roll-to-Roll Processing commands installed capacity; Inkjet Printing gains share fastest in medical and aerospace qualification tiers.
Application:
Application selection follows end-user tolerance for price premium versus form factor freedom, with regulated medical and aerospace segments accepting longer qualification timelines.
- Wearable Devices:Conformal health monitoring patches, fitness bands, and smartwatch displays integrate flexible sensors and OLED panels on curved wrist geometries. Samsung Electronics and Apple procurement contracts drive substrate volumes through South Korean and Chinese supply chains.
- Smart Packaging:Printed sensors and indicators embedded in pharmaceutical and food packaging monitor temperature excursions or tampering events. European logistics operators face CSRD-adjacent traceability mandates that accelerate RFID-integrated label adoption across EV battery and pharmaceutical supply chains.
- Consumer Electronics:Foldable smartphones and curved television panels push substrate bending radius specifications below 5mm.
- Aerospace Electronics:Lightweight, conformal antenna arrays and cabin interior sensors reduce mass versus rigid PCB alternatives.
- Smart Cards:Embedded flexible secure elements and antenna coils for contactless payment and identification credentials.
Wearable Devices concentrate revenue; Smart Packaging shows steepest expansion trajectory as regulatory traceability requirements proliferate.
End User:
Procurement authority varies by vertical, with defense and aerospace contractors imposing stringent qualification protocols that exclude commodity-grade suppliers.
- Consumer Device OEMs:Vertically integrated electronics groups in South Korea and China source flexible OLED backplanes and sensor modules through captive display subsidiaries. Samsung Display Co. Ltd internalizes substrate supply to compress vendor counts and accelerate iteration cycles for foldable smartphone form factors.
- Defense Contractors:Northrop Grumman and BAE Systems procurement specifications for conformal antenna and wearable soldier systems mandate ITAR compliance and extended environmental testing. These requirements filter supplier pools to domestic U.S. and UK facilities with established security clearances.
- Electronics Manufacturers:Contract assembly houses in Vietnam and Mexico integrate flexible circuit boards into finished devices.
- Aerospace Suppliers:Tier 1 integrators in Germany and Japan specify flame-retardant polyimide grades for cabin interior applications.
- Packaging Firms:Brand owners and converters in the Netherlands and California pilot printed sensor integration for cold chain verification.
Electronics Manufacturers handle greatest transaction volume; Defense Contractors impose the steepest qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian display clusters while consumption spreads across North American medical device developers and European logistics operators. South Korea and China anchor manufacturing scale through vertically integrated panel ecosystems. Germany and the United States drive specialized demand for automotive and healthcare applications.
South Korea
Samsung Display and LG Display anchor captive demand for flexible OLED backplanes through their Seoul Capital Area fabrication complexes. Korea's Ministry of Trade, Industry and Energy channels industrial policy support into domestic printed electronics ecosystems via R&D tax credits and equipment depreciation allowances. The Gyeonggi-do cluster surrounding Suwon houses concentrated roll-to-roll coating capacity serving foldable smartphone substrate requirements.
China
BOE Technology Group extends roll-to-roll capacity across Beijing, Hefei, and Chengdu production sites to capture wearable device OEM procurement contracts. MIIT industrial policy directs subsidies toward domestic display material localization, reducing import dependency for polyimide substrates and silver conductive pastes. The Yangtze River Delta around Shanghai concentrates precision inkjet printing equipment assembly for medical wearable specialists.
United States
Medical wearable developers in Massachusetts and California drive FDA 510(k) qualified demand for biocompatible flexible sensors. EPA volatile organic compound emission limits for solvent-based screen printing force converters toward water-borne ink systems, concentrating reformulation costs among smaller job shops. The Boston-Cambridge corridor hosts concentrated thin-film transistor research bridging MIT spinouts with defense contractors.
Germany
Automotive Tier 1 suppliers in Bavaria and Baden-Württemberg embed capacitive touch sensors into curved dashboard substrates for BMW and Mercedes-Benz instrument clusters. REACH restrictions on phthalate plasticizers accelerate bio-based conductive ink qualification timelines for European medical wearable entrants. The Stuttgart industrial zone concentrates micro-LED transfer printing pilot lines for next-generation automotive display integration.
Japan
E Ink Holdings and precision equipment manufacturers anchor demand for electrophoretic film production in the Chubu region around Nagoya. METI technology roadmaps prioritize flexible electronics integration into aging population healthcare monitoring systems. The Kansai corridor between Osaka and Kyoto houses concentrated barrier coating expertise for organic photovoltaic encapsulation.
Global Flexible and Printed Electronics Market Competitive Landscape
The competitive structure tilts toward vertically integrated display specialists with captive substrate supply. Korean and Chinese electronics groups internalize polyimide backplane production to compress vendor counts and accelerate iteration cycles. Three archetypes dominate: integrated panel manufacturers controlling upstream material flow, specialty chemical suppliers anchoring substrate chemistry differentiation, and precision equipment vendors capturing roll-to-roll coating line margins. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players seek to bridge semiconductor fabrication precision with high-throughput film processing.
Among integrated display specialists, Samsung Display Co. Ltd and BOE Technology Group Co. Ltd exemplify the scale-driven archetype through multi-site roll-to-roll capacity deployment. DuPont de Nemours, Inc. occupies a position within the materials tier, representing specialty chemical suppliers whose substrate formulations enable high-temperature processing compatibility. These three entities collectively illustrate how competitive positioning fragments between manufacturing scale control and material science differentiation.
| Leading Market Players |
|---|
| AU Optronics Corp. |
| DuPont de Nemours, Inc. |
| Samsung Display Co. Ltd |
| Royole Corporation |
| 3M Company |
| LG Display Co. Ltd |
| E Ink Holdings Inc. |
| FlexEnable Ltd |
| BOE Technology Group Co. Ltd |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FDA-registered medical wearable substrates and commodity-grade logistics labels manifests in pricing spreads exceeding 4x at the converter level, with supply chain configurations diverging toward captive Korean display ecosystems versus distributed Chinese assembly houses. This tier divergence concentrates margin pools near ISO 10993-qualified polyimide suppliers while compressing returns on PET-based RFID antenna production.
Pricing Analysis
Margin tightening in medical-grade flexible sensors reflects silver flake feedstock volatility and extended FDA 510(k) qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates epidermal biocompatibility-certified substrates from industrial-grade alternatives. Cost-down pressure on commodity printed circuit boards accelerates because BOE and Samsung Display internalize polyimide backplane production. Consumer electronics OEMs exhibit lowest price sensitivity for foldable smartphone substrates, while logistics operators demand sub-cent unit economics for disposable RFID labels.
Supply Chain Analysis
ISO 13485 and FDA-registered facility requirements gate medical wearable substrate supply to Massachusetts and California cleanroom operations, while automotive qualification tiers concentrate barrier coating expertise in Stuttgart and Nagoya. Raw material dependencies center on silver conductive pastes from Japanese chemical suppliers, high-purity polyimide resins, and precision roll-to-roll coating lines from German and Japanese capital equipment vendors. Single-source equipment vulnerability creates delivery bottlenecks during capacity expansions. Distribution runs through vertically integrated Korean display subsidiaries for OLED backplanes, and through Vietnamese contract manufacturers for fitness band assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible and printed electronics is becoming a vertical-integration race where substrate chemistry control and roll-to-roll capacity ownership determine pricing power. Players capturing upstream polyimide formulation or downstream display module assembly secure margin pools unavailable to component converters.
For Market Incumbents: Hedge silver flake price exposure through long-term offtake agreements with precious metal refiners, and defend medical certification moats by accelerating FDA-registered cleanroom capacity in the Boston-Cambridge corridor against emerging Swiss and German entrants. Backward integration into high-temperature polyimide resin production reduces dependency on DuPont substrate supply. For New Entrants and Emerging Players: REACH in Europe opens a window for bio-based conductive ink specialists to displace phthalate-dependent formulations in medical wearable supply chains. Target Indian PLI scheme allocations for flexible circuit board assembly outside traditional East Asian nodes. Pursue automotive interior surface integration contracts with Bavarian Tier 1 suppliers as the most penetrable premium segment. For Investors and Strategic Acquirers: Re-rating potential sits with specialty chemical suppliers given ECHA substance restriction tailwinds accelerating material reformulation cycles. Long-term viability favors substrate chemistry innovators with thermal stability above 400°C enabling micro-LED transfer printing adoption. Monitor Korean Ministry of Trade, Industry and Energy equipment depreciation allowance announcements as inflection indicators for regional capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Resin Production | DuPont substrate chemistry dominance weakens as Korean display groups develop captive formulations. |
| Micro-LED Transfer Printing Pilot Line Deployment | Stuttgart automotive Tier 1 suppliers validate curved dashboard integration for BMW and Mercedes-Benz clusters. |
| FDA 510(k) Registration Facility Investment | Massachusetts medical wearable developers secure biocompatibility-certified supply priority for remote patient monitoring contracts. |
| REACH-Compliant Bio-Based Ink Formulation | Swiss and German medical specialists displace phthalate-dependent competitors in European epidermal health patch procurement. |
| Roll-to-Roll Capacity Expansion in India | PLI scheme allocations attract flexible circuit assembly outside Vietnam-dominated consumer electronics supply chains. |
Research Methodology
Document review covered SEC filings from display panel manufacturers, ECHA substance restriction databases, and FDA 510(k) clearance records, complemented by interviews with polymer chemistry R&D directors, medical device procurement managers at Korean consumer electronics groups, roll-to-roll equipment engineers in Germany and Japan, and logistics operators deploying E-paper shelf labels. Bottom-up demand modeling for flexible sensor volumes across wearable device OEMs triangulated against top-down display panel production forecasts from MIIT and Korean Ministry of Trade, Industry and Energy disclosures.
Historical capacity utilization patterns from Korean and Chinese display fabs were cross-referenced against panel input from substrate chemistry specialists and automotive Tier 1 HMI designers. Segmentation dimensions modeled included product type, deposition technology, application vertical, and end-user procurement authority tier. CAGRs were derived from installed roll-to-roll line counts and inkjet printing qualification timelines across medical and aerospace certification tiers. Forecast inputs incorporated EPA volatile organic compound emission limit enforcement trajectories and EU Battery Passport mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for solution-processed organic photovoltaics or atomic layer deposition barrier coatings would alter the outlook for indoor energy harvesting and flexible encapsulation demand. Forecasts reflect assumptions regarding Korean industrial policy continuity and silver price stabilization. A model refresh is warranted upon material change in ECHA substance restriction scope or FDA breakthrough device designation pathways for skin-contact wearables.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Lab on Chips Market