
 High Voltage Circuit Breaker Market | 2026-2036
High Voltage Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Circuit Breaker Market Intelligence
SF6-free insulation technology is fragmenting traditional product architectures across the high voltage circuit breaker landscape. ABB leverages its vacuum interrupter portfolio to capture early-phase utility tenders in Europe. Siemens Energy anchors large-scale projects through in-house production of GIS assemblies. Mitsubishi Electric competes on 800 kV+ ultra-high voltage expertise across Asian markets.
A high voltage circuit breaker is an electromechanical switching device rated for voltages above 72.5 kV, designed to interrupt fault currents up to 63 kA or higher using arc quenching media such as sulfur hexafluoride, vacuum, or compressed air. Its primary purpose is protecting transmission infrastructure by isolating electrical faults within milliseconds to prevent cascading grid failures. Sulfur hexafluoride retains dominant installed base share despite environmental pressure, while vacuum technology captures fastest growth in 72.5–145 kV urban substations where leakage risk faces regulatory scrutiny. Air insulated variants occupy mature, cost-sensitive segments in emerging markets where capital constraints outweigh footprint concerns.
The EU F-Gas Regulation mandates phased SF6 reduction in new switchgear, compelling manufacturers to redesign arc quenching systems. IEC 62271 and IEEE C37 series define interruption capability and seismic withstand standards that gate market access across regions. Grid operators in China face MEE oversight on fluorinated gas inventory reporting. Stakeholders must weigh stranded asset risk in SF6-dependent installed bases against the engineering maturity of alternative interruption technologies.
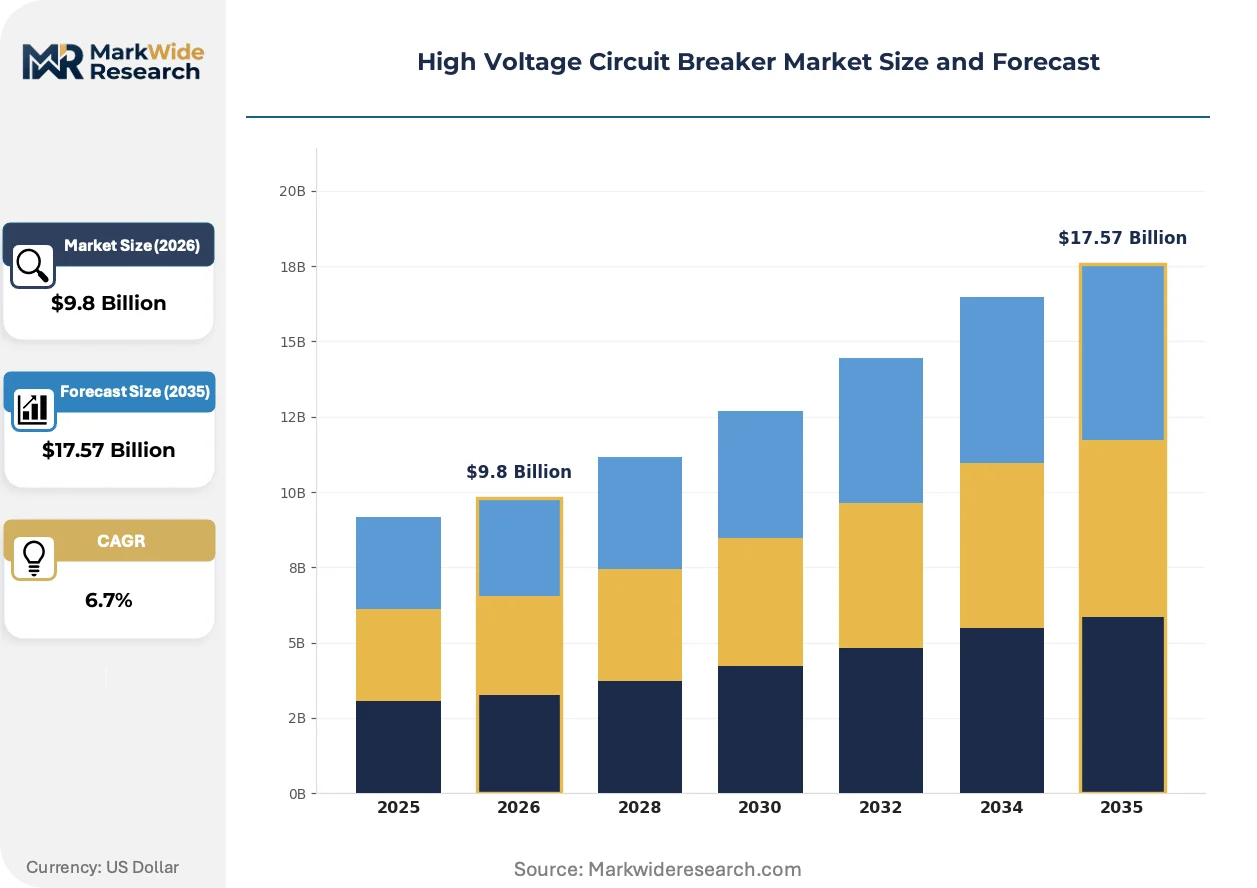
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale re-architecture of arc quenching systems across the installed base, compressing product development cycles while elevating vacuum interrupter engineering to mission-critical status.
Growth Catalysts
- Grid Modernization Mandates:China's dual carbon goals and transmission expansion targets are accelerating procurement of 550 kV+ circuit breakers for ultra-high voltage corridors connecting western generation to eastern load centers.
- IEC 62271-100:Tightened interruption performance requirements for capacitive current switching are disqualifying legacy designs and opening tender opportunities for next-generation spring-operated mechanisms.
- Urban Substation Density:Vacuum technology is capturing 72.5–145 kV applications in German and Japanese metropolitan networks where footprint constraints and leakage risk dominate site selection criteria.
Market Restraints
- Copper and Rare Earth Volatility:Permanent magnet actuator systems depend on neodymium supply concentrated in Chinese processing facilities, exposing BOM costs to export quota fluctuations.
- SF6 Gas Banking Requirements:The EU F-Gas Regulation mandates inventory tracking and phased reduction, imposing compliance overhead that disadvantages smaller manufacturers lacking gas handling infrastructure.
- Voltage Ceiling Limitations:Vacuum interrupters face dielectric recovery challenges above 245 kV, constraining their addressable market to medium-voltage ranges despite environmental advantages.
Strategic Opportunities
- India Transmission Buildout:Green Energy Corridors and renewable energy zones are creating demand for 400 kV GIS installations where domestic manufacturing incentives under the PLI scheme favor local assembly partnerships.
- Digital Twin Integration:Convergence of circuit breaker mechanics with IIoT sensor networks enables predictive maintenance contracts that extend customer lifetime value beyond hardware margins.
- Retrofit Services:Aging air-blast installations in North American utilities present white-space for modular vacuum retrofits that bypass complete substation rebuilds.
Industry Challenges
- High-Voltage Vacuum Engineering Talent:The specialized physics of ultra-high voltage vacuum arc interruption commands limited global expertise, constraining R&D velocity at firms attempting SF6-free migration.
- Type Test Certification Timelines:IEC 62271-100 full short-circuit testing requires months of queue time at accredited laboratories, delaying product launches and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Circuit Breaker Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfur Hexafluoride, Air Insulated, Vacuum, Oil Insulated Technology: Hybrid, Electronically-Controlled, Electro-Hydraulic, Mechanical End User: Utilities, Manufacturing, Renewable Energy, Data Centers Installation: Indoor, Outdoor, Modular, Integrated |
| Companies Covered | ABB, GE Vernova, Hitachi Energy, Schneider Electric, Siemens Energy, Mitsubishi Electric, CG Power & Industrial Solutions, Pfiffner Group, Toshiba International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Circuit Breaker Market Strategic Shifts & Innovations
Solid-state switching concepts and hybrid interruption architectures are compressing the traditional electromechanical paradigm, while regulatory chemistry restrictions accelerate material science investment.
Vacuum interrupter technology with axial magnetic field contacts is rendering obsolete SF6-dependent puffer designs in the 72.5–145 kV urban substation segment. German municipal utilities and Japanese regional power companies are specifying vacuum-first procurement policies for new 66 kV and 110 kV installations. The structural consequence is a bifurcation in supplier capabilities, with firms lacking vacuum manufacturing heritage facing exclusion from premium European and East Asian tenders.
The EU F-Gas Regulation mandates 67% reduction in SF6 use by 2030 from 2014 baseline levels, compelling manufacturers to redesign arc quenching systems around alternative media. Industrial consequence includes accelerated patent filing in vacuum bottle sealing and compressed air blast optimization. GIS manufacturers serving Scandinavian markets are responding with product line conversions that eliminate SF6 entirely, accepting higher unit costs to maintain market access.
Utility procurement departments are consolidating vendor panels and demanding 25-year lifecycle cost guarantees that unbundle equipment from service contracts. Traditional equipment distributors face margin compression as direct OEM-service integration captures aftermarket revenue streams. This pattern is most pronounced in German and Austrian transmission system operators, where framework agreements now specify availability-based performance clauses rather than discrete hardware purchases.
High Voltage Circuit Breaker Market Segmentation
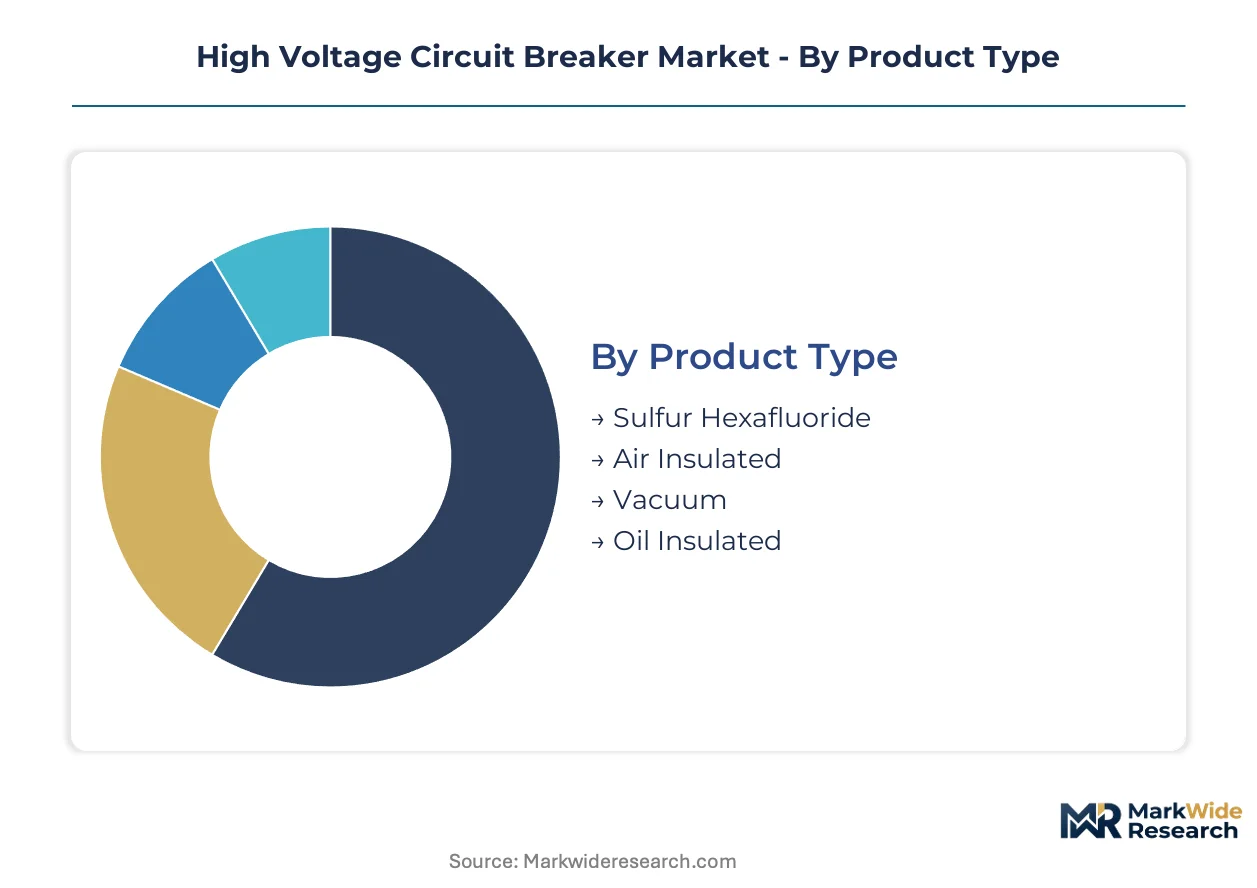
Segmentation reveals divergent replacement cycles across interruption technologies. Arc quenching media and operating mechanisms determine asset lifespans ranging from 15 years for oil-insulated legacy units to 35+ years for modern vacuum interrupters.
Product Type:
Replacement velocity varies dramatically by insulation medium, with environmental regulations compressing turnover for fluorinated gas-dependent architectures.
- Sulfur Hexafluoride:Dominates the 245 kV+ installed base with superior dielectric recovery and thermal capacity. German transmission system operators and Chinese ultra-high voltage corridors specify SF6 for 550 kV interconnection projects despite EU F-Gas Regulation phase-down mandates.
- Vacuum:Axial magnetic field contact designs now achieve 145 kV ratings with 50 kA interruption capability. Japanese metropolitan utilities and German municipal networks prioritize vacuum for urban GIS installations where leakage monitoring costs outweigh footprint premiums.
- Air Insulated:Compressed air puffer mechanisms serve cost-constrained utilities in India and Brazil where capital budgets limit GIS adoption.
- Oil Insulated:Legacy bulk-oil designs persist in North American rural cooperatives with extended maintenance deferrals.
Sulfur hexafluoride dominates installed base. Vacuum is where expansion concentrates.
Technology:
Operating mechanism sophistication determines maintenance intervals and remote operability premiums across transmission automation roadmaps.
- Hybrid:Combines vacuum interrupters with SF6 insulation for 245 kV applications, bridging dielectric performance gaps during technology transition. Scandinavian utilities specify hybrid architectures to meet EU F-Gas reduction timelines without sacrificing voltage ratings.
- Electronically-Controlled:Permanent magnet actuators with digital position sensing enable sub-cycle synchronization for grid stability services. German TSO framework agreements now mandate electronic control interfaces for new 420 kV installations.
- Electro-Hydraulic:High-force density suited for 800 kV+ ultra-high voltage breakers requiring rapid contact separation.
- Mechanical:Spring-operated mechanisms retain lowest first cost for emerging market utilities with limited automation requirements.
Mechanical systems anchor legacy replacement demand. Electronically-controlled architectures are climbing the fastest on smart grid integration requirements.
End User:
Procurement sophistication and lifecycle cost horizons segment buyer behavior across infrastructure investment cycles.
- Utilities:Transmission system operators in China, Germany, and India drive volume through framework agreements specifying 25-year availability guarantees. State Grid Corporation procurement emphasizes 800 kV+ ratings for western-to-eastern power transfer corridors.
- Renewable Energy:Offshore wind and solar zone interconnections require 145 kV GIS with rapid fault clearing. North Sea wind farm developers specify vacuum-insulated designs to satisfy project finance environmental covenants.
- Manufacturing:Heavy industrial facilities prioritize reliability-centered maintenance with predictive diagnostics integration.
- Data Centers:Hyperscale campus substations demand compact 72.5 kV installations with minimal footprint and zero leakage risk.
Utilities dominate installed base. Renewable energy is where expansion concentrates.
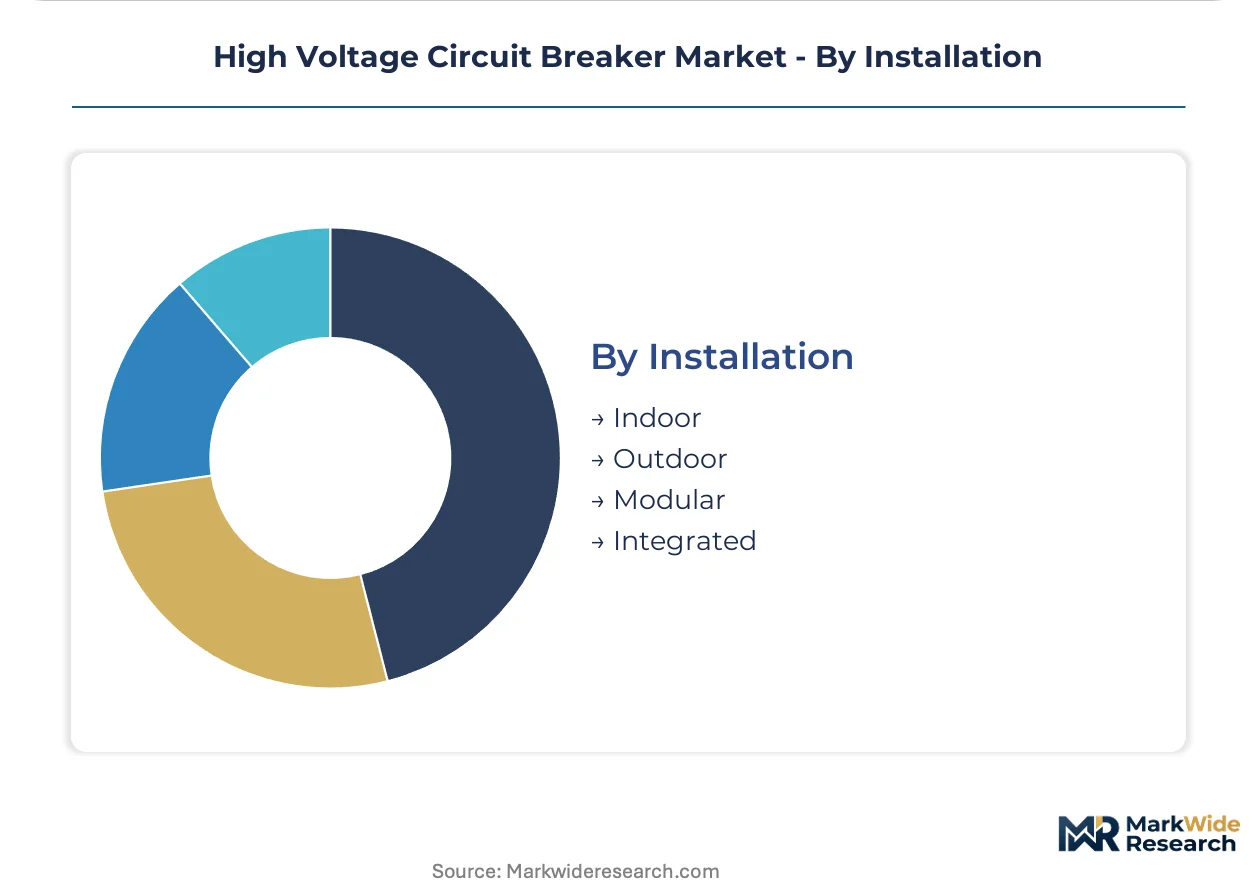
Installation:
Site constraints and modularity requirements determine capital deployment flexibility across greenfield and brownfield projects.
- Outdoor:Air-insulated switchgear occupies substation yards in regions with available land and moderate climate conditions. Indian transmission buildout favors outdoor AIS for Green Energy Corridor rural substations.
- Modular:Factory-assembled GIS skids reduce field installation time for data center and industrial campus projects. Japanese urban utilities specify modular 66 kV units for constrained Tokyo and Osaka substation sites.
- Indoor:Climate-controlled environments extend maintenance intervals in extreme temperature or contamination zones.
- Integrated:Combined breaker-transformer modules streamline EPC contracting for turnkey substation delivery.
Outdoor configurations dominate installed base. Modular designs are gaining share fastest on urban density constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High voltage circuit breaker trade flows reflect divergent manufacturing capabilities and grid investment cycles across major economies. China maintains substantial export surplus in 550 kV+ ultra-high voltage equipment, while Germany and Japan remain net importers of specialized interruption components despite strong domestic assembly presence.
China
State Grid Corporation drives procurement of 800 kV+ circuit breakers for western-to-eastern power transfer corridors under dual carbon goals. MEE oversight on fluorinated gas inventory reporting tightens environmental compliance for SF6-dependent installations. Manufacturing clusters in Xi'an and Shenyang produce vacuum interrupter assemblies for domestic urban substation buildouts.
Germany
Transmission system operators specify 25-year availability guarantees in framework agreements for 420 kV installations. EU F-Gas Regulation mandates 67% SF6 reduction by 2030, accelerating vacuum-first procurement policies. Industrial concentration in Berlin-Brandenburg and Bavaria supports GIS assembly operations serving Scandinavian export markets.
India
Green Energy Corridors and renewable energy zones create demand for 400 kV GIS installations under PLI scheme domestic manufacturing incentives. CEA technical standards govern interruption performance requirements for transmission expansion projects. Manufacturing partnerships concentrate in Gujarat and Maharashtra to serve western regional load centers.
Japan
Metropolitan utilities prioritize vacuum-insulated 66 kV and 110 kV installations in Tokyo and Osaka substations where leakage risk dominates site selection. METI efficiency standards shape procurement specifications for urban density-constrained projects. Regional power companies in Kansai specify modular factory-assembled GIS skids to reduce field installation time.
United States
Aging air-blast installations in rural cooperatives present retrofit opportunities for modular vacuum replacements without complete substation rebuilds. FERC grid reliability standards influence circuit breaker specification for transmission automation roadmaps. Equipment demand concentrates in Texas and California where renewable interconnection drives 145 kV GIS procurement.
High Voltage Circuit Breaker Market Key Industry Players
On the supply side, the industry is consolidating around integrated manufacturers with captive vacuum interrupter production and established type test certification relationships. European and Japanese incumbents anchor premium-tier positioning through in-house GIS assembly capabilities, while Chinese state-affiliated entities capture scale-driven procurement in domestic ultra-high voltage corridors. Three strategic archetypes dominate: full-stack integrators controlling interrupter-to-GIS value chains, component specialists licensing vacuum bottle technology, and regional assemblers serving cost-constrained emerging markets. Competitive intensity centers on M&A activity targeting vacuum interrupter engineering talent and strategic partnerships securing rare earth magnet supply for permanent magnet actuator systems.
Among the full-stack integrators, ABB leverages its vacuum interrupter heritage to capture early-phase utility tenders in European markets transitioning from SF6-dependent architectures. Siemens Energy anchors large-scale project execution through captive GIS assembly operations serving German transmission system operator framework agreements. Mitsubishi Electric occupies a position within the ultra-high voltage specialization tier, drawing on technical expertise for 800 kV+ applications across Asian interconnection projects. These three entities exemplify divergent strategic postures: technology transition leadership, integrated project delivery scale, and voltage ceiling engineering depth.
| Leading Market Players |
|---|
| ABB |
| GE Vernova |
| Hitachi Energy |
| Schneider Electric |
| Siemens Energy |
| Mitsubishi Electric |
| CG Power & Industrial Solutions |
| Pfiffner Group |
| Toshiba International |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam maritime corridor carries vacuum interrupter assemblies and GIS subcomponents from Chinese manufacturing clusters to European assembly plants, with freight cost volatility amplifying price spreads between SF6-dependent legacy systems and next-generation vacuum architectures. This logistics dynamic concentrates pricing power with full-stack integrators controlling captive interrupter production, while tier-2 assemblers absorb margin compression from rare earth magnet cost fluctuations.
Pricing Analysis
The technology-generation pricing gap separates mature SF6 puffer designs from axial magnetic field vacuum interrupters and emerging hybrid architectures bridging dielectric performance thresholds. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—IEC 62271-100 full short-circuit tested units command substantial premiums over type-test-pending alternatives. Cost compression in economy-tier mechanical spring mechanisms is intensifying because Indian and Brazilian utilities prioritize first-cost minimization over lifecycle value. Renewable energy developers exhibit lowest price sensitivity, accepting vacuum insulation premiums to satisfy project finance environmental covenants.
Supply Chain Analysis
Upstream feedstock concentration in Chinese neodymium processing facilities and Japanese specialty steel production for vacuum bottle enclosures creates asymmetric dependency patterns across the value chain. Manufacturing draws from South Korean permanent magnet actuator specialists, German GIS assembly operations, and Chinese ultra-high voltage breaker fabrication. Single-source vulnerability in rare earth magnet supply exposes BOM costs to export quota fluctuations. Distribution runs through direct OEM-service integration capturing aftermarket revenue, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and availability-based performance guarantees now expand faster than hardware margins, transforming circuit breaker procurement from capital expenditure to service-attach relationships. This shift rewards vendors integrating IIoT sensor networks with lifecycle cost accountability.
For Market Incumbents: Build captive vacuum interrupter manufacturing moats to exclude SF6-dependent competitors from EU F-Gas Regulation-compliant tenders. Secure type test certification queue priority at IEC-accredited laboratories to freeze engineering resources at rival firms. Deepen backward integration into rare earth magnet supply through long-term offtake agreements with Chinese processors, insulating against export quota volatility that threatens permanent magnet actuator costs. For New Entrants and Emerging Players: Build out modular vacuum retrofit services targeting North American rural cooperatives with aging air-blast installations, bypassing complete substation rebuilds. Concentrate on 72.5–145 kV urban substation segments where German and Japanese utilities specify vacuum-first procurement policies. Partner with established GIS assemblers for private-label manufacturing rather than competing on full short-circuit certification timelines. For Investors and Strategic Acquirers: Component specialists with vacuum bottle sealing patents and established utility relationships represent the most defensible acquisition targets in a consolidating supplier landscape. Long-term viability hinges on exposure to transmission automation roadmaps rather than commodity replacement cycles. Watch for framework agreement wins by German transmission system operators specifying 25-year availability guarantees—these signal tipping points in service-attach revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Vacuum Interrupter Production | Controls critical component supply for EU F-Gas Regulation compliance, excluding competitors from premium tenders. |
| Type Test Certification Investment | Secures laboratory queue priority at IEC-accredited facilities, accelerating product launch timelines. |
| Predictive Maintenance Platform Development | Captures recurring revenue streams beyond hardware margins through IIoT-enabled lifecycle contracts. |
| Rare Earth Magnet Supply Partnership | Mitigates BOM cost exposure to Chinese export quota fluctuations in permanent magnet actuators. |
| Modular Retrofit Service Launch | Addresses North American air-blast installed base without requiring complete substation capital expenditure. |
Research Approach
A spread of perspectives from transmission system operator procurement directors, vacuum interrupter engineering specialists, GIS assembly plant managers, and aftermarket service contract managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through IEC standard documentation, EU F-Gas Regulation compliance filings, and customs trade data tracking vacuum interrupter assembly flows. Bottom-up triangulation across utility framework agreement terms and top-down reconciliation with transmission capital expenditure disclosures anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning arc quenching media, operating mechanism sophistication, end-user procurement sophistication, and installation site constraints. CAGRs emerged from regression analysis against transmission expansion project pipelines and replacement cycle velocity by insulation technology. Forecast inputs incorporated MEE fluorinated gas inventory reporting trends and PLI scheme domestic manufacturing incentive uptake in India.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-affiliated entities capturing ultra-high voltage corridor procurement would shift outcomes materially. Regulatory acceleration of SF6 phase-down timelines or breakthroughs in vacuum dielectric recovery above 245 kV would force updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Middle East and Africa Electric Drives Market