
 Nanoparticle Technology Market | 2026-2036
Nanoparticle Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoparticle Technology Market Foresight
Buyer concentration among pharmaceutical contract manufacturers is pivoting toward a smaller pool of large-scale biologics producers with dedicated nanformulation capabilities. Nanophase Technologies Corporation leverages its arc-discharge metal nanoparticle platform to serve industrial catalyst clients with precise size distributions. American Elements sustains one of the broadest catalogues of engineered nanopowders, competing across electronics and energy storage supply chains. SkySpring Nanomaterials anchors its position through ISO-certified production of gold and silver nanoparticles for diagnostic and therapeutic applications.
Nanoparticle technology encompasses materials with at least one dimension between 1 and 100 nanometers, typically synthesized through bottom-up approaches such as solvothermal precipitation or top-down methods like laser ablation, enabling tunable optical, electronic, and catalytic properties for targeted industrial deployment. Metallic nanoparticles occupy the most mature revenue pool, with established silver and gold formulations dominating antimicrobial and imaging segments, while quantum dots capture expanding margins in display backlighting and biomedical tracking due to narrow emission tunability. Nanoparticle carriers represent the fastest-growing structural category, driven by lipid and polymer systems that encapsulate nucleic acids and small-molecule drugs for targeted cellular delivery.
The FDA maintains active guidance on nanotechnology-enabled health products, requiring extensive physicochemical characterization that elevates barriers for new entrants in therapeutic applications. REACH registration mandates in Europe impose substance-by-substance evaluation costs on metallic and carbon-based nanoparticles, reshaping supplier economics for exporters serving EU electronics and coatings manufacturers. ISO/TS 19337 provides measurement protocols for nanoparticle size and surface area, creating baseline quality expectations that procurement teams now embed in supplier qualification. Stakeholders must monitor how emerging EPA rules on nanoscale materials reporting under the Toxic Substances Control Act will alter domestic manufacturing compliance burdens and outsourcing decisions.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating nanformulation capabilities around lipid nanoparticle platforms for mRNA therapeutics, compressing supplier diversity while elevating technical barriers for specialized production.
Growth Catalysts
- Lipid Nanoparticle Carriers:Encapsulation systems for nucleic acid delivery are expanding across oncology and infectious disease pipelines, with pharmaceutical manufacturers prioritizing scalable manufacturing partnerships.
- National Nanotechnology Initiative:Sustained federal funding in the United States underwrites translational research and commercialization infrastructure for clinical-grade nanoparticle production.
- Quantum Dot Display Backlighting:Narrow emission tunability in cadmium-free formulations is displacing conventional phosphor technologies in premium consumer electronics panels.
Market Restraints
- Precious Metal Input Volatility:Gold and silver nanoparticle production faces margin compression from spot price fluctuations and refined feedstock scarcity.
- REACH Registration Burden:Substance-by-substance evaluation costs for metallic and carbon-based nanoparticles reshape supplier economics for European electronics and coatings exporters.
- Physicochemical Characterization Complexity:FDA guidance on nanotechnology-enabled health products mandates extensive analytical validation that extends development timelines.
Strategic Opportunities
- Inhaled Nanoparticle Therapeutics:Pulmonary delivery formulations for respiratory diseases represent an underdeveloped vector with limited approved products and substantial unmet clinical need.
- Dual Carbon Goals in China:National emissions mandates accelerate demand for platinum group metal nanoparticles in hydrogen fuel cell catalysts and automotive catalytic converters.
- ISO/TS 19337 Certification:Standardized measurement protocols for size and surface area create procurement qualification tools that favor accredited suppliers.
Industry Challenges
- Scale-Up Engineering Talent:Translating bench-scale solvothermal synthesis to continuous manufacturing requires process engineers with rare cross-training in colloid chemistry and chemical engineering.
- Multi-Jurisdictional Compliance:Divergent EPA nanoscale reporting rules, ECHA registration mandates, and FDA characterization requirements force parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoparticle Technology Market |
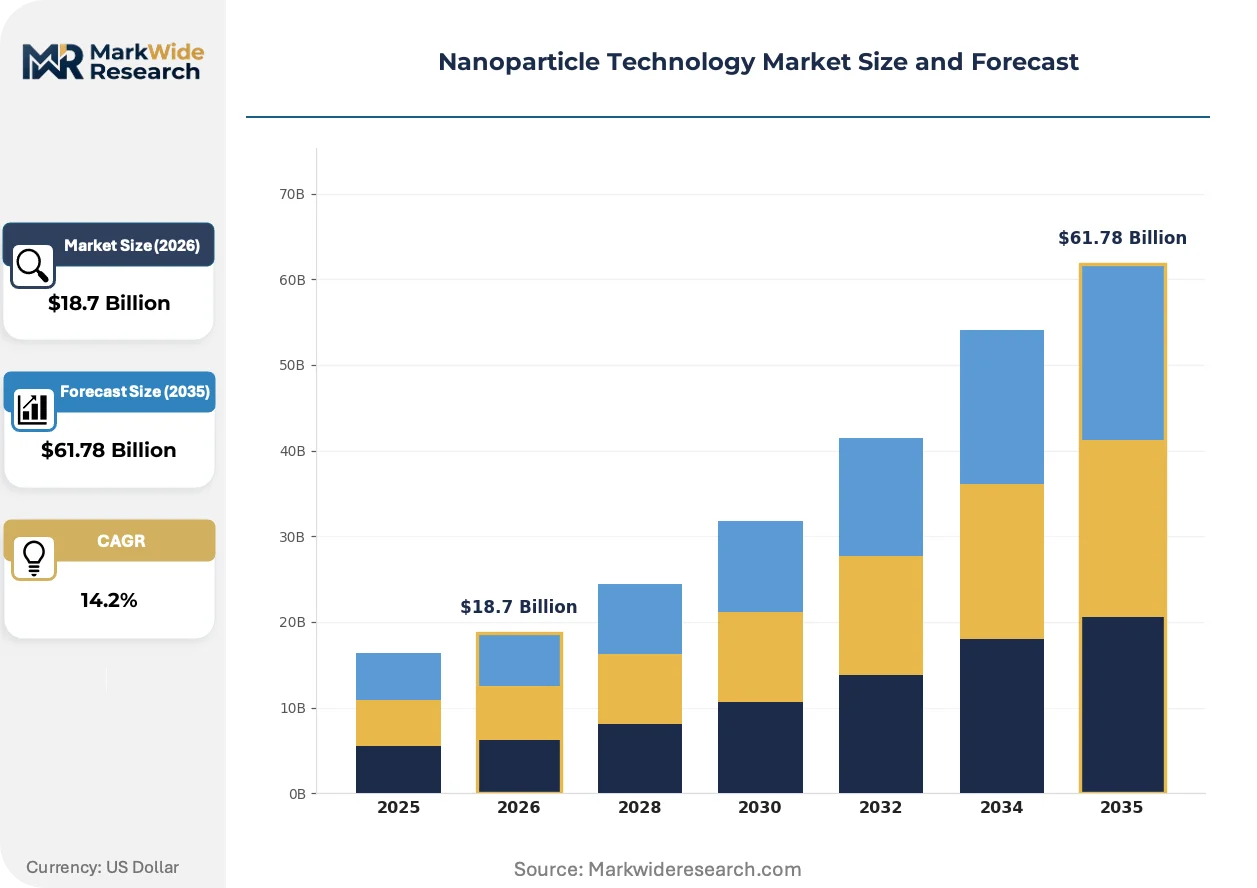
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Dots, Metallic Nanoparticles, Nanoparticle Carriers, Silica Nanoparticles End User: Healthcare, Electronics, Agriculture, Environmental Application: Drug Delivery, Imaging, Sensors, Catalysis Technology: Solvothermal, Laser Ablation, Chemical Vapor Deposition, Biogenic Synthesis |
| Companies Covered | Nanophase Technologies Corporation, American Elements, nanoComposix, Bruker Corporation, Thermo Fisher Scientific, Nanosys, Altair Nanotechnologies, Unidym, SkySpring Nanomaterials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoparticle Technology Market Shifts & Advancements
Continuous flow manufacturing and AI-assisted particle design are compressing development cycles while regulatory harmonization efforts struggle to keep pace with platform diversification.
Microfluidic synthesis platforms are decentralizing nanoparticle production from centralized batch facilities to distributed point-of-use manufacturing. Biopharmaceutical quality groups are validating these systems for GMP lipid nanoparticle formulation. This architecture reduces cold-chain logistics burdens and enables personalized medicine dosing.
REACH registration mandates in Europe impose substance-by-substance evaluation costs on metallic and carbon-based nanoparticles. Electronics and coatings manufacturers are reformulating with pre-registered materials or shifting procurement to domestic European suppliers. German automotive OEMs now require REACH-compliant nanoparticle documentation in tier-one supplier contracts.
Pharmaceutical procurement teams are consolidating supplier relationships around integrated CDMO partners offering end-to-end nanformulation through fill-finish capabilities. Smaller specialty chemical houses without dedicated biologics infrastructure are losing preferred vendor status. This concentration is most visible in United States mRNA vaccine supply chains.
Nanoparticle Technology Market Segmentation
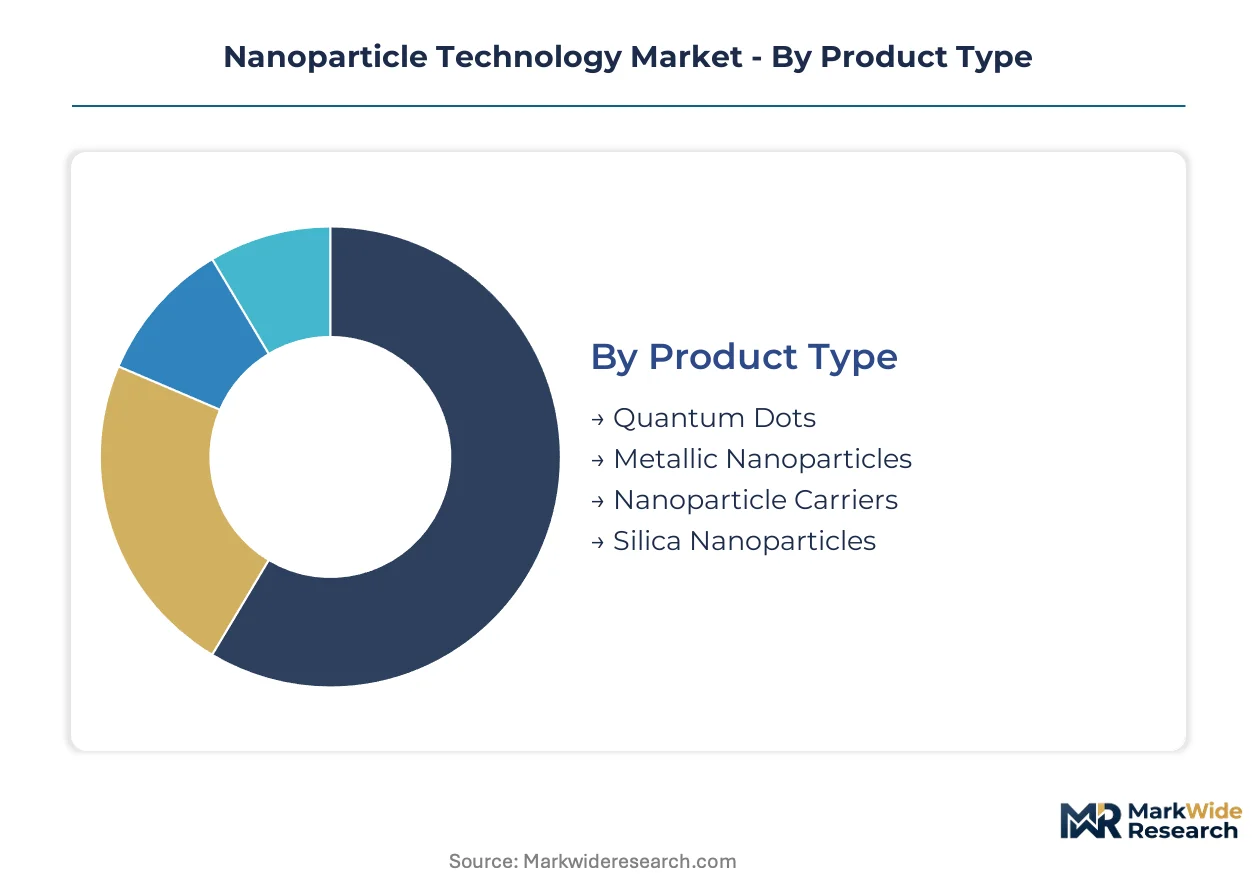
Nanoparticle technology markets fragment across four distinct classification axes, each carrying divergent regulatory burdens and manufacturing scale requirements. Product type segmentation determines whether FDA biologics guidance, REACH substance registration, or ISO measurement protocols apply. End user and application categories further stratify procurement priorities between pharmaceutical quality groups and industrial materials buyers.
Product Type:
FDA's evolving nanotechnology guidance framework imposes tiered characterization requirements, with lipid-based carriers facing the most extensive physicochemical validation while metallic formulations navigate REACH substance-by-substance evaluation.
- Nanoparticle Carriers:Lipid and polymer encapsulation systems engineered for nucleic acid and small-molecule delivery. Pharmaceutical contract manufacturers in the United States concentrate procurement around scalable CDMO partners with dedicated nanformulation suites, driven by mRNA therapeutic pipeline expansion.
- Metallic Nanoparticles:Silver and gold formulations with established antimicrobial and imaging applications. Electronics and coatings manufacturers serving European markets face margin pressure from REACH registration mandates, reshaping supplier selection toward pre-registered feedstock sources.
- Quantum Dots:Semiconductor nanocrystals with narrow emission tunability displacing conventional phosphor technologies.
- Silica Nanoparticles:Mesoporous and solid formulations for catalytic and diagnostic applications.
Leading the category by volume: Metallic Nanoparticles. Growing fastest: Nanoparticle Carriers.
End User:
Customer procurement patterns split between validated pharmaceutical supply chains requiring GMP documentation and industrial buyers prioritizing feedstock cost stability.
- Healthcare:Biopharmaceutical manufacturers dominate commercial value, with quality groups validating microfluidic synthesis platforms for clinical-grade lipid nanoparticle production. Federal funding through the National Nanotechnology Initiative sustains translational infrastructure in the United States.
- Electronics:Display backlighting and sensor manufacturers drive quantum dot volume, with procurement teams screening suppliers for cadmium-free formulation compliance.
- Agriculture:Crop protection and nutrient delivery applications utilizing antimicrobial metallic formulations.
- Environmental:Remediation and monitoring deployments requiring surface-functionalized silica and metal oxide systems.
Dominating revenue contribution: Healthcare. Expanding most quickly: Electronics.
Application:
Functional use cases determine whether development timelines stretch across multi-year FDA approval pathways or compress within industrial R&D cycles.
- Drug Delivery:Pulmonary and intravenous formulations for oncology and infectious disease indications. Inhaled nanoparticle therapeutics represent an underdeveloped vector with limited approved products and substantial unmet clinical need in respiratory disease.
- Imaging:Contrast agents and fluorescent trackers leveraging gold nanoparticle surface plasmon resonance and quantum dot emission properties.
- Sensors:Point-of-care diagnostic platforms and environmental monitoring devices.
- Catalysis:Industrial process intensification and automotive emissions control utilizing platinum group metal nanoparticles.
Commanding development investment: Drug Delivery. Gaining share fastest: Catalysis.
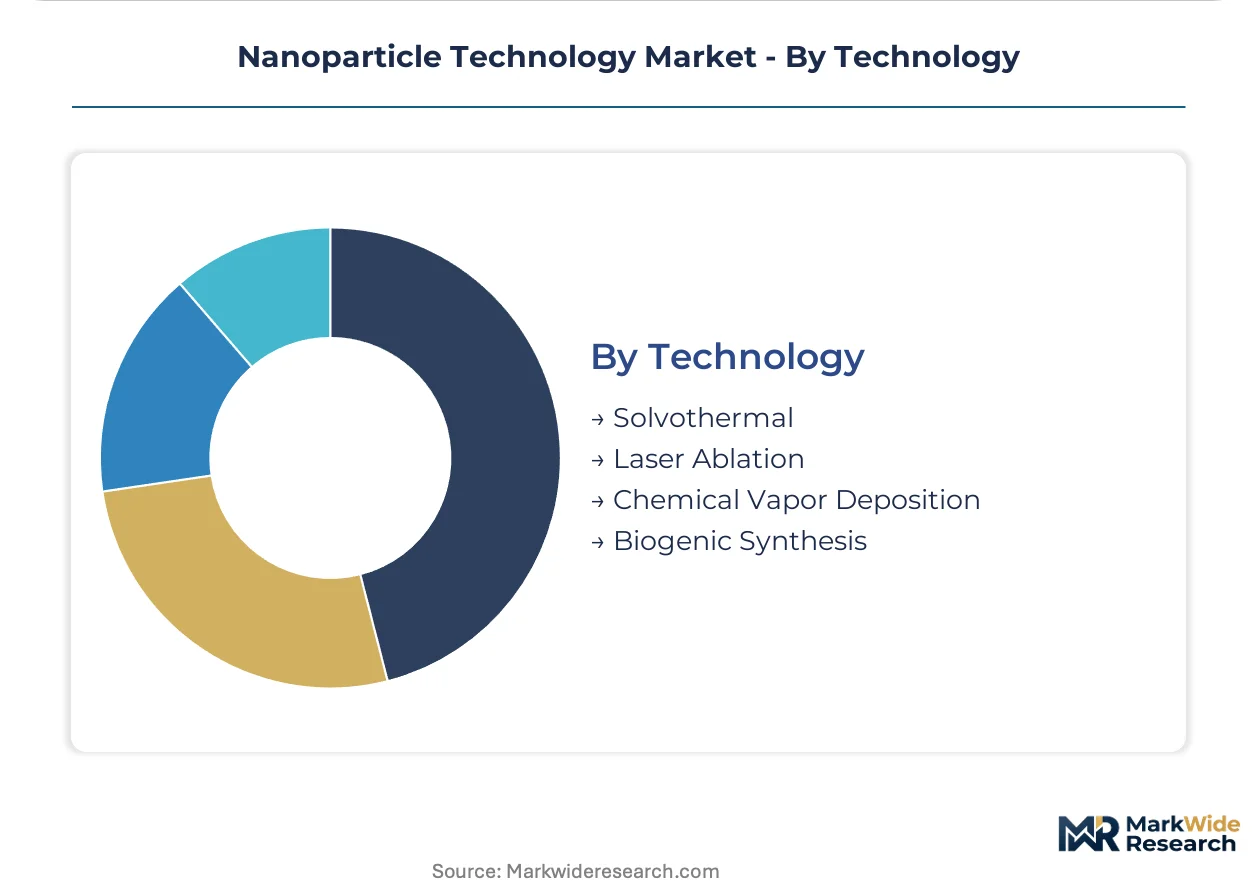
Technology:
Synthesis method selection constrains scale-up pathways and talent requirements, with continuous flow platforms displacing batch processing in pharmaceutical applications.
- Solvothermal:Bottom-up precipitation in high-temperature solvents enabling precise size distribution control. Translating bench-scale protocols to continuous manufacturing demands process engineers with cross-training in colloid chemistry and chemical engineering, creating acute talent scarcity.
- Laser Ablation:Top-down metal vaporization producing ligand-free nanoparticles with minimal contamination.
- Chemical Vapor Deposition:Gas-phase synthesis for thin-film and quantum dot fabrication.
- Biogenic Synthesis:Microbial and plant-mediated reduction methods for sustainable production.
Maintaining commercial dominance: Solvothermal. Steepest expansion trajectory: Biogenic Synthesis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers concentrate procurement around scalable nanformulation partners in the United States, while REACH registration mandates reshape supplier economics for European electronics and coatings exporters.
United States
The National Nanotechnology Initiative sustains translational infrastructure for clinical-grade nanoparticle production across oncology and infectious disease pipelines. FDA's evolving nanotechnology guidance framework imposes tiered physicochemical characterization requirements that elevate barriers for therapeutic applications. Greater Boston and San Francisco Bay Area clusters host biopharmaceutical quality groups validating microfluidic synthesis platforms for GMP lipid nanoparticle formulation.
Germany
Automotive OEMs require REACH-compliant nanoparticle documentation in tier-one supplier contracts for catalytic converter and sensor applications. ECHA substance-by-substance evaluation costs for metallic and carbon-based nanoparticles drive procurement shifts toward pre-registered feedstock sources. The Rhine-Ruhr industrial corridor concentrates platinum group metal nanoparticle demand for hydrogen fuel cell catalysts aligned with national emissions mandates.
China
Dual carbon goals accelerate demand for platinum group metal nanoparticles in hydrogen fuel cell catalysts and automotive catalytic converters. MIIT and MEE oversight of nanoscale materials production tightens environmental compliance for solvothermal synthesis facilities. The Yangtze River Delta anchors display backlighting manufacturing, with procurement teams screening quantum dot suppliers for cadmium-free formulation compliance.
Japan
METI funding priorities support quantum dot development for premium consumer electronics panels displacing conventional phosphor technologies. PMDA guidance on nanotechnology-enabled health products parallels FDA characterization requirements for pharmaceutical applications. The Kansai region around Osaka maintains precision chemical processing infrastructure for narrow emission tunability in semiconductor nanocrystal fabrication.
United Kingdom
Research councils underwrite biogenic synthesis methods for sustainable nanoparticle production targeting environmental remediation applications. MHRA alignment with EMA nanomedicine guidance streamlines regulatory pathways for lipid nanoparticle therapeutics. The Cambridge-London corridor concentrates diagnostic platform development leveraging gold nanoparticle surface plasmon resonance for point-of-care sensing.
Nanoparticle Technology Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized therapeutic and sustainable synthesis applications. The vendor base stratifies across integrated chemical conglomerates with broad engineered materials portfolios, dedicated nanomaterial specialists with ISO-certified production infrastructure, and contract development partners offering end-to-end nanformulation through fill-finish capabilities. Competitive positioning depends on accreditation depth, regulatory documentation quality, and continuous manufacturing scale rather than feedstock cost alone. Dominant moves include strategic partnerships between pharmaceutical manufacturers and scalable CDMO partners, plus portfolio diversification into lipid nanoparticle platforms for nucleic acid delivery.
Within the specialty chemical tier, Nanophase Technologies Corporation, American Elements, and SkySpring Nanomaterials exemplify differentiated positioning through metal nanoparticle platforms, broad catalog breadth, and ISO-certified precious metal production respectively. These entities represent archetypes of process technology specialization, supply chain breadth, and quality-system rigor that procurement teams evaluate against physicochemical characterization standards. Their geographic distribution across North American industrial clusters reflects concentration of federal funding and pharmaceutical manufacturing infrastructure.
| Leading Market Players |
|---|
| Nanophase Technologies Corporation |
| American Elements |
| nanoComposix |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Nanosys |
| Altair Nanotechnologies |
| Unidym |
| SkySpring Nanomaterials |
| Others |
Supply & Pricing Matrix
Silver spot price volatility cascades through metallic nanoparticle production, compressing margins for antimicrobial formulations while pharmaceutical-grade lipid nanoparticle carriers command premium spreads tied to FDA characterization compliance tiers.
Pricing Analysis
Volume concentrates in metallic silver and gold formulations where commodity feedstock costs dominate, while margins accrue to lipid nanoparticle carriers with GMP certification and ISO/TS 19337 documentation. Price differentiation separates REACH-registered European suppliers from unregistered competitors facing market exclusion. Pricing pressure stems from precious metal input scarcity and ECHA substance evaluation fees. Industrial coatings buyers exhibit highest price sensitivity; biopharmaceutical procurement teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's dual carbon framework and Germany's automotive tier-one contracting reshape platinum group metal nanoparticle sourcing toward local refiners. Production concentrates in the United States, China, and Germany, with each hub serving distinct regulatory jurisdictions. Feedstock dependencies span refined precious metals, phospholipid excipients, and semiconductor-grade precursors. Single-source vulnerability runs through specialized solvothermal synthesis equipment. Distribution runs through integrated CDMO partnerships for pharmaceutical applications and direct technical sales for industrial catalyst clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with control over continuous flow manufacturing platforms and GMP-certified production suites determining pricing power and customer lock-in.
For Market Incumbents: Cement market position through captive production of lipid excipients and backward integration into phospholipid supply. Acquire ISO/TS 19337 certification depth to disqualify smaller competitors from pharmaceutical procurement shortlists. Threats include microfluidic synthesis platform entrants and REACH registration cost barriers reshaping European metallic nanoparticle economics.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in quantum dot display materials creates entry space for cadmium-free formulation specialists. Target pulmonary delivery formulations for respiratory therapeutics, an underdeveloped vector with limited approved products. Pursue biogenic synthesis methods for sustainable production credentials that differentiate against conventional solvothermal incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale CDMOs with underutilized GMP nanformulation capacity in the United States. Long-term viability hinges on regulatory documentation depth and continuous manufacturing scale rather than feedstock access alone. Watch for EPA nanoscale reporting rule finalization as inflection signal for domestic manufacturing compliance burdens and outsourcing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lipid Excipients | Captive phospholipid supply secures margin control against raw material volatility. |
| ISO/TS 19337 Certification Investment | Standardized measurement protocols unlock pharmaceutical procurement qualification. |
| Microfluidic Platform Deployment | Continuous flow manufacturing reduces cold-chain logistics for personalized medicine. |
| REACH Pre-Registration Portfolio | Substance-by-substance compliance maintains European electronics market access. |
| Biogenic Synthesis Scale-Up | Microbial reduction methods address sustainability mandates in environmental applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pharmaceutical quality directors, CDMO procurement leads, plant managers at solvothermal synthesis facilities, and regulatory affairs specialists at FDA and EMA. Secondary sources encompassed EPA nanoscale reporting dockets, ECHA registration databases, National Nanotechnology Initiative funding disclosures, and ISO technical specification documents. Bottom-up volume modeling triangulated against top-down expenditure analysis across healthcare, electronics, and catalysis end uses.
Data-stream reconciliation merged production capacity surveys with end-user procurement pipeline visibility across the projection horizon. Segmentation dimensions spanned product type, synthesis technology, application function, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating pipeline-stage therapeutic candidates, display panel procurement forecasts, and automotive emissions control mandates. Industry-specific inputs included mRNA therapeutic manufacturing partnerships, quantum dot backlighting adoption rates, and hydrogen fuel cell catalyst demand tied to national emissions frameworks.
Inputs from EPA rulemaking dockets and ECHA registration databases were available through the study window; gaps in proprietary CDMO capacity utilization rates introduce uncertainty bands around near-term supply projections. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology transfer velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market