
 Programmable Semiconductor Technologies Market | 2026-2036
Programmable Semiconductor Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Semiconductor Technologies Market Analytics
Automotive electrification is restructuring demand patterns across programmable semiconductor buyers. Lattice Semiconductor leverages low-power FPGA architectures to anchor infotainment and ADAS socket wins. Intel Corporation sustains manufacturing scale through captive foundry investments and process node leadership. AMD competes aggressively in data center adaptive computing with high-performance programmable logic portfolios.
Programmable semiconductor technologies comprise integrated circuits whose logic functions can be configured or reconfigured after manufacturing, typically through SRAM-based lookup tables, flash cells, or antifuse elements enabling field customization. These devices serve industrial and commercial purposes where hardware flexibility, parallel processing, and rapid prototyping outperform fixed-function alternatives. FPGAs command the largest revenue pool among product types due to reprogrammability premiums in prototyping and low-volume production. Embedded systems technology captures expanding share as system-on-chip integration merges programmable logic with Arm cores and AI accelerators. Industrial automation applications generate above-average margins where long product lifecycles and ruggedization requirements justify premium pricing.
The US CHIPS and Science Act directs NIST and Department of Commerce to administer fab construction subsidies tied to national security guardrails. The EU Chips Act coordinates ESA and national regulators to reduce external dependency through designated first-of-a-kind facility status. REACH and RoHS frameworks from ECHA constrain material selections and packaging chemistries across European-bound shipments. Stakeholders must monitor how bilateral export control expansions alter foundry access and design tool licensing before committing to multi-year capacity agreements.
Market Dynamics
Automotive electrification is forcing a fundamental reconfiguration of programmable semiconductor procurement, as OEMs and tier-1 suppliers abandon discrete component sourcing in favor of system-level adaptive computing platforms that integrate FPGA, embedded AI acceleration, and software-defined vehicle architectures.
Growth Catalysts
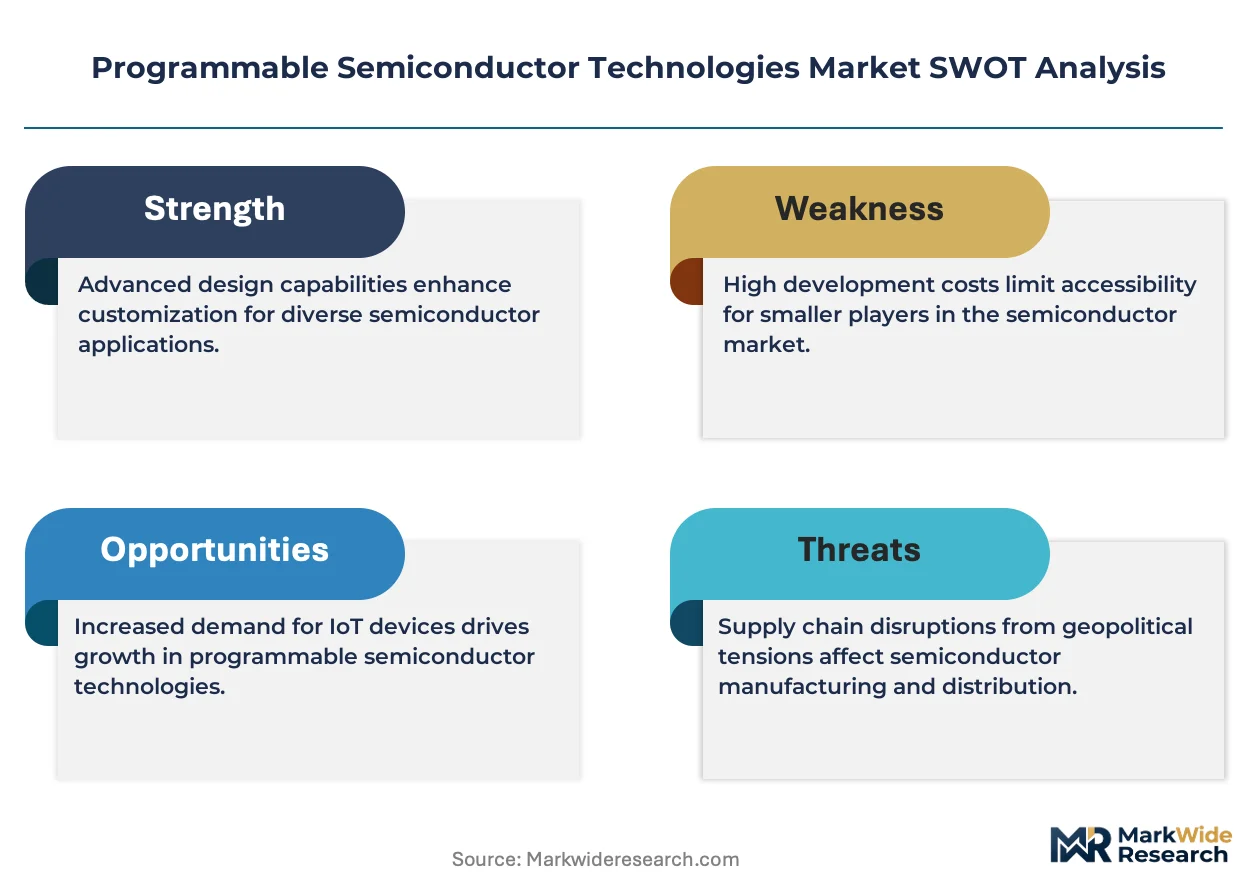
- EU Chips Act subsidies:Designated first-of-a-kind facility status accelerates fab construction across Germany, France, and Italy, reducing external dependency for European automotive and industrial buyers.
- ADAS sensor fusion:Camera, radar, and LiDAR integration demands real-time programmable logic for data preprocessing, driving socket penetration in Level 2+ autonomous platforms.
- Silicon carbide power modules:Wide-bandgap semiconductor adoption in electric vehicle inverters creates companion demand for gate-drive control FPGAs with deterministic latency.
Market Restraints
- EUV lithography concentration:Advanced node capacity bottlenecks at ASML-dependent foundries in Taiwan and South Korea limit supply elasticity for high-density programmable logic.
- Neon and palladium exposure:Ukrainian and Russian supply chain disruptions for noble gases and catalytic materials introduce input cost volatility for fab operations.
- Fixed-function ASIC substitution:Mature-node application-specific integrated circuits erode FPGA sockets in high-volume consumer electronics where programmability premiums cannot be recovered.
Strategic Opportunities
- Edge AI inference:Convergence of programmable logic with Arm Ethos neural processing units opens unmanned aerial vehicle and agricultural robotics applications previously served by GPU accelerators.
- India PLI scheme:Production-linked incentives for semiconductor packaging and testing attract design houses seeking tariff-advantaged access to domestic electronics manufacturing.
- Software-defined radio:5G Open RAN disaggregation mandates from Japanese and South Korean carriers create greenfield demand for reconfigurable RF signal chains.
Industry Challenges
- Physical design expertise gap:Advanced packaging methodologies for chiplet-based programmable SoCs outpace university curriculum refresh cycles, constraining hiring pipelines.
- Multi-die integration complexity:Heterogeneous integration of logic dies, HBM stacks, and silicon photonics requires new thermal and electrical simulation workflows that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Semiconductor Technologies Market |
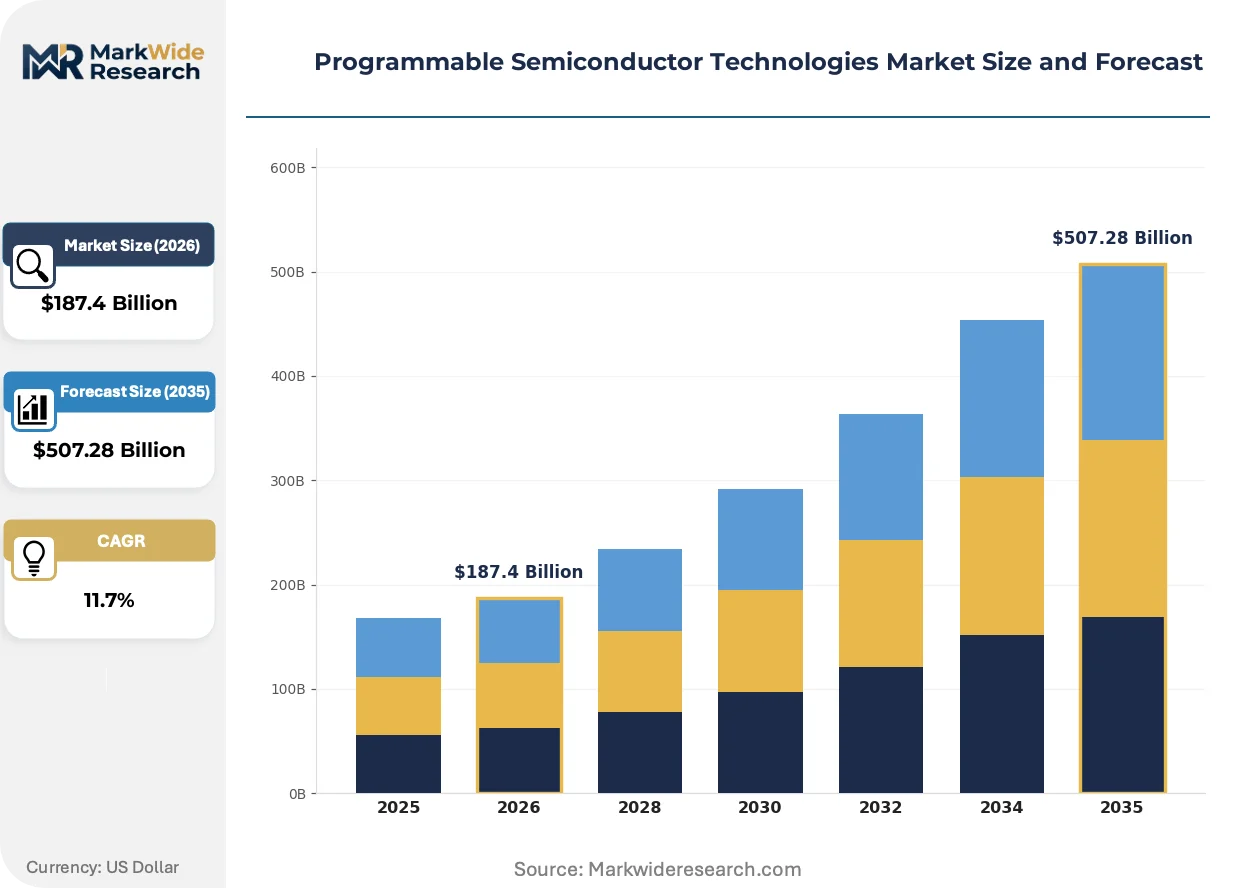
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGAs, ASICs, Microcontrollers, DSPs Technology: Configurable Logic, Flash Memory, Embedded Systems, Analog Application: Telecommunications, Automotive, Consumer Electronics, Industrial Automation End User: OEMs, Tier-1 Suppliers, System Integrators, Aftermarket Providers |
| Companies Covered | Advanced Micro Devices (AMD), Intel Corporation, Lattice Semiconductor, Microchip Technology, Achronix Semiconductor Corporation, QuickLogic Corporation, Efinix, Gowin Semiconductor, Flex Logix Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Semiconductor Technologies Market Evolving Landscape
Heterogeneous integration is compressing the traditional boundaries between discrete programmable logic, memory, and specialized accelerators, forcing vendors to rearchitect product portfolios around system-in-package delivery models rather than standalone device sales.
Chiplet-based FPGA architectures are consolidating high-bandwidth memory and AI engines onto interposer substrates, enabling data center customers to customize compute-memory ratios without full reticle redesigns. Cloud service providers in the United States and China are adopting these disaggregated platforms for training workload optimization. The structural consequence is that programmable logic vendors must now compete on packaging ecosystem partnerships rather than silicon node leadership alone.
REACH substance restrictions from ECHA are constraining halogenated flame retardants and certain phthalates in semiconductor packaging materials bound for European automotive and industrial markets. Manufacturers are qualifying alternative molding compounds and substrate laminates that maintain thermal cycling reliability under extended temperature ranges. European tier-1 suppliers are accelerating supplier audits to ensure material declaration compliance ahead of phased restriction deadlines.
Automotive OEMs are consolidating semiconductor procurement under centralized software and hardware platform teams, displacing the traditional tier-1 mediated component sourcing model. Direct engagements between Volkswagen, Toyota, and programmable semiconductor vendors are compressing specification cycles and forcing real-time roadmap alignment. This pattern is most visible in Germany and Japan, where legacy keiretsu and Zulieferer relationships are yielding to platform-centric supplier governance structures.
Programmable Semiconductor Technologies Market Segmentation
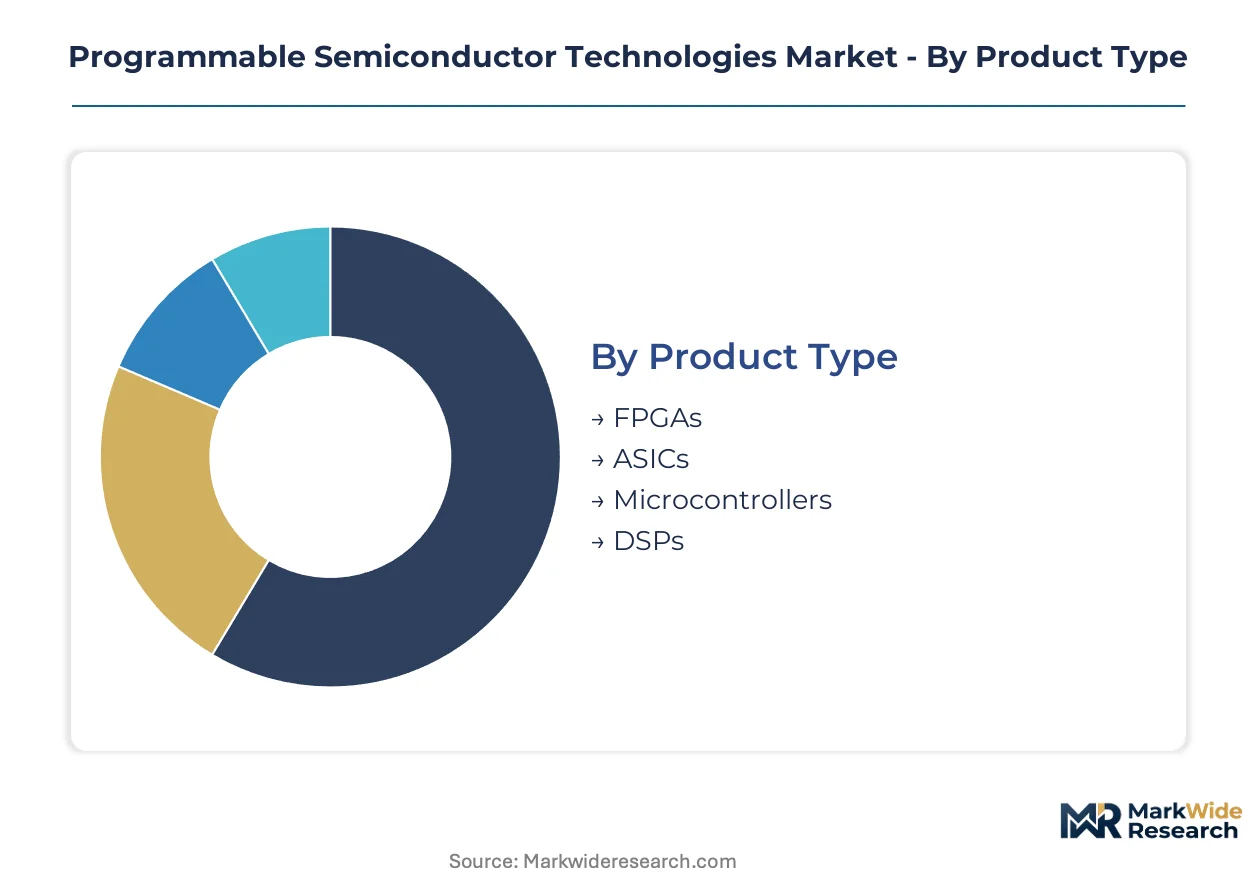
Programmable semiconductor procurement cycles vary dramatically across product architectures, with SRAM-based FPGAs demanding 3-5 year refresh intervals while flash-configured devices extend to 7-10 year lifecycles. Understanding these replacement rhythms helps suppliers align roadmap investments with customer capital expenditure windows.
Product Type:
Upgrade urgency differs sharply across programmable logic families, with reprogrammable architectures commanding premium replacement cycles compared to fixed-function alternatives.
- FPGAs:Field-programmable gate arrays deploy SRAM lookup tables or flash cells to enable post-manufacturing logic reconfiguration. Automotive electrification in Germany and Japan is concentrating demand for infotainment and ADAS preprocessing sockets where deterministic latency requirements justify reprogrammability premiums.
- ASICs:Application-specific integrated circuits sacrifice field flexibility for die-area efficiency and unit cost optimization at volume. Data center operators in the United States are driving placement concentration for AI training accelerators where mask costs amortize across million-unit deployments.
- Microcontrollers:Embedded processing cores with on-chip flash and mixed-signal peripherals serve deterministic control applications.
- DSPs:Digital signal processors optimize multiply-accumulate throughput for real-time algorithmic workloads.
Volume placements concentrate in ASICs; the faster expansion belongs to FPGAs.
Technology:
Cost tier stratification separates premium interposer-based solutions from standard monolithic dies and economy-grade discrete alternatives.
- Configurable Logic:Lookup table fabrics and routing matrices enable hardware-level algorithm adaptation without silicon respin. Taiwan-based foundries anchor supply concentration for advanced node programmable fabrics where EUV lithography access determines competitive positioning.
- Flash Memory:Non-volatile configuration storage eliminates external boot devices and enables instant-on operation. Industrial automation deployments across France and Italy favor flash-based FPGAs for safety-critical machinery control where power interruption tolerance is mandatory.
- Embedded Systems:Heterogeneous integration of programmable logic with Arm cores and AI accelerators.
- Analog:Mixed-signal programmable devices combining data converters and RF front-ends.
Cost premiums widen most dramatically for Configurable Logic; Embedded Systems are climbing the fastest as system-on-chip consolidation accelerates.
Application:
Customer type heterogeneity separates long-lifecycle industrial buyers from consumer electronics vendors with compressed qualification timelines.
- Telecommunications:Baseband processing and fronthaul aggregation demand programmable logic for protocol flexibility across generational transitions. South Korean carriers are driving socket concentration for 5G Open RAN disaggregation where reconfigurable RF chains enable multi-vendor interoperability.
- Automotive:Functional safety requirements and extended temperature ranges constrain supplier qualification. OEMs in Germany and Japan are consolidating procurement under platform teams for software-defined vehicle architectures.
- Consumer Electronics:High-volume, cost-sensitive deployments with shortened product lifecycles.
- Industrial Automation:Ruggedized programmable controllers for factory floor and process control environments.
Procurement scale concentrates in Consumer Electronics; Automotive applications are expanding most quickly as electrification multiplies semiconductor content per vehicle.
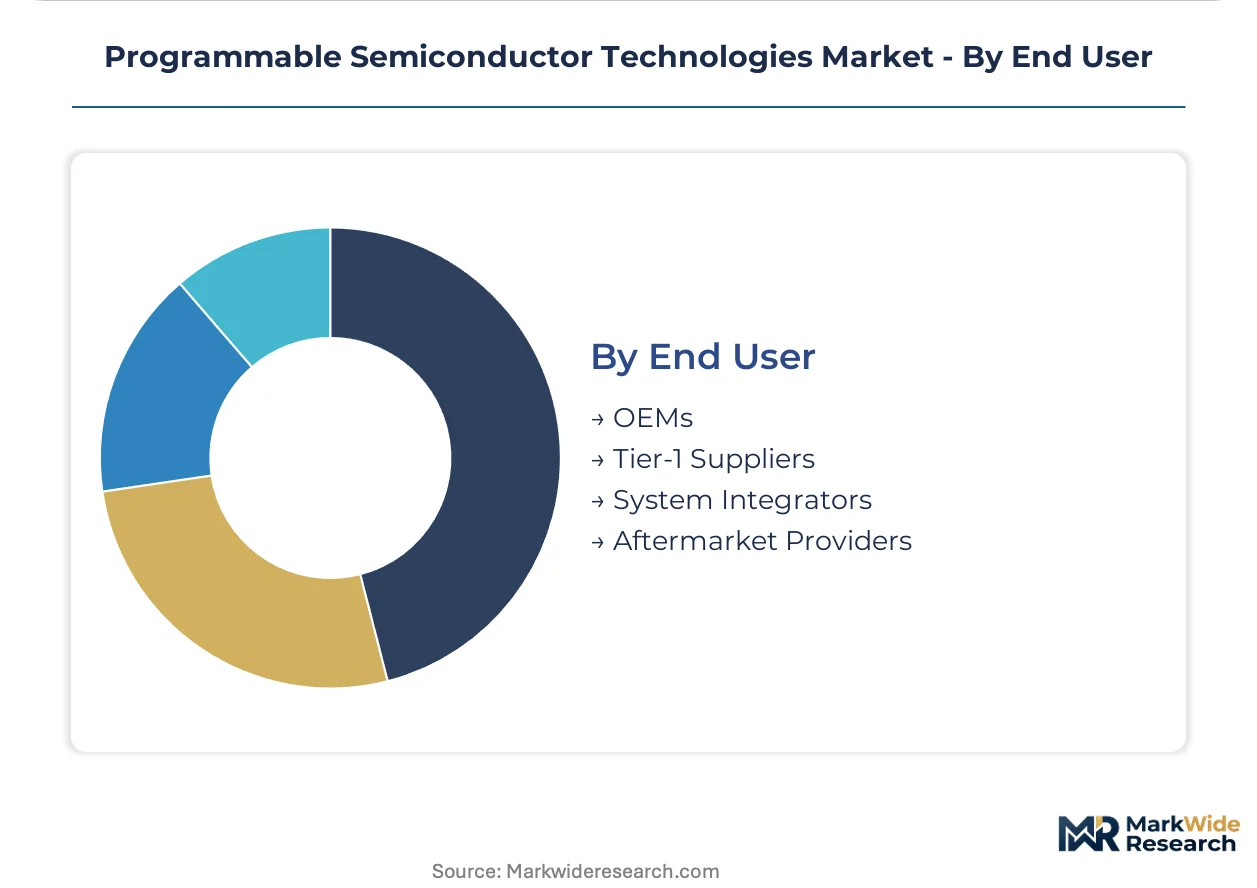
End User:
Supply concentration varies across direct OEM engagements versus tier-1 mediated distribution channels.
- OEMs:Original equipment manufacturers specify programmable semiconductors for captive system designs. Volkswagen and Toyota are compressing specification cycles through direct vendor engagements that displace traditional tier-1 relationships.
- Tier-1 Suppliers:Intermediate component integrators serving multiple OEM platforms with qualified module designs.
- System Integrators:Custom solution providers combining programmable logic with application-specific software stacks.
- Aftermarket Providers:Replacement and upgrade suppliers serving installed base maintenance and retrofit applications.
Procurement volume concentrates in Tier-1 Suppliers; direct OEM engagements are gaining share fastest as platform-centric governance structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hsinchu Science Park and Pyeongtaek anchor foundry concentration for advanced node programmable logic. Tax incentives under Taiwan's Statute for Industrial Innovation and South Korea's K-Semiconductor Belt accelerate capacity buildouts. National industrial policies now determine procurement access for automotive and defense buyers.
United States
Cloud service providers in Northern Virginia and Oregon drive data center FPGA consumption for AI training workloads. The CHIPS and Science Act directs Department of Commerce subsidies toward domestic fab construction with national security guardrails. Intel's manufacturing investments in Arizona and Ohio exemplify captive foundry strategies reducing external dependency.
Taiwan
Leading-edge foundry output from Hsinchu and Tainan supplies programmable logic for global automotive and telecommunications OEMs. The National Development Council coordinates Statute for Industrial Innovation tax credits sustaining R&D intensity. TSMC's advanced packaging facilities in Taichung concentrate heterogeneous integration capabilities for chiplet-based FPGAs.
South Korea
Samsung Electronics and SK Hynix anchor memory-integrated programmable SoC production for 5G baseband and AI inference. The K-Semiconductor Belt clusters Pyeongtaek and Yongin facilities with government-backed infrastructure investment. Seoul-based design houses are migrating toward Arm-integrated embedded FPGA architectures for consumer electronics.
Germany
Automotive OEMs in Stuttgart and Munich consolidate procurement for software-defined vehicle platforms requiring deterministic control logic. The EU Chips Act designates first-of-a-kind facility status for Dresden and Magdeburg fab investments. Bavarian industrial automation buyers favor flash-based FPGAs from domestic distributors for machinery safety systems.
China
Domestic foundries in Shanghai and Wuxi expand mature-node programmable logic capacity for telecommunications infrastructure substitution. MIIT localization mandates accelerate design house migration from foreign IP toward indigenous RISC-V and FPGA architectures. Yangtze Memory Technologies and SMIC anchor packaging partnerships for government-funded data center deployments.
Programmable Semiconductor Technologies Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive foundry operators commanding premium positioning in data center and defense applications while fabless design houses capture automotive and industrial sockets through low-power specialization. Market structure tilts toward consolidated leadership at the leading edge, where EUV lithography access creates supply-side moats, and fragmented competition at mature nodes where Chinese and European entrants compete on cost. Three archetypes dominate: integrated device manufacturers with captive fabrication, fabless FPGA specialists with foundry partnerships, and emerging Chinese vendors with domestic ecosystem alignment. Competitive dynamics center on heterogeneous integration capabilities and packaging ecosystem partnerships rather than silicon node leadership alone.
Within the fabless specialist tier, Lattice Semiconductor and Achronix Semiconductor Corporation represent divergent positioning strategies—one anchored in ultra-low-power automotive sockets, the other in high-performance data center acceleration. Intel Corporation occupies a distinctive structural position as the remaining integrated device manufacturer with captive leading-edge fabrication, exemplifying backward integration into wafer supply that fabless competitors cannot replicate. These three companies illustrate how competitive advantage now derives from packaging technology partnerships and software toolchain completeness rather than transistor density metrics.
| Leading Market Players |
|---|
| Advanced Micro Devices (AMD) |
| Intel Corporation |
| Lattice Semiconductor |
| Microchip Technology |
| Achronix Semiconductor Corporation |
| QuickLogic Corporation |
| Efinix |
| Gowin Semiconductor |
| Flex Logix Technologies |
| Others |
Value Network & Pricing Analysis
Sovereign-backed foundry investments across Taiwan, South Korea, and the United States anchor capacity ownership patterns that translate directly into pricing discipline for advanced node programmable logic. National industrial policies now determine which buyers secure allocation priority, compressing margin flexibility for fabless design houses dependent on external fabrication.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement premiums from standard-queue discounts across foundry customer portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects EUV lithography access tiers, with automotive OEMs paying certification-grade premiums for AEC-Q100 qualified devices. Cost compression in consumer-grade FPGAs intensifies as Chinese foundries expand mature-node capacity. Tier-1 suppliers exhibit highest price sensitivity due to fixed OEM contract pass-through constraints, while defense contractors absorb premiums for trusted foundry sourcing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for data center adaptive computing platforms, displacing traditional tier-1 mediated distribution. Supply concentrates in Taiwan, South Korea, and the United States for leading-edge programmable logic, with China expanding domestic mature-node alternatives. Raw material dependencies span neon gas from Ukrainian extraction zones, palladium catalysts from Russian refineries, and high-purity silicon from German chemical processors. Single-source vulnerability at ASML's EUV lithography systems creates supply chain risk. Distribution runs through authorized distributors for industrial automation, direct foundry relationships for automotive platform teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The programmable semiconductor market sits in a technology-transition phase as chiplet-based heterogeneous integration displaces monolithic FPGA architectures. Legacy standalone device vendors face margin compression unless they rearchitect around system-in-package delivery models.
For Market Incumbents: Cement packaging ecosystem partnerships with HBM suppliers and interposer substrate vendors to defend socket share against emerging chiplet competitors. Deepen backward integration into advanced packaging capabilities in Taiwan and South Korea to reduce dependency on external OSATs. Prioritize automotive functional safety certification investments as OEMs consolidate procurement under platform-centric governance structures.
For New Entrants and Emerging Players: Tier-2 automotive suppliers in India represent the most penetrable channel partner type for tariff-advantaged programmable logic penetration. Target agricultural robotics and unmanned aerial vehicle applications where edge AI inference demands outpace incumbent low-power portfolio coverage. Pursue production-linked incentive qualification under India's semiconductor packaging scheme to establish cost-competitive assembly and test operations.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless FPGA specialists with automotive safety certifications in Germany and Japan as valuation multiples compress from inventory correction cycles. Long-term viability hinges on software toolchain completeness and heterogeneous integration roadmaps rather than silicon node leadership alone. Watch for EU Chips Act first-of-a-kind facility designation announcements as inflection indicators for European supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet-Based Architecture Transition | Enables customization of compute-memory ratios for TSMC CoWoS-packaged data center deployments. |
| Automotive Functional Safety Certification | AEC-Q100 and ISO 26262 compliance unlocks direct OEM procurement engagements in Stuttgart and Munich. |
| Advanced Packaging Capacity Expansion | Heterogeneous integration capabilities in Taichung and Pyeongtaek determine competitive positioning. |
| Edge AI Inference Platform Launch | Arm Ethos-integrated embedded FPGAs penetrate agricultural robotics previously served by GPU accelerators. |
| Domestic Foundry Partnership | SMIC and Yangtze Memory alliances secure MIIT-compliant access for China telecommunications infrastructure substitution. |
Research Methodology
Independent corroboration across foundry capacity announcements, automotive OEM procurement disclosures, and regulatory filing databases underwrites the qualitative findings. Primary interviews with FPGA product managers, automotive platform engineers, tier-1 supplier procurement leads, and foundry business development executives combined with secondary validation from SEC 10-K filings, Department of Commerce CHIPS Act award announcements, and EU Chips Act facility designation records. Bottom-up unit demand modeling and top-down semiconductor content-per-vehicle estimates triangulate market sizing.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions modeled include product architecture, technology node, application end-use, and regional production cluster. CAGRs derive from shipment trajectory analysis and foundry utilization rate projections. Industry-specific forecast inputs span EUV lithography capacity ramp schedules and automotive electrification semiconductor content curves.
Several conditions sit outside the modeled scope, including geopolitical escalation affecting Taiwan Strait logistics, rapid ASML alternative lithography breakthroughs, and fixed-function ASIC substitution acceleration in consumer electronics. Forecasts reflect assumptions about subsidy program continuity and foundry yield maturation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market