
 Latin America Surveillance Analog Camera Market | 2026-2036
Latin America Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Surveillance Analog Camera Market Insights
Consolidation among municipal government buyers across Brazil and Mexico is recalibrating procurement volumes toward framework-contract suppliers. Hangzhou Hikvision Digital Technology Co Ltd leverages its extensive distributor network to sustain deep inventory positions in São Paulo and Mexico City. Bosch Sicherheitssysteme GmbH anchors its regional presence through localized technical support centers that reduce deployment friction for large infrastructure projects. Hanwha Vision America competes aggressively on price-performance ratios for mid-tier commercial installations throughout the Andean region.
Latin America surveillance analog cameras capture video signals through coaxial cable transmission without digital encoding, typically operating at resolutions up to 960H or D1 with composite video output for real-time monitoring in legacy security architectures. Dome cameras occupy the largest volume share across Latin American retail and banking environments where discreet ceiling-mounted surveillance remains standard. Bullet cameras generate faster growth in Mexico's industrial perimeter security segment due to their weather-resistant housings and long-range infrared illumination. Government end users concentrate demand for PTZ cameras at critical infrastructure sites requiring active operator-controlled tracking capabilities.
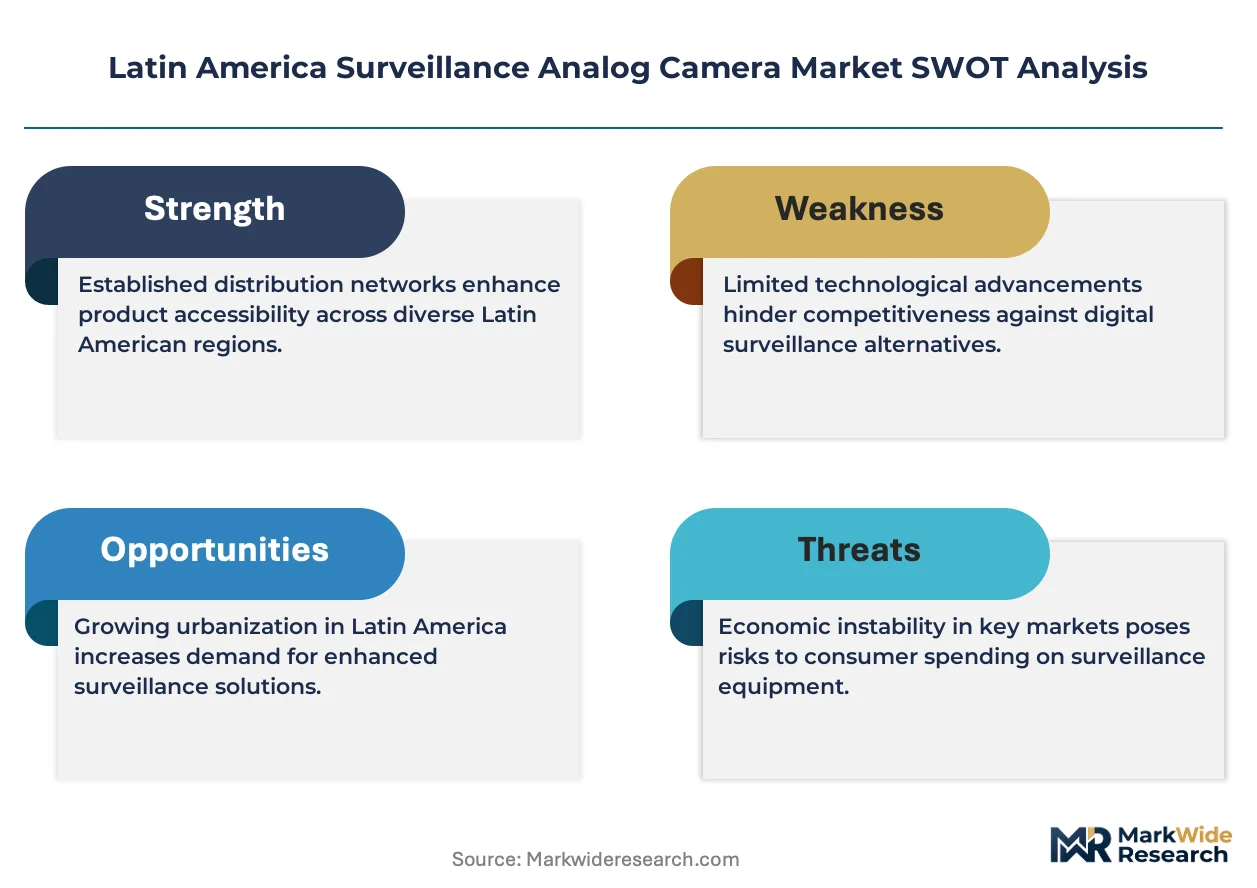
Brazil's ANATEL certification mandates electromagnetic compatibility testing for all imported surveillance equipment, while Mexico's Federal Telecommunications Institute enforces similar conformity assessment protocols that filter non-compliant suppliers from public tenders. Argentina's national communications regulator adds import licensing layers that extend lead times for analog camera shipments entering through Buenos Aires port authorities. Stakeholders must weigh the accelerating cost convergence between analog and IP camera ecosystems when committing to long-term infrastructure refresh cycles across Latin American security budgets.
Market Dynamics
The Latin America surveillance analog camera market faces structural pressure from accelerating cost convergence between analog coaxial systems and IP-based digital infrastructure, forcing procurement committees across Brazil and Mexico to compress refresh cycle timelines.
Growth Catalysts
- ANATEL Certification Harmonization:Brazil's telecommunications regulator has streamlined electromagnetic compatibility testing protocols for surveillance hardware, reducing import clearance friction for compliant equipment suppliers.
- Industrial Perimeter Security Expansion:Manufacturing clusters across Mexico's northern border states are deploying weather-resistant bullet cameras with long-range infrared illumination to protect high-value logistics corridors.
- Municipal Framework Contracting:City governments in São Paulo and Mexico City are consolidating vendor relationships through multi-year procurement agreements that favor established distributor networks.
Market Restraints
- Input Cost Volatility in Copper and Rare Earth Magnets:Coaxial cable production depends on copper pricing swings, while infrared LED assemblies face supply concentration from East Asian rare earth processors.
- Argentina's Import Licensing Layers:The national communications regulator imposes extended documentation requirements that stretch lead times for analog camera shipments entering Buenos Aires port facilities.
- IP Camera Substitution Threat:Network-based surveillance systems with Power-over-Ethernet capability are compressing the total cost of ownership gap against legacy analog installations in greenfield projects.
Strategic Opportunities
- Andean Commercial Mid-Tier Penetration:Colombia and Peru present underdeveloped channels for dome camera deployments in retail banking and hospitality verticals where discreet ceiling-mounted surveillance remains preferred.
- Hybrid DVR-NVR Bridge Technology:Convergence between analog signal encoding and network video recording is creating upgrade pathways that preserve existing coaxial infrastructure investments.
- Mexico's Federal Telecommunications Institute Conformity Streamlining:Recent protocol harmonization with Brazilian testing standards is reducing dual-certification burdens for cross-border equipment suppliers.
Industry Challenges
- Coaxial Infrastructure Technical Skill Shortage:Installation and maintenance expertise for composite video signal troubleshooting is aging out of the workforce faster than certification programs replenish talent pools.
- Legacy System Integration Complexity:Municipal security departments struggle to synchronize PTZ camera control protocols between analog matrix switchers and modern video management software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Surveillance Analog Camera Market |
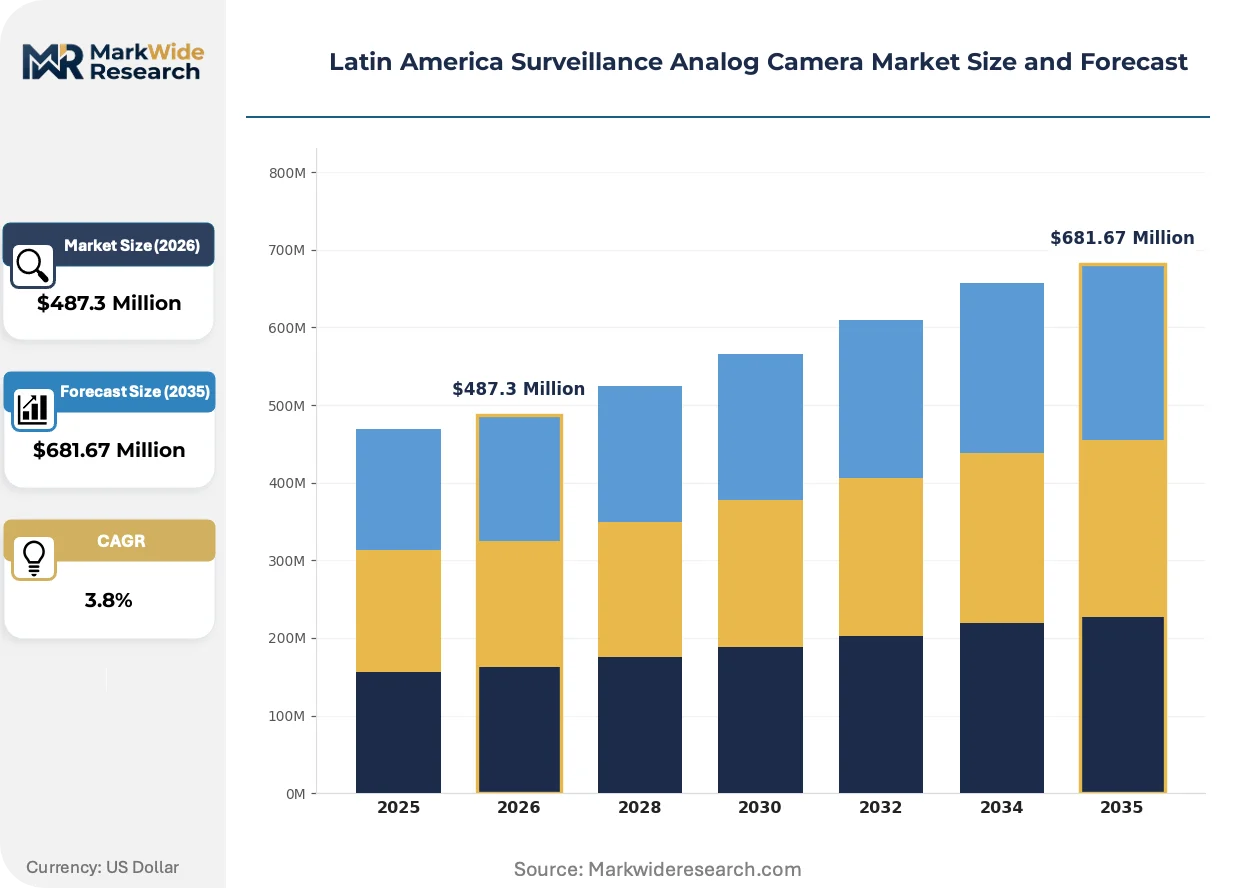
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, C-Mount Cameras, PTZ Cameras End User: Residential, Commercial, Industrial, Government Technology: Standard Definition, High Definition, Infrared, Thermal Imaging Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Teledyne FLIR LLC, Hangzhou Hikvision Digital Technology Co Ltd, Hanwha Vision America, ACTi Corporation, Bosch Sicherheitssysteme GmbH, Pelco, Zhejiang Uniview Technologies Co Ltd, IDIS Ltd, Honeywell International Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Surveillance Analog Camera Market Trends and Innovations
Technological adaptation across Latin American security infrastructure is accelerating as end-users seek to extend analog equipment lifespans while accommodating digital monitoring requirements. Procurement patterns are shifting toward transitional architectures that bridge legacy investments with contemporary functionality.
Signal encoding chipsets with embedded H.264 compression capability are modularizing the analog-to-digital boundary within camera housings themselves. Industrial facility operators in Mexico's manufacturing corridors are adopting these units to feed hybrid recording systems without full infrastructure replacement. This modularizing approach compresses upgrade capital requirements while preserving coaxial cable investments.
Brazil's ANATEL certification mandates for electromagnetic compatibility testing are tightening surveillance hardware import pathways, filtering non-compliant suppliers from public tender participation. The industrial consequence is accelerated distributor consolidation toward framework-contract holders with established testing relationships. Municipal government buyers in São Paulo metropolitan zone are responding by pre-qualifying smaller vendor pools to reduce procurement cycle friction.
Buyer committees across Latin American banking and retail verticals are unbundling after-sales service contracts from equipment procurement, treating maintenance as separately negotiated multi-year agreements. Systems integrators in Mexico City and São Paulo are displacing traditional distributor-led service models with direct technical support centers. This pattern is most visible in dome camera deployments where ceiling-mounted installations demand specialized calibration expertise.
Latin America Surveillance Analog Camera Market Segmentation
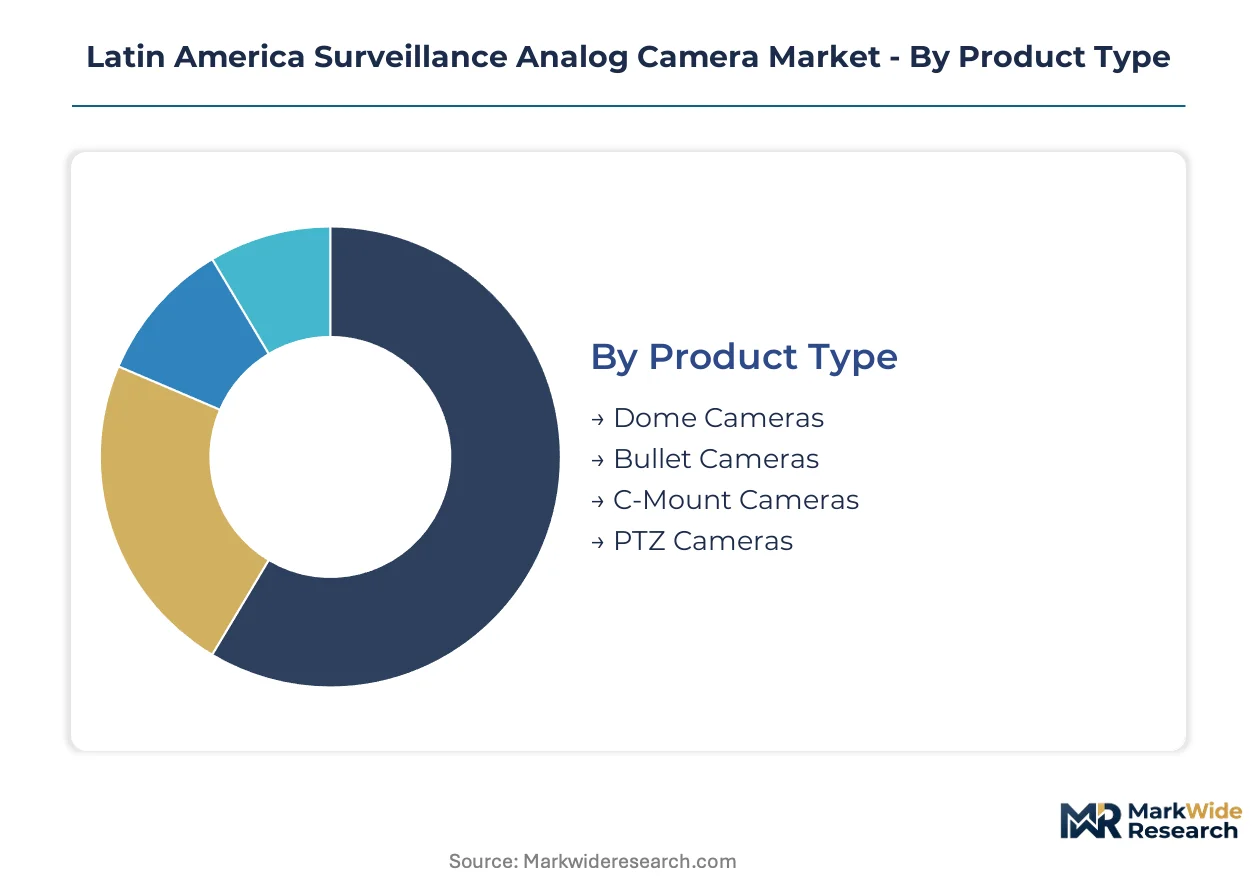
Segmentation of the Latin America surveillance analog camera market reveals how technical specifications, procurement pathways, and end-use requirements shape equipment selection across Brazil, Mexico, and Argentina. Understanding these divides clarifies where coaxial infrastructure investments concentrate versus where IP substitution pressures mount.
Product Type:
Dome, bullet, C-mount, and PTZ configurations differentiate by mounting flexibility, environmental sealing, and operator control requirements across Latin American security deployments.
- Dome Cameras:These housings enclose the lens and sensor within a hemispherical casing designed for discreet ceiling-mounted surveillance in retail banking and hospitality environments. Brazilian retail chains in São Paulo and Rio de Janeiro specify vandal-resistant polycarbonate domes for high-traffic commercial floors where aesthetic discretion conflicts with security visibility.
- Bullet Cameras:Weather-resistant cylindrical housings with integrated infrared illumination arrays dominate Mexico's northern border manufacturing corridors. Matamoros and Tijuana facility operators deploy these units for long-range perimeter monitoring where dust, humidity, and temperature cycling degrade less protected enclosures.
- C-Mount Cameras:Interchangeable lens systems with CS-mount compatibility serve specialized industrial inspection applications requiring varifocal adjustments.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with preset positioning protocols anchor critical infrastructure monitoring at Brazilian power substations and Mexican port facilities.
Dome cameras lead on scale across commercial verticals; bullet cameras lead on momentum in Mexico's industrial perimeter expansion.
End User:
Residential, commercial, industrial, and government buyers diverge sharply in procurement sophistication, installation standards, and compliance documentation requirements.
- Residential:Single-family and multi-unit housing deploys compact dome and bullet units through retail channels with minimal technical support. Argentine homeowners in Buenos Aires suburbs face extended lead times due to national communications regulator import licensing layers that complicate consumer-grade equipment availability.
- Commercial:Banking, hospitality, and retail verticals demand ceiling-mounted dome configurations with discrete positioning. Colombia's retail banking sector in Bogotá concentrates procurement through framework-contract integrators who bundle installation with multi-year maintenance agreements.
- Industrial:Manufacturing and logistics facilities prioritize weather-sealed bullet cameras with infrared range extension. Mexico's automotive assembly plants in Aguascalientes specify IP66-rated housings to withstand chemical washdown protocols.
- Government:Municipal and federal agencies enforce ANATEL certification compliance for electromagnetic compatibility testing. São Paulo's metropolitan transit authority consolidates vendor pools through pre-qualified distributor networks to accelerate public tender cycles.
Commercial end users lead on scale; government buyers lead on procurement consolidation momentum.
Technology:
Resolution specifications, illumination methods, and environmental sensing capabilities segment equipment by image quality and operational conditions.
- Standard Definition:960H and D1 resolution formats with composite video output preserve compatibility with legacy DVR installations. Brazilian municipal governments extending existing coaxial infrastructure favor these units to defer full-system replacement capital requirements.
- High Definition:HD-TVI and HD-CVI signal formats transmit 1080p resolution over coaxial cable without Ethernet infrastructure. Mexican industrial operators in Monterrey manufacturing clusters adopt these hybrid-capable units to bridge analog investments toward digital recording platforms.
- Infrared:LED array illumination extending visible spectrum capture into near-total darkness conditions. Peru's mining security operations in the Andes deploy long-range infrared bullet cameras for perimeter monitoring at remote extraction sites lacking ambient lighting infrastructure.
- Thermal Imaging:Uncooled microbolometer sensors detecting heat signatures independent of visible light. Critical infrastructure operators in Brazil's offshore petroleum facilities specify these units for intrusion detection through fog and smoke conditions.
Standard definition leads on installed base scale; high definition leads on upgrade pathway momentum.
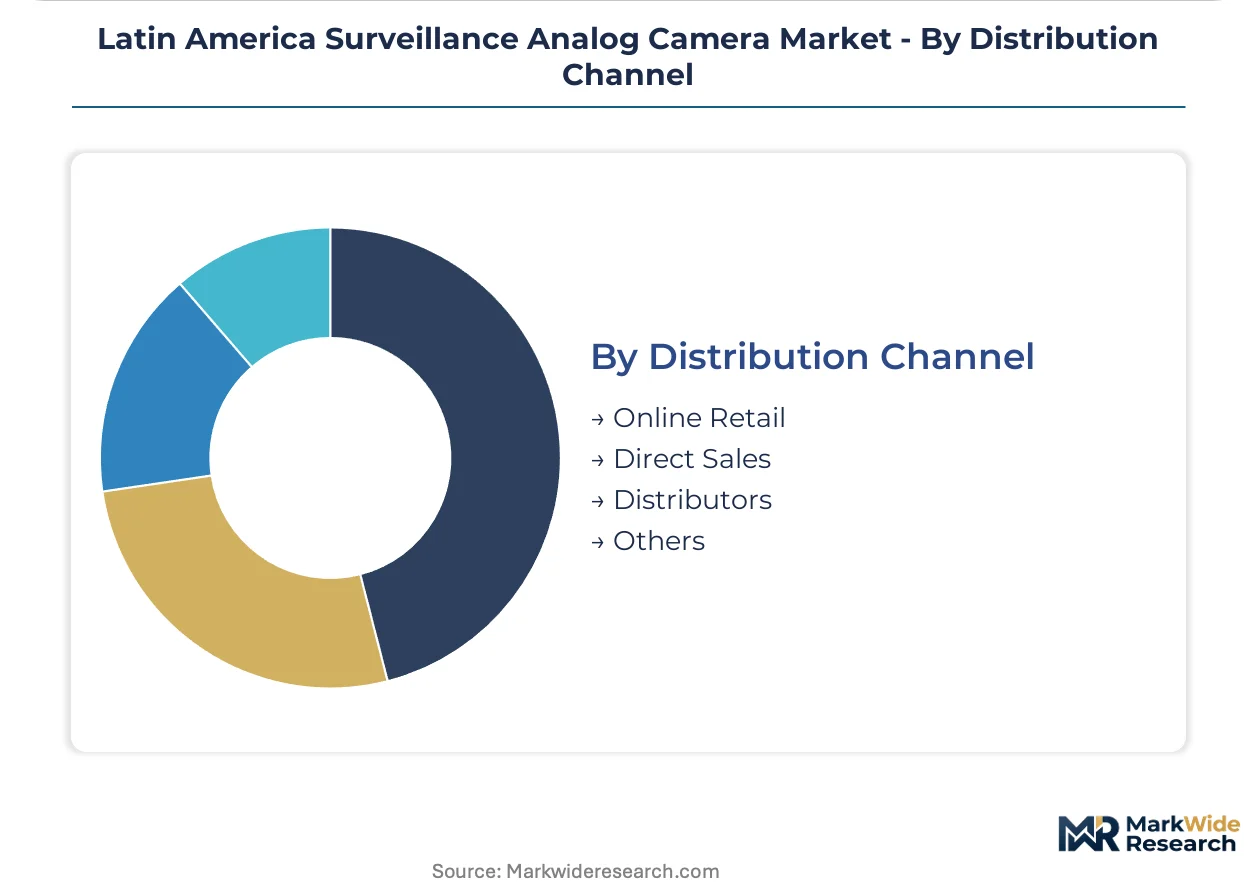
Distribution Channel:
Equipment reaches Latin American end users through diverging pathways that shape pricing transparency, technical support availability, and compliance documentation access.
- Online Retail:E-commerce platforms serve price-sensitive residential buyers and small commercial installers with limited project scale. Chile's Santiago metropolitan area shows concentrated demand through marketplace channels for consumer-grade dome and bullet configurations.
- Direct Sales:Manufacturer-to-end-user relationships dominate large government and industrial tenders requiring customized specification negotiation. Hangzhou Hikvision Digital Technology Co Ltd maintains direct technical support centers in São Paulo and Mexico City to reduce deployment friction for framework-contract holders.
- Distributors:Regional inventory positions with ANATEL certification pre-clearance accelerate procurement cycles for Brazilian systems integrators. Established distributor networks in São Paulo and Rio de Janeiro consolidate market access for compliant equipment suppliers.
- Others:Systems integrator-led procurement and leasing arrangements serve specialized verticals with bundled service requirements.
Distributors lead on volume throughput scale; direct sales leads on large-project capture momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled coaxial infrastructure technicians cluster in São Paulo and Mexico City, anchoring installation capacity for legacy surveillance deployments across Latin America's two largest metropolitan zones.
Brazil
Municipal transit authorities in São Paulo and Rio de Janeiro are expanding dome camera networks along bus corridors and metro stations. ANATEL certification requirements for electromagnetic compatibility testing filter import pathways, consolidating procurement toward pre-qualified distributor networks. The São Paulo metropolitan transit authority bundles PTZ camera deployments with multi-year maintenance agreements to reduce vendor management overhead.
Mexico
Automotive assembly plants in Aguascalientes and electronics manufacturers in Tijuana drive bullet camera demand for perimeter security with IP66-rated weather sealing. The Federal Telecommunications Institute enforces conformity assessment protocols that harmonize with Brazilian testing standards, easing cross-border equipment flows. Northern border manufacturing cities from Matamoros to Tijuana concentrate industrial security spending on long-range infrared illumination systems.
Argentina
Retail banking branches in Buenos Aires specify vandal-resistant dome configurations for high-traffic commercial floors. The national communications regulator imposes extended import licensing documentation that stretches lead times through Buenos Aires port authorities. Suburban residential developments around Córdoba and Rosario source consumer-grade bullet cameras through retail channels despite clearance delays.
Colombia
Bogotá's retail banking sector concentrates procurement through framework-contract integrators bundling installation with service agreements. The country's telecommunications regulator maintains equipment type-approval requirements that shape import compliance pathways. Mining security operations in the Andean highlands deploy thermal imaging units for intrusion detection through fog and limited visibility conditions.
Chile
Santiago's metropolitan area sources consumer-grade dome and bullet configurations through e-commerce marketplace channels. The national telecommunications regulator enforces electromagnetic compatibility standards that parallel regional certification frameworks. Copper mining security budgets in the Atacama Desert sustain demand for weather-sealed bullet cameras with extended infrared range.
Latin America Surveillance Analog Camera Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's surveillance analog camera market, creating a tiered structure where scale-driven manufacturers anchor volume positions while regional specialists capture niche verticals. The vendor base separates into three strategic archetypes: diversified security conglomerates with broad product portfolios, pure-play video surveillance specialists with concentrated technical expertise, and Chinese manufacturers with cost-optimized production scale. Competitive dynamics center on distributor network depth for ANATEL certification compliance and direct technical support center placement to reduce deployment friction.
Among diversified security conglomerates, Bosch Sicherheitssysteme GmbH and Honeywell International Inc represent integrated building technology providers whose regional presence spans multiple security verticals. Hangzhou Hikvision Digital Technology Co Ltd exemplifies the scale-driven specialist archetype, occupying a position anchored by extensive distributor inventory positions in São Paulo and Mexico City. These three companies collectively illustrate how competitive positioning in Latin America's analog camera market depends on certification pre-clearance relationships and localized technical support infrastructure rather than product differentiation alone.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Hanwha Vision America |
| ACTi Corporation |
| Bosch Sicherheitssysteme GmbH |
| Pelco |
| Zhejiang Uniview Technologies Co Ltd |
| IDIS Ltd |
| Honeywell International Inc |
| Others |
Pricing and Supply Chain Analysis
Municipal framework-contract buyers in São Paulo and Mexico City anchor pricing power for established distributor networks, compressing margins for non-pre-qualified suppliers while sustaining premium tiers for ANATEL-certified equipment with bundled technical support.
Pricing Analysis
Unbundled after-sales service contracts from equipment procurement now dominate commercial verticals, with banking and retail buyers treating maintenance as separately negotiated multi-year agreements. Three-tier pricing structure across premium ANATEL-certified, standard compliant, and economy non-certified levels differentiates by electromagnetic compatibility testing investment. Cost compression in mid-tier commercial installations intensifies because Hanwha Vision America and Chinese manufacturers compete aggressively on price-performance ratios. Small residential installers through Chilean e-commerce channels exhibit highest price sensitivity, while São Paulo municipal transit authorities show lowest sensitivity due to framework-contract volume commitments.
Supply Chain Analysis
Skilled coaxial infrastructure technicians in São Paulo and Mexico City manufacturing zones face aging-out faster than certification programs replenish talent pools, constraining installation capacity for legacy deployments. Component sourcing draws from Chinese infrared LED assembly plants, Brazilian copper cable processors, and Mexican weather-sealed housing fabricators. Single-source vulnerability concentrates in East Asian rare earth processors supplying infrared illumination arrays. Distribution runs through ANATEL-pre-cleared distributor networks in São Paulo and Rio de Janeiro that consolidate inventory positions for compliant equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America surveillance analog camera market compounds steadily as municipal infrastructure refresh cycles and industrial perimeter security expansion sustain replacement demand despite IP substitution pressures.
For Market Incumbents: Hedge against IP camera substitution by accelerating hybrid DVR-NVR bridge technology deployment that preserves coaxial infrastructure investments. Deepen backward integration into infrared LED assembly to offset rare earth processor concentration risk. Fortify ANATEL certification relationships to maintain framework-contract eligibility as Brazilian municipal buyers consolidate vendor pools.
For New Entrants and Emerging Players: Capture underdeveloped Andean commercial channels in Colombia and Peru where retail banking and hospitality verticals lack established dome camera integrators. Prioritize Bogotá framework-contract bidding against incumbent distributor-led service models. Lead with direct technical support center placement to displace traditional installation-calibration dependencies.
For Investors and Strategic Acquirers: Chinese security conglomerates are the most active acquirer in this space, seeking Latin American distributor networks with ANATEL pre-clearance relationships. The five-to-ten year viability window favors hybrid-capable specialists with backward integration into signal encoding chipset design. Monitor cost convergence velocity between analog and IP ecosystems as the critical inflection signal for portfolio reweighting.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid DVR-NVR Bridge Technology Deployment | Preserves coaxial cable investments while accommodating digital recording requirements for Mexican industrial operators. |
| ANATEL Certification Pre-Clearance Investment | Maintains framework-contract eligibility as São Paulo municipal buyers consolidate toward pre-qualified vendor pools. |
| Direct Technical Support Center Expansion | Reduces deployment friction for large infrastructure projects and displaces distributor-led service models. |
| Backward Integration into Infrared LED Assembly | Mitigates rare earth processor concentration risk from East Asian suppliers for long-range illumination systems. |
| Andean Channel Partner Development | Captures underpenetrated retail banking and hospitality verticals in Colombia and Peru lacking established integrators. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Colombia, and Chile, with primary inputs from each national market combining interviews with municipal procurement officers, industrial security directors, systems integrators, and distributor network managers alongside secondary validation. Primary fieldwork draws from ANATEL regulatory filings, Mexican Federal Telecommunications Institute conformity assessment records, customs trade data for surveillance equipment imports, and SEC 10-K disclosures from listed security equipment manufacturers. Bottom-up installation volume estimates triangulate against top-down security spending forecasts from national budget appropriations.
Granularity-level modeling disaggregates volume and value across product type, end user vertical, technology resolution tier, and distribution channel throughout the projection horizon. The analytical framework derives CAGRs from segment-specific replacement cycle timing, infrastructure investment pipelines, and regulatory compliance phase-in schedules. Industry-specific forecast inputs include municipal framework-contract award timelines, manufacturing foreign direct investment flows into northern Mexico, and telecommunications regulator certification queue lengths.
Copper price volatility, rare earth export restriction escalations, and accelerated IP camera cost parity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about infrastructure refresh pacing and regulatory harmonization trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Hyperspectral Imaging Camera Market
Imaging
Global Microscopy Market
Imaging
Mobile Imaging Services Market
Imaging
Global Computed Radiography Market
Imaging
Hyperspectral Imaging Market
Imaging
Instant Digital Cameras Market
Imaging
North America Image Sensors Market
Imaging
Camera Technology Market
Imaging
Hybrid Imaging Market
Imaging
Wide Field Imaging Devices Market
Imaging
Photoacoustic Imaging Market
Imaging
Automotive Compact Camera Module Market
Imaging
Video Processing Solutions Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Photography Ring Flash Market
Imaging
Brain Imaging and Neuroimaging Market