
 Third-Generation Solar Cells Market | 2026-2036
Third-Generation Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Third-Generation Solar Cells Market Analytics
Chinese perovskite pilot lines is repositioning the supply base toward tandem-cell architectures before Western fabs reach comparable scale. Oxford PV leverages European R&D partnerships to anchor its specialty in silicon-perovskite tandems for premium rooftop segments. LONGi Green Energy sustains cost leadership through in-house wafering and metallization, while First Solar competes on cadmium-telluride thin-film efficiency at utility scale.
Third-generation solar cells employ emergent absorber materials—organic semiconductors, perovskite halides, or multi-junction III-V stacks—deposited via solution processing, vacuum evaporation, or epitaxial growth onto flexible or rigid substrates, converting photon energy across broader spectral ranges than conventional silicon. Their primary purpose lies in applications where weight, form factor, or low-light performance outweighs pure cost-per-watt metrics. Perovskite technology leads research investment and efficiency gains, though organic photovoltaics occupies niche building-integrated segments where semi-transparency and flexible substrates command price premiums. Multi-junction cells dominate space and concentrated-solar power plants where extreme efficiency justifies manufacturing complexity.
The EU Green Deal and REACH shape material sourcing and end-of-life recycling obligations for European producers, while China's MIIT and GB standards govern domestic perovskite stability testing and grid-interconnection protocols. The US EPA and state-level renewable portfolio standards influence project finance eligibility and domestic content bonuses. Stakeholders must monitor which regulatory jurisdiction certifies tandem-cell degradation rates first, as that approval will unlock insured project debt and reshape competitive positioning across the value chain.
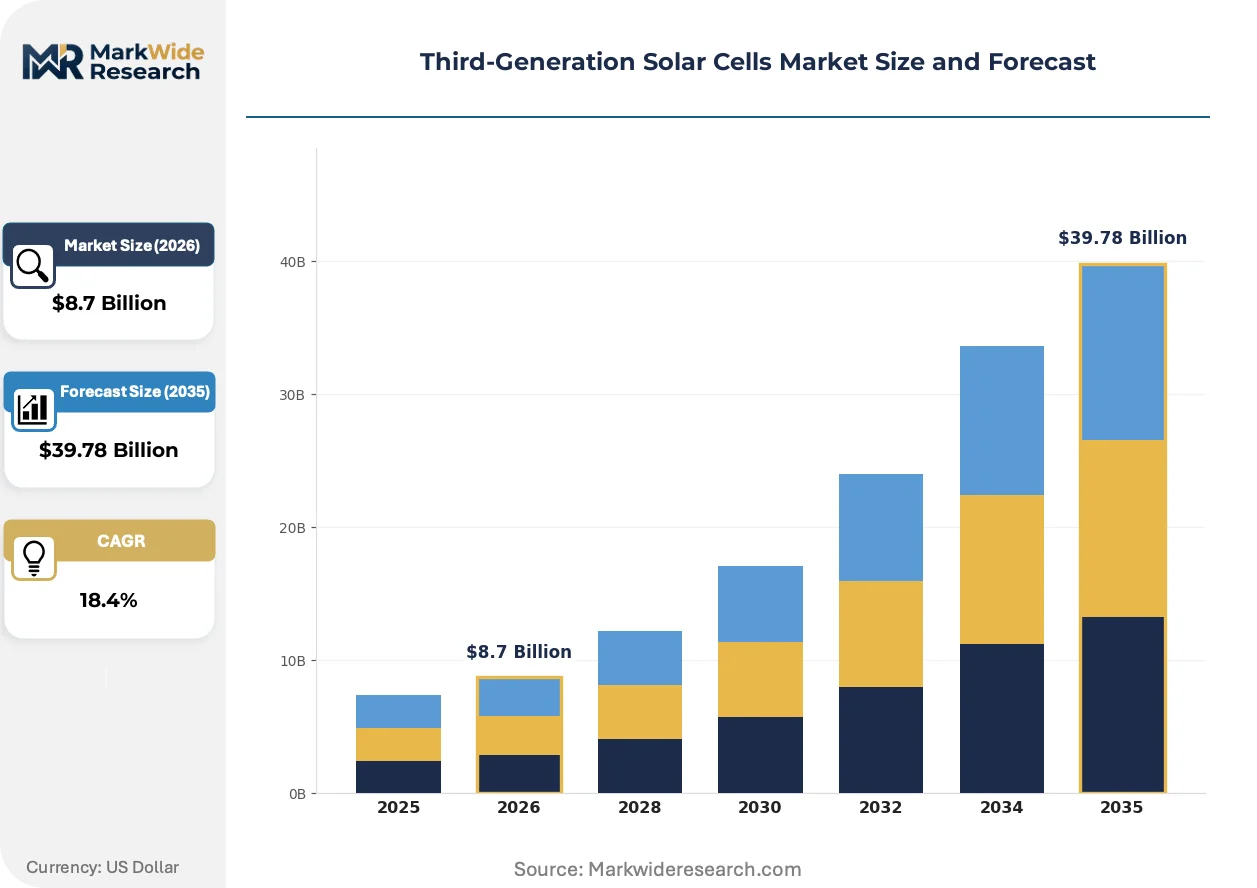
Market Dynamics
Silicon-perovskite tandem architectures are compressing the efficiency gap between laboratory records and commercial modules, forcing capital reallocation across wafering, metallization, and encapsulation equipment before degradation certification standards stabilize.
Growth Catalysts
- EU Green Deal carbon-accounting rules:Tightening supply-chain disclosure requirements for solar imports are favoring domestic European module assembly and transparent perovskite sourcing.
- Building-integrated photovoltaics:Semi-transparent organic and perovskite films are penetrating commercial facade retrofits where conventional silicon cannot conform to curved or weight-constrained substrates.
- China's MIIT pilot protocols:Government-backed tandem-cell demonstration projects are accelerating grid-interconnection testing for next-generation architectures ahead of Western certification timelines.
Market Restraints
- Lead halide toxicity:REACH and RoHS substance restrictions in Europe are complicating perovskite formulation choices and end-of-life recycling obligations for manufacturers targeting EU markets.
- Silver paste dependency:Metallization costs for silicon bottom cells in tandem stacks remain vulnerable to precious metal price volatility and concentrated refining capacity.
- Epitaxial III-V manufacturing:Multi-junction cell production requires MOCVD reactors and germanium substrates with limited supplier bases outside specialized compound-semiconductor foundries.
Strategic Opportunities
- Agrivoltaic dual-use installations:Semi-transparent organic modules are penetrating agricultural canopy applications in Japan and the Netherlands where spectral selectivity supports crop growth beneath power generation.
- US IRA domestic content bonuses:Treasury guidance on advanced manufacturing tax credits is creating first-mover advantage for thin-film and tandem-cell facilities qualifying under domestic content thresholds.
- Perovskite-silicon equipment convergence:Shared vacuum deposition and laser scribing tools are enabling retrofit of existing silicon lines for tandem production without full fab replacement.
Industry Challenges
- Thermal cycling certification:IEC 61215 and IEC 61646 test protocols for silicon modules do not adequately capture ion-migration degradation mechanisms unique to hybrid organic-inorganic perovskites.
- Cross-licensing complexity:Fragmented patent estates covering perovskite composition, solvent engineering, and encapsulation are inflating freedom-to-operate due diligence for commercial scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third-Generation Solar Cells Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Perovskite, Organic Photovoltaics, Multi-Junction, Thin-Film End User: Residential, Commercial, Industrial, Utility Application: Building Integrated Photovoltaics, Power Plants, Off-Grid Systems, Transportation Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Oxford PV, Saule Technologies, LONGi Green Energy, First Solar, 3GSolar, Greatcell Solar, Heliatek, Solaronix, PECCELL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third-Generation Solar Cells Market Evolving Landscape
Solution-processed deposition techniques are collapsing the capital intensity gap between silicon wafering and thin-film manufacturing, enabling new entrants to challenge incumbent module supply chains without polysilicon integration.
Slot-die coating and inkjet printing of perovskite precursor layers is automating the transition from batch spin-coating to roll-to-roll fabrication, allowing glass and flexible polymer substrate manufacturers to adopt photovoltaic production without semiconductor cleanroom infrastructure, compressing time-to-market for building-integrated and consumer electronics applications.
China's MIIT stability testing protocols and GB standards for perovskite grid connection are diverging from IEC frameworks, creating a dual-track certification environment where modules qualified for domestic Chinese projects may require additional testing for European or North American deployment, segmenting the addressable market by regulatory jurisdiction rather than pure technical performance.
Utility-scale developers in India and the United States are unbundling module supply from engineering-procurement-construction contracts, creating direct procurement relationships with emerging tandem-cell manufacturers that bypass traditional distributor and integrator channels, concentrating volume commitments with technology-specific suppliers before bankability standards mature.
Third-Generation Solar Cells Market Segmentation
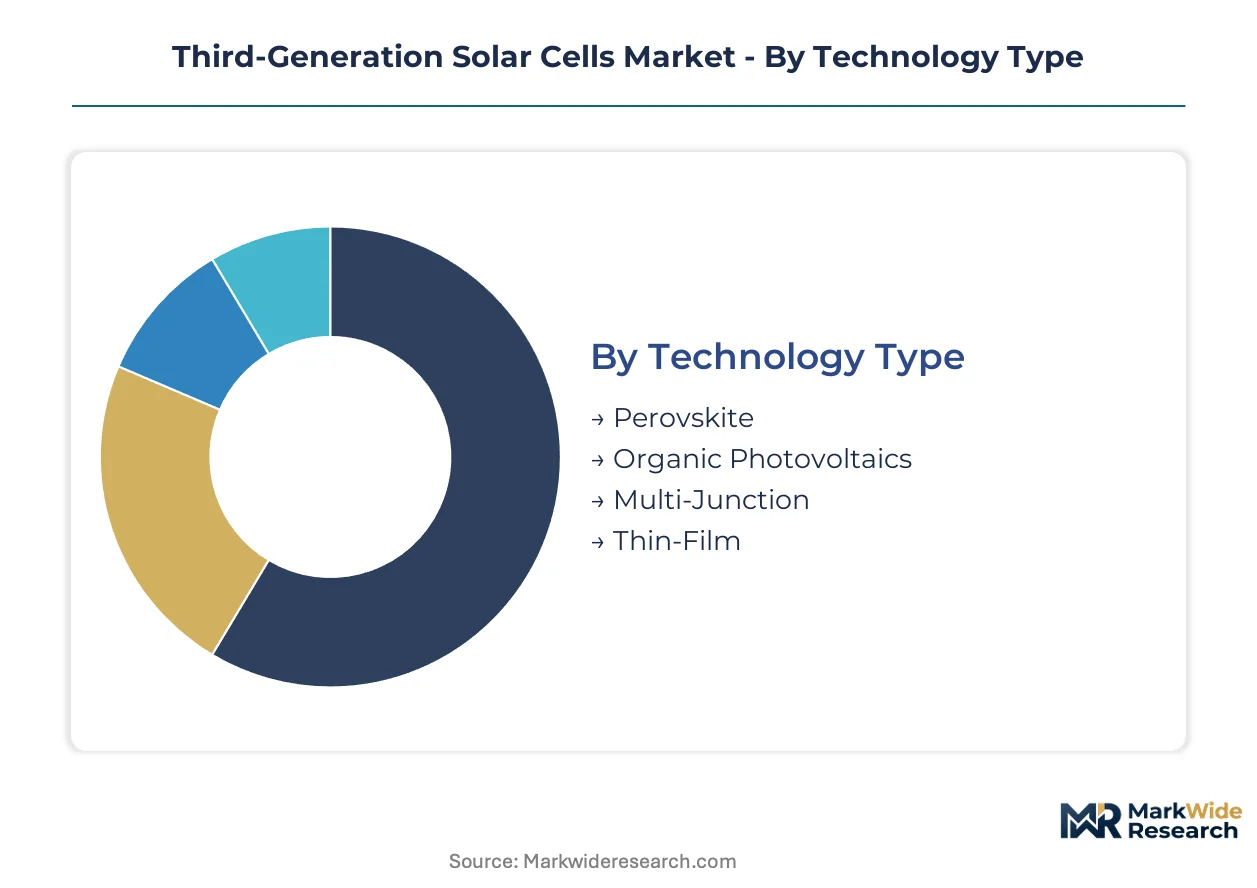
Third-generation solar cells fragment across multiple dimensions that determine manufacturing investment, certification pathways, and customer procurement patterns. Technology type dictates deposition equipment and material supply chains. End-user concentration shapes financing structures and bankability requirements. Application specificity drives form-factor and encapsulation choices.
Technology Type:
Perovskite commands volume leadership through solution-processed manufacturing scalability, while multi-junction retains premium positioning through efficiency extremes.
- Perovskite:Hybrid organic-inorganic halide absorbers deposited via slot-die coating or inkjet printing achieve tandem-cell efficiencies exceeding single-junction silicon limits. Chinese MIIT pilot lines are absorbing the majority of precursor chemical output as domestic manufacturers accelerate grid-interconnection testing ahead of IEC certification timelines.
- Organic Photovoltaics:Carbon-based semiconductors enable semi-transparent, flexible modules for architectural integration where weight and aesthetics override cost-per-watt metrics. Demand concentrates in German and Dutch building retrofit markets where EU Green Deal carbon-accounting rules favor domestically assembled facade systems.
- Multi-Junction:Stacked III-V compound semiconductors grown via metalorganic chemical vapor deposition deliver efficiencies above 40 percent under concentrated illumination. Space agencies and concentrated solar power developers in the United States and Saudi Arabia absorb limited production from specialized compound-semiconductor foundries.
- Thin-Film:Cadmium-telluride and copper-indium-gallium-selenide absorbers deposited on glass substrates compete on manufacturing throughput rather than efficiency records. Utility-scale procurement in India and the United States favors this technology where project finance depends on proven degradation warranties rather than laboratory performance.
Today's leader: Perovskite. Tomorrow's challenger: Multi-Junction.
End User:
Utility-scale procurement concentrates volume commitments, while residential segments sustain premium pricing through distributed generation incentives.
- Utility:Centralized power plants require module bankability certifications and 25-year performance warranties that favor established thin-film and emerging tandem-cell suppliers with demonstrated field data. Indian and American developers are unbundling module supply from engineering-procurement-construction contracts to secure direct relationships with technology-specific manufacturers.
- Commercial:Corporate renewable energy buyers prioritize building-integrated aesthetics and carbon-disclosure compliance over pure cost optimization. German commercial facade retrofits are absorbing semi-transparent organic and perovskite modules that satisfy REACH substance restrictions and end-of-life recycling obligations.
- Industrial:Manufacturing facilities with high behind-the-meter consumption value reliability and peak-shaving capability. Off-grid and hybrid systems with battery storage are penetrating remote industrial sites in Australia and South Africa where grid extension costs exceed distributed generation capital.
- Residential:Rooftop installations depend on installer network density and financing product availability. Premium silicon-perovskite tandems from European R&D partnerships are penetrating high-income segments where efficiency density matters more than first-cost minimization.
Utility procurement anchors current revenue. Commercial integration delivers the steepest expansion trajectory.
Application:
Building-integrated photovoltaics command form-factor premiums, while power plants absorb manufacturing scale.
- Building Integrated Photovoltaics:Semi-transparent and flexible modules replace conventional glazing in curtain walls, skylights, and canopies. Japanese agrivoltaic installations are deploying spectral-selective organic films that transmit photosynthetically active radiation while generating electricity above rice paddies and greenhouse operations.
- Power Plants:Utility-scale ground-mounted installations prioritize levelized cost of energy and degradation-resistant encapsulation. American developers are qualifying tandem-cell modules under Treasury IRA domestic content guidance to capture advanced manufacturing tax credits before bankability standards mature.
- Off-Grid Systems:Remote telecommunications, rural electrification, and disaster relief applications value lightweight packaging and rapid deployment. Flexible perovskite and organic modules are penetrating African and Southeast Asian markets where logistics constraints exclude glass-heavy conventional panels.
- Transportation:Electric vehicle integrated solar roofs, charging station canopies, and railway corridor installations demand automotive-grade reliability testing. German automotive suppliers are piloting perovskite integration into passenger vehicle roofs where curved surface conformity exceeds silicon capabilities.
Power plants dominate shipment volume. Building integration captures margin expansion.
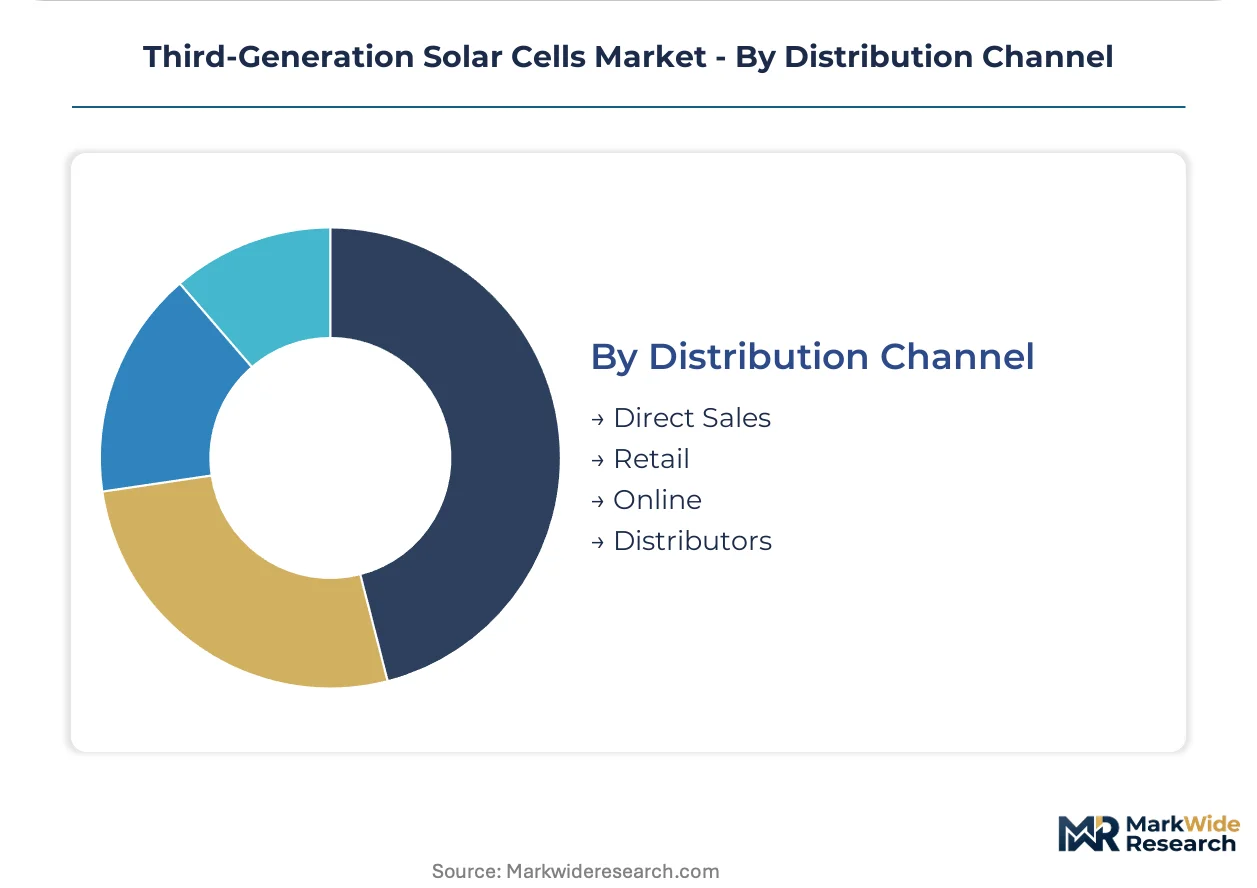
Distribution Channel:
Direct sales concentrate strategic relationships, while distributor networks fragment price transparency.
- Direct Sales:Module manufacturers engage utility developers and engineering-procurement-construction firms through long-term offtake agreements and co-development partnerships. Emerging tandem-cell suppliers are bypassing traditional distributors to secure volume commitments before certification completion.
- Distributors:Regional wholesalers maintain inventory positions and installer credit facilities for established technologies. European distributors are building perovskite handling capabilities as REACH compliance documentation becomes a competitive differentiator.
- Retail:Big-box home improvement and electrical supply chains serve residential and small commercial contractors. Online configurators for building-integrated systems are penetrating premium residential segments where aesthetic customization commands price premiums.
- Online:E-commerce platforms enable direct-to-consumer sales of portable and consumer electronics-integrated solar products. Japanese and South Korean electronics retailers are featuring flexible organic photovoltaic accessories for outdoor recreation and emergency preparedness.
Direct sales capture strategic utility volume. Distributor relationships determine residential market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting pilot-line investments toward jurisdictions with faster certification timelines and lighter substance restrictions, compressing the cost-of-compliance gap between European REACH obligations and Chinese MIIT protocols.
China
Domestic absorption of perovskite precursor chemicals concentrates in Yangtze River Delta pilot facilities where MIIT grid-interconnection testing precedes IEC timelines. GB standards for stability assessment diverge from European frameworks, creating a dual-track qualification environment. Suzhou and Hefei clusters host integrated polysilicon-to-module ecosystems with government-backed building-integrated demonstration projects.
United States
Treasury IRA guidance on advanced manufacturing tax credits is concentrating thin-film and tandem-cell facility announcements in the Southwest and Southeast. EPA domestic content thresholds influence engineering-procurement-construction contract structures for utility-scale developers. Texas and Arizona project pipelines are unbundling module procurement to secure direct supplier relationships before bankability standards mature.
Germany
EU Green Deal carbon-accounting rules and REACH substance restrictions are favoring domestically assembled facade systems with transparent supply-chain disclosure. Commercial retrofit demand in Berlin and Munich absorbs semi-transparent organic modules where end-of-life recycling obligations command price premiums. ECHA lead-halide toxicity assessments complicate perovskite formulation choices for manufacturers targeting building-integrated segments.
India
Central Electricity Authority renewable purchase obligations and state-level solar parks are absorbing cadmium-telluride and emerging tandem-cell volumes at utility scale. PLI scheme incentives for advanced cell manufacturing are attracting domestic module assembly investments in Gujarat and Rajasthan. Rajasthan Solar Park developers are qualifying new technologies under extended field-test protocols before 25-year warranty commitments.
Japan
METI agrivoltaic pilot programs are deploying spectral-selective organic films in rice paddy and greenhouse applications where photosynthetically active radiation transmission supports dual-use economics. Kanto and Kansai regional grids are testing perovskite stability under humid subtropical conditions distinct from desert test environments. Osaka-based electronics retailers are featuring flexible photovoltaic accessories for outdoor recreation and emergency preparedness segments.
Third-Generation Solar Cells Market Competitive Landscape
Chinese producers anchor the scale-driven tier; European specialists hold premium positioning through R&D partnerships and architectural integration capabilities. The vendor base separates into three functional archetypes: integrated polysilicon-to-module conglomerates with captive wafering capacity, thin-film specialists competing on manufacturing throughput, and emergent tandem-cell developers racing to secure bankability certification ahead of degradation standard finalization. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms retrofit existing silicon lines for tandem production.
Among the named participants, Oxford PV exemplifies European R&D partnership models, LONGi Green Energy represents Chinese integrated manufacturing scale, and First Solar anchors American thin-film specialization. Oxford PV occupies a position within silicon-perovskite tandem development, LONGi Green Energy sits within cost leadership through in-house wafering and metallization control, and First Solar exemplifies utility-scale competition through cadmium-telluride efficiency records. These three entities collectively represent the geographic and technological divergence shaping procurement patterns across utility, commercial, and building-integrated segments.
| Leading Market Players |
|---|
| Oxford PV |
| Saule Technologies |
| LONGi Green Energy |
| First Solar |
| 3GSolar |
| Greatcell Solar |
| Heliatek |
| Solaronix |
| PECCELL Technologies |
| Others |
Value Network & Pricing Analysis
Utility-scale developers unbundling module procurement from engineering-procurement-construction contracts are forcing supply chains to absorb direct volume commitments without distributor margin layers, compressing pricing power for middlemen while concentrating margin with manufacturers capable of bankability certification.
Pricing Analysis
Distributor margins collapse where direct manufacturer-to-developer relationships dominate procurement. Three-tier pricing structure across premium certified tandems, standard thin-film, and economy-grade organic modules separates bankable warranties from field-test products. Cost compression in standard-tier cadmium-telluride modules intensifies as Chinese perovskite pilot lines scale precursor output. Utility buyers exhibit lowest price sensitivity where 25-year performance guarantees dominate procurement criteria; residential segments show highest sensitivity to first-cost minimization.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for precursor chemical and finished module logistics. Manufacturing concentrates in China, Germany, and the United States where MIIT, REACH, and IRA frameworks respectively govern qualification protocols. Perovskite precursor supply rests on iodide salt refining capacity concentrated in Chinese chemical parks; silver paste for silicon bottom cells draws from Korean and Japanese metallization specialists. Single-source vulnerability in germanium substrate supply for multi-junction cells creates chokepoint exposure. Distribution runs through direct sales for utility volume and specialized distributors for building-integrated segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where faster MIIT certification timelines in China against REACH substance restrictions in Europe create divergent cost-of-compliance profiles for perovskite manufacturers.
For Market Incumbents: Cement bankability leadership by accelerating tandem-cell degradation certification ahead of IEC standard finalization. Secure captive supply of silver paste and iodide precursors through backward integration into metallization and chemical refining. Defend against emerging Chinese scale players by anchoring premium rooftop segments through silicon-perovskite efficiency records.
For New Entrants and Emerging Players: Capture white-space in agrivoltaic spectral-selective organic modules where Japanese METI pilot programs validate dual-use economics ahead of global scale. Penetrate building-integrated facade retrofits in German commercial markets where EU Green Deal carbon-accounting rules favor transparent supply-chain disclosure. Lead with direct-to-developer sales models that bypass traditional distributor markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compound-semiconductor foundries holding MOCVD reactor capacity for multi-junction III-V stacks. Long-term viability hinges on which regulatory jurisdiction certifies tandem-cell degradation rates first, unlocking insured project debt. Watch for Treasury IRA domestic content guidance finalization as inflection signal for American manufacturing facility valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Tandem-Cell Certification Acceleration | First-mover bankability under IEC or MIIT protocols captures utility-scale procurement commitments before competitors qualify. |
| Precursor Chemical Backward Integration | Captive iodide salt refining capacity insulates perovskite manufacturers from Chinese chemical park supply volatility. |
| Agrivoltaic Pilot Program Expansion | METI-validated spectral-selective organic modules unlock dual-use economics in Japanese and Dutch agricultural markets. |
| Building-Integrated Direct Sales Channel | Bypassing distributors for commercial facade retrofits captures margin layers while satisfying REACH disclosure requirements. |
| Silver Paste Metallization Substitution | Copper-based alternatives reduce precious metal dependency and concentrated Korean refining exposure in tandem-cell stacks. |
Research Methodology
Direct dialogue with module manufacturing executives, utility procurement officers, engineering-procurement-construction contractors, and grid-interconnection regulators grounded qualitative assessment in operational reality. Secondary validation drew from MIIT pilot protocol disclosures, EPA domestic content guidance documents, EU Green Deal implementation texts, and IEC certification draft standards. Bottom-up project pipeline tracking across Indian state solar parks and American Southwest development zones triangulated against top-down chemical precursor production estimates.
Segmented outputs across technology type, end-user concentration, application specificity, and distribution channel structure were generated through the projection horizon. CAGRs derived from fitted adoption curves incorporating learning-rate effects in perovskite deposition equipment and policy incentive phase-out schedules. Key inputs included MIIT stability testing timeline assumptions and Treasury IRA guidance interpretation for domestic content thresholds.
Underlying measurement precision varies by segment; utility-scale procurement volumes carry tighter precision than emerging building-integrated applications where project-level data remains sparse. Forecasts reflect documented assumptions regarding certification timeline convergence and precursor chemical supply expansion. Perovskite degradation mechanism uncertainty and regulatory jurisdiction fragmentation represent primary revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market