
 3D Xpoint Technology Market | 2026-2036
3D Xpoint Technology Market Size, Share, and Industry Trends Forecast 2026-2036
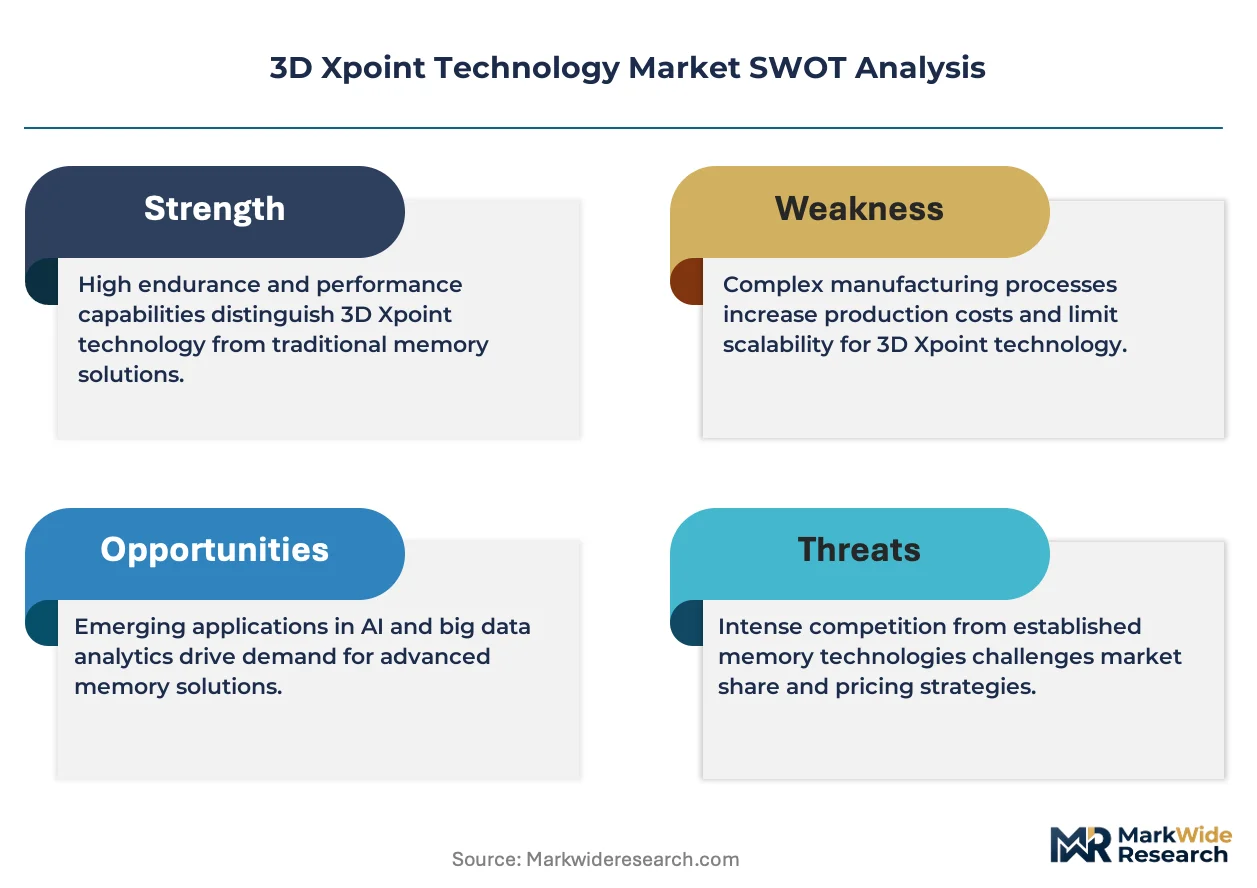
3D Xpoint Technology Market Analysis
Asset-light leasing models for advanced fabrication equipment are reshaping capital deployment among emerging memory contenders. Intel Corporation leverages its captive foundry infrastructure to sustain process development without full equipment ownership. Micron Technology anchors its competitive stance through backward integration into materials sourcing for non-volatile cell stacks. Samsung Electronics dominates advanced packaging partnerships that extend its reach into hybrid memory configurations.
3D Xpoint technology refers to a class of non-volatile memory cells built on a bulk-change mechanism in chalcogenide materials, offering bit-addressable access latencies between DRAM and NAND flash. The architecture eliminates transistor-per-cell overhead, enabling denser crosspoint arrays for high-throughput storage-class memory applications. Memory modules and high-performance SSDs command the largest installed base, though compute acceleration cards represent the fastest-expanding margin pool as AI training workloads proliferate. Embedded memory configurations remain nascent but attract focused R&D investment from cloud providers seeking rack-level consolidation.
FDA oversight applies to medical device data logging subsystems that incorporate persistent memory, while EPA regulations govern fluorinated gas emissions from etching processes used in 3D Xpoint layer deposition. The EU F-Gas Regulation tightens supply chain constraints for European-bound production, compelling manufacturers to qualify alternative chemistries or absorb carbon-border compliance costs. Stakeholders must monitor whether emerging neuromorphic computing architectures displace conventional storage-class memory interfaces before fabrication scale economics mature.
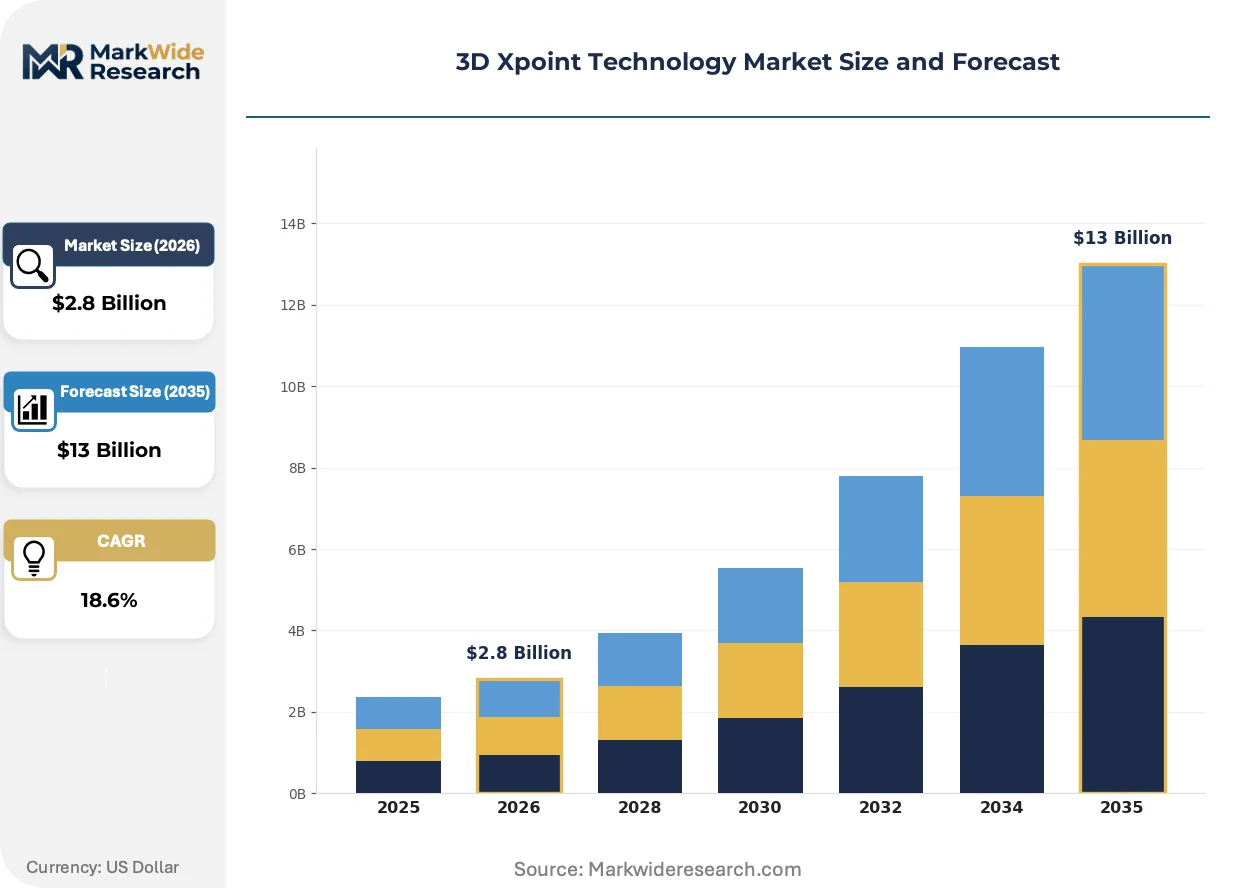
Market Dynamics
Hyperscale data center operators are consolidating storage tiers around bit-addressable persistent memory, forcing NAND flash suppliers into defensive positioning while chalcogenide-based cell architectures capture latency-sensitive workloads previously served by DRAM overprovisioning.
Growth Catalysts
- EU F-Gas Regulation phase-down:The regulation's tightening quotas on fluorinated etching gases are accelerating qualification of alternative chemistries, creating first-mover advantages for manufacturers with advanced process engineering capabilities.
- AI training infrastructure buildouts:Cloud providers deploying GPU clusters for large language model training are specifying storage-class memory to eliminate checkpoint serialization bottlenecks.
- Chalcogenide material refinements:Advances in germanium-antimony-tellurium stoichiometry are extending cell endurance beyond prior generation limits, opening financial services transaction logging applications.
Market Restraints
- Deposition equipment concentration:Atomic layer deposition tools for crosspoint array fabrication source predominantly from a limited supplier base in Germany and Japan, creating chokepoint vulnerability.
- DRAM price elasticity:Continued cost declines in conventional volatile memory narrow the total-cost-of-ownership gap for latency-sensitive deployments, threatening substitution at the margin.
- EPA fluorinated gas reporting:Mandatory disclosure requirements for etching process emissions add compliance overhead to US-based fabrication, disadvantaging domestic production relative to jurisdictions with less stringent monitoring.
Strategic Opportunities
- Edge computing node consolidation:Industrial automation OEMs in Germany are piloting embedded persistent memory to eliminate battery-backed SRAM in programmable logic controllers.
- India PLI scheme for semiconductors:The production-linked incentive framework offers capital expenditure support for domestic memory packaging and testing facilities, attracting module assembly relocation.
- Compute Express Link integration:Convergence between CXL protocol enablement and storage-class memory controllers permits cache-coherent sharing across processor sockets, unlocking multi-tenant cloud database architectures.
Industry Challenges
- Chalcogenide thin-film deposition expertise:The specialized knowledge base for uniform phase-change material sputtering across 300mm wafers concentrates within a narrow cohort of process engineers, constraining talent mobility.
- Storage Performance Development Kit certification:Software stack qualification for kernel-bypass access libraries requires extended validation cycles with operating system distributors, delaying customer deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Xpoint Technology Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Modules, Storage Devices, High-Performance SSDs, Compute Acceleration Cards End User: Data Centers, Cloud Providers, Enterprises, Industrial Applications Technology: Non-Volatile Memory, Neuromorphic Computing, Hybrid Memory, Embedded Memory Application: Artificial Intelligence, Big Data Analytics, Edge Computing, Internet of Things |
| Companies Covered | Intel Corporation, Micron Technology, Samsung Electronics, Western Digital Corporation, SK Hynix, Toshiba Corporation, IM Flash Technologies, SanDisk Corporation, Kingston Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Xpoint Technology Market Emerging Trajectories
Process integration advances are compressing the latency gap between volatile and persistent memory hierarchies, while regulatory chemistry restrictions and hyperscale procurement centralization reshape competitive positioning.
Phase-change memory cells built on interfacial phase-change switching are digitizing the storage hierarchy by enabling direct CPU load/store operations without block-oriented translation layers. Hyperscale operators in Oregon and Virginia are deploying these modules in PCIe Gen5 form factors to support real-time fraud detection pipelines. The architecture is digitizing traditional three-tier storage designs into unified memory pools, collapsing separate DRAM and NAND procurement categories.
REACH authorization requirements for antimony trioxide are forcing reformulation of chalcogenide alloy compositions in European-bound production. Manufacturers must submit substitution plans to ECHA or secure time-limited exemptions for continued use. Module suppliers serving Frankfurt and Dublin data centers are prioritizing tellurium-rich alternatives to preempt authorization denial risks.
Consolidated procurement through cloud provider central sourcing teams is displacing traditional distributor relationships for high-performance SSDs. Direct engagement between memory manufacturers and infrastructure engineering teams at major cloud operators now governs qualification timelines and volume commitments. This concentration is most pronounced in Washington State and Northern Virginia, where co-location density supports dedicated supply agreements bypassing channel intermediaries.
3D Xpoint Technology Market Segmentation
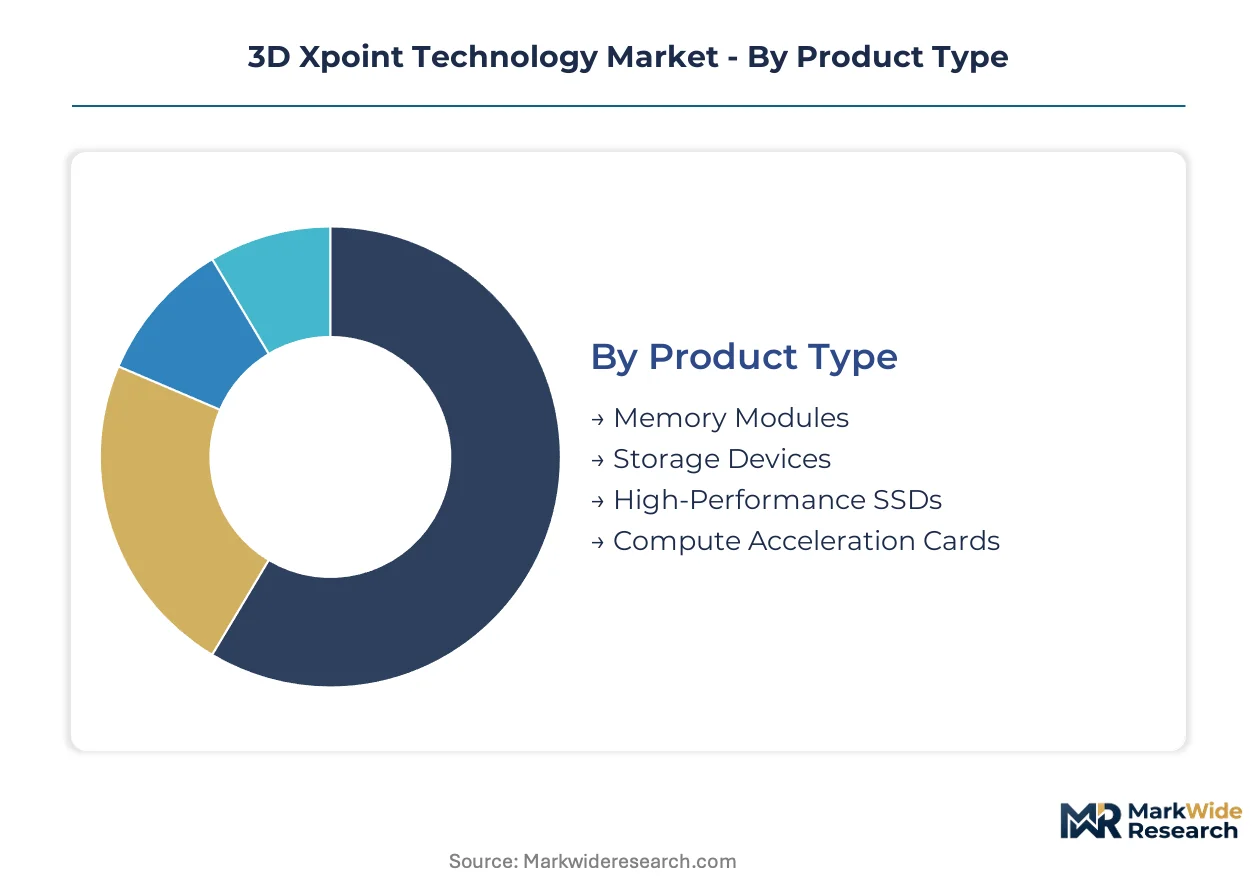
Segmentation in 3D Xpoint technology reveals how chalcogenide-based cell architectures fragment across latency tiers, deployment scales, and integration depths. Each dimension exposes distinct procurement patterns among hyperscale operators, industrial OEMs, and cloud infrastructure architects.
Product Type:
Latency requirements and form factor constraints shape product-level demand across storage-class memory hierarchies.
- Memory Modules:Dual in-line memory modules with bit-addressable persistent memory cells attach directly to CPU memory controllers via standard DIMM slots. Hyperscale data centers in Oregon and Virginia deploy these for in-memory database acceleration, driven by checkpoint elimination in AI training pipelines.
- High-Performance SSDs:PCIe-attached storage devices leverage crosspoint arrays for block-access workloads requiring sub-microsecond latency. Cloud providers specify these for real-time fraud detection systems, constrained by CXL protocol certification timelines.
- Storage Devices:Enterprise storage arrays integrate persistent memory tiers between DRAM and NAND flash.
- Compute Acceleration Cards:FPGA and GPU companion cards embed persistent memory for model parameter caching.
Established volume favors memory modules; emerging adoption favors compute acceleration cards.
End User:
Procurement scale and technical specification authority concentrate differently across buyer archetypes.
- Data Centers:Co-location and hyperscale facilities consolidate storage tiers around persistent memory to collapse separate DRAM and NAND procurement categories. Operators in Northern Virginia negotiate direct supply agreements bypassing channel intermediaries, driven by rack-level consolidation mandates.
- Cloud Providers:Centralized infrastructure engineering teams govern qualification timelines and volume commitments. Washington State-based operators pilot CXL-enabled cache-coherent configurations, constrained by kernel-bypass software stack validation cycles.
- Enterprises:Financial services transaction logging and high-frequency trading platforms specify endurance-optimized cell configurations.
- Industrial Applications:Programmable logic controller manufacturers in Germany pilot embedded persistent memory to eliminate battery-backed SRAM.
Procurement concentration favors data centers; technical customization favors industrial applications.
Technology:
Integration depth and interface standardization create distinct competitive moats across technology layers.
- Non-Volatile Memory:Chalcogenide phase-change cells built on germanium-antimony-tellurium stoichiometry enable bit-addressable persistence without block-oriented translation layers. Intel's captive foundry infrastructure in New Mexico sustains process development, driven by EU F-Gas Regulation compliance requirements for etching chemistry substitution.
- Hybrid Memory:Heterogeneous integration combines persistent memory with conventional DRAM in unified address spaces. Advanced packaging partnerships in South Korea extend reach into multi-die configurations, constrained by atomic layer deposition equipment concentration in Germany and Japan.
- Neuromorphic Computing:Spike-based architectures explore phase-change materials for synaptic emulation.
- Embedded Memory:System-on-chip integration targets edge node consolidation in automotive and industrial controllers.
Manufacturing scale favors non-volatile memory; architectural experimentation favors neuromorphic computing.
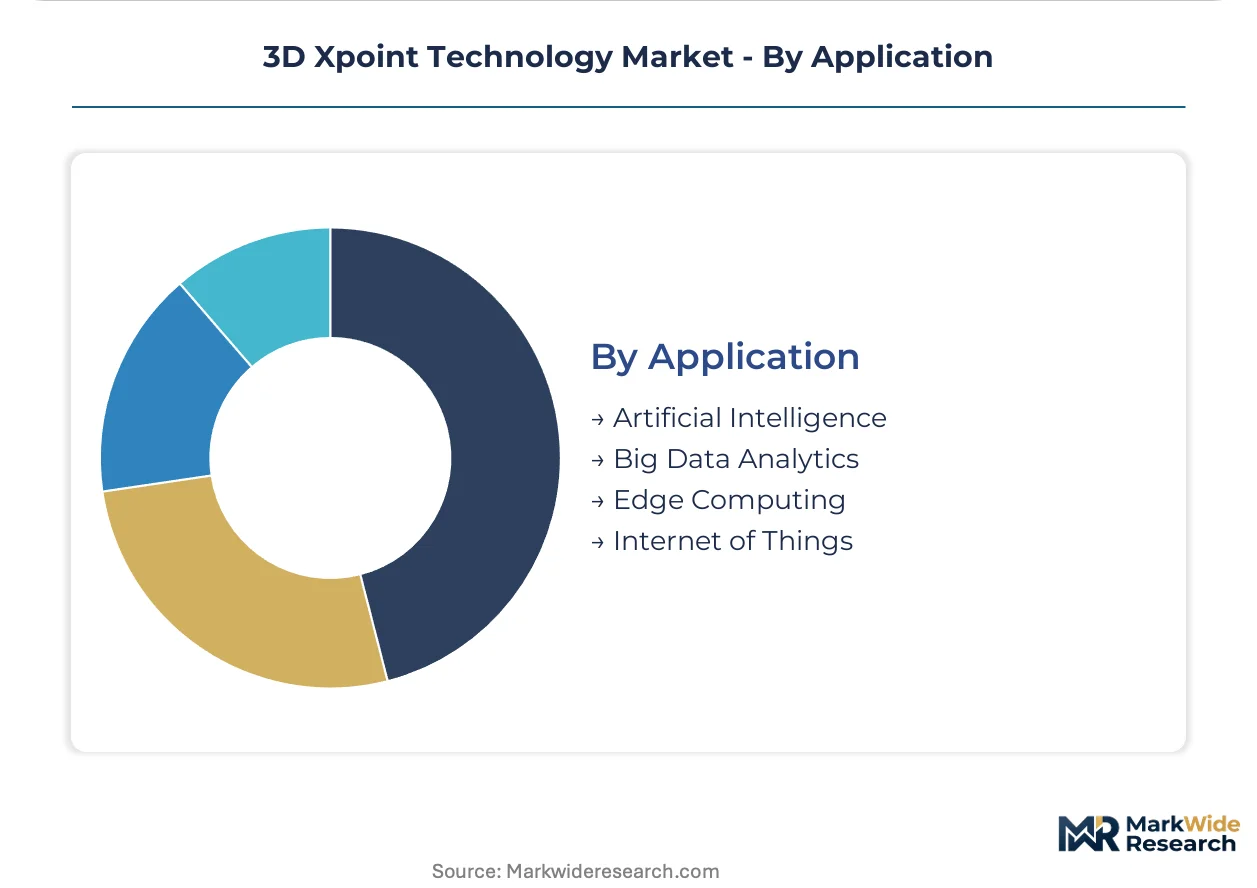
Application:
Workload characteristics and data gravity patterns determine interface requirements and endurance specifications.
- Artificial Intelligence:Large language model training infrastructure requires storage-class memory to eliminate checkpoint serialization bottlenecks. GPU cluster deployments specify PCIe Gen5 form factors, driven by parameter server scaling demands in cloud provider data halls.
- Big Data Analytics:Real-time stream processing pipelines leverage persistent memory for stateful operator recovery. Financial services transaction logging in New York applies endurance-extended cell configurations, constrained by REACH authorization timelines for antimony trioxide alternatives.
- Edge Computing:Distributed inference nodes prioritize form factor and thermal envelope over raw bandwidth.
- Internet of Things:Sensor fusion gateways specify low-capacity embedded configurations for local buffering.
Infrastructure investment favors artificial intelligence; deployment breadth favors edge computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Intel and Micron anchor captive fabrication, while European procurement absorbs carbon-border compliance costs from tightened F-Gas Regulation quotas. The regional asymmetry reflects divergent regulatory stringency and infrastructure density across fabrication corridors.
United States
Hyperscale operators in Northern Virginia and Oregon drive module procurement through direct supply agreements bypassing channel intermediaries. EPA fluorinated gas reporting mandates add compliance overhead to domestic etching processes. Intel's New Mexico fabrication corridors sustain process development for chalcogenide cell architectures.
Germany
Industrial automation OEMs pilot embedded persistent memory to eliminate battery-backed SRAM in programmable logic controllers. REACH authorization requirements for antimony trioxide force reformulation of chalcogenide alloy compositions in European-bound production. Frankfurt data centers prioritize tellurium-rich alternatives to preempt regulatory denial risks.
China
MIIT dual carbon goals and domestic semiconductor self-sufficiency programs accelerate captive foundry investments in memory fabrication. SAMR market concentration reviews shape partnership structures for advanced packaging capabilities. Yangtze River Delta clusters concentrate atomic layer deposition equipment utilization for crosspoint array development.
South Korea
Advanced packaging partnerships extend reach into hybrid memory configurations serving AI training infrastructure buildouts. METI-aligned export control frameworks influence equipment sourcing strategies for deposition tools. Seoul Capital Area facilities dominate multi-die integration expertise for heterogeneous memory architectures.
India
The PLI scheme for semiconductors offers capital expenditure support for domestic memory packaging and testing facilities attracting module assembly relocation. BIS certification timelines govern qualification cycles for storage-class memory imports. Karnataka and Telangana clusters emerge as preferred locations for backend integration investments.
3D Xpoint Technology Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling materials and process IP. The structure consolidates around captive foundry operators with backward integration into chalcogenide sourcing and independent module assemblers dependent on external wafer supply. Three archetypes dominate: IDM operators with in-house fabrication, fabless designers licensing cell architectures, and pure-play packagers serving modular form factors. Competitive moves concentrate on strategic partnerships for advanced packaging and geographic relocation of backend operations to jurisdictions with incentive-aligned regulatory frameworks.
Among IDM operators with captive fabrication infrastructure, Intel Corporation exemplifies the integrated archetype through its New Mexico-based process development corridors. Micron Technology anchors the materials-integrated tier with Idaho-based R&D clusters controlling upstream chalcogenide supply chains. Samsung Electronics occupies a position spanning both fabrication scale and advanced packaging partnerships for heterogeneous memory configurations.
| Leading Market Players |
|---|
| Intel Corporation |
| Micron Technology |
| Samsung Electronics |
| Western Digital Corporation |
| SK Hynix |
| Toshiba Corporation |
| IM Flash Technologies |
| SanDisk Corporation |
| Kingston Technology Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in atomic layer deposition tooling across Germany and Japan compresses lead times for crosspoint array fabrication, forcing memory manufacturers to absorb premium equipment leasing rates while passing selective cost escalations to hyperscale buyers with locked-in volume commitments.
Pricing Analysis
Configured-to-order memory modules for AI training clusters command substantial premiums over standard PCIe Gen5 SSDs due to kernel-bypass software certification requirements and CXL protocol validation cycles. Pricing stratifies across endurance-optimized, latency-critical, and commodity storage tiers, with hyperscale cloud providers in Washington State and Northern Virginia exhibiting lowest price sensitivity due to direct supply agreements, while industrial automation OEMs in Germany face acute margin pressure from REACH-driven antimony trioxide substitution costs.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates risk for etching equipment components and chalcogenide raw material flows. Supply draws from captive foundry infrastructure in New Mexico and Idaho, advanced packaging partnerships in South Korea, and atomic layer deposition tool sourcing from Germany and Japan. Germanium-antimony-tellurium stoichiometry and fluorinated gas chemistries constitute critical input dependencies. Distribution runs through direct manufacturer-to-cloud-provider agreements that displace traditional channel intermediaries in hyperscale procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated around hyperscale cloud infrastructure teams in Northern Virginia and Washington State, consolidating procurement authority through direct supply agreements that bypass distributor relationships and compress qualification timelines for emerging memory architectures.
For Market Incumbents: Pre-empt neuromorphic computing displacement by accelerating CXL-enabled cache-coherent controller development before fabrication scale economics mature. Defend position through backward integration into tellurium-rich chalcogenide sourcing to neutralize REACH authorization risks for antimony trioxide. Prioritize captive foundry capacity additions in New Mexico corridors to sustain process development without full equipment ownership burdens.
For New Entrants and Emerging Players: Pursue embedded persistent memory configurations for industrial automation OEMs in Germany, where battery-backed SRAM elimination creates immediate substitution openings with lower certification barriers than hyperscale cloud qualification. Target India's PLI scheme for semiconductor packaging and testing facilities to capture module assembly relocation incentives. Lead with edge computing node consolidation narratives rather than AI training infrastructure head-to-head competition.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU F-Gas Regulation phase-down and EPA fluorinated gas reporting create asymmetric compliance costs that favor first-movers with advanced process engineering capabilities. Acquisition targets should concentrate on atomic layer deposition expertise holders and chalcogenide thin-film sputtering specialists. Monitor whether Compute Express Link protocol adoption rates outpace storage-class memory controller availability as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU F-Gas Alternative Chemistry Qualification | First-mover manufacturers in New Mexico corridors capture permanent cost advantages over laggards facing carbon-border adjustments. |
| CXL Protocol Controller Development | Cache-coherent sharing across processor sockets unlocks multi-tenant cloud database architectures for hyperscale operators in Virginia. |
| India PLI Scheme Facility Relocation | Backend packaging and testing investments in Karnataka clusters reduce exposure to US-China tariff friction on module assembly. |
| Tellurium-Rich Chalcogenide Reformulation | REACH authorization preemption for Frankfurt and Dublin data center shipments eliminates time-limited exemption uncertainty. |
| Direct Cloud Provider Supply Agreements | Bypassing channel intermediaries in Washington State procurement corridors compresses margin leakage and accelerates qualification cycles. |
Methodological Framework
A spread of perspectives from hyperscale infrastructure engineering directors, memory module procurement leads at cloud providers, atomic layer deposition equipment specialists, chalcogenide materials sourcing managers, and industrial automation OEM technical architects converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EPA fluorinated gas emission disclosures, EU ECHA REACH authorization databases, and hyperscaler capital expenditure disclosures. Bottom-up wafer supply estimates and top-down storage-class memory demand projections were triangulated to anchor volume assumptions.
Demand-supply balance dynamics across the analysis window shaped the forecast framework, with segmentation modeled by product type, end user archetype, integration technology depth, and application workload characteristics. CAGRs were derived from fitted growth curves applied to bit-addressable persistent memory deployment trajectories in AI training infrastructure, with cross-validation against DRAM price elasticity parameters and NAND flash substitution thresholds. Industry-specific inputs included chalcogenide cell endurance benchmarks and CXL protocol certification timeline assumptions.
Sensitivities concentrate around neuromorphic computing architecture maturation, EU F-Gas Regulation quota tightening schedules, and EPA reporting requirement stringency adjustments. Forecasts reflect documented assumptions on hyperscale procurement concentration and deposition equipment utilization rates. Material shifts in chalcogenide thin-film deposition expertise distribution or REACH authorization denial patterns for antimony trioxide would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Global Nano Batteries Market