
 In-Mold Electronics (IME) Market | 2026-2036
In-Mold Electronics (IME) Market Size, Share, and Industry Trends Forecast 2026-2036
In-Mold Electronics (IME) Market Foresight
Tier-one automotive supply channels is reconfiguring as OEMs consolidate electronic component procurement around single-source IME integrators capable of delivering finished human-machine interface assemblies. DuPont leverages its materials science portfolio to dominate high-temperature conductive ink formulations for in-mold applications. TactoTek anchors Nordic design-to-manufacture capabilities, competing directly with Nissha Co., Ltd. for automotive interior programs requiring three-dimensional touch surfaces.
In-mold electronics fuses printed conductive traces, electronic components, and decorative films into thermoformed plastic parts through injection molding, typically achieving circuit layer thicknesses below 200 micrometers while maintaining functional reliability across automotive temperature ranges. The technology eliminates separate circuit boards and wiring harnesses, reducing assembly steps and enabling seamless, curved user interfaces. Automotive Panels within the Product Type dimension commands the dominant margin pool as OEMs specify IME for center stack and steering wheel controls, while Smart Packaging under Application grows fastest as brand owners adopt interactive product authentication and consumer engagement features. Conductive Inks within Technology leads volume consumption due to its foundational role across all IME architectures.
FDA scrutiny of medical device interfaces is elevating cleanliness and biocompatibility standards for IME deployed in Healthcare Sector applications, while EPA and REACH frameworks govern the chemical composition of conductive inks and substrate adhesives. NHTSA human-factors guidelines for driver distraction are reshaping Automotive Industry specifications for haptic feedback and touch-response latency in IME-based controls. Stakeholders must monitor evolving automotive safety standards and medical device electromagnetic compatibility requirements to sustain market access across regulated end-use segments.
Market Dynamics
Automotive OEM procurement consolidation around single-source IME integrators is restructuring competitive boundaries, as weight reduction mandates and curved interface specifications eliminate multi-vendor assembly models.
Growth Catalysts
- EU Green Deal recyclability mandates:Suppliers are reformulating conductive inks and substrate materials to meet circular economy requirements, accelerating material innovation cycles.
- Capacitive touch-enabled dashboard panels:German and US automotive interior manufacturers are expanding procurement volumes as OEMs consolidate electronic functions into thermoformed surfaces.
- East Asian electronics integration:South Korean and Japanese integrators are scaling production capacity for next-generation consumer devices and vehicle human-machine interfaces.
Market Restraints
- Silver flake conductive ink cost volatility:Precious metal price swings compress margin stability for ink formulators serving high-volume automotive programs.
- Specialized thermoforming equipment concentration:Precision molding system suppliers cluster in Germany and Japan, creating geographic supply risk for new market entrants.
- REACH chemical compliance friction:ECHA substance restrictions on specific adhesive chemistries extend qualification timelines for European automotive qualifications.
Strategic Opportunities
- Smart packaging authentication:Brand owners in cosmetics and pharmaceuticals are adopting interactive IME surfaces for consumer engagement and anti-counterfeiting verification.
- Healthcare device interfaces:FDA biocompatibility pathways for medical-grade IME create premium positioning for suppliers mastering cleanliness protocols.
- 5G antenna integration:Convergence of printed electronics with thermoformed structural components enables embedded connectivity in automotive and consumer enclosures.
Industry Challenges
- Multi-physics simulation expertise scarcity:IME design requires simultaneous optimization of thermal, electrical, and mechanical performance across injection molding cycles.
- NHTSA human-factors certification timelines:Driver distraction testing for haptic feedback latency extends automotive program validation by 8-14 months.
- Legacy PCB supply chain displacement:Traditional circuit board manufacturers are defending position through price aggression, complicating IME volume ramp economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Mold Electronics (IME) Market |
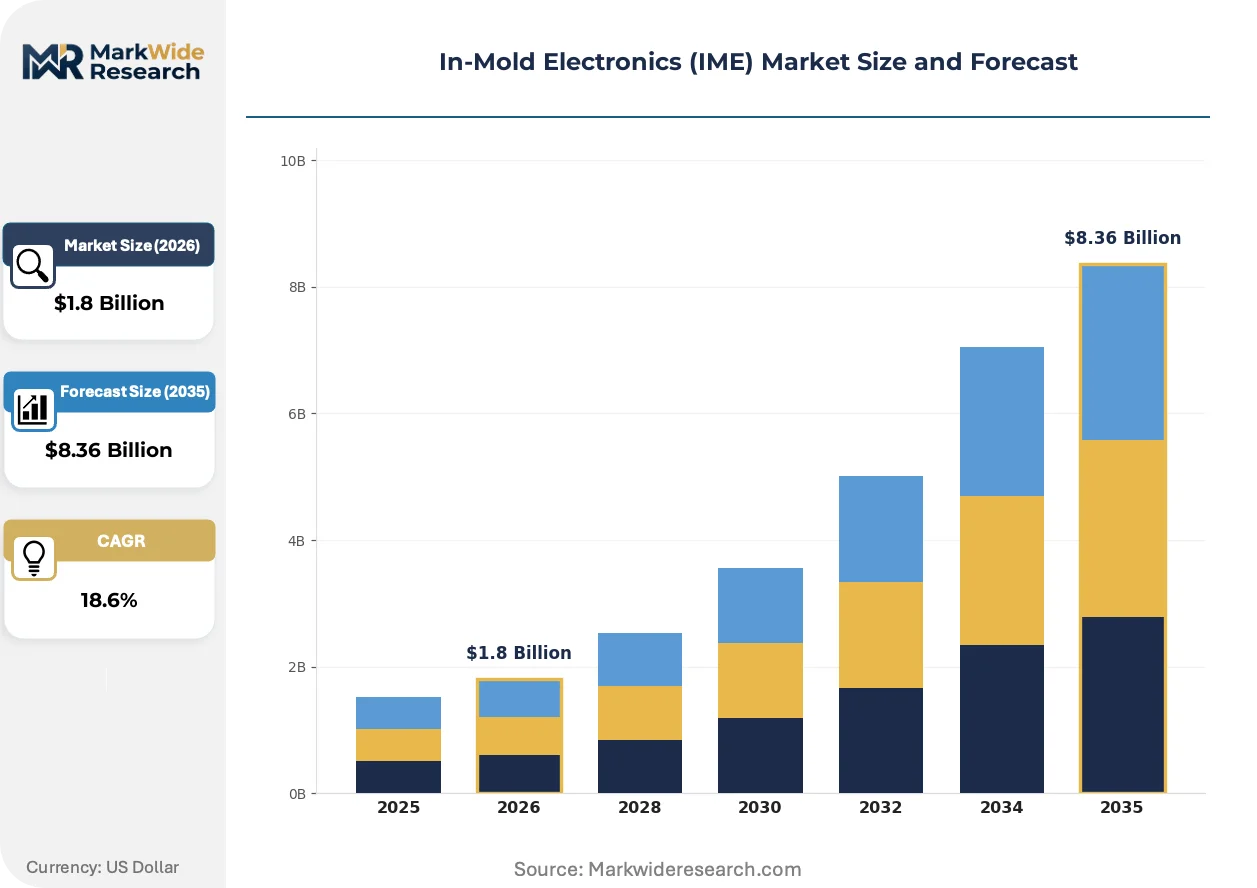
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphone Cases, Automotive Panels, Medical Devices, Wearable Technology End User: Consumer Electronics, Automotive Industry, Healthcare Sector, Industrial Applications Technology: Conductive Inks, Flexible Circuits, Capacitive Touch Sensors, 3D Printing Application: Smart Packaging, Interactive Displays, Custom Controls, User Interfaces |
| Companies Covered | CERADROP, GenesInk, DuPont, TEKRA, LLC., Nissha Co., Ltd., TactoTek, Eastprint Incorporated, Molex, Butler Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Mold Electronics (IME) Market Shifts & Advancements
Printed electronics manufacturing is converging with structural thermoforming, collapsing traditional boundaries between decorative surfaces and functional circuitry. Three developments are compressing design-to-production cycles.
Film-insert molding with embedded printed silver traces is collapsing the distinction between circuit carriers and cosmetic finishes. Automotive interior suppliers in Stuttgart and Detroit are qualifying three-dimensional touch surfaces for center stack applications. This integration eliminates separate wiring harnesses and enables seamless curved geometries previously requiring mechanical assemblies.
REACH substance restrictions and EPA chemical reporting requirements are elevating formulation transparency demands. Conductive ink suppliers must now document full material composition across supply tiers. Medical device and automotive segments are responding by qualifying alternative metal-based and carbon-based conductive systems with cleaner toxicological profiles.
Automotive OEMs are consolidating electronic component procurement around finished human-machine interface assemblies rather than discrete parts. Tier-one suppliers in Bavaria and Michigan are absorbing printed electronics capabilities in-house or through exclusive partnerships. This concentration is most visible in steering wheel control and dashboard programs where single-source accountability reduces warranty exposure.
In-Mold Electronics (IME) Market Segmentation
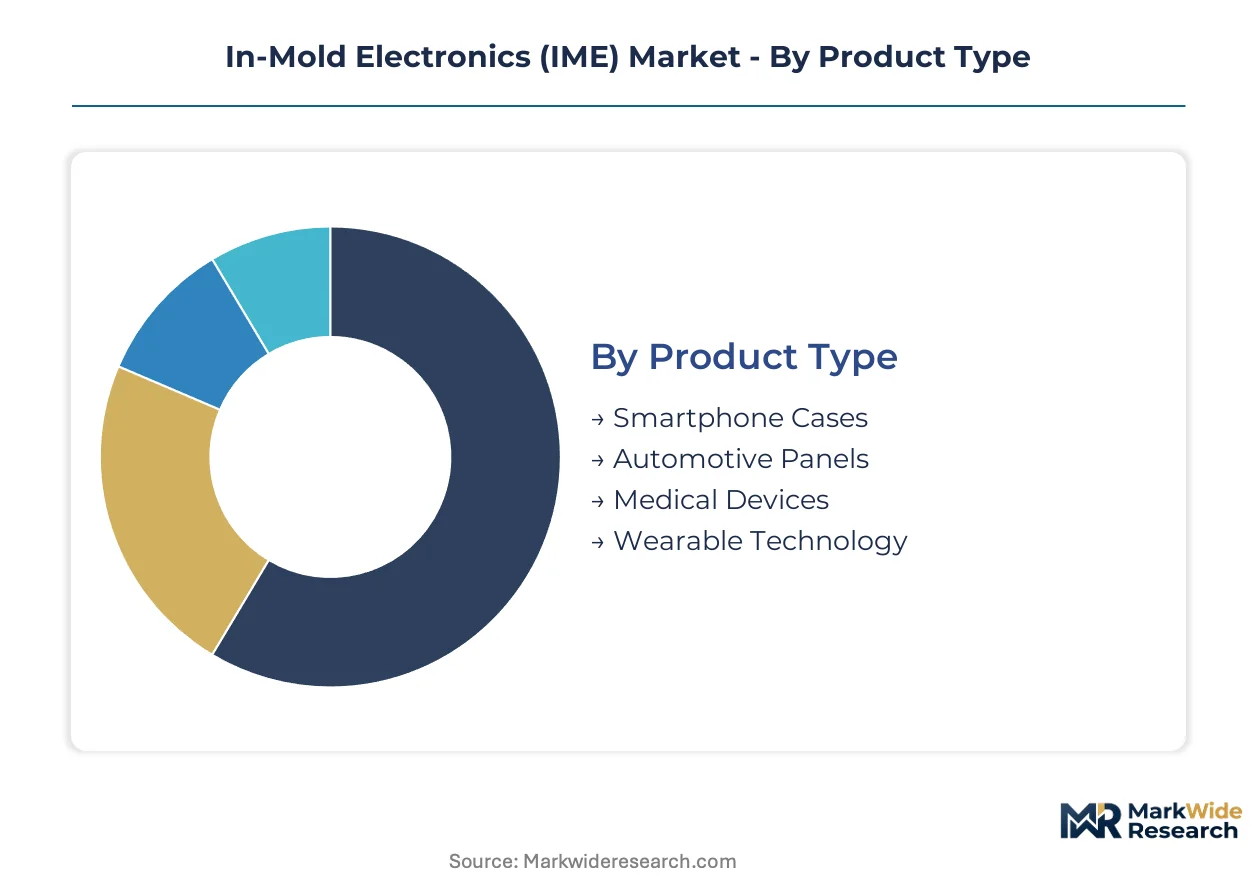
IME segmentation reflects divergent qualification timelines across end-use sectors, with automotive programs demanding 18-24 month validation cycles while consumer electronics refresh annually. Understanding these velocity differences enables suppliers to calibrate R&D resource allocation and inventory positioning.
Product Type:
Automotive Panels turn over slowest due to OEM validation rigor, while Smartphone Cases cycle fastest alongside annual device launches.
- Automotive Panels:Thermoformed dashboard and center stack assemblies integrate capacitive touch layers below 200 micrometers thickness. German and US interior manufacturers are expanding procurement as weight reduction mandates consolidate electronic functions into curved surfaces.
- Smartphone Cases:Printed antenna and touch-sensing circuits embed directly into injection-molded protective enclosures. South Korean electronics integrators are scaling production capacity for next-generation flagship devices requiring seamless three-dimensional interfaces.
- Medical Devices:FDA biocompatibility requirements govern interface cleanliness for surgical and diagnostic equipment.
- Wearable Technology:Fitness bands and smartwatch housings incorporate haptic feedback and biometric sensing.
Automotive Panels anchors the volume base while Smartphone Cases gains share at the steepest rate.
End User:
Cost tier stratification separates premium medical-grade qualification from high-volume consumer electronics manufacturing.
- Automotive Industry:NHTSA human-factors guidelines govern haptic feedback latency and driver distraction metrics for steering wheel and dashboard controls. Tier-one suppliers in Bavaria and Michigan are absorbing printed electronics capabilities to deliver finished human-machine interface assemblies.
- Healthcare Sector:FDA electromagnetic compatibility and cleanliness protocols elevate manufacturing standards for surgical and diagnostic interfaces. Suppliers mastering biocompatibility pathways command premium positioning against commodity electronics manufacturers.
- Consumer Electronics:Brand owners in cosmetics and pharmaceuticals are adopting interactive surfaces for product authentication.
- Industrial Applications:Harsh-environment controls for manufacturing equipment demand extended temperature range reliability.
Automotive Industry commands the largest revenue pool while Healthcare Sector delivers the highest margin per unit.
Technology:
Material cost concentration varies sharply, with silver-based Conductive Inks exposed to precious metal volatility versus polymer-dominant Flexible Circuits.
- Conductive Inks:Silver flake formulations provide foundational conductivity across all IME architectures. ECHA substance restrictions and EPA chemical reporting requirements are pushing suppliers to document full material composition and qualify alternative metal-based and carbon-based systems.
- Flexible Circuits:Polyimide and polyester substrates enable dynamic bending in wearable and medical applications. Japanese precision molding system suppliers cluster around this technology, creating geographic supply risk for new market entrants.
- Capacitive Touch Sensors:Transparent conductive oxide layers enable seamless user interface detection.
- 3D Printing:Additive manufacturing supports prototyping and low-volume customization for medical device programs.
Conductive Inks anchors the volume base while Flexible Circuits expands most quickly in medical and wearable segments.
Application:
Customer type fragmentation separates automotive OEM specification from brand-owner direct procurement in packaging and consumer goods.
- Smart Packaging:Interactive product surfaces enable consumer engagement and anti-counterfeiting verification for cosmetics and pharmaceuticals. EU Green Deal recyclability mandates are accelerating material innovation cycles for substrate and adhesive reformulation.
- User Interfaces:Consolidated electronic component procurement around finished assemblies reduces warranty exposure for automotive OEMs. REACH chemical compliance friction extends qualification timelines for European automotive programs requiring specific adhesive chemistries.
- Interactive Displays:Curved and seamless screen enclosures eliminate visible circuit boundaries.
- Custom Controls:Specialized industrial and medical equipment interfaces demand application-specific form factors.
User Interfaces anchors the volume base while Smart Packaging climbs the fastest as brand owners adopt authentication features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's position as the primary European gateway for IME substrate materials and precision molding equipment. Rail links from Stuttgart to Bavaria distribute conductive inks and thermoformed components to automotive interior clusters across Central Europe.
United States
Detroit-area OEMs specify capacitive touch-enabled dashboard panels for weight reduction programs. NHTSA human-factors guidelines govern haptic feedback latency in steering wheel controls. Michigan and Bavaria-based tier-one suppliers are absorbing printed electronics capabilities to deliver finished assemblies.
Germany
Stuttgart's automotive interior manufacturers expand procurement of three-dimensional touch surfaces for center stack applications. EU Green Deal recyclability mandates push suppliers to reformulate conductive inks and substrate materials. Precision molding system suppliers cluster in Bavaria and Baden-Württemberg, creating concentrated equipment access.
South Korea
Seoul Capital Area electronics integrators scale IME production for next-generation consumer devices and vehicle interfaces. The country's national industrial regulator enforces chemical reporting requirements for adhesive formulations. Busan-Ulsan manufacturing corridors host expanding capacity for smartphone case and wearable technology programs.
Japan
Nagoya-area precision molding specialists supply thermoforming equipment critical to IME circuit layer formation. METI standards govern material composition documentation across supply tiers. Osaka-based electronics manufacturers qualify alternative metal-based conductive systems for cleaner toxicological profiles.
China
Yangtze River Delta electronics manufacturers integrate printed antenna and touch-sensing circuits into injection-molded enclosures. Dual carbon goals accelerate substrate material innovation cycles. Shenzhen and Dongguan clusters concentrate prototyping capacity for annual consumer device refresh schedules.
In-Mold Electronics (IME) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying conductive inks, substrates, and precision equipment. The vendor base organizes around three strategic archetypes: materials science conglomerates controlling high-temperature ink formulations, design-to-manufacture integrators delivering finished assemblies, and precision equipment fabricators supplying thermoforming systems. Dominant competitive moves include exclusive partnership structures between ink formulators and automotive tier-ones, plus geographic expansion of molding equipment service networks.
Among materials-focused players, DuPont anchors the high-temperature conductive ink segment. TactoTek occupies a position within the Nordic design-to-manufacture tier, while Nissha Co., Ltd. represents Japanese precision integration capabilities. These three exemplify how competitive boundaries are restructuring as OEM procurement consolidates around single-source accountability.
| Leading Market Players |
|---|
| CERADROP |
| GenesInk |
| DuPont |
| TEKRA, LLC. |
| Nissha Co., Ltd. |
| TactoTek |
| Eastprint Incorporated |
| Molex |
| Butler Technologies |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese precision thermoforming equipment constrains global IME expansion, forcing automotive tier-ones into long-term offtake commitments that lock in pricing premiums while squeezing margin flexibility for new ink formulators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade qualified formulations from consumer electronics commodity inks and medical-device biocompatible systems. Price differentiation hinges on ECHA REACH compliance documentation and NHTSA human-factors certification status. Cost compression in consumer electronics tiers is intensifying because South Korean integrators are consolidating procurement around single-source IME partners. Automotive OEMs exhibit lowest price sensitivity due to warranty exposure and 18-24 month validation timelines, while smart packaging brand owners drive hardest bargain negotiations.
Supply Chain Analysis
Contract manufacturing concentration sits with Bavarian automotive interior specialists and Busan-Ulsan electronics integrators, with Nagoya-area equipment fabricators anchoring upstream capacity. Geographic supply concentration clusters in Germany, South Korea, and Japan for finished assemblies, while silver flake and polyimide substrates draw from established chemical processing corridors. Single-source vulnerability permeates high-temperature conductive ink formulation, where DuPont's materials science portfolio dominates qualified automotive programs. Distribution runs through exclusive partnerships between ink formulators and tier-one suppliers rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-physics simulation expertise scarcity defines competitive moats in this market, as OEMs consolidate procurement around integrators capable of simultaneous thermal-electrical-mechanical optimization across injection molding cycles.
For Market Incumbents: Harden defensible positions by acquiring captive thermoforming equipment service networks in Stuttgart and Detroit corridors, and deepen backward integration into conductive ink formulation to offset silver price volatility. Legacy PCB manufacturers are defending position through price aggression in consumer electronics tiers, making certification investment in NHTSA human-factors pathways the critical margin protection lever. For New Entrants and Emerging Players: Build out prototyping capacity in Shenzhen-Dongguan clusters to serve annual consumer device refresh schedules, then migrate toward automotive qualification through exclusive partnerships with Bavarian tier-ones seeking second-source IME integrators. Smart packaging authentication represents the most penetrable application, with cosmetics and pharmaceutical brand owners adopting interactive surfaces for anti-counterfeiting verification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among design-to-manufacture integrators delivering finished human-machine interface assemblies under multi-year automotive programs. Long-term viability across the analysis window favors acquisition targets with mastered FDA biocompatibility pathways and established ECHA REACH documentation systems. Monitor NHTSA driver distraction guideline revisions as the critical inflection signal for haptic feedback latency requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Ink Formulation | DuPont leverages materials science portfolio to dominate high-temperature automotive qualifications. |
| Exclusive Partnership with Tier-One Automotive Suppliers | TactoTek anchors Nordic design-to-manufacture capabilities competing with Nissha for interior programs. |
| FDA Biocompatibility Pathway Investment | Medical-grade IME suppliers command premium positioning against commodity electronics manufacturers. |
| Smart Packaging Authentication Platform Launch | Cosmetics and pharmaceutical brand owners adopt interactive surfaces for consumer engagement. |
| 5G Antenna Integration Capability Buildout | Printed electronics convergence enables embedded connectivity in automotive and consumer enclosures. |
Research Methodology
Operator-level perspectives from automotive platform engineers, tier-one procurement directors, conductive ink formulators, and precision molding equipment specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, ECHA substance restriction databases, NHTSA human-factors guidelines, and automotive production registration data. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates across product type, end user, technology, and application dimensions.
Scenario-bracketing around EU Green Deal recyclability mandates, silver price volatility bands, and NHTSA certification timeline variations framed the analytical envelope across the projection horizon. Segmentation modeling incorporated automotive validation rigor, consumer electronics refresh velocity, and medical device biocompatibility tiering as industry-specific forecast inputs. CAGRs were derived from installed base penetration curves and replacement cycle analysis rather than extrapolated trend fitting.
Stress conditions across precious metal price swings, REACH substance restriction expansions, and thermoforming equipment lead time extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM procurement consolidation velocity and single-source integrator qualification timelines. Quarterly review of ECHA substance restriction proposals and NHTSA human-factors guideline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market