
 Next Gen TV (ATSC TV) Market | 2026-2036
Next Gen TV (ATSC TV) Market Size, Share, and Industry Trends Forecast 2026-2036
Next Gen TV (ATSC TV) Market Foresight
Broadcast licensing revenue is rewriting profit expectations for television ecosystem participants. Samsung Electronics leverages its display manufacturing scale to control premium panel supply for ATSC 3.0-enabled sets. Sony Corporation anchors its position through broadcast camera and production equipment dominance that feeds content into Next Gen TV pipelines. Sinclair Broadcast Group operates the largest local station portfolio in the United States, giving it outsized influence over ATSC 3.0 rollout timing and coverage maps.
Next Gen TV refers to the ATSC 3.0 broadcast television standard that transmits IP-based signals using OFDM modulation with scalable video coding for resolutions up to 8K, designed to merge over-the-air broadcasting with broadband internet functionality for interactive and personalized viewing experiences. Smart TVs represent the primary hardware category capturing consumer upgrade cycles as households replace legacy sets to access 4K live broadcasts and on-demand streaming through unified interfaces. The application dimension shows streaming and live broadcast converging as broadcasters simulcast traditional channels alongside internet-delivered supplemental content. OLED technology leads premium positioning for Next Gen TV displays while LCD variants sustain volume shipments through cost-sensitive residential and commercial deployments.
The Federal Communications Commission governs spectrum allocation and broadcaster transition timelines in the United States, while South Korea's Ministry of Science and ICT previously managed its national ATSC 3.0 deployment framework. The Consumer Technology Association coordinates industry interoperability testing that shapes manufacturer compliance burdens and retail readiness. Stakeholders must monitor FCC repack proceedings and broadcaster capital commitment schedules to anticipate hardware demand inflection points and infrastructure investment windows.
Market Dynamics
The transition from MPEG-2 to HEVC video compression is forcing broadcasters to replace headend equipment and consumer households to upgrade receiving hardware, creating synchronized infrastructure and retail demand cycles that lock in multi-year capital commitments.
Growth Catalysts
- FCC spectrum repack mandates:The Federal Communications Commission's channel reallocation deadlines compress broadcaster upgrade timelines, accelerating transmitter and antenna procurement cycles.
- ATSC 3.0 emergency alert capabilities:The advanced alerting functionality embedded in the standard creates public safety procurement pull from state and municipal emergency management agencies.
- South Korea's nationwide deployment:The completed national rollout provides proven reference architectures that reduce technical risk for North American operators evaluating similar scale investments.
Market Restraints
- Silicon tuner supply concentration:Advanced OFDM demodulator production concentrates among a limited set of semiconductor foundries, creating vulnerability to capacity constraints.
- Dual-illumination infrastructure costs:Broadcasters must maintain simultaneous ATSC 1.0 and 3.0 transmission during transition periods, doubling energy and site lease expenditures.
- Mobile broadband substitution:Unlimited cellular data plans and 5G broadcast services reduce the perceived value proposition of over-the-air reception for younger demographics.
Strategic Opportunities
- Targeted advertising enablement:The IP-based architecture permits addressable ad insertion that legacy broadcast cannot support, opening new revenue streams for local stations.
- Automotive receiver integration:Connected vehicle platforms present an underpenetrated hardware category for ATSC 3.0 chipsets, with infotainment systems serving as the primary integration point.
- Consumer Technology Association certification programs:The interoperability testing framework reduces manufacturer compliance friction and accelerates retail channel readiness.
Industry Challenges
- Broadcast engineer skill gaps:The shift from RF-centric to IP-centric transmission architectures demands networking expertise that traditional television engineering teams often lack.
- Consumer education complexity:Households struggle to distinguish ATSC 3.0-ready sets from 4K displays lacking tuners, complicating retail messaging and return rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Gen TV (ATSC TV) Market |
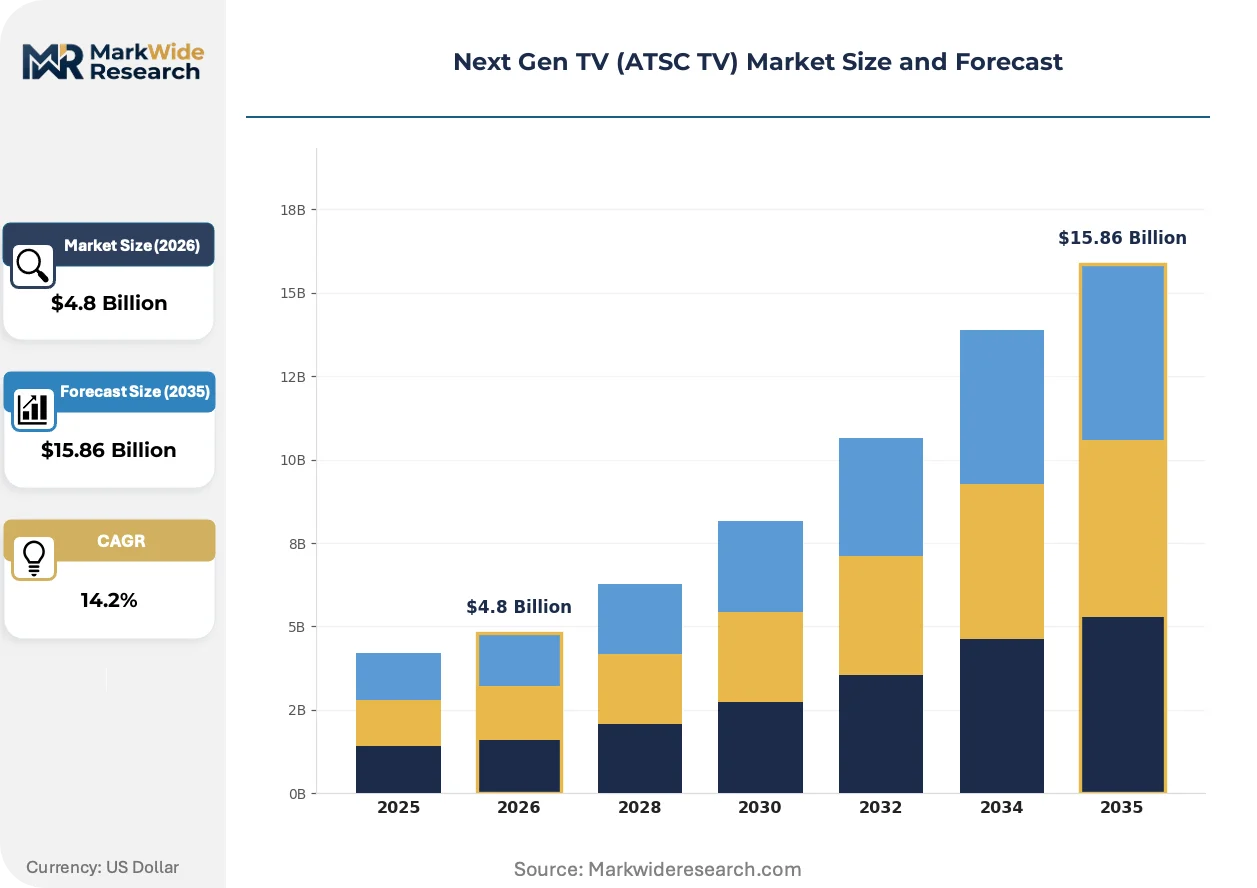
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panels, Smart TVs, Projectors, Set-Top Boxes Technology: OLED, QLED, LCD, LED End User: Residential, Commercial, Educational, Hospitality Application: Streaming, Live Broadcast, Gaming, Interactive Services |
| Companies Covered | Samsung Electronics, Sony Corporation, LG Electronics, TCL Corporation, Hisense Group, Panasonic Corporation, NBCUniversal, Sinclair Broadcast Group, Fox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Gen TV (ATSC TV) Market Shifts & Advancements
Scalable video coding and hybrid broadcast-broadband integration are collapsing the historical separation between linear and on-demand consumption, forcing content distributors to unify technical architectures.
Higher Efficiency Video Coding (HEVC) replaces MPEG-2 as the mandatory compression standard for 4K and 8K transmission, reducing bandwidth requirements by roughly half for equivalent image quality. Broadcast equipment vendors and smart TV manufacturers have aligned procurement roadmaps around this codec transition. The legacy MPEG-2 hardware installed base is rendering obsolete across headend and consumer receiver categories.
The Federal Communications Commission's 2023 framework for broadcaster voluntary transition permits market-driven rather than mandated rollout pacing, creating uneven geographic coverage that fragments national advertising markets. Stations in designated markets face compressed capital planning horizons as competitors activate 3.0 services. Large metropolitan areas with consolidated ownership structures are responding fastest due to coordinated spectrum and tower access.
Households increasingly expect unified content discovery across over-the-air and streaming sources, pressuring electronics manufacturers to integrate channel guides that blend IP-delivered and broadcast programming without mode switching. Retail purchasers now evaluate tuner capabilities alongside streaming app portfolios during replacement cycles. This behavior shift is most pronounced in suburban markets where antenna reception supplements rather than replaces subscription services.
Next Gen TV (ATSC TV) Market Segmentation
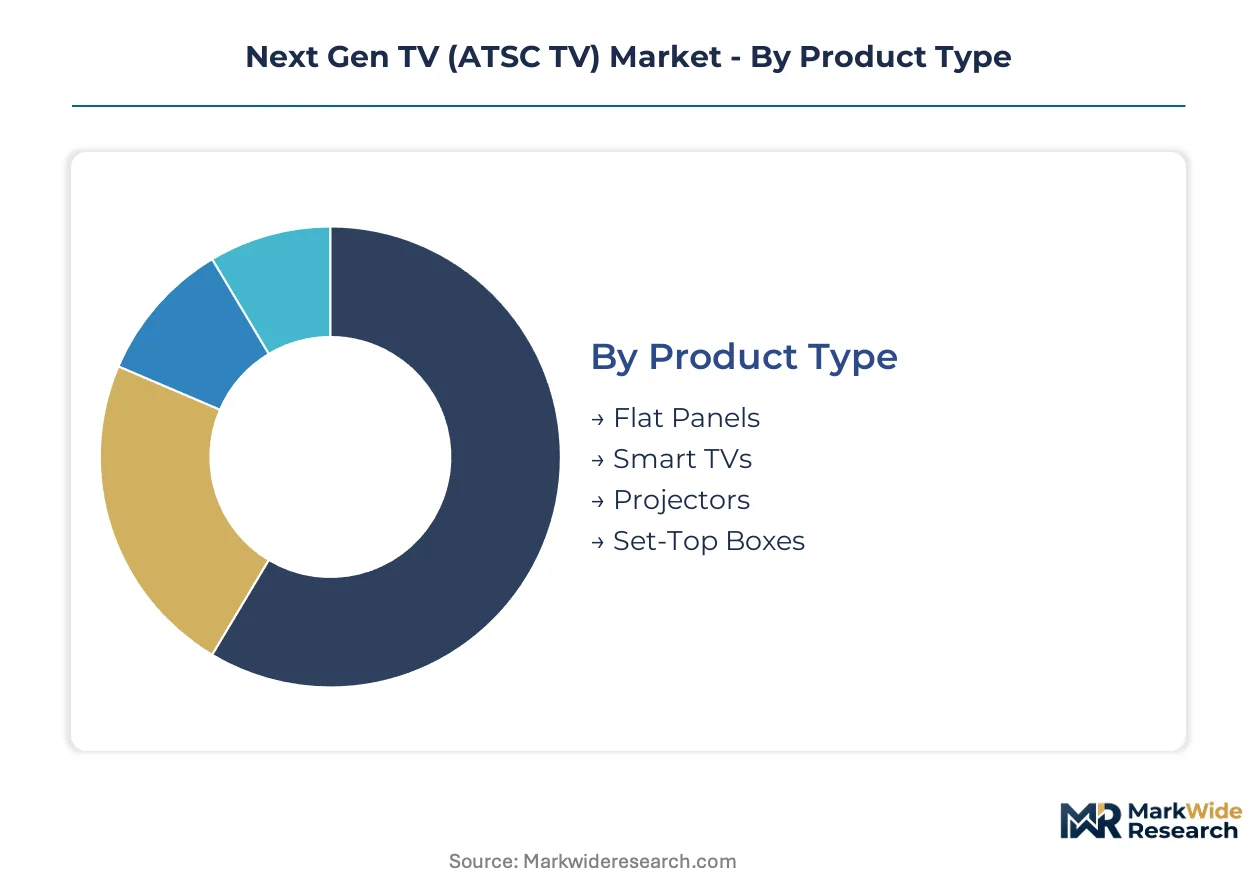
Next Gen TV market segmentation reveals divergent replacement cycles across hardware categories, with consumer displays turning over every 7-10 years while infrastructure equipment spans 15-20 year depreciation schedules. Understanding these temporal patterns helps suppliers align inventory builds with broadcaster capital commitment windows and retail demand spikes.
Product Type:
Cycle times range from 3-5 years for set-top boxes to 10-15 years for projection systems, creating asynchronous demand pulses that complicate manufacturer capacity planning.
- Flat Panels:LCD and OLED display modules dominate unit shipments, with ATSC 3.0 tuner integration now standard in 55-inch and larger SKUs. Residential upgrade cycles in suburban markets drive replacement demand as households seek unified streaming and broadcast interfaces.
- Smart TVs:Integrated operating systems with IP-based ATSC 3.0 receivers eliminate external tuner requirements. South Korean manufacturers leverage vertical display supply chains to control premium panel allocation for 4K and 8K models.
- Projectors:Commercial cinema and large-venue installations sustain niche demand with extended replacement timelines.
- Set-Top Boxes:External tuner solutions bridge legacy displays during transition periods, with faster obsolescence as smart TV penetration climbs.
Flat Panels anchors the volume base while Smart TVs gains share at the steepest rate.
Technology:
Cost tiers separate premium self-emissive displays from volume backlit LCD variants, with manufacturing scale determining competitive positioning across price bands.
- OLED:Organic electroluminescent layers enable per-pixel dimming and infinite contrast ratios for premium positioning. South Korean and Japanese display makers control vapor deposition equipment supply, constraining capacity expansion for large-format panels.
- QLED:Quantum dot enhancement layers boost LCD color gamut without abandoning mature manufacturing infrastructure. Samsung Electronics has scaled QD-OLED hybrid architectures to defend margin position against pure OLED rivals.
- LCD:Edge-lit and direct-lit configurations sustain mid-market volume through cost-optimized Chinese manufacturing.
- LED:Direct-view microLED and miniLED背光 variants command ultra-premium pricing for commercial and luxury residential installations.
LCD sustains the shipment base while OLED climbs the fastest among premium tiers.
End User:
Customer type determines procurement sophistication, with commercial buyers negotiating enterprise service agreements unavailable to residential purchasers.
- Residential:Individual households drive replacement cycles through retail channels, with antenna reception supplementing streaming subscriptions in cost-sensitive demographics.
- Commercial:Corporate campuses and digital signage networks prioritize 24/7 durability ratings and centralized device management platforms.
- Educational:K-12 and university procurement follows E-Rate funding cycles and district-wide standardization mandates.
- Hospitality:Hotel chains require hospitality-optimized remote controls and property management system integration for in-room entertainment.
Residential commands absolute unit volume while Commercial shows the steepest expansion trajectory for ATSC 3.0-enabled displays.
Application:
Use case differentiation is collapsing as hybrid broadcast-broadband architectures unify technical delivery mechanisms.
- Streaming:IP-delivered content now converges with over-the-air signals through ATSC 3.0's broadband return channel. Consumer expectations for seamless app integration pressure electronics manufacturers to unify discovery interfaces.
- Live Broadcast:4K and 8K sports and event coverage drives tuner capability requirements. Sinclair Broadcast Group's ATSC 3.0 rollout timing directly influences regional hardware demand patterns.
- Gaming:Low-latency display modes and variable refresh rate support attract console and PC gaming segments.
- Interactive Services:Targeted advertising and emergency alert functionality leverage the standard's IP backbone for addressable content insertion.
Live Broadcast anchors current infrastructure investment while Streaming reshapes long-term competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in South Korea exhibit the lowest price elasticity for ATSC 3.0 hardware, while cost-sensitive buyers in India and Southeast Asia compress margin structures for entry-tier manufacturers.
United States
Sinclair Broadcast Group's station portfolio drives infrastructure deployment across mid-sized metropolitan areas. The FCC's voluntary transition framework permits uneven geographic pacing that fragments national advertising markets. Dallas-Fort Worth and Atlanta clusters concentrate transmitter manufacturing and broadcast engineering services.
South Korea
Nationwide ATSC 3.0 completion creates reference architectures for equipment validation and export. The Ministry of Science and ICT previously administered spectrum coordination that enabled single-frequency network efficiency. Seoul Capital Area hosts Samsung Electronics and LG Electronics display manufacturing complexes serving premium panel demand.
Japan
Broadcasters evaluate hybrid broadcast-broadband integration for 2024 Olympics content delivery infrastructure. METI coordinates industry interoperability testing that shapes manufacturer compliance schedules. Osaka-Kansai industrial corridor concentrates precision electronics component fabrication for tuner modules.
Germany
Public broadcasters ARD and ZDF pilot ATSC 3.0 reception for automotive infotainment integration. CE marking requirements and RoHS compliance shape import specifications for Asian display manufacturers. Bavaria's Munich-Stuttgart axis anchors broadcast technology R&D clusters.
China
TCL Corporation and Hisense Group leverage domestic LCD manufacturing scale for cost-optimized ATSC 3.0 export models. MIIT spectrum allocation frameworks differ from North American channel plans, requiring tuner hardware variants. Pearl River Delta concentration sustains panel backplane and driver IC fabrication.
Next Gen TV (ATSC TV) Market Competitive Landscape
Capability concentration sits with display technology specialists; scale advantage sits with diversified electronics conglomerates. The market exhibits tiered structure with premium OLED positioning defended by Korean and Japanese manufacturers against Chinese LCD volume competition. Strategic archetypes include vertical display integrators, broadcast infrastructure operators, and semiconductor tuner specialists. Competitive moves center on captive panel supply agreements and transmitter site consolidation.
Among Korean electronics conglomerates, Samsung Electronics and LG Electronics exemplify vertical integration archetypes that control vapor deposition equipment and premium OLED wafer supply. Sony Corporation represents Japanese broadcast equipment heritage that anchors professional camera-to-display workflow positioning. Sinclair Broadcast Group occupies a distinctive infrastructure-operator role through its local station portfolio concentration.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony Corporation |
| LG Electronics |
| TCL Corporation |
| Hisense Group |
| Panasonic Corporation |
| NBCUniversal |
| Sinclair Broadcast Group |
| Fox Corporation |
| Others |
Supply & Pricing Matrix
Long Beach port congestion during peak display panel import seasons amplifies landed cost differentials between Korean and Chinese manufacturers, compressing margins for mid-tier OEMs while reinforcing Samsung Electronics and LG Electronics pricing power through captive transpacific logistics contracts.
Pricing Analysis
Long-term offtake agreements between broadcast equipment vendors and transmitter manufacturers dominate infrastructure procurement, while consumer hardware moves through spot-market spot purchases with quarterly price negotiations. Price differentiation rests on tuner certification tier and panel resolution grade, with ATSC 3.0-certified 8K displays commanding substantial premiums over 4K variants lacking full standard compliance. Cost compression in LCD tiers is intensifying because TCL Corporation and Hisense Group are expanding domestic Chinese fab capacity. Residential buyers in India and Southeast Asia exhibit the highest price sensitivity, while South Korean households show minimal elasticity for premium OLED configurations.
Supply Chain Analysis
Export control regimes limiting advanced lithography equipment shipments to Chinese foundries constrain domestic production of high-performance OFDM demodulator chipsets, forcing mainland manufacturers to source from Taiwanese and South Korean semiconductor vendors. Geographic supply concentration centers on South Korea for OLED vapor deposition equipment, Taiwan for tuner module ASICs, and China for LCD backplane glass. Raw material dependencies include indium tin oxide for transparent electrodes, gallium nitride for RF amplification, and high-purity silicon for tuner substrates. Single-source vulnerability pervades advanced OFDM demodulator production. Distribution runs through electronics retail chains and direct OEM procurement for broadcaster infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATSC 3.0 deployment timelines hinge on broadcast engineering talent pools that remain shallow outside South Korea and select US metropolitan clusters, creating execution bottlenecks that separate capable integrators from aspirants.
For Market Incumbents: Harden transmitter site portfolios through tower lease consolidation in designated market areas where Sinclair Broadcast Group has established early-mover coverage. Deepen in-house production of ATSC 3.0-compatible tuner modules to offset silicon supply concentration risk from Taiwanese foundries. FCC repack deadline compression threatens capital planning flexibility for laggard stations. For New Entrants and Emerging Players: Mid-market commercial digital signage networks in Germany and Japan represent the most penetrable entry point for ATSC 3.0-enabled display vendors lacking Korean manufacturing scale. Automotive infotainment integration for connected vehicle platforms offers a second white-space corridor with limited incumbent saturation. Partner with public broadcasters ARD and ZDF on pilot deployments to establish reference installations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to divest non-core broadcast infrastructure units amid IP-centric transmission architecture transitions. Long-term viability favors suppliers with demonstrated interoperability certification through Consumer Technology Association programs. Monitor FCC broadcaster capital commitment schedules as the primary inflection signal for hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Transmitter Site Consolidation | Sinclair Broadcast Group leverages tower access to compress competitor rollout timelines in designated markets. |
| OFDM Demodulator Supply Agreement | Long-term foundry contracts reduce vulnerability to Taiwanese semiconductor capacity constraints. |
| Consumer Technology Association Certification | Interoperability validation accelerates retail channel readiness for smart TV manufacturers. |
| Automotive Infotainment Integration | Connected vehicle platforms open underpenetrated hardware category for ATSC 3.0 chipsets. |
| Targeted Advertising Platform Development | IP-based addressable insertion creates new revenue streams for local broadcast stations. |
Research Methodology
Desk research of FCC repack proceedings, broadcaster capital expenditure disclosures, and Consumer Technology Association certification databases preceded structured interviews with broadcast engineering directors, smart TV product managers, semiconductor procurement leads, and transmitter site acquisition specialists. Primary fieldwork across Dallas-Fort Worth, Atlanta, and Seoul Capital Area informed infrastructure deployment pacing assumptions. Secondary validation drew from customs import records for display panel shipments, SEC filings of publicly traded broadcasters, and equipment vendor order backlogs. Bottom-up unit shipment estimates triangulated against top-down broadcaster capital commitment aggregates.
Fixed assumptions across the modeling period include FCC voluntary transition framework persistence, HEVC codec standard stability, and South Korean reference architecture validity for North American deployment. Segmentation dimensions modeled encompass product type, display technology tier, end-user category, and application use case. CAGRs derive from logistic diffusion curves fitted to broadcaster upgrade cycle data and consumer replacement rate surveys. Forecast inputs incorporate spectrum repack completion timelines and smart TV penetration trajectories.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or display panel commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding broadcaster coordination behavior and semiconductor supply elasticity. Material shifts in FCC mandate timing or OFDM demodulator export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Printed Electronics Market