
 South America Compound Chocolate Market | 2026-2036
South America Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
South America Compound Chocolate Market Analytics
Modular portion packs and single-serve sachets for foodservice channels is realigning procurement patterns across the South America compound chocolate landscape. Cargill Incorporated leverages its integrated supply chain from tropical fat sourcing through finished compound manufacturing to control input costs. The Barry Callebaut Group anchors its regional competitiveness through specialized coating formulations tailored to high-temperature climates. Puratos NV differentiates via technical service networks that embed application laboratories inside Brazilian and Colombian customer facilities.
Compound chocolate substitutes cocoa butter with vegetable fats such as palm kernel oil or shea stearin, achieving snap and melt profiles at lower cost for coating, molding, and enrobing applications. Milk Compound leads volume consumption due to its versatility across confectionery bars and bakery inclusions, though Dark Compound commands margin premiums in health-positioned product lines. Specialty Stores distribution channels sustain higher per-unit prices through artisan positioning, while Bulk Packaging dominates industrial procurement flows to Brazilian and Argentine processed food manufacturers.
ANVISA governs food additive approvals and labeling standards for compound chocolate sold in Brazil, while Argentina's national food safety authority enforces Mercosur-aligned compositional thresholds. REACH-equivalent chemical frameworks under Mercosur technical regulations increasingly influence imported ingredient compliance for multinational suppliers. Stakeholders must monitor evolving vegetable fat sustainability certification requirements and regional sugar reduction mandates that could reformulate standard compound bases.
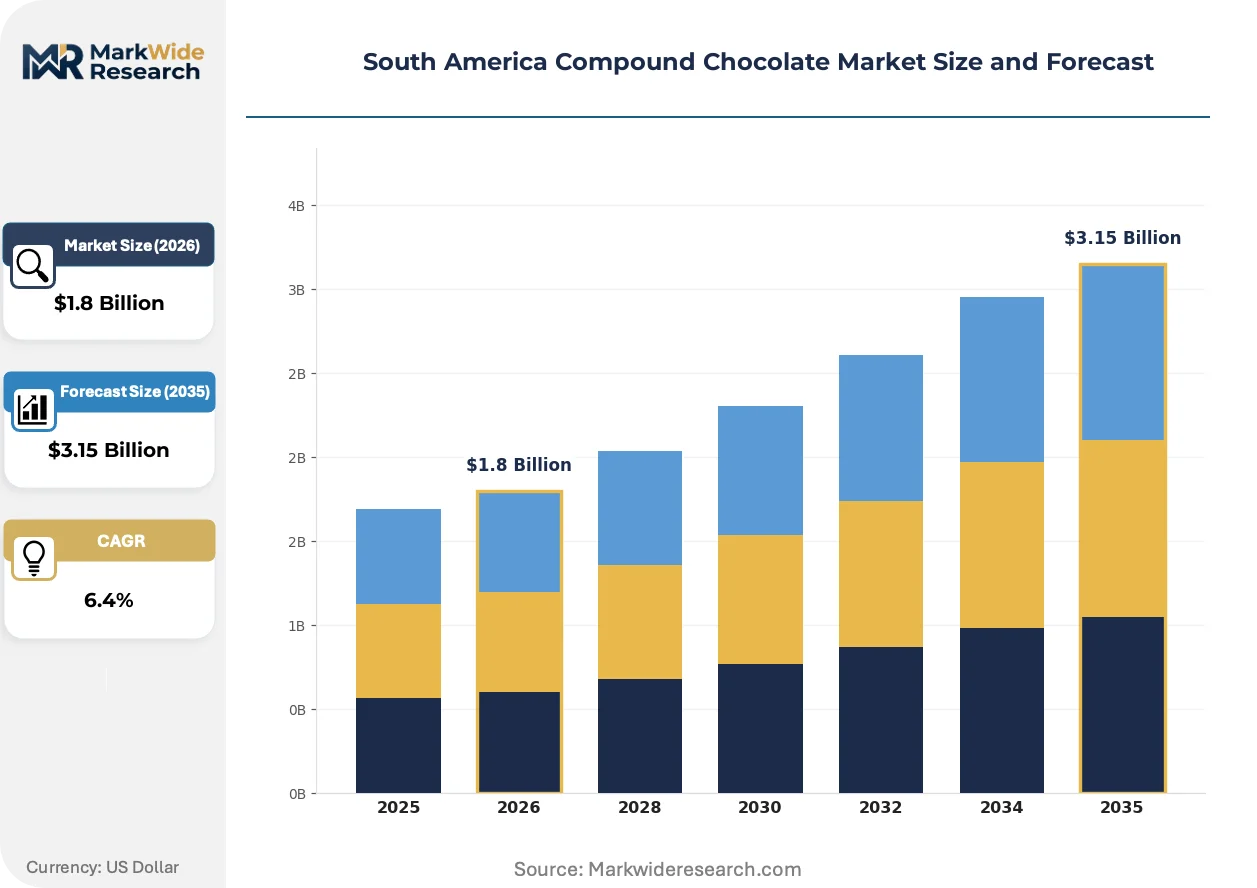
Market Dynamics
ANVISA's updated food additive regulations and Brazil's accelerating cocoa butter substitution with tropical fats are compressing formulation cycles across South American compound chocolate manufacturing. São Paulo's industrial bakery clusters near port infrastructure concentrate demand while reshaping regional procurement geography.
Growth Catalysts
- ANVISA Regulatory Modernization:Brazil's streamlined approval pathways for palm kernel oil and shea stearin derivatives accelerate new product launches. Reformulated compound bases reach market faster under 2023-2024 guidance updates.
- Industrial Bakery Expansion:São Paulo state's enrobed snack and bakery filling segments absorb rising compound chocolate volumes. Proximity to Santos port infrastructure reduces tropical fat input logistics costs.
- Tropical Fat Substitution Economics:Cocoa butter replacement with regionally sourced palm and shea derivatives cuts raw material expenditure. Argentine confectionery converters replicate Brazilian cost models.
Market Restraints
- Input Cost Volatility:Palm kernel oil prices fluctuate with Southeast Asian weather patterns and Malaysian export duties. Brazilian manufacturers lack price hedging instruments for tropical fat procurement.
- Supply Concentration Risk:Mercosur's vegetable fat processing capacity clusters in southeastern Brazil. Argentine and Colombian buyers face single-source dependency for specialized coating formulations.
- Technical Limitation:High-temperature climate performance gaps persist between compound chocolate and pure cocoa butter coatings. Barry Callebaut's specialized formulations remain proprietary.
Strategic Opportunities
- Colombian Market Underpenetration:Bogotá and Medellín processed food sectors show low compound chocolate adoption relative to Brazil. Puratos NV's embedded application laboratories demonstrate service-model viability.
- Sugar Reduction Mandates:Chile's front-of-package labeling laws and Brazil's pending ANVISA sugar threshold discussions create reformulation demand. Low-glycemic compound bases attract health-positioned product lines.
- Single-Serve Foodservice Packaging:Modular sachets and portion packs for hospitality channels bypass traditional bulk distribution. Argentine hotel and café segments trial direct procurement from converters.
Industry Challenges
- Application Technologist Scarcity:Brazilian and Colombian food science programs underproduce compound chocolate formulation specialists. Puratos NV and Cargill Incorporated compete for limited regional talent pools.
- REACH-Equivalent Compliance Timelines:Mercosur's evolving chemical framework documentation requirements delay imported ingredient approvals. Multinational suppliers face extended registration cycles for novel emulsifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Compound Chocolate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Compound, Milk Compound, White Compound, Sugar-free Compound Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores End User: Food Industry, Beverage Industry, Confectionery, Retail Packaging Type: Bags, Boxes, Pouches, Bulk Packaging |
| Companies Covered | Cargill Incorporated, Puratos NV, The Barry Callebaut Group, Santa Barbara Chocolate, Blommer Chocolate Company, Aalst Chocolate Pte Ltd, Sephra, Unigra, Nestlé S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Compound Chocolate Market Evolving Landscape
Precision tempering systems and clean-label emulsifier portfolios are compressing technical barriers between compound chocolate and premium coating categories across South American manufacturing.
Shea stearin fractionation technology is rewriting snap and melt profile standards for high-temperature climate applications. Colombian and Argentine enrobed snack manufacturers adopt these systems at accelerating pace. The technology is rewriting cost-performance tradeoffs previously favoring pure cocoa butter in premium positioning.
ANVISA's updated food additive positive lists and Mercosur-aligned compositional thresholds impose stricter documentation burdens on imported vegetable fat derivatives. Industrial compound chocolate buyers now require supplier certificates of analysis exceeding prior disclosure norms. Brazilian São Paulo-state converters invest in in-house laboratory verification capacity to compress compliance timelines.
Foodservice channel buyers in Argentina and Colombia consolidate procurement through specialized distributors offering technical support bundled with compound chocolate supply. Traditional bulk packaging relationships with direct manufacturer accounts erode in mid-scale bakery and confectionery segments. This pattern concentrates most visibly in Buenos Aires and Bogotá metropolitan procurement offices.
South America Compound Chocolate Market Segmentation
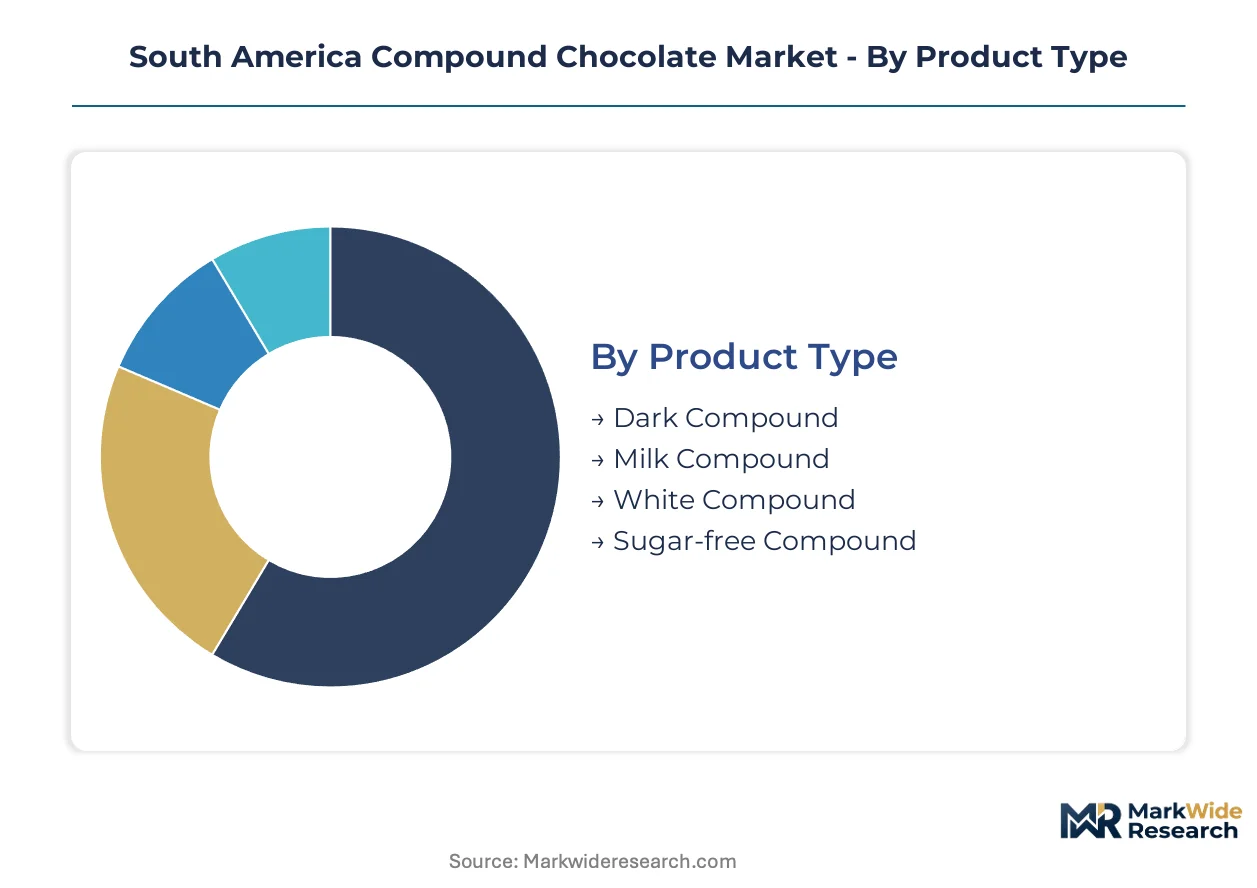
Compound chocolate segmentation in South America tracks divergent cost structures across cocoa butter substitution grades and procurement channel economics. Industrial buyers prioritize bulk formats and tropical fat formulations, while retail-facing segments demand portion-controlled packaging and clean-label positioning.
Product Type:
Capital intensity varies sharply across product categories, with shea stearin fractionation systems and precision tempering infrastructure demanding the heaviest upfront investment for high-performance compounds.
- Milk Compound:Blends cocoa powder with milk solids and palm kernel oil to deliver creamy mouthfeel at reduced cost. São Paulo's industrial bakeries and enrobed snack manufacturers absorb the majority of regional volume, driven by ANVISA's streamlined approval pathways for tropical fat derivatives.
- Dark Compound:Higher cocoa content with shea stearin or palm stearin replacement achieves snap and gloss profiles approaching pure chocolate. Argentine confectionery converters and Colombian premium positioning lines concentrate demand, though climate performance gaps persist against cocoa butter benchmarks.
- White Compound:Cocoa butter-free formulation relying on vegetable fat, sugar, and milk powder for coating applications. Brazilian biscuit manufacturers represent the primary installed base.
- Sugar-free Compound:Maltitol or erythritol-based bases targeting Brazil's pending ANVISA sugar threshold discussions and Chile's front-of-package labeling compliance. Limited current penetration but accelerating trial in health-positioned product lines.
Most installed capacity flows through Milk Compound. Expansion is steepest in Dark Compound.
Distribution Channel:
Channel selection determines margin capture, with direct manufacturer relationships yielding lowest per-kilogram pricing and specialized intermediaries extracting service premiums.
- Specialty Stores:Artisan-positioned outlets in Buenos Aires and Bogotá metropolitan areas sustain higher per-unit prices through technical consultation bundled with compound supply. Puratos NV's embedded application laboratories demonstrate this service-model viability for mid-scale bakery and confectionery procurement.
- Bulk Packaging (via Direct Manufacturer Accounts):São Paulo-state converters and Argentine processed food manufacturers dominate procurement flows, leveraging proximity to Santos port infrastructure for tropical fat input logistics optimization. Cargill Incorporated's integrated supply chain from sourcing through finished manufacturing anchors cost competitiveness here.
- Supermarkets:Retail-packaged compounds for home baking and small commercial users. Brazilian chains lead regional assortment depth.
- Online Stores:Emerging channel for technical specifications and sample procurement, particularly among Colombian formulators seeking imported emulsifier portfolios.
Volume concentrates in direct manufacturer relationships. Margin expansion is fastest in specialty store channels.
End User:
End-use diversification tracks the spread of compound chocolate beyond traditional confectionery into functional food and beverage applications.
- Confectionery:Enrobed bars, molded pieces, and panned products remain the core demand driver. Barry Callebaut's specialized high-temperature climate formulations command positioning premiums here.
- Food Industry:Bakery inclusions, biscuit coatings, and frozen dessert applications absorb rising volumes. Industrial bakery clusters in São Paulo state reshape regional procurement geography.
- Beverage Industry:Compound chocolate for flavored milk and powdered drink mixes, primarily Brazilian dairy processors.
- Retail:Private-label and branded consumer packs for home use, channeling through supermarket and convenience store networks.
Most formulation technical service capacity serves Confectionery. Application development is expanding most quickly in Food Industry.
Packaging Type:
Packaging configuration directly shapes logistics economics and customer workflow integration.
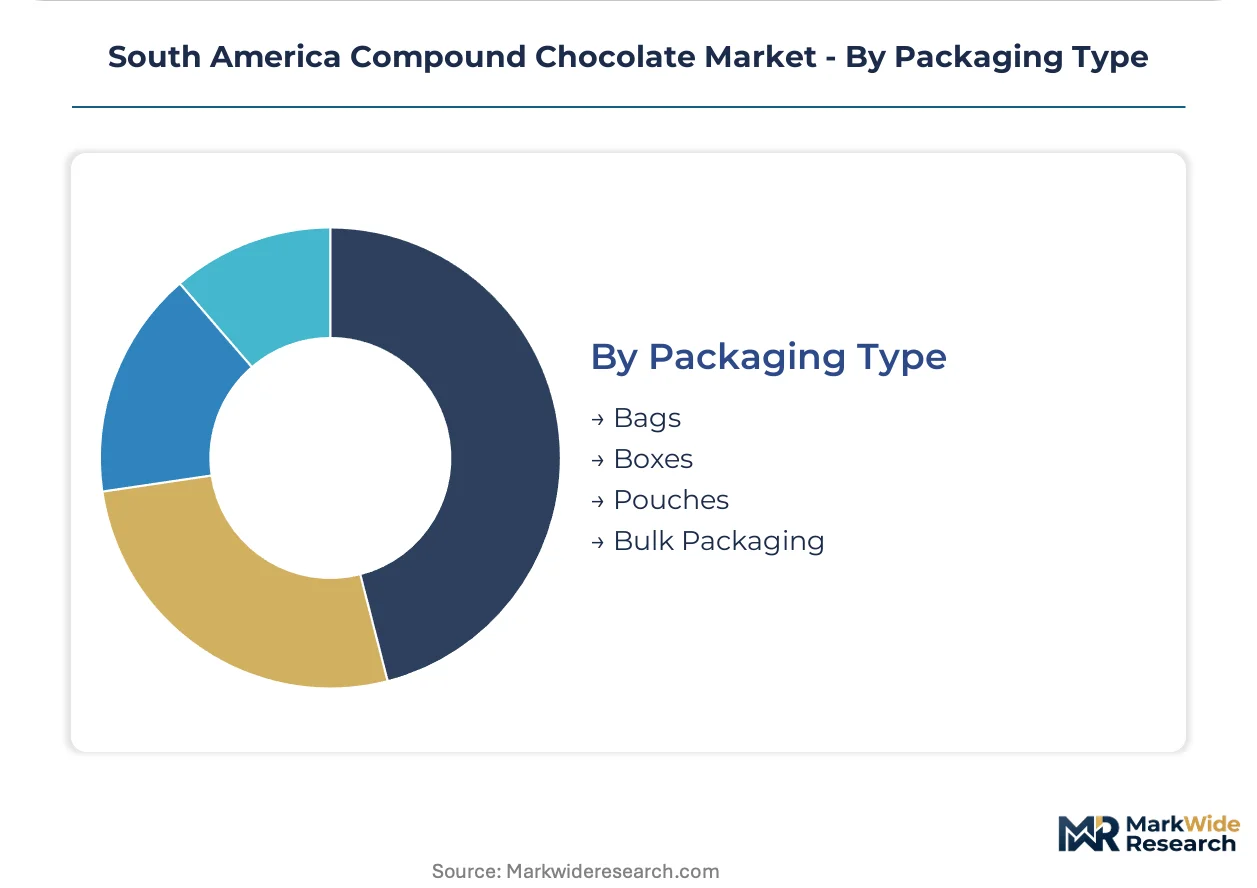
- Bulk Packaging:25kg blocks and liquid tanker deliveries dominate industrial procurement, minimizing unit handling costs for Brazilian and Argentine processed food manufacturers. Santos port proximity reduces inbound tropical fat expenditure for São Paulo-state converters.
- Pouches:Flexible format for foodservice channel modular sachets and single-serve portion packs. Argentine hotel and café segments trial direct procurement from converters, bypassing traditional bulk distribution relationships.
- Bags:Intermediate scale for mid-volume bakery and confectionery operations.
- Boxes:Rigid packaging for retail shelf presentation and gift positioning.
Most tonnage moves through Bulk Packaging. Format innovation is climbing the fastest in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's industrial chocolate sector originated in São Paulo state's immigrant-founded confectionery workshops during the mid-twentieth century. Argentine and Colombian markets subsequently developed distinct procurement patterns shaped by local bakery traditions and import substitution policies. The contemporary landscape reflects these divergent historical foundations.
Brazil
São Paulo state's enrobed snack manufacturers and industrial bakeries absorb the majority of regional compound chocolate tonnage. ANVISA's streamlined 2023-2024 approval pathways for palm kernel oil derivatives accelerate new product launches. Santos port infrastructure enables São Paulo-state converters to minimize tropical fat input logistics costs through direct bulk handling.
Argentina
Buenos Aires metropolitan confectionery converters replicate Brazilian cost models through cocoa butter substitution with regionally sourced tropical fats. The national food safety authority enforces Mercosur-aligned compositional thresholds on imported compound bases. Argentine hotel and café segments in Buenos Aires trial direct procurement from converters, bypassing traditional bulk distribution relationships.
Colombia
Bogotá and Medellín processed food sectors show historically low compound chocolate adoption relative to Brazilian benchmarks. Puratos NV's embedded application laboratories demonstrate service-model viability for mid-scale bakery procurement. Bogotá metropolitan procurement offices increasingly consolidate foodservice channel buying through specialized distributors bundling technical support with compound supply.
Chile
Santiago-based confectionery manufacturers face front-of-package labeling laws that create reformulation demand for low-glycemic compound bases. Health-positioned product lines in Chilean retail channels command margin premiums for reduced-sugar positioning. Santiago's industrial food processing clusters absorb rising volumes of specialty compound formulations.
South America Compound Chocolate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and climate-performance specialization. The vendor base organizes into three tiers: integrated agribusiness conglomerates controlling tropical fat sourcing through finished manufacturing; specialized coating formulators with proprietary high-temperature climate portfolios; and regional converters competing on logistics proximity. Dominant competitive moves include backward integration into palm and shea derivative processing, plus embedded technical service deployment inside customer facilities.
Within the integrated supply chain tier, Cargill Incorporated anchors cost competitiveness through captive tropical fat sourcing. The Barry Callebaut Group occupies the specialized formulation vector with climate-adapted coating technologies. Puratos NV exemplifies the service-embedded model through application laboratory placement inside Brazilian and Colombian customer facilities. These three players represent distinct strategic archetypes rather than overlapping positioning.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Puratos NV |
| The Barry Callebaut Group |
| Santa Barbara Chocolate |
| Blommer Chocolate Company |
| Aalst Chocolate Pte Ltd |
| Sephra |
| Unigra |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
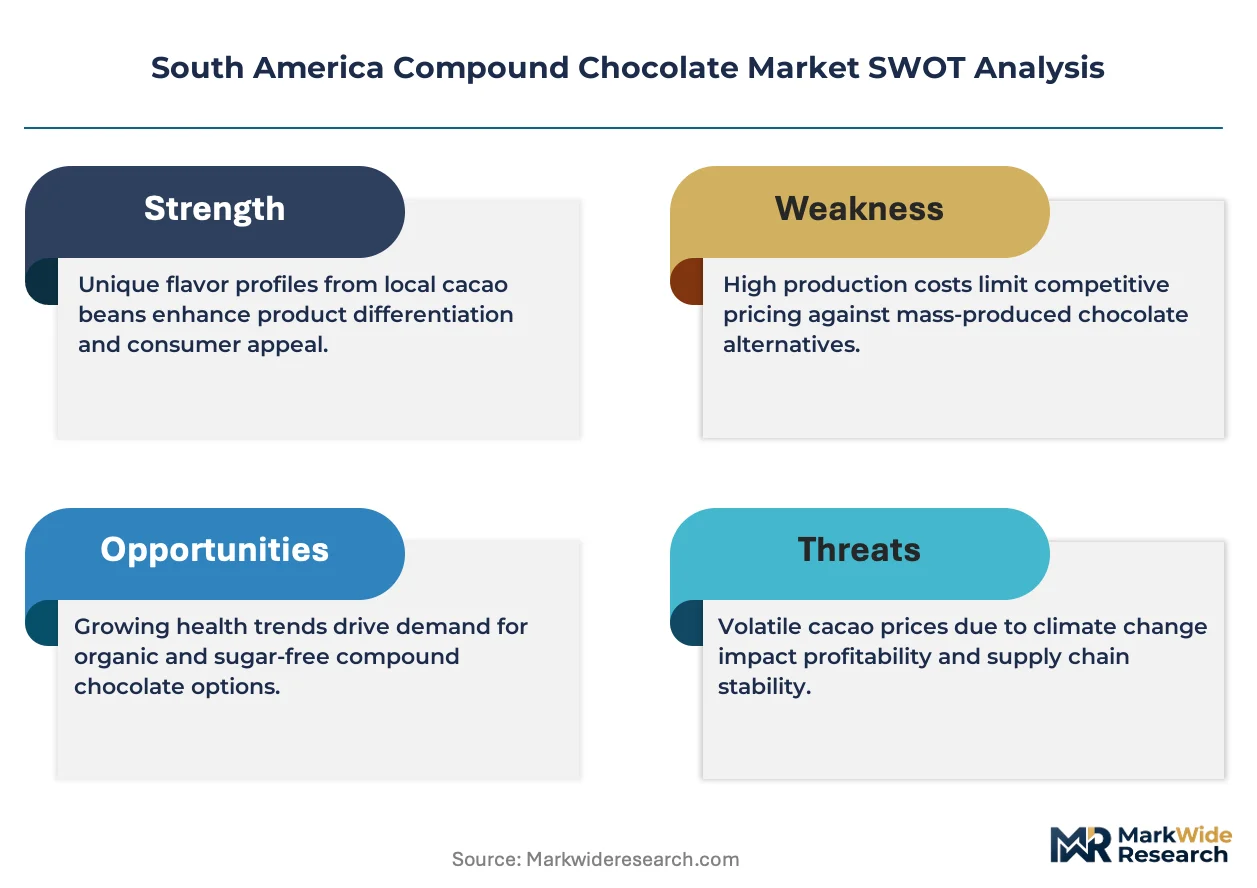
Palm kernel oil futures volatility cascades through South American compound chocolate manufacturing into three distinct pricing strata. São Paulo-state converters absorb input cost shocks through Santos port bulk handling efficiencies, while Argentine and Colombian buyers face elevated landed costs from single-source Mercosur dependencies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates South American compound chocolate procurement. Price differentiation rests on climate-performance certification grade and volume scale commitments. Cost compression in economy-tier milk compound is intensifying because Brazilian industrial bakeries consolidate purchasing through direct manufacturer accounts. Foodservice channel buyers in Buenos Aires and Bogotá show lowest price sensitivity due to bundled technical service premiums.
Supply Chain Analysis
Freight cost differentials between Santos port bulk handling and overland trucking to Argentine and Colombian markets concentrate procurement power in southeastern Brazil. Supply draws from Malaysian and Indonesian palm kernel oil processing, Brazilian shea stearin fractionation capacity, and Argentine dairy solids production. Single-source vulnerability pervades specialized coating formulations. Distribution runs through direct manufacturer accounts for industrial buyers and specialized technical-service distributors for mid-scale foodservice procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America compound chocolate markets function as a geographic-arbitrage play between Brazil's ANVISA-regulated formulation pathways and Argentina's Mercosur-aligned compliance costs. The cost differential creates procurement migration incentives toward São Paulo-state manufacturing clusters.
For Market Incumbents: Anticipate margin compression from Argentine and Colombian converters replicating Brazilian tropical fat substitution models. Anchor defensive positioning through backward integration into palm and shea derivative processing. Expand embedded application laboratory networks inside Colombian customer facilities to lock in technical switching costs against emerging regional competitors. For New Entrants and Emerging Players: Capture Bogotá and Medellín mid-scale bakery segments where compound chocolate adoption lags Brazilian benchmarks by a significant penetration gap. Deploy service-embedded go-to-market models replicating Puratos NV's application laboratory placement. Target Colombian foodservice distributors consolidating procurement through technical support bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating formulators possessing proprietary high-temperature climate portfolios. Long-term viability favors acquisition targets controlling captive tropical fat sourcing or embedded customer technical service infrastructure. A model refresh is warranted upon material change in ANVISA additive approval timelines or Mercosur REACH-equivalent enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Fat Processing | Cargill Incorporated's captive palm kernel oil sourcing anchors cost competitiveness against merchant-market dependent rivals. |
| Embedded Application Laboratory Deployment | Puratos NV's Bogotá facility placements demonstrate service-model viability for converting Colombian bakery procurement. |
| Climate-Adapted Coating Formulation Development | Barry Callebaut's proprietary high-temperature portfolios command positioning premiums in Argentine enrobed snack manufacturing. |
| Single-Serve Foodservice Packaging Innovation | Argentine hotel and café direct procurement trials validate modular sachet bypass of traditional bulk distribution. |
| Sugar Reduction Base Reformulation | Chile's front-of-package labeling compliance creates pull-through demand for low-glycemic compound in Santiago retail channels. |
Research Methodology
Direct dialogue with compound chocolate plant managers, procurement leads at Brazilian and Argentine confectionery converters, ANVISA regulatory affairs specialists, and tropical fat sourcing directors grounded this analysis. Secondary validation drew from ANVISA additive approval databases, Mercosur technical regulation filings, Santos port customs records, and industry association production surveys. Bottom-up volume triangulation against top-down value estimates compressed estimation variance.
Segment-level outputs across product type, distribution channel, end user, and packaging configuration dimensions were generated through the projection horizon. CAGRs were derived from input-cost elasticity modeling and substitution rate assumptions. Key forecast inputs included palm kernel oil price trajectory scenarios and ANVISA regulatory modernization implementation pace.
ANVISA guidance reversals, Mercosur REACH-equivalent documentation delays, and Southeast Asian tropical fat export duty shocks are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in Brazilian industrial bakery cluster expansion rates or Argentine foodservice channel consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Citrus Gummies Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Sugarless Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Italy Chocolate Market
Confectionery
South Africa Confectionery Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Fruit Jellies Market
Confectionery
Low Calorie Sweets Market
Confectionery
Gummy Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Gummy Candy Market